
 France Electric Vehicle Lithium-Ion Battery Separator Market | 2026-2036
France Electric Vehicle Lithium-Ion Battery Separator Market Size, Share, and Industry Trends Forecast 2026-2036
France Electric Vehicle Lithium-Ion Battery Separator Market Insights
CE marking under the EU Battery Regulation is redrawing competitive boundaries for separator suppliers serving French EV producers. Asahi Kasei leverages its polyolefin membrane expertise to anchor supply relationships with European battery cell builders. SK Innovation competes through integrated separator-electrolyte R&D pipelines, while Daramic SAS specializes in lead-acid crossover technologies that navigate the transition toward lithium-ion qualification.
France Electric Vehicle Lithium-Ion Battery Separators are microporous membranes, typically 5-30 micrometers thick, manufactured from polyethylene or polypropylene through dry or wet stretching processes to enable ion transport while preventing electrode short circuits. Their primary function is electrochemical isolation within cylindrical, prismatic, and pouch cell architectures deployed in electric powertrains. Porous film dominates current procurement volumes, though coated separators command premium positioning due to enhanced thermal shutdown performance and electrolyte wettability. Wet process technology leads manufacturing investment in France, while dry process lines retain cost advantages for medium-capacity cell tiers serving compact urban vehicles.
France's national implementation of the EU Battery Regulation, enforced by national market surveillance authorities coordinating with ECHA substance restrictions, mandates supply chain due diligence and performance-grade labeling that directly shapes separator material selection and import documentation. DGCCRF consumer safety inspections and upcoming EU critical raw material act requirements will tighten origin verification protocols for polyolefin feedstocks and ceramic coating additives. Stakeholders must monitor how France's national hydrogen and electromobility investment plans redirect cell capacity allocation between automotive OEMs and energy storage integrators.
Market Dynamics
Wet-process coated separator technology is consolidating procurement power among French gigafactory operators, compressing margins for dry-process suppliers while elevating performance-grade specifications across the Hauts-de-France cluster.
Growth Catalysts
- EU Battery Regulation recycled content mandates:France's enforcement through DGCCRF inspections creates certified demand for separators with traceable polyolefin feedstocks and ceramic coating documentation.
- Renault and Stellantis platform scaling:Domestic OEM production targets for EV architectures are pulling separator volumes toward Dunkirk and Douai manufacturing zones.
- Wet-process thermal shutdown coatings:Enhanced electrolyte wettability and safety performance are displacing uncoated porous films in premium cell tiers.
Market Restraints
- Polyolefin feedstock import dependency:Asian supply concentration for ultra-high molecular weight polyethylene creates input cost volatility and origin verification burdens under EU critical raw material tracking.
- CE marking compliance timeline:ECHA substance restrictions and carbon footprint declaration requirements extend qualification cycles for new separator formulations.
- Dry-process cost-floor compression:Wet-process capital intensity limits supplier participation, narrowing the qualified vendor base for high-performance contracts.
Strategic Opportunities
- Energy storage integrator demand:France's national hydrogen and electromobility investment plans are redirecting cell capacity toward grid-scale battery projects with different separator specification profiles.
- Coated separator technology convergence:Ceramic-polymer hybrid layers combined with functionalized electrolyte interfaces open premium positioning beyond automotive applications.
- Local supply chain clustering:Hauts-de-France regional incentives for battery ecosystem co-location reduce logistics exposure and enable just-in-time separator delivery models.
Industry Challenges
- Specialized polymer processing talent scarcity:Wet-process stretching and coating expertise concentrates among a limited pool of engineers familiar with sub-20 micrometer membrane control.
- Qualification timeline compression:OEM platform launch schedules demand simultaneous separator certification across cylindrical, prismatic, and pouch cell formats.
- Legacy dry-process asset repositioning:Medium-capacity urban vehicle segments require cost-optimized separators that preserve equipment utilization without cannibalizing premium coated product investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Electric Vehicle Lithium-Ion Battery Separator Market |
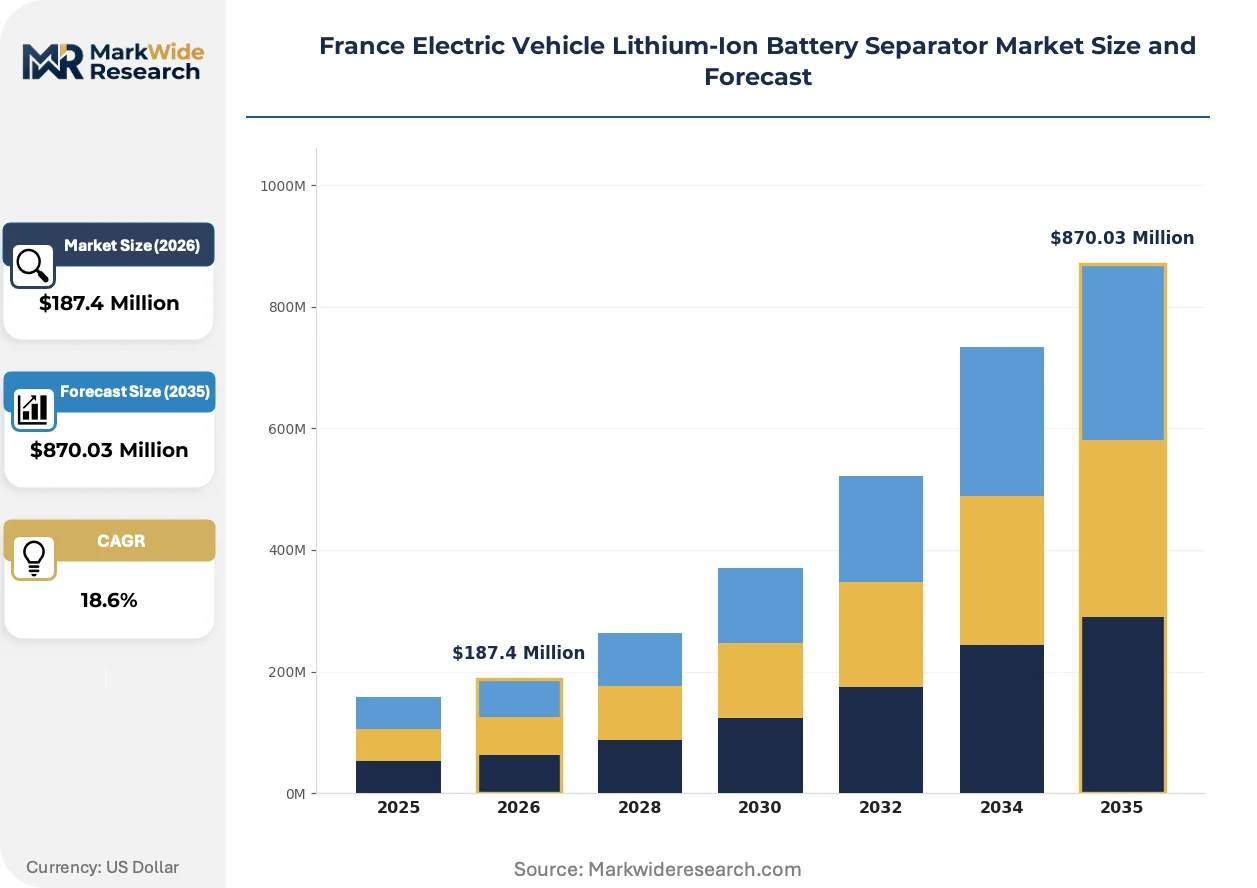
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Porous Film, Non-Woven Fabric, Coated Separator, Solid Separator End User: Original Equipment Manufacturers, Aftermarket Providers, Tier-1 Suppliers, Battery Manufacturers Technology: Dry Process, Wet Process, Coating Technology, Extrusion Technology Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity |
| Companies Covered | Asahi Kasei Corporation, Sumitomo Chemical Co., Ltd., Mitsubishi Chemical Group Corporation, SK Innovation, Toray Industries, UBE Corporation, Daramic SAS, Delfortgroup AG, W-SCOPE Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Electric Vehicle Lithium-Ion Battery Separator Market Trends and Innovations
Separator technology trajectories in France are splitting between performance-maximizing coated architectures and cost-optimized uncoated films, with regulatory pressure accelerating the divergence rather than converging on a single standard.
Coated ceramic-polymer composite separators are bifurcating procurement tiers across French cell manufacturers. High-nickel cathode cells for premium EV platforms adopt these membranes for enhanced thermal stability and electrolyte retention. Standard porous films retain position in compact urban vehicle batteries where cost-per-kilowatt-hour dominates supplier selection.
France's national implementation of the EU Battery Regulation enforces supply chain due diligence through DGCCRF market surveillance and ECHA substance restrictions. Carbon footprint declarations and recycled content thresholds reshape material selection protocols. Separator importers face tightened documentation requirements for polyolefin origins and ceramic additive compositions.
Cell manufacturers are consolidating separator procurement around tier-1 suppliers capable of integrated R&D partnerships. Long-term offtake agreements displace spot purchasing as gigafactory operators seek volume certainty and co-development access. This pattern concentrates most visibly in the Dunkirk-Douai corridor where battery production clusters demand synchronized separator logistics.
France Electric Vehicle Lithium-Ion Battery Separator Market Segmentation
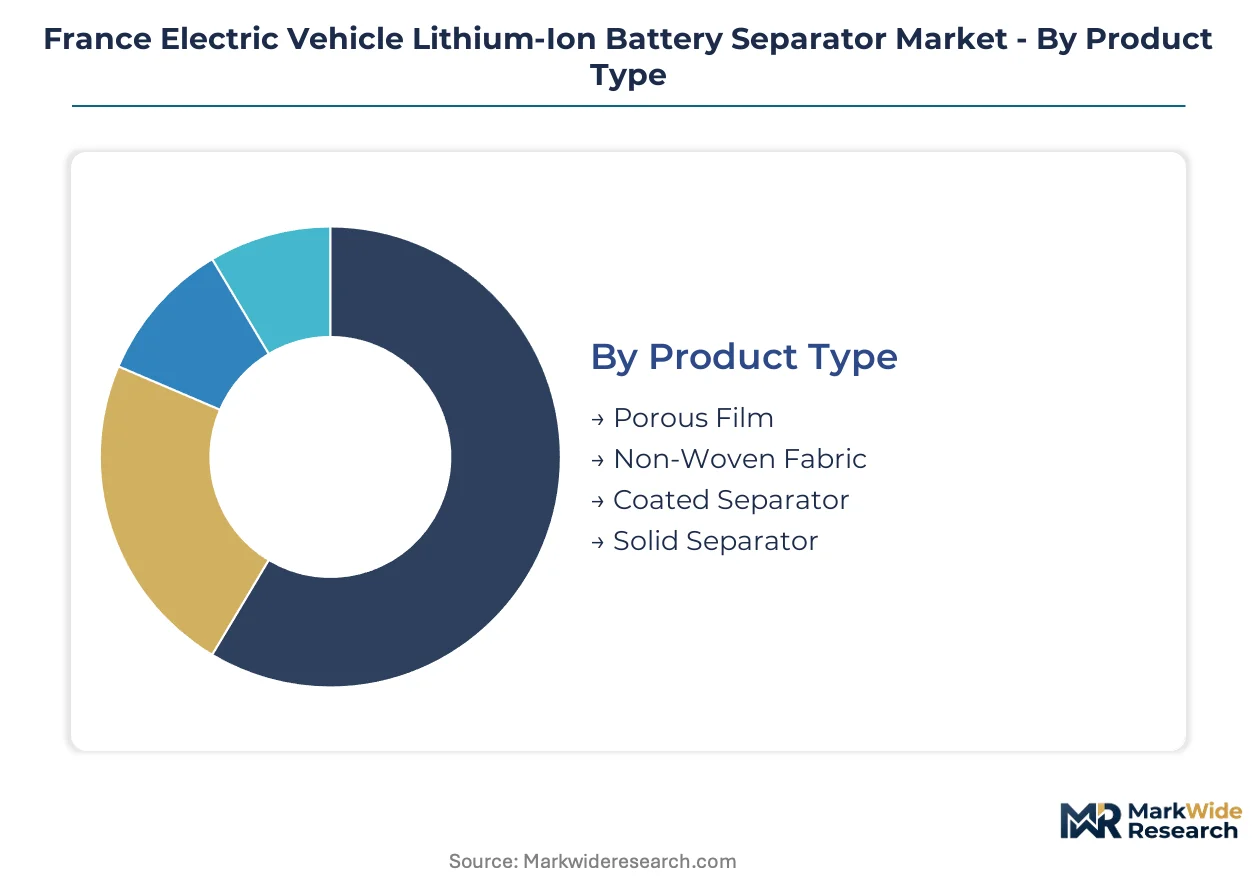
Segmentation in the France EV battery separator market reveals how procurement channels split between gigafactory direct contracts and tier-1 supplier intermediation. Each dimension—product form, customer type, manufacturing method, and cell scale—channels volume through distinct commercial pathways with diverging margin structures.
Product Type:
Channel distribution varies sharply by separator form: coated products flow through integrated R&D partnerships, while uncoated films move via distributor networks serving smaller cell builders.
- Coated Separator:Ceramic-polymer hybrid membranes deliver thermal shutdown protection and enhanced electrolyte wettability. Wet-process lines at Dunkirk and Douai gigafactories pull these through long-term offtake agreements with qualified tier-1 suppliers.
- Porous Film:Standard polyethylene or polypropylene microporous membranes, 5-30 micrometers thick, manufactured through dry or wet stretching. Compact urban vehicle programs in France specify these for cost-sensitive cell tiers where thermal performance requirements remain moderate.
- Non-Woven Fabric:Fibrous mat structures serving specialty applications with irregular pore distribution requirements.
- Solid Separator:Dense ceramic or polymer electrolyte barriers for solid-state cell architectures under development.
By volume, porous film leads. By growth pace, coated separator is climbing the fastest.
End User:
Margin concentration follows customer scale: battery manufacturers and OEMs capture direct pricing, while tier-1 suppliers and aftermarket providers absorb intermediary markups.
- Battery Manufacturers:Cell builders operating gigafactories in Hauts-de-France negotiate directly for separator volumes matching platform-specific electrochemical requirements. Renault and Stellantis supply agreements cascade specifications through this channel.
- Original Equipment Manufacturers:Automotive OEMs with in-house cell assembly capabilities source separators through integrated procurement arms. Their qualification timelines under EU Battery Regulation CE marking compress supplier selection windows.
- Tier-1 Suppliers:Component integrators aggregating separator procurement for mid-tier cell producers.
- Aftermarket Providers:Replacement battery specialists sourcing standard-grade separators for repair and refurbishment channels.
By contract value, battery manufacturers dominate. By access difficulty, OEM direct channels are expanding most quickly.
Technology:
Capital intensity separates the technology tiers: wet process demands continuous coating lines, while dry process retains equipment flexibility for batch operations.
- Wet Process:Solvent-based stretching of ultra-high molecular weight polyethylene produces highly uniform pore structures. French gigafactory investments concentrate procurement here for high-nickel cathode cells requiring sub-20 micrometer thickness control.
- Coating Technology:Ceramic deposition and functionalized polymer layers applied atop base membranes. DGCCRF market surveillance under EU Battery Regulation mandates documentation of coating additive origins and carbon footprint declarations.
- Dry Process:Mechanical stretching of polypropylene without solvent exposure, preserving cost advantages for medium-capacity urban vehicle segments.
- Extrusion Technology:Melt-blowing and phase-inversion methods for non-standard pore architectures.
By installed capacity, wet process leads. By investment velocity, coating technology is gaining share fastest.
Capacity:
Cell scale determines separator specification stringency: higher capacities demand thinner membranes with enhanced thermal stability, compressing the qualified supplier base.
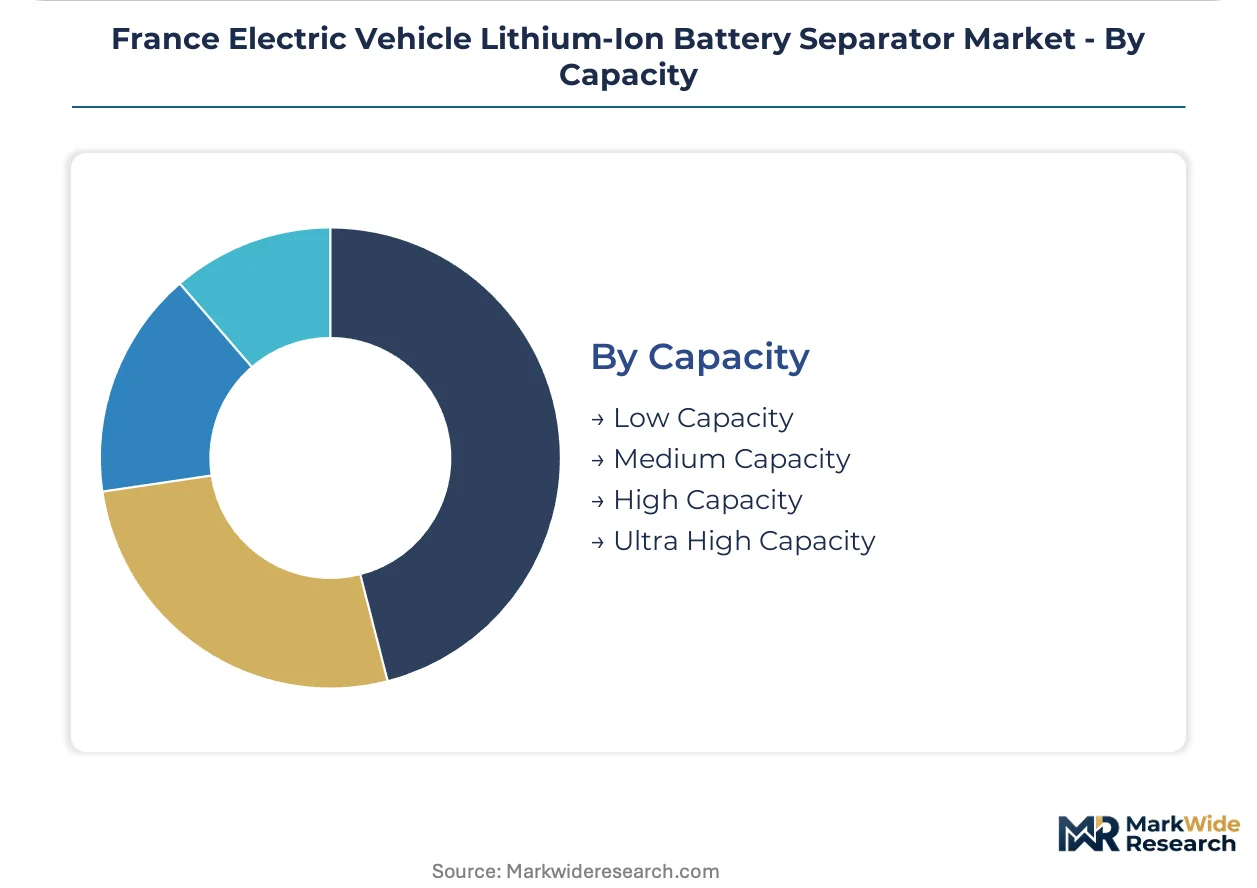
- High Capacity:Cells exceeding 100 Ah for premium EV platforms specify coated wet-process separators with ceramic hybrid layers. These applications concentrate in Stellantis and Renault flagship architectures assembled near Douai.
- Medium Capacity:50-100 Ah cells for compact urban vehicles balance cost and performance through uncoated wet-process or dry-process films.
- Low Capacity:Sub-50 Ah cells for auxiliary power and two-wheeler applications.
- Ultra High Capacity:Grid-scale storage cells with distinct separator requirements diverging from automotive electrochemical profiles.
By procurement volume, high capacity leads. By specification evolution, ultra high capacity is advancing most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
National hydrogen and electromobility investment plans across European economies are redirecting cell capacity allocation between automotive OEMs and energy storage integrators, reshaping separator procurement geography.
Germany
Volkswagen Group and BMW EV platform scaling pulls separator volumes toward Saxony and Thuringia battery plants. KBA vehicle certification requirements under EU Battery Regulation enforce carbon footprint documentation for imported polyolefin feedstocks. The Erfurt-Dresden corridor concentrates wet-process separator qualification activity for high-nickel cathode cells.
Spain
Stellantis and Volkswagen Group gigafactory investments in Valencia and Sagunto generate coated separator demand for premium EV architectures. Spain's national recovery plan channels EU Next Generation funds toward battery ecosystem localization. The Aragon region hosts emerging separator testing facilities serving Iberian cell manufacturers.
Italy
Enel X and automotive tier-1 suppliers drive grid-scale storage separator specifications distinct from automotive electrochemical profiles. ANVISA-aligned substance tracking protocols influence ceramic coating additive documentation. Lombardy-based engineering firms specialize in dry-process equipment retrofits for cost-sensitive urban vehicle segments.
Poland
LG Energy Solution and SK Innovation cell plants in Wrocław and Dzierżoniów anchor separator procurement for export-oriented battery production. Poland's national industrial policy offers co-location incentives for polyolefin processing equipment. The Lower Silesia cluster concentrates medium-capacity cell separator demand for compact European EV platforms.
Sweden
Northvolt's Skellefteå gigafactory establishes closed-loop battery manufacturing with recycled content mandates affecting separator material selection. Swedish environmental protection agency enforcement of EU Battery Regulation due diligence requirements tightens origin verification for ultra-high molecular weight polyethylene imports. Västerbotten region incentives attract ceramic coating additive suppliers.
France Electric Vehicle Lithium-Ion Battery Separator Market Competitive Landscape
Listed leaders compete with private specialists across capital access and R&D partnership dimensions, creating tiered supply relationships with French gigafactory operators. Three to five Japanese and Korean conglomerates anchor premium coated separator supply through integrated membrane-electrolyte development pipelines. European specialists occupy mid-tier positioning through lead-acid crossover technologies transitioning toward lithium-ion qualification. Capacity expansion and long-term offtake agreements represent the dominant competitive moves, compressing spot market participation.
Among Japanese chemical conglomerates, Asahi Kasei Corporation, Mitsubishi Chemical Group Corporation, and Toray Industries exemplify the integrated R&D archetype, occupying positions that leverage polyolefin membrane expertise to anchor supply relationships with European battery cell builders. These entities sit within the tier qualified for wet-process coated separator contracts under EU Battery Regulation CE marking requirements. Daramic SAS represents the European specialist archetype, with its French SAS structure indicating regional anchoring for customers navigating the transition from legacy battery technologies.
| Leading Market Players |
|---|
| Asahi Kasei Corporation |
| Sumitomo Chemical Co., Ltd. |
| Mitsubishi Chemical Group Corporation |
| SK Innovation |
| Toray Industries |
| UBE Corporation |
| Daramic SAS |
| Delfortgroup AG |
| W-SCOPE Corporation |
| Others |
Pricing and Supply Chain Analysis
CE marking under the EU Battery Regulation gates both supplier qualification and price differentiation simultaneously, forcing separator vendors to absorb certification costs into tiered product positioning while buyers sort procurement across performance-grade specifications.
Pricing Analysis
Certification level under EU Battery Regulation CE marking creates the primary spread between separator tiers. Wet-process coated membranes with full carbon footprint documentation command premium positioning through long-term offtake agreements, while uncoated porous films compete on per-square-meter transactional pricing for compact urban vehicle programs. Pricing pressure stems from polyolefin feedstock volatility and DGCCRF inspection compliance burdens compressing margins at the standard tier. Tier-1 battery manufacturers exhibit lowest price sensitivity due to platform qualification lock-in, whereas aftermarket providers and mid-tier cell builders drive aggressive cost negotiation.
Supply Chain Analysis
Inventory lead times for ultra-high molecular weight polyethylene feedstocks extend qualification cycles and amplify working capital requirements across French separator converters. Supply concentration rests on South Korea, Japan, and China for polyolefin resin and ceramic coating additives, with European coating equipment manufacturers feeding secondary processing stages. Single-source vulnerability pervades the ultra-high molecular weight polyethylene segment where Asian petrochemical complexes dominate global capacity. Distribution runs through direct gigafactory contracts in Hauts-de-France, bypassing traditional distributor networks for high-volume automotive programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France EV battery separator market represents a high-growth disruption as solid-state cell architectures and EU recycled content mandates simultaneously reshape material specifications and supplier qualification protocols.
For Market Incumbents: Secure wet-process coated separator capacity expansion in the Dunkirk-Douai corridor before qualification windows close under tightening CE marking timelines. Anchor backward integration into ceramic coating additive supply to defend margin position against polyolefin feedstock volatility and emerging Korean integrated membrane-electrolyte competitors. For New Entrants and Emerging Players: Anchor in energy storage integrator demand diverging from automotive electrochemical profiles, where separator specification flexibility exceeds gigafactory procurement rigidity. Target grid-scale battery projects under France's national hydrogen plan with hybrid ceramic-polymer membranes optimized for cycle life rather than power density, leveraging distributor channels bypassed by tier-1 automotive suppliers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across wet-process coating technology as sub-20 micrometer membrane control requirements concentrate equipment procurement among limited engineering specialists. Over a five-to-ten-year viability window, prioritize acquisition targets with demonstrated ECHA substance restriction compliance and existing Renault or Stellantis qualification status. Monitor Northvolt's Skellefteå recycled content mandates as the signal indicating when closed-loop material verification becomes table stakes for European separator supply.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Wet-process line investments in Hauts-de-France align with Stellantis and Renault platform scaling timelines. |
| Backward Integration | Ceramic coating additive production reduces exposure to ECHA origin verification requirements and supply disruption. |
| Long-term Supply Agreement | Gigafactory offtake contracts with Douai cell manufacturers displace spot purchasing and compress competitor access. |
| Joint Venture | Co-development partnerships with polyolefin resin suppliers accelerate recycled content threshold compliance under EU Battery Regulation. |
| Green Certification Program | Carbon footprint declaration systems satisfy DGCCRF inspection protocols and unlock premium tier positioning. |
Research Methodology
The analysis maps wet-process separator technology, dry-process membrane production, ceramic coating additive supply, and energy storage integration channels, each validated through procurement directors at battery gigafactories, polymer processing engineers, regulatory compliance officers, and tier-1 automotive supplier executives. Primary fieldwork combined with secondary validation from ECHA substance restriction databases, DGCCRF market surveillance records, EU Battery Regulation implementation guidance, and customs trade data for polyolefin feedstock flows. Bottom-up volume modeling triangulated against top-down gigafactory capacity announcements.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product form, end-user category, manufacturing technology, and cell capacity tier. CAGRs derived from regression analysis of separator demand against EV platform production schedules and battery cell chemistry evolution. Industry-specific forecast inputs incorporated Stellantis and Renault public platform scaling commitments and France's national hydrogen investment plan redirections of cell capacity allocation.
Material uncertainties — regulatory enforcement timing variations, solid-state cell technology disruption, and polyolefin feedstock supply concentration shocks — sit outside the modeled envelope. Forecasts reflect documented assumptions about gigafactory construction timelines and OEM platform launch schedules. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Nanobolt Lithium Tungsten Batteries Market
Lithium-ion Battery
Southeast Asia Lithium-Ion Battery Market
Lithium-ion Battery
Li-Sulfur Battery Market
Lithium-ion Battery
Europe Electric Vehicle Battery Anode Market
Lithium-ion Battery
Ternary Lithium Battery Market
Lithium-ion Battery
Salt Lake Battery Grade Lithium Carbonate Market
Lithium-ion Battery
Automotive Lithium-Sulfur Battery Market
Lithium-ion Battery
Germany Electric Vehicle Battery Anode Market
Lithium-ion Battery
Cathode Material of Power Lithium Battery Market
Lithium-ion Battery
South America Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Japan Lithium-Ion Battery Market
Lithium-ion Battery
Lithium Polymer Battery Market
Lithium-ion Battery
Lithium Ion Battery Cathodes Market
Lithium-ion Battery
Germany SLI Battery Market
Lithium-ion Battery
Lithium Battery Components Market
Lithium-ion Battery
Silicon Anode Battery Market