
 EV SOLID State Battery Market | 2026-2036
EV SOLID State Battery Market Size, Share, and Industry Trends Forecast 2026-2036
EV SOLID State Battery Market Intelligence
The emergence of battery-as-a-service (BaaS) models is decoupling battery ownership from vehicle ownership, creating new revenue streams for fleet operators and OEMs. This shift allows for flexible battery lifecycle management and upgrades outside of the initial vehicle purchase. Toyota Motor Corporation leverages its extensive automotive manufacturing expertise to integrate solid-state designs into future vehicle platforms. Solid Power, Inc. specializes in sulfide-based all-solid-state battery cell technology for next-generation EV applications.
EV solid-state batteries are electrochemical energy storage devices that utilize a solid material for the electrolyte instead of the liquid or polymer gel electrolytes found in conventional lithium-ion batteries. This solid electrolyte, often a ceramic or polymer, enables higher energy density and improves safety by eliminating flammable liquid components. Electric passenger vehicles represent the largest application segment, with automakers prioritizing range and safety enhancements for mass-market adoption. Within product types, sulfide electrolytes are gaining traction for their high ionic conductivity, while polymer-based systems offer manufacturing flexibility.
Regulatory frameworks like the US EPA's vehicle emissions standards and the EU Green Deal's transport decarbonization targets are accelerating the transition to electric vehicles. In parallel, China's dual carbon goals create a strong policy pull for advanced battery technologies, including solid-state designs. Stakeholders must now navigate the complex trade-offs between different solid electrolyte chemistries to secure a defensible position in the supply chain.
Market Dynamics
The pursuit of higher energy density to address electric vehicle range anxiety is the central force shaping this market. This imperative drives investment into advanced solid electrolyte materials, specifically sulfide-based chemistries, which offer superior performance and safety profiles over conventional batteries.
Growth Catalysts
- Government Mandates:The US EPA's stringent vehicle emissions standards and the EU Green Deal's transport decarbonization goals create a strong regulatory pull for zero-emission vehicle technologies, including solid-state batteries.
- Electrolyte Advancements:Sulfide-based solid electrolytes are gaining traction due to their high ionic conductivity, which enables faster charging and higher energy density in next-generation electric vehicle applications.
- Policy Support in China:China's dual carbon goals provide substantial government support for the EV supply chain, accelerating the research, development, and commercialization of advanced battery technologies.
Market Restraints
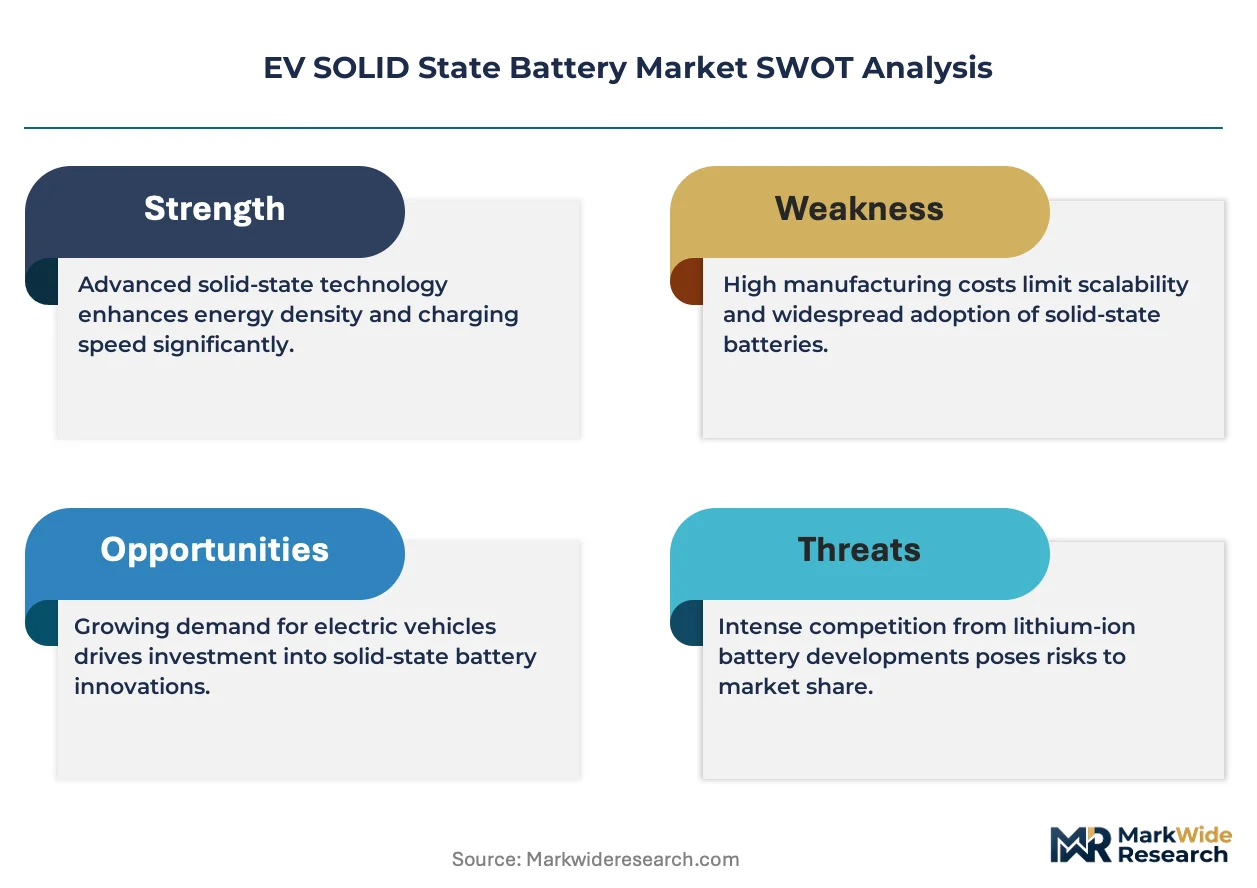
- High Manufacturing Costs:The production of solid electrolytes, particularly sulfide-based materials, involves expensive raw materials and complex synthesis processes, creating a significant cost barrier to mass-market commercialization.
- Interfacial Instability:Poor physical contact and chemical reactivity at the electrode-electrolyte interface can lead to high resistance and dendrite formation, which degrades battery performance and cycle life over time.
- Raw Material Bottlenecks:The supply chain for critical precursor materials, such as high-purity lithium sulfide, remains underdeveloped and concentrated, posing a significant risk to scaling up production globally.
Strategic Opportunities
- Aerospace and Aviation:The high energy density and enhanced safety profile of solid-state batteries create significant opportunities in emerging sectors like electric vertical take-off and landing (eVTOL) aircraft.
- Battery-as-a-Service (BaaS) Integration:The modular nature of solid-state battery packs can be leveraged within BaaS business models, enabling flexible battery swapping, upgrades, and second-life applications outside the initial vehicle sale.
- Localized Production Incentives:Government policies like the US Inflation Reduction Act (IRA) encourage the onshoring of battery manufacturing, creating opportunities for new entrants to establish regional production hubs.
Industry Challenges
- Manufacturing Process Scalability:Moving from pilot-line fabrication to high-volume, cost-effective manufacturing requires overcoming significant process control and capital investment hurdles for solid electrolyte and cell assembly.
- Lack of Standardized Protocols:The absence of industry-wide standards for testing performance, safety, and longevity complicates validation for automotive OEMs and hinders component interchangeability across suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EV SOLID State Battery Market |
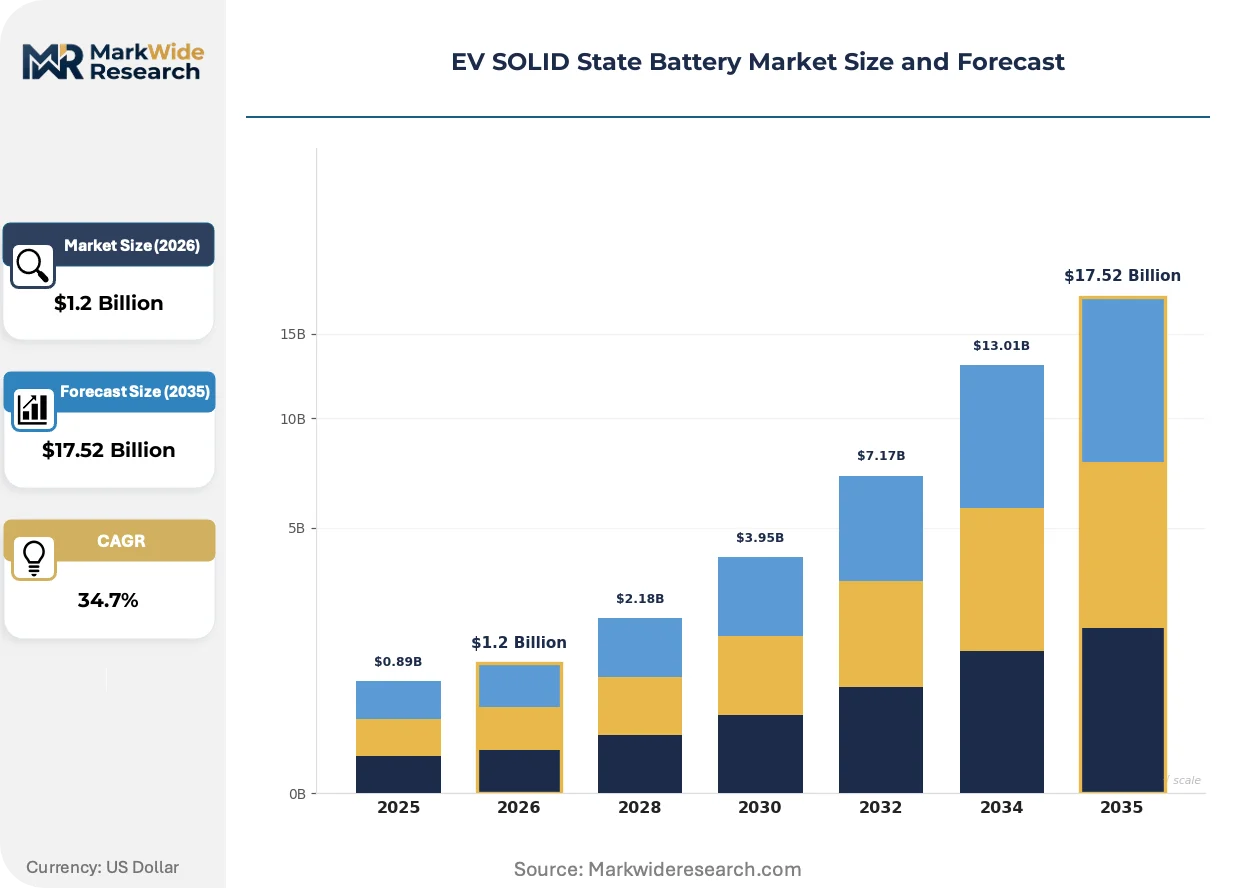
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $17.52 Billion |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Electrolyte, Ceramic Electrolyte, Sulfide Electrolyte, Oxide Electrolyte Application: Electric Passenger Vehicles, Electric Two-Wheelers, Electric Commercial Vehicles, Electric Buses End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers Deployment: Automotive OEM Plants, Battery Manufacturing Facilities, Research Laboratories, Testing Centers |
| Companies Covered | Solid Power, Inc., QuantumScape Corporation, Toyota Motor Corporation, Samsung SDI Co., Ltd., Contemporary Amperex Technology Co., Ltd., ProLogium Technology Co., Ltd., Blue Solutions, Factorial Energy, Ilika plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV SOLID State Battery Market Strategic Shifts & Innovations
A fundamental shift from material science discovery toward scalable manufacturing engineering defines the current development phase. The emphasis is now on creating viable production pathways that integrate with existing automotive assembly lines, moving technology from lab to factory.
Sulfide-based solid electrolytes function as highly conductive ion pathways, offering superior performance compared to other chemistries. Electric vehicle manufacturers are prioritizing this technology for next-generation long-range models due to its potential for fast charging. This focus on performance means sulfide technology is overtaking polymer and oxide-based systems in the race for commercialization in high-performance passenger vehicles.
Regulatory frameworks, including the EU Green Deal's transport decarbonization targets and the US EPA's stringent vehicle emissions standards, are creating powerful mandates for electrification. This policy pressure directly accelerates automaker investment in advanced battery technologies that promise longer range and faster charging. The passenger vehicle segment is most affected, with R&D roadmaps now heavily skewed toward solid-state battery commercialization.
The emergence of battery-as-a-service (BaaS) models decouples battery ownership from the vehicle itself, creating new lifecycle revenue streams. This model disrupts the traditional one-time vehicle sale by enabling battery swapping, upgrades, and flexible financing for fleet operators. This trend is most prominent in China, where it is being applied to commercial electric vehicle fleets to lower upfront costs.
EV SOLID State Battery Market Segmentation
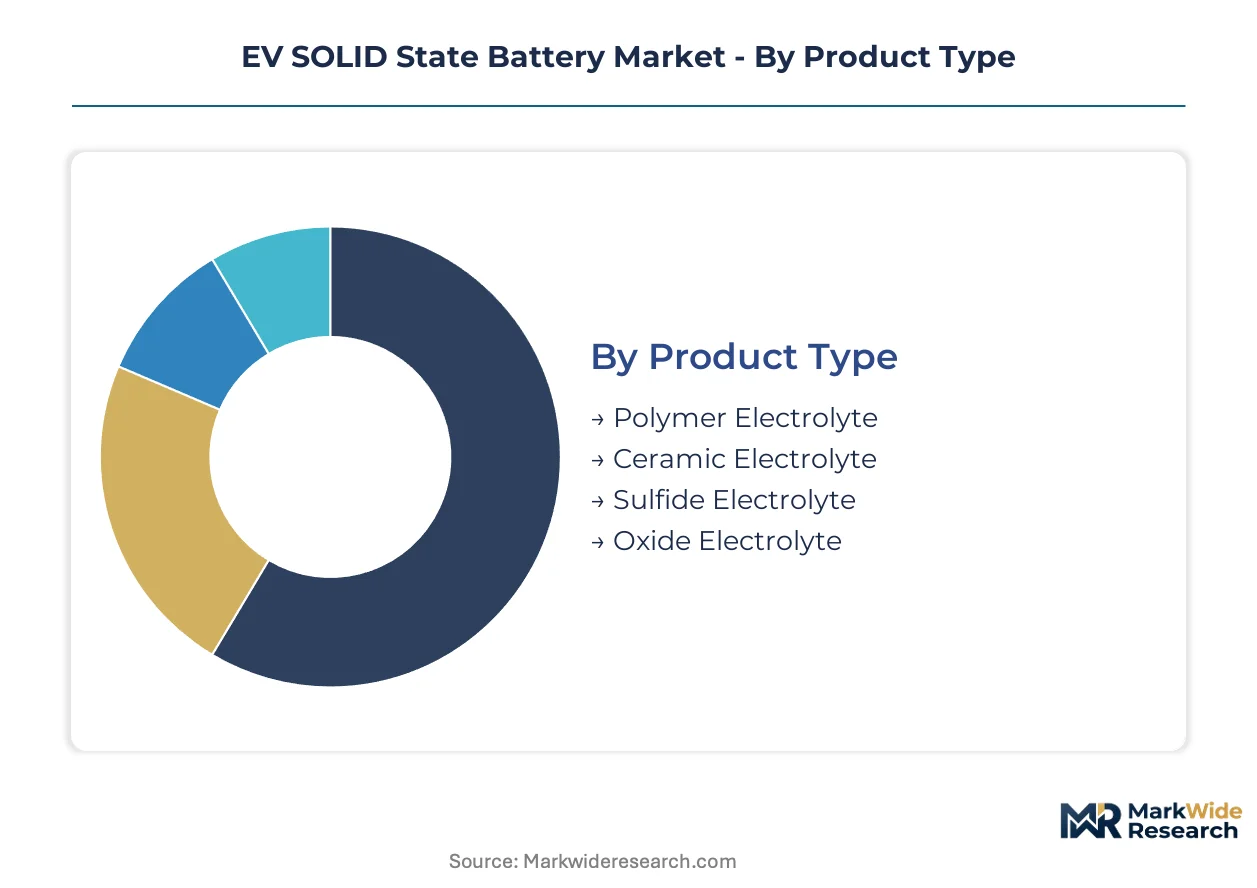
Understanding the EV solid-state battery market requires a detailed breakdown of its constituent parts. This segmentation highlights the diverse technological approaches, application areas, and supply chain participants driving market evolution. Analyzing these distinct segments reveals the specific demands and regulatory pressures shaping commercialization pathways.
Product Type:
The choice of product type in EV solid-state batteries often dictates the specific safety certifications required for automotive integration.
- Sulfide Electrolyte:Sulfide electrolytes offer high ionic conductivity, enabling faster charging and superior energy density for next-generation EV applications. Demand is concentrating in China's manufacturing hubs, driven by government support for advanced battery technologies.
- Polymer Electrolyte:Polymer electrolytes provide manufacturing flexibility and improved safety due to their solid, non-flammable nature. Automotive OEMs prioritize these systems for their adaptability in various vehicle platforms.
- Ceramic Electrolyte:Ceramic electrolytes offer high thermal stability and mechanical strength, essential for demanding EV operating conditions.
- Oxide Electrolyte:Oxide electrolytes provide excellent chemical stability and are being explored for high-voltage battery designs.
Leading the category by volume: Sulfide Electrolyte. Growing fastest: Polymer Electrolyte.
Application:
Application segments in the EV solid-state battery market exhibit varying cost sensitivities and performance requirements.
- Electric Passenger Vehicles:Automakers prioritize solid-state batteries for passenger vehicles to address range anxiety and reduce charging times. Demand is strong in Europe, driven by stringent EU Green Deal decarbonization targets.
- Electric Commercial Vehicles:Electric commercial vehicles require durable, high-capacity batteries to support heavy-duty cycles and long operational routes. China's logistics fleets are increasingly adopting these advanced battery solutions.
- Electric Two-Wheelers:Electric two-wheelers benefit from solid-state batteries' enhanced safety and compact design for urban mobility.
- Electric Buses:Electric buses need high energy density batteries to ensure sufficient range and rapid charging capabilities for public transport networks.
Electric Passenger Vehicles currently dominate this segment. Electric Commercial Vehicles show the steepest expansion trajectory.
End User:
The volume of solid-state battery procurement varies significantly across different end-user types in the EV supply chain.
- OEMs:Original Equipment Manufacturers integrate solid-state batteries directly into new vehicle designs, driving demand for high-volume, customized solutions. Toyota Motor Corporation is actively developing solid-state integration for future platforms.
- Tier-1 Suppliers:Tier-1 suppliers develop and assemble battery packs and modules for OEMs, requiring robust testing and scalability. These suppliers navigate complex specifications from multiple automotive clients.
- Vehicle Assemblers:Vehicle assemblers integrate pre-assembled battery systems into the final vehicle production line.
- Aftermarket Providers:Aftermarket providers focus on replacement batteries and upgrades, particularly for older EV models requiring performance enhancements.
OEMs represent the largest end-user segment. Tier-1 Suppliers are gaining share fastest as battery technology matures.
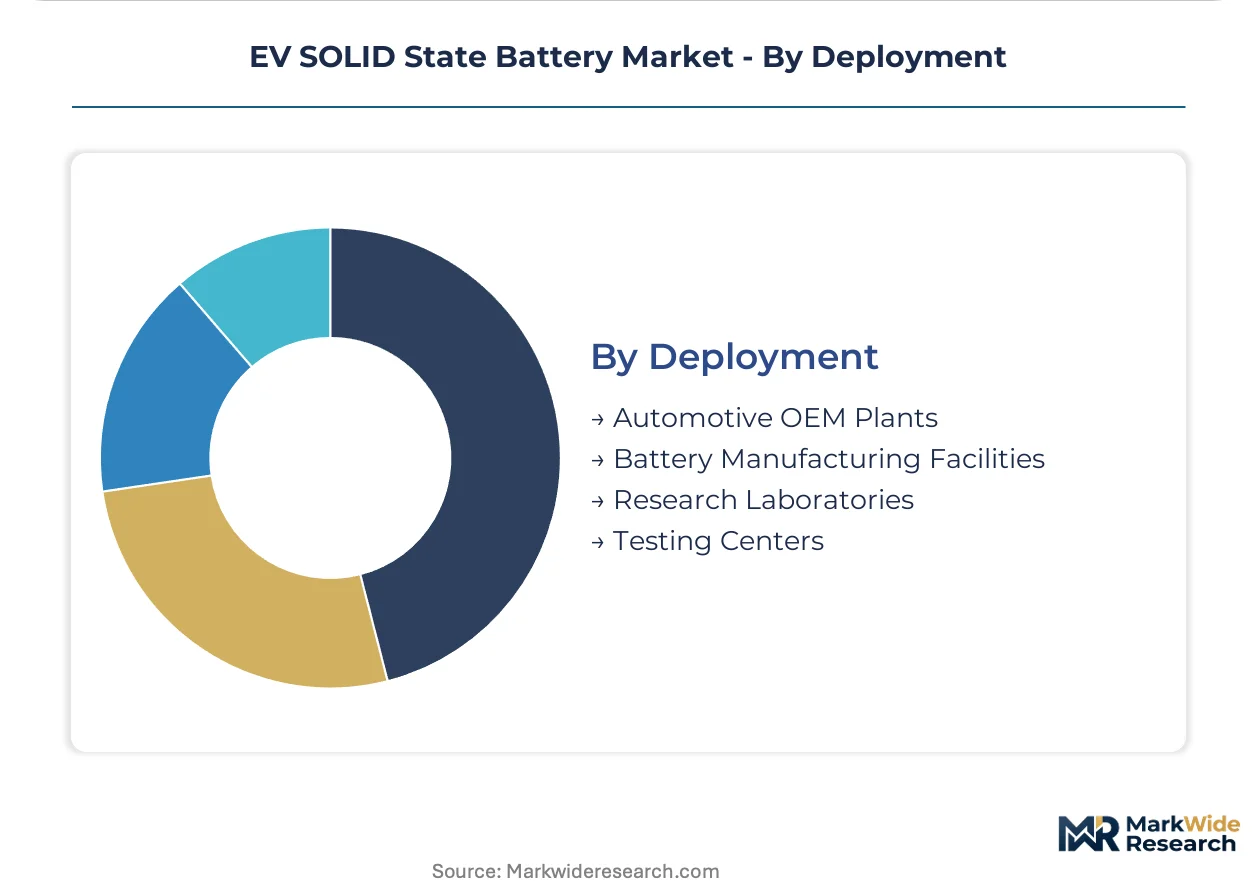
Deployment:
Deployment strategies for EV solid-state battery manufacturing reflect the concentrated nature of specialized production facilities.
- Battery Manufacturing Facilities:Dedicated battery manufacturing facilities specialize in large-scale production of solid-state cells and modules. These facilities require significant capital investment and highly controlled environments for advanced material handling.
- Automotive OEM Plants:Automotive OEM plants integrate battery assembly lines into vehicle production, optimizing logistics and reducing transportation costs. This approach supports localized production incentives like the US Inflation Reduction Act.
- Research Laboratories:Research laboratories focus on material science discovery and prototype development for next-generation solid-state chemistries.
- Testing Centers:Testing centers validate battery performance, safety, and longevity according to industry standards before commercial deployment.
Battery Manufacturing Facilities currently lead in deployment volume. Research Laboratories are climbing the fastest in terms of new investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capabilities for solid-state batteries are highly concentrated in East Asian manufacturing centers, while significant demand for electric vehicles drives development efforts across Europe and North America. This geographic divide shapes investment flows and technology transfer agreements. Automakers in all regions prioritize range and safety enhancements for mass-market EV adoption.
China
Strong domestic demand for electric vehicles fuels extensive research into advanced battery chemistries within China. China's dual carbon goals provide substantial government support for the EV supply chain, accelerating battery technology commercialization. Manufacturing hubs across the Yangtze River Delta and Pearl River Delta are expanding capacity for solid-state cell production.
United States
The United States seeks to overcome electric vehicle range anxiety and charging time limitations through advanced battery solutions. The US EPA's stringent vehicle emissions standards and the US Inflation Reduction Act (IRA) incentivize localized battery manufacturing. Research centers in Silicon Valley and automotive manufacturing hubs in Michigan are fostering solid-state battery innovation.
Germany
Germany's automotive industry drives demand for high-performance solid-state batteries to meet stringent European environmental targets. The EU Green Deal's transport decarbonization goals provide a strong regulatory pull for zero-emission vehicle technologies. Automotive R&D centers in Bavaria and emerging battery production sites in Saxony are integrating advanced battery designs.
Japan
Long-standing battery research and development expertise positions Japan as a key innovator in solid-state battery technology. METI initiatives actively support the development and commercialization of next-generation battery solutions. Aichi Prefecture, home to major automotive OEMs, and the Kansai region, with its strong materials science base, focus on solid-state integration.
South Korea
South Korea's major battery manufacturers are heavily investing in solid-state battery development to maintain global competitiveness. Government support for future mobility technologies encourages innovation in advanced electrochemical systems. The Seoul Capital Area, with its numerous R&D centers, and Ulsan, a significant automotive manufacturing hub, advance solid-state cell development.
EV SOLID State Battery Market Key Industry Players
Top-tier battery manufacturers anchor the supply side of the EV solid-state battery market, while specialist battery developers and established automotive OEMs also shape the competitive environment. The market exhibits a tiered structure, reflecting varying levels of technological maturity and production scale. Strategic archetypes include established automotive players, dedicated battery innovators, and materials science specialists. Competitive moves involve technology licensing and strategic partnerships to accelerate product development.
Established automotive players like Toyota Motor Corporation exemplify OEM-led integration efforts, leveraging extensive vehicle manufacturing expertise. Solid Power, Inc. represents the dedicated solid-state battery technology developers, specializing in sulfide-based systems for next-generation EV applications. Contemporary Amperex Technology Co., Ltd. signifies the large-scale battery manufacturing expertise transitioning to solid-state, aiming to scale production for a broader market.
| Leading Market Players |
|---|
| Solid Power, Inc. |
| QuantumScape Corporation |
| Toyota Motor Corporation |
| Samsung SDI Co., Ltd. |
| Contemporary Amperex Technology Co., Ltd. |
| ProLogium Technology Co., Ltd. |
| Blue Solutions |
| Factorial Energy |
| Ilika plc |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's transport decarbonization goals gate both qualified supply and premium-tier pricing access for advanced EV battery technologies. This regulatory environment necessitates robust material sourcing and manufacturing practices throughout the supply chain.
Pricing Analysis
Cost-down pressure on solid-state battery cells accelerates because manufacturing processes for sulfide electrolytes remain capital-intensive. The dominant pricing structure involves contract-based long-term offtake agreements between battery manufacturers and automotive OEMs. Price differentiation drivers include certification level for automotive safety standards and the volume scale of procurement. Electric passenger vehicle manufacturers are most price-sensitive, balancing performance with mass-market affordability, while specialized applications like eVTOL aircraft exhibit lower price sensitivity.
Supply Chain Analysis
Logistics and freight costs significantly influence the landed price of high-purity precursor materials for solid-state batteries. Geographic supply concentration for critical raw materials like high-purity lithium sulfide centers in China and South Korea. Raw material dependencies include lithium, sulfur, and specific ceramic or polymer precursors. A structural supply chain risk is the single-source vulnerability for specialized electrolyte components. Distribution runs through Tier-1 battery suppliers directly to Original Equipment Manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intensifying competition from established lithium-ion battery manufacturers is forcing weaker players out, framing this market as a consolidation play.
For Market Incumbents: Lock in long-term supply agreements for high-purity raw materials to mitigate commodity price volatility. Invest in next-generation sulfide electrolyte manufacturing capacity within key automotive hubs like Germany to reduce logistics costs. This strategy defends against new entrants leveraging localized production incentives, such as those offered by the US Inflation Reduction Act. Deepen vertical integration into cell assembly to control quality and cost.
For New Entrants and Emerging Players: Specialized polymer electrolyte technology offers a technology-first wedge into niche applications requiring manufacturing flexibility. Target the electric two-wheeler segment in Asia for initial market penetration, where cost sensitivity is balanced with safety demand. A go-to-market angle involves strategic partnerships with established automotive component suppliers to leverage existing distribution channels and OEM relationships.
For Investors and Strategic Acquirers: Increased patent filings for scalable solid-state manufacturing processes is the leading indicator that commercial viability approaches. Focus on acquisition targets with demonstrated pilot-line production capabilities for sulfide or polymer electrolytes. These companies often possess unique intellectual property and critical material science expertise. Long-term viability depends on achieving cost parity with advanced lithium-ion chemistries for mass-market EV adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Secure Long-Term Material Contracts | Ensures stable supply of critical precursors for battery production, mitigating price fluctuations. |
| Invest in Localized Manufacturing | Reduces transportation costs and aligns with regional incentives like the US Inflation Reduction Act. |
| Develop Polymer Electrolyte Systems | Offers manufacturing flexibility for diverse vehicle platforms and improved safety profiles. |
| Form Automotive OEM Partnerships | Accelerates technology integration and provides access to high-volume electric vehicle platforms. |
| Standardize Testing Protocols | Facilitates broader market acceptance and reduces validation times for new battery designs. |
Research Approach
Independent corroboration across industry whitepapers, government energy reports, and academic journals underwrites the qualitative findings and quantitative projections within this analysis. Primary interviews with OEM platform engineers, battery R&D leads, and government policy advisors informed specific market dynamics. The study employed both bottom-up and top-down triangulation to ensure data accuracy and comprehensive market coverage.
The rate-of-change decomposition framing structured the market forecast across the analysis window. Segmentation dimensions modeled include product type, application, end user, deployment, and regional regulatory cluster. Compound Annual Growth Rates were derived through a robust statistical analysis of historical data and projected market drivers. Key forecast inputs included electric vehicle production forecasts and advanced battery material cost trends.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events and rapid shifts in global economic policy. Forecasts reflect assumptions regarding technological advancements and regulatory stability throughout the projection horizon. Stakeholders should weigh assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Laminated Lithium Ion Secondary Battery Market
Lithium-ion Battery
Silicon Anode Lithium-Ion Battery Market
Lithium-ion Battery
Asia-Pacific Solid State Battery Market
Lithium-ion Battery
Lithium-Ion Battery Anode Market
Lithium-ion Battery
North America Lithium-Ion Battery Market
Lithium-ion Battery
Sodium Battery Electrolyte Market
Lithium-ion Battery
China SLI Battery Market
Lithium-ion Battery
France Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Graphene Battery Technology Market
Lithium-ion Battery
21700 Lithium Battery Sales Market
Lithium-ion Battery
France Electric Vehicle Lithium-Ion Battery Separator Market
Lithium-ion Battery
Thin Film Battery Market
Lithium-ion Battery
Sodium-Ion Battery Market
Lithium-ion Battery
Europe Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lithium Ion Capacitor Market
Lithium-ion Battery
Asia Pacific Electric Vehicle Battery Materials Market