
 Silicon Anode Battery Market | 2026-2036
Silicon Anode Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon Anode Battery Market Analysis
The capital-intensity divergence between thin-film deposition specialists and conventional graphite-anode incumbents is unwinding competitive assumptions in cell manufacturing. Amprius Technologies leverages its silicon nanowire architecture to sustain premium positioning in aerospace and defense contracting. Group14 Technologies anchors its commercial strategy on a silicon-carbon composite platform that competes directly with graphite cost curves at scale.
Silicon anode batteries substitute silicon or silicon-oxide materials for graphite at the negative electrode, achieving theoretical capacities near 4,200 mAh/g compared to graphite's 372 mAh/g limit, primarily to extend driving range in electric vehicles and runtime in portable electronics. The electric vehicle end user segment dominates current capacity allocations as automotive manufacturers negotiate long-term offtake agreements for silicon-anode cell supply. Solid-state technology configurations attract the fastest development funding despite lithium-ion formats controlling near-term manufacturing yield and cost structures.
The EPA tailpipe emission standards and NHTSA fuel economy mandates in the United States tighten compliance pathways that favor higher-density battery chemistries in vehicle electrification programs. China's MIIT and SAMR administer GB standards for cell safety and performance that gate market access for imported silicon-anode technologies. Stakeholders must monitor regulatory calibration timelines across multiple jurisdictions to align capital deployment with compliance windows.
Market Dynamics
The capital-intensity gap between silicon anode production and graphite anode manufacturing is restructuring competitive entry barriers as OEMs lock in multi-year supply contracts. Thin-film deposition equipment and nanoscale material handling capabilities now separate viable producers from aspirants.
Growth Catalysts
- EPA tailpipe emission standards:The United States mandates drive automotive OEMs toward higher energy density chemistries that extend electric vehicle range without increasing pack weight.
- Aerospace runtime extension:Unmanned aerial systems and satellite manufacturers procure silicon-anode cells for missions demanding maximum energy per kilogram.
- China's MIIT GB standards:Domestic certification requirements for cell safety and performance accelerate local silicon-oxide anode capacity buildout.
Market Restraints
- Purified metallurgical-grade silicon supply:Electrode-grade silicon feedstock concentrates among polysilicon producers serving photovoltaic markets, creating allocation competition during demand spikes.
- Electrolyte formulation incompatibility:Standard carbonate electrolytes degrade at silicon anode surfaces during lithiation cycles, requiring costly additive packages or alternative solvent systems.
- Cell formation energy consumption:Pre-lithiation and solid-electrolyte interphase conditioning steps add manufacturing overhead that graphite anodes avoid.
Strategic Opportunities
- India PLI scheme for advanced chemistry cells:Production-linked incentives for battery manufacturing attract silicon anode technology licensors seeking alternative supply bases outside China.
- Maritime electrification:Harbor vessels and short-route ferries require energy densities beyond lithium iron phosphate capabilities, opening a procurement channel with less price sensitivity than automotive.
- Solid-state convergence:Silicon anodes paired with sulfide or oxide solid electrolytes promise volumetric energy densities that liquid electrolyte formats cannot match.
Industry Challenges
- Electrochemist talent scarcity:The intersection of silicon surface chemistry, binder mechanics, and cell engineering requires specialists whose training pipelines lag capacity expansion timelines.
- Pre-lithiation equipment qualification:Stabilized lithium metal powders and vapor deposition systems demand cleanroom infrastructure unfamiliar to conventional electrode coating facilities.
- Recyclability certification:The EU Battery Regulation's recycled content thresholds for lithium and silicon remain undefined in implementing acts, freezing circular economy investment decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon Anode Battery Market |
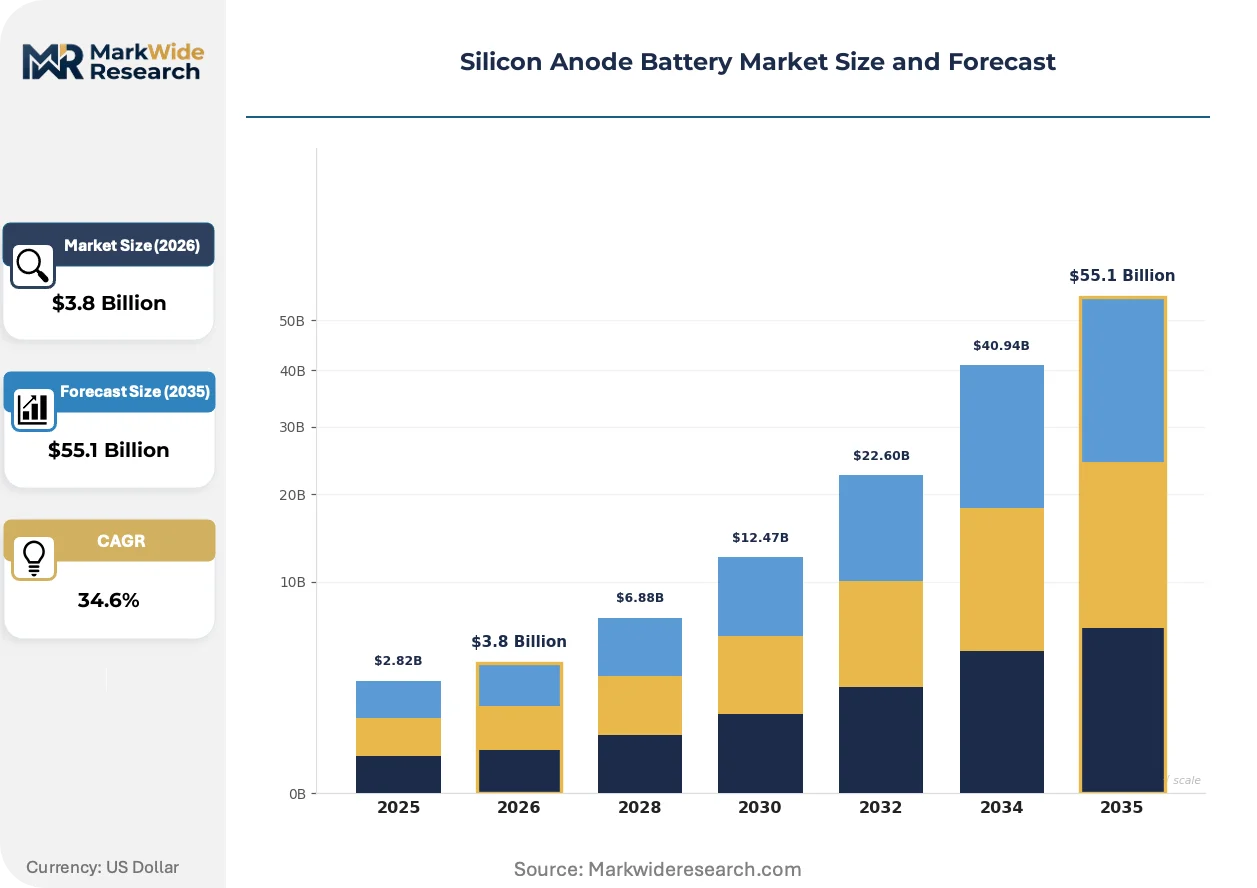
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $55.1 Billion |
| CAGR (2026 – 2036) | 34.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumer Electronics, Electric Vehicles, Energy Storage Systems, Aerospace End User: Automotive Manufacturers, Electronic Device Producers, Power Grid Operators, Aerospace Companies Technology: Lithium-Ion, Lithium Polymer, Solid-State, Hybrid Systems Application: Mobile Devices, EV Charging Infrastructure, Renewable Energy Storage, Defense Applications |
| Companies Covered | Amprius Technologies, Group14 Technologies, Sila Nanotechnologies, Enevate Corporation, ENOVIX Corporation, Nexeon Ltd, NanoGraf Corporation, XG Sciences, OneD Material, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Anode Battery Market Emerging Trajectories
Silicon anode architectures are fragmenting across deposition methods and composite formulations as manufacturers bet on divergent paths to cycle stability. Each technical route carries distinct capital requirements and performance trade-offs.
Silicon nanowire arrays grown directly on current collectors eliminate conventional slurry coating and calendaring steps. Aerospace battery pack designers at Tier 1 suppliers specify these architectures for applications where every gram of non-active material penalizes mission capability. The manufacturing footprint is miniaturizing as vapor-liquid-solid growth reactors replace batch chemical vapor deposition chambers, compressing cleanroom square footage requirements by an order of magnitude.
REACH authorization procedures for novel silicon nanoparticle surface treatments are extending formulation approval timelines for European market entry. The European Chemicals Agency's evolving nanomaterial registration requirements force simultaneous toxicology and electrochemical validation. Cell producers targeting EU automotive qualification are front-loading regulatory submission costs before performance optimization is complete.
Long-term offtake contracting is displacing spot purchasing for silicon anode precursor materials as automotive OEMs secure supply visibility. Tier 2 cathode and anode material suppliers report that battery cell manufacturers now demand five-year price ceilings indexed to silicon metal futures rather than quarterly negotiations. This pattern concentrates most visibly in South Korea where cell makers face IRA domestic content requirements that favor vertically integrated supply chain structures.
Silicon Anode Battery Market Segmentation
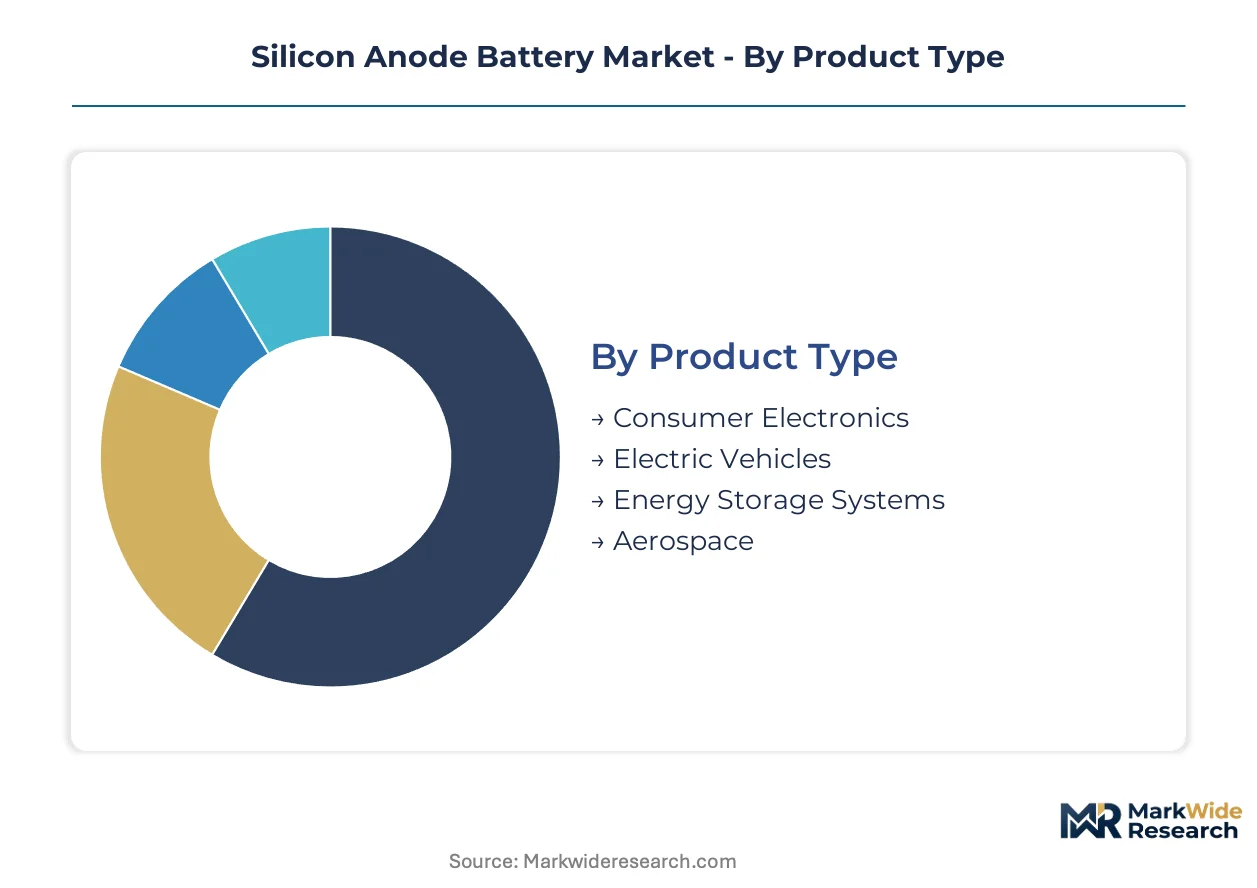
Silicon anode battery segmentation reveals how margin pools concentrate across high-value aerospace contracts versus volume-driven automotive procurement. Understanding these divides enables targeted capacity investment and partnership strategies.
Product Type:
Margin concentration skews toward applications where energy density commands absolute priority over unit cost.
- Electric Vehicles:Automotive OEMs negotiate multi-year offtake agreements for silicon-oxide anode cells, prioritizing range extension over pack weight reduction. China's CATL and BYD dominate capacity allocations for domestic EV platforms.
- Aerospace:Unmanned aerial systems and satellite manufacturers specify silicon nanowire architectures where every gram of non-active material penalizes mission capability. Tier 1 suppliers report premium pricing holds against graphite alternatives.
- Consumer Electronics:Smartphone and laptop manufacturers integrate silicon-anode cells for runtime extension in flagship product tiers.
- Energy Storage Systems:Grid-scale deployments favor hybrid configurations blending silicon with graphite to balance cycle life against capital expenditure constraints.
The dominant share belongs to Electric Vehicles, while Aerospace is closing the gap fastest on margin contribution per megawatt-hour.
End User:
Procurement sophistication varies sharply between vertically integrated automotive groups and fragmented electronics assemblers.
- Automotive Manufacturers:OEMs in Germany and South Korea lock in five-year supply contracts with price ceilings indexed to silicon metal futures. The EU Battery Regulation's carbon footprint declarations reshape sourcing qualification criteria.
- Aerospace Companies:Defense contractors and commercial satellite operators demand traceable supply chains with ITAR or EASA certification. Pre-lithiation equipment qualification requirements filter supplier pools aggressively.
- Electronic Device Producers:Mobile and computing brands source through tiered supplier structures with limited direct anode material engagement.
- Power Grid Operators:Utility procurement favors lithium iron phosphate for stationary storage, limiting silicon anode penetration outside demonstration projects.
Automotive Manufacturers capture the largest procurement volume, though Aerospace Companies deliver the steepest expansion trajectory in contract value.
Technology:
Manufacturing yield differentiation separates commercially viable formats from laboratory-scale alternatives.
- Solid-State:Silicon anodes paired with sulfide or oxide electrolytes promise volumetric energy densities unreachable by liquid formats. South Korean cell makers channel IRA-compliant funding into pilot production lines.
- Lithium-Ion:Silicon-oxide and silicon-carbon composite anodes integrate into existing electrode coating infrastructure with modified binder systems. China's MIIT GB standards gate market access for imported technologies.
- Lithium Polymer:Pouch cell formats accommodate silicon expansion through flexible packaging, limiting adoption to premium consumer electronics.
- Hybrid Systems:Blended silicon-graphite anodes balance capacity gains against cycle stability in grid storage applications.
Lithium-Ion retains the dominant installed base, while Solid-State is gaining share fastest on development funding inflows.
Application:
Deployment timelines stretch from immediate consumer product integration to decade-long defense qualification cycles.
- EV Charging Infrastructure:Fast-charging station buffer batteries require high C-rate capability that silicon anodes degrade under, limiting near-term adoption.
- Mobile Devices:Flagship smartphone launches drive annual demand spikes for compact silicon-anode cells with premium energy density specifications.
- Renewable Energy Storage:Solar and wind farm developers prioritize levelized cost of storage over energy density, marginalizing silicon anode economics.
- Defense Applications:Military specifications for extreme temperature operation and mechanical abuse tolerance favor silicon nanowire architectures with extended qualification timelines.
Mobile Devices holds the dominant revenue position, while Defense Applications is climbing the fastest on classified program ramp-ups.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive procurement in China tolerates price premiums for range extension, while European utilities reject silicon anode economics for grid storage. Aerospace buyers in the United States accept cost multiples that consumer electronics brands in South Korea dismiss.
China
CATL and BYD negotiate multi-year offtake agreements for silicon-oxide anode cells serving domestic EV platforms. MIIT and SAMR administer GB standards for cell safety and performance that gate market access for imported technologies. The Yangtze River Delta hosts the densest concentration of electrode-grade silicon precursor production.
United States
Defense contractors and commercial satellite operators demand silicon nanowire architectures for missions where every gram of non-active material penalizes capability. EPA tailpipe emission standards and NHTSA fuel economy mandates tighten compliance pathways favoring higher-density battery chemistries. Silicon Valley and Greater Boston anchor venture funding for solid-state silicon anode development.
Germany
Automotive OEMs lock in five-year supply contracts with price ceilings indexed to silicon metal futures. The EU Battery Regulation mandates carbon footprint declarations and recycled content thresholds that reshape material sourcing qualification criteria. Bavaria's industrial corridor concentrates cell testing and pack integration facilities.
South Korea
Cell makers channel IRA-compliant funding into pilot production lines for silicon anode solid-state configurations. MFDS and related agencies coordinate with automotive safety regulators on battery certification protocols. The Seoul Capital Area houses the headquarters of tier-1 suppliers negotiating backward integration into anode material production.
India
Production-linked incentives for advanced chemistry cell manufacturing attract silicon anode technology licensors seeking alternative supply bases outside China. The CEA and BIS administer evolving standards for battery safety and performance. Gujarat and Tamil Nadu host the first wave of giga-factory commitments with silicon anode compatibility built into design specifications.
Silicon Anode Battery Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where premium positioning and scale economics rarely coexist. The vendor base separates into thin-film deposition specialists, silicon-carbon composite platform operators, and conventional graphite-anode incumbents retrofitting capacity. Two dominant competitive moves define current dynamics: multi-year offtake contracting that locks in supply visibility, and strategic partnerships with automotive OEMs seeking IRA-compliant domestic content. Geographic expansion into India and Southeast Asia represents a secondary vector as producers diversify beyond Chinese supply chain exposure.
Within the nanowire architecture tier, Amprius Technologies occupies a position exemplifying premium aerospace and defense contracting. Group14 Technologies and Sila Nanotechnologies sit within the silicon-carbon composite segment, representing alternative paths to cost parity with graphite at manufacturing scale. These three companies anchor distinct technical approaches that structure competitive segmentation across end-use applications.
| Leading Market Players |
|---|
| Amprius Technologies |
| Group14 Technologies |
| Sila Nanotechnologies |
| Enevate Corporation |
| ENOVIX Corporation |
| Nexeon Ltd |
| NanoGraf Corporation |
| XG Sciences |
| OneD Material |
| Others |
Supply Flow & Price Mechanics
Electrode-grade silicon precursor capacity utilization above 85 percent in the Yangtze River Delta locks in cost advantages that smaller deposition facilities cannot match, compressing price floors for silicon-oxide anode cells while elevating premiums for nanowire architectures with aerospace qualification.
Pricing Analysis
After-sales revenue from cell formation services and extended performance warranties drives lifetime value for silicon anode manufacturers. Contract-based long-term offtake dominates, with five-year price ceilings indexed to silicon metal futures separating automotive procurement from spot purchasing in consumer electronics. Price differentiation rests on certification grade—EASA or ITAR traceability commands substantial premiums over standard industrial tiers. Cost compression in silicon-carbon composite tiers is intensifying as Group14 Technologies and Sila Nanotechnologies approach graphite cost parity. Consumer electronics brands exhibit the highest price sensitivity, while defense contractors accept cost multiples for mission-critical energy density.
Supply Chain Analysis
Port congestion on the Shanghai-Rotterdam trade lane elevates inbound logistics costs for European cell manufacturers dependent on Chinese electrode-grade silicon. Supply concentrates in China, South Korea, and Germany, with purified metallurgical-grade silicon feedstock drawing from polysilicon producers serving photovoltaic markets. Key inputs include stabilized lithium metal powders, nanoscale silicon precursors, and specialized carbonate electrolyte formulations with additive packages. Single-source vulnerability in thin-film deposition equipment—vapor-liquid-solid growth reactors and chemical vapor deposition chambers—creates qualification bottlenecks. Distribution runs through vertically integrated battery cell manufacturers with captive anode material production or long-term tolling agreements with Tier 2 suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment—EU Battery Regulation carbon footprint declarations and recycled content thresholds—locks in incumbent advantages through multi-year qualification timelines that new entrants cannot accelerate.
For Market Incumbents: Secure multi-year offtake agreements with automotive OEMs before IRA domestic content requirements fully crystallize, locking in volume commitments that starve emerging competitors of scale. Deepen backward integration into electrode-grade silicon precursor production to insulate margin structures from photovoltaic market demand spikes. Invest in pre-lithiation equipment qualification ahead of EU implementing acts defining recycled content thresholds, converting regulatory uncertainty into a barrier for late movers.
For New Entrants and Emerging Players: Maritime electrification harbor vessels and short-route ferries represent an underserved application where energy density requirements exceed lithium iron phosphate capabilities and price sensitivity trails automotive procurement. India's PLI scheme for advanced chemistry cells offers a geographic white space with silicon anode compatibility built into initial giga-factory specifications. Pursue technology licensing arrangements with established electrode coating facilities rather than greenfield capacity, accelerating time-to-revenue while avoiding cleanroom infrastructure capital intensity.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among silicon-carbon composite platform operators with automotive qualification and long-term supply contracts indexed to input futures rather than spot markets. Over a five-to-ten year horizon, acquisition targets should demonstrate viable paths to manufacturing yield above 80 percent in lithium-ion formats or secured pilot line funding for solid-state configurations. The signal to watch is EPA tailpipe emission standard calibration timelines, which would accelerate OEM procurement decisions and revalue qualified supplier pipelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Locks in electrode-grade silicon allocation ahead of photovoltaic demand spikes. |
| Technology Licensing | Accelerates market entry for new entrants via existing electrode coating infrastructure. |
| Capacity Expansion | Captures automotive OEM volume commitments under IRA domestic content requirements. |
| Backward Integration | Insulates margin structures from polysilicon market price volatility. |
| Joint Venture | Distributes solid-state pilot line capital burden across multiple funding sources. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and industry association disclosures. Primary interviews engaged cell engineering directors at Tier 1 battery manufacturers, procurement leads at automotive OEMs, electrochemists at anode material suppliers, and aerospace certification specialists. Secondary validation drew from EPA emission standard dockets, EU Battery Regulation implementing acts, MIIT GB standard publications, and SEC filings of publicly traded battery technology companies. Bottom-up capacity buildout estimates triangulated against top-down automotive electrification penetration scenarios.
Segmentation dimensions modeled include product architecture, end-user procurement sophistication, technology format, and application deployment timeline across the projection horizon. CAGRs were derived from installed base growth, replacement demand patterns, and technology substitution curves. Industry-specific forecast inputs incorporated silicon metal futures pricing volatility, pre-lithiation equipment lead times, and solid-state electrolyte manufacturing yield trajectories.
Underlying assumptions cover stable regulatory calibration timelines for EPA and EU Battery Regulation compliance windows, with deviation risk concentrated in accelerated solid-state technology maturation or abrupt photovoltaic silicon feedstock allocation shifts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Germany Electric Vehicle Battery Anode Market
Lithium-ion Battery
Bangladesh Lithium-Ion Battery Market
Lithium-ion Battery
Automotive Lithium-Ion Battery Cell Market
Lithium-ion Battery
Pouch Lithium-Ion Batteries Market
Lithium-ion Battery
Lithium-Air Battery Market
Lithium-ion Battery
Asia Pacific Electric Vehicle Battery Anode Market
Lithium-ion Battery
Lithium-Ion Battery Separator Market
Lithium-ion Battery
Germany SLI Battery Market
Lithium-ion Battery
Graphene Battery Technology Market
Lithium-ion Battery
Europe Electric Vehicle Battery Anode Market
Lithium-ion Battery
Global Nanowire Battery Market
Lithium-ion Battery
Solid Electrolyte for Lithium Ion Battery Market
Lithium-ion Battery
Lithium Nickel Manganese Cobalt Oxide Battery Market
Lithium-ion Battery
Prismatic Lithium Cobalt Oxide (LiCoO2) Battery Market
Lithium-ion Battery
Lithium-Ion (Li-Ion) Batteries Market
Lithium-ion Battery
China Electric Vehicle Battery Anode Market