
 Asia-Pacific Water Enhancer Market | 2026-2036
Asia-Pacific Water Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Water Enhancer Market Outlook
FSSAI clean-label certification is bifurcating the Asia-Pacific water enhancer competitive landscape into compliant formulators and legacy players facing reformulation costs. The Kraft Heinz Company leverages its condiment R&D infrastructure to cross-apply flavor science into low-calorie enhancer lines. PepsiCo anchors its position through deep convenience store penetration across Southeast Asian metropolitan corridors. Dyla LLC (Stur) differentiates via stevia-only formulations that preempt sugar-tax exposure in multiple regional markets.
Asia-Pacific water enhancers comprise concentrated liquid, powder, or tablet formulations designed to dissolve in plain water, typically containing electrolytes, vitamins, natural or artificial flavoring agents, and zero- to low-calorie sweeteners with serving sizes calibrated to 2-16 fluid ounces of water. These products serve commercial and consumer hydration needs by transforming tap or bottled water into flavored, functional beverages without carbonation infrastructure. Liquid formats dominate current shelf presence due to single-serve portability and minimal dissolution friction, while powder segments capture bulk-buying households seeking cost-per-serve efficiency. Health Stores distribution channels carry disproportionate margin pools as they stock premium-positioned herbal and spice-flavored variants targeting athletes and wellness-focused consumers.
Japan's Consumer Affairs Agency enforces strict additive disclosure rules that elevate compliance costs for imported enhancer brands. India's FSSAI and China's SAMR collectively shape regional formulation standards through divergent sweetener approval lists and labeling mandates. Australia's TGA overlaps with food standards in regulating vitamin-fortified enhancer claims, creating a multi-jurisdictional compliance burden. Stakeholders must monitor evolving sugar-tax proposals across Southeast Asian economies and pre-position reformulated portfolios before tariff-triggered demand shifts materialize.
Market Dynamics
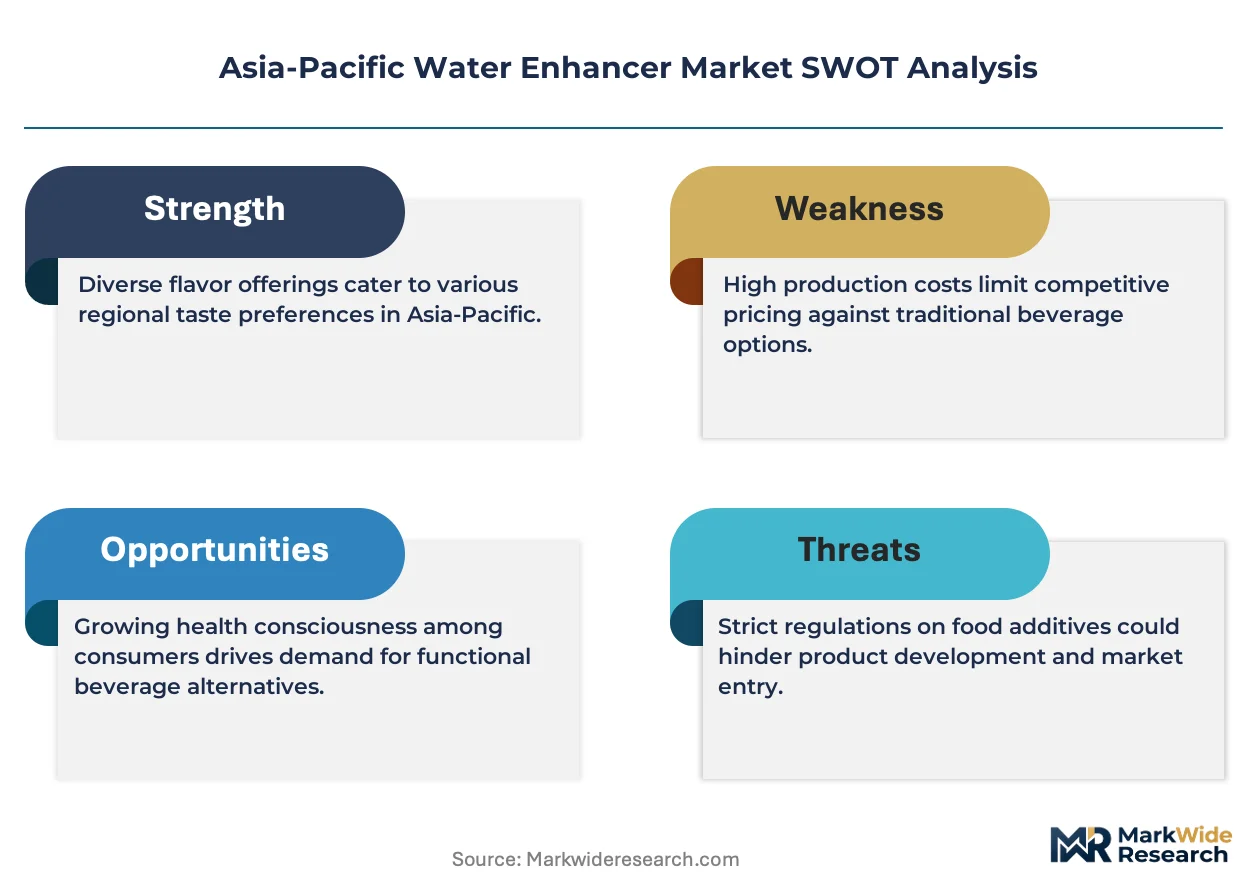
FSSAI clean-label mandates are forcing rapid reformulation across the Asia-Pacific water enhancer supply base, splitting compliant producers from legacy operators facing steep compliance costs.
Growth Catalysts
- Electrolyte-Enhanced Formulations:Fitness enthusiasts in China's tier-one cities are driving demand for protein-fortified and mineral-dense variants calibrated to post-workout recovery protocols.
- Sugar-Tax Prepositioning:Stevia-only sweetener systems are capturing shelf space ahead of anticipated excise duties across Southeast Asian economies.
- Congestion-Driven Portability:Single-serve liquid formats dominate urban commuting corridors in Shanghai and Beijing where consumers prioritize minimal-carry hydration solutions.
Market Restraints
- Multi-Jurisdictional Compliance Burden:Divergent sweetener approval lists between India's FSSAI and China's SAMR create formulation lock-in risks for regional portfolios.
- Import Cost Escalation:Japan's Consumer Affairs Agency disclosure rules elevate testing and labeling expenditures for foreign brands entering the market.
- Tap Water Substitution:Municipal infrastructure improvements in select Australian and South Korean metros reduce the perceived value proposition of enhancer products.
Strategic Opportunities
- Rural India Penetration:Powder formats priced for cost-per-serve efficiency can access underserved households beyond tier-one urban centers.
- Herbal-Flavor Premiumization:Health Stores channels in Australia and Japan carry disproportionate margins for spice-infused variants targeting wellness consumers.
- Vitamin-Fortified Positioning:Australia's TGA regulatory overlap creates a pathway for clinical-grade hydration claims distinct from standard food-grade positioning.
Industry Challenges
- Reformulation Timeline Compression:Accelerated FSSAI certification deadlines strain R&D bandwidth for legacy artificial-sweetener portfolios.
- Flavor Science Talent Scarcity:Cross-functional expertise bridging condiment R&D and low-calorie beverage systems commands premium compensation in competitive labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Water Enhancer Market |
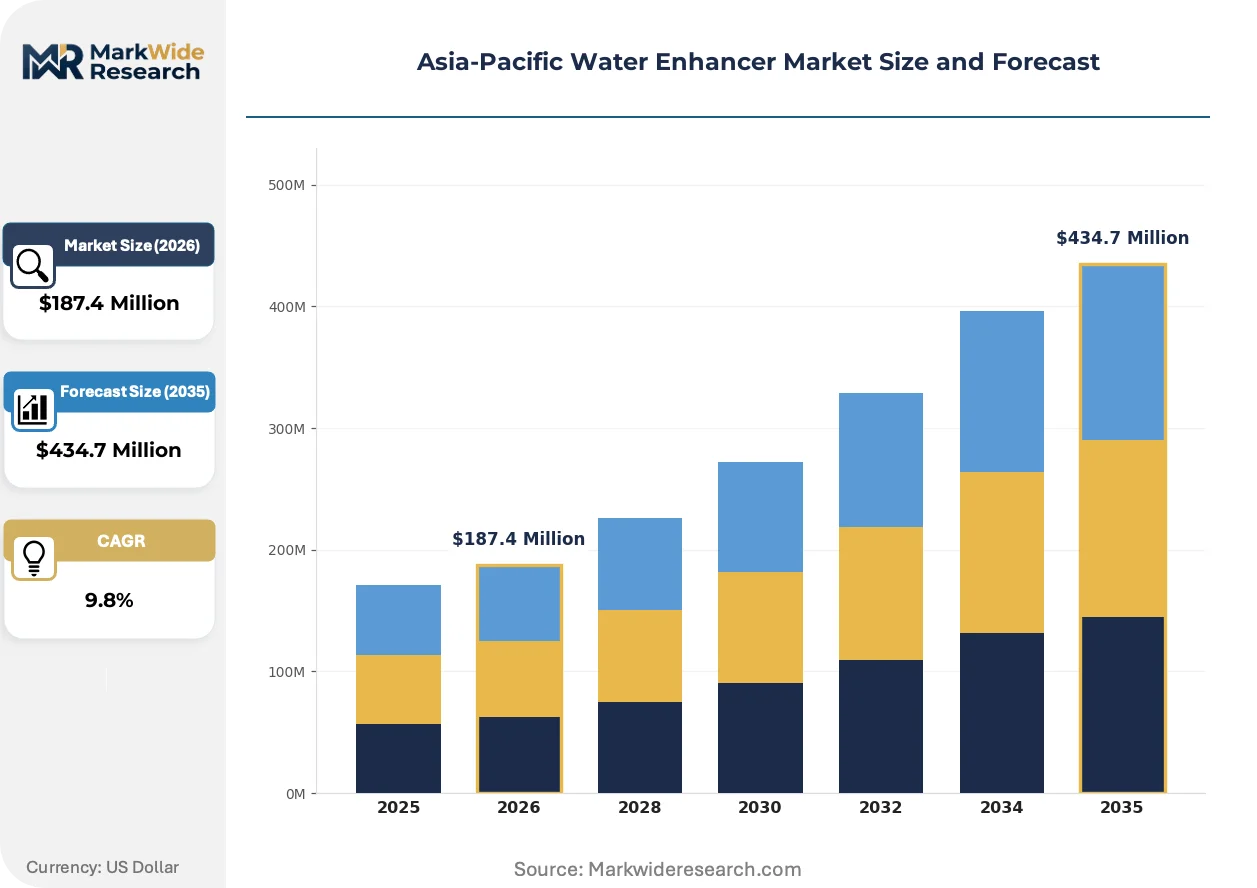
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $434.7 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Concentrate, Tablet Flavor Profile: Fruit, Herbal, Spice, Savory Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Health Stores End User: Fitness Enthusiasts, Health-conscious Consumers, Athletes, General Population |
| Companies Covered | The Kraft Heinz Company, Dyla LLC (Stur), The Coca-Cola Company, Keurig Dr Pepper Inc, INFUZE, FLAVR Group, AriZona Beverages USA LLC, Wisdom Natural Brands, PepsiCo Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Water Enhancer Market Strategic Shifts
Stevia-extraction refinement and clean-label certification protocols are actively bifurcating the Asia-Pacific competitive landscape between premium natural-positioned lines and legacy artificial-formulation incumbents.
Cold-pressed stevia glycoside extraction is displacing conventional heat-processed sweetener systems across premium-positioned product lines. Japanese and Australian wellness consumers are adopting these variants at accelerated rates, compressing demand for aspartame and sucralose formulations in health-focused retail channels.
SAMR's tightening of pre-market additive registration requirements is elevating documentation burdens for imported enhancer brands. Domestic Chinese formulators with established regulatory dossiers are capturing shelf space from foreign competitors facing extended approval timelines. Vitamin-fortified claims face heightened substantiation scrutiny under overlapping TGA and food standards frameworks.
Convenience store penetration strategies are consolidating distribution influence in Southeast Asian metropolitan corridors. Traditional grocery channels in Bangkok and Jakarta are losing share to 24-hour retail formats where single-serve liquid enhancers dominate impulse purchase occasions. Urban commuter patterns in these cities are reinforcing portable-format preference hierarchies.
Asia-Pacific Water Enhancer Market Segmentation
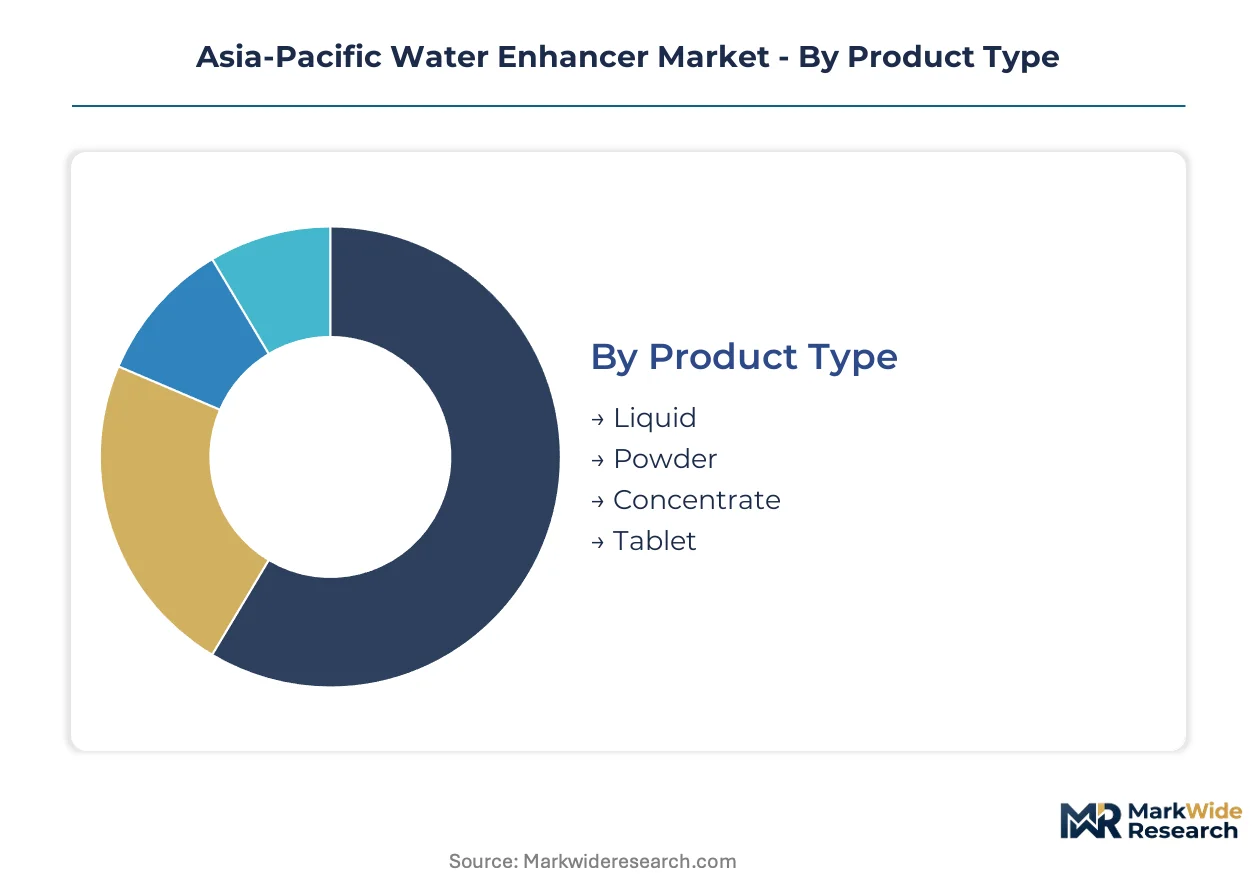
Asia-Pacific water enhancer segmentation reveals divergent channel strategies across format types. Liquid concentrates dominate convenience retail in congested urban corridors, while powder variants access price-sensitive households through bulk e-commerce channels.
Product Type:
Liquid formats flow through convenience store networks in Shanghai and Beijing, while powder concentrates capture rural India via online retail bulk purchasing.
- Liquid:Single-serve droppers and squeeze bottles dissolve instantly without agitation. China's tier-one cities concentrate demand for portable 2-ounce vials calibrated to 500ml bottled water, driven by subway commuting patterns and office hydration rituals.
- Powder:Sachet and jar formats deliver cost-per-serve efficiency for household stockpiling. India's tier-two and tier-three cities represent the primary expansion zone as FSSAI clean-label certification enables premium positioning in emerging retail channels.
- Concentrate:Multi-dose bottles target foodservice and institutional buyers seeking fountain-dispensed flavor systems.
- Tablet:Effervescent formats appeal to outdoor recreation segments in Australia and Japan with extended shelf stability.
Liquid dominates installed base. Powder is where expansion concentrates.
Flavor Profile:
Margin concentration varies sharply across taste categories, with herbal variants commanding premium positioning in health-focused retail.
- Fruit:Citrus and berry formulations anchor mass-market penetration through supermarket promotional cycles. Southeast Asian markets show particular affinity for tropical fruit profiles—mango, lychee, and calamansi—aligned with local palate preferences.
- Herbal:Ginger, turmeric, and ginseng infusions target wellness consumers in Japanese and Australian Health Stores channels. Australia's TGA regulatory framework enables clinical-grade hydration claims that differentiate these variants from standard food-grade positioning.
- Spice:Cardamom, cinnamon, and chili-lime profiles serve niche ethnic markets and fusion cuisine crossover applications.
- Savory:Umami and vegetable-based formulations remain experimental, primarily confined to Japanese functional beverage innovation pipelines.
Fruit commands volume leadership. Herbal posts the steepest expansion trajectory.
Distribution Channel:
Channel mix reflects urban infrastructure density and regulatory compliance burdens across national markets.
- Online Retail:E-commerce platforms capture subscription-based replenishment and bulk powder purchasing. India's direct-to-consumer channels bypass traditional retail markups while navigating FSSAI labeling requirements through digital disclosure protocols.
- Supermarkets:Multi-brand shelf sets in Australia's Coles and Woolworths networks standardize liquid format visibility. China's SAMR pre-market registration requirements favor domestic formulators with established dossiers in these high-volume channels.
- Convenience Stores:24-hour formats in Bangkok, Jakarta, and Manila drive impulse liquid purchases through checkout-adjacent placement.
- Health Stores:Specialty retailers in Japan and Australia stock premium herbal variants with disproportionate margin structures.
Supermarkets anchor volume throughput. Online Retail is climbing the fastest.
End User:
User segmentation maps directly to functional claim intensity and price tolerance thresholds.
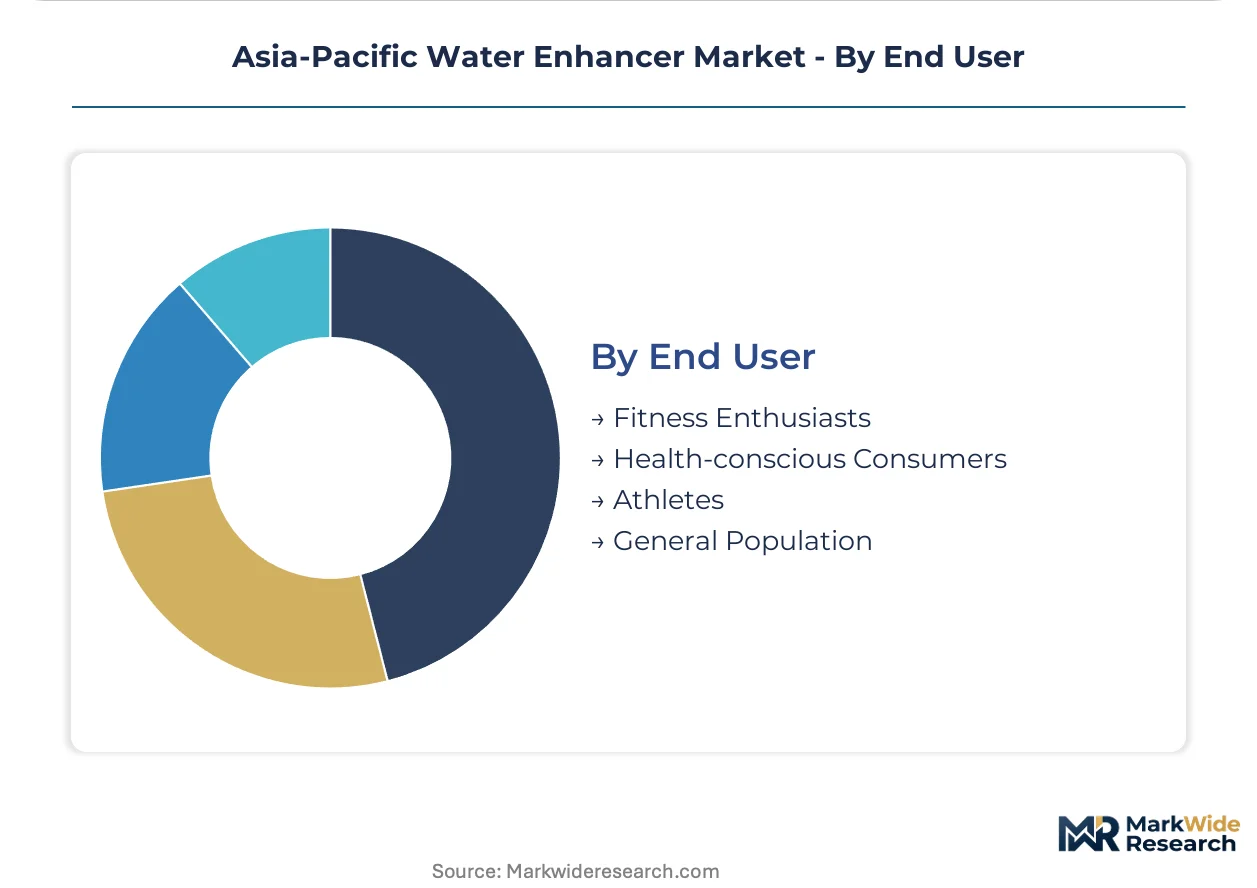
- Fitness Enthusiasts:Protein-enhanced and electrolyte-dense formulations dominate post-workout consumption occasions. China's gym culture expansion in Shenzhen and Chengdu drives calibrated mineral replenishment protocols.
- Health-conscious Consumers:Stevia-sweetened and clean-label variants attract sugar-avoidant households across Australia's metropolitan corridors. Japan's Consumer Affairs Agency disclosure rules elevate transparency expectations in this segment.
- Athletes:Clinical-grade vitamin fortification and isotonic calibration serve competitive training regimens under Australia's TGA overlapping jurisdiction.
- General Population:Flavor-preference-driven purchasing in Southeast Asian mass markets prioritizes palatability over functional claims.
General Population represents volume base. Fitness Enthusiasts is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fitness enthusiasts in China's tier-one cities anchor regional demand, while health-conscious households in Australia and Japan drive premium natural-positioned adoption. India's emerging middle class and Southeast Asia's convenience retail expansion complete the buyer mosaic.
China
Shanghai and Beijing commuters favor single-serve liquid vials calibrated to 500ml bottled water for subway and office hydration rituals. SAMR's pre-market additive registration requirements favor domestic formulators with established dossiers over foreign entrants facing extended approval timelines. Shenzhen and Chengdu gym culture expansion drives protein-enhanced and electrolyte-dense formulation demand.
India
Tier-two and tier-three cities represent the primary powder format expansion zone as cost-per-serve efficiency attracts price-sensitive households. FSSAI clean-label certification mandates are bifurcating the competitive landscape into compliant producers and legacy operators facing reformulation costs. Mumbai and Delhi-NCR concentrate health-conscious consumer demand for stevia-sweetened variants in emerging retail channels.
Japan
Wellness consumers in Tokyo and Osaka are adopting cold-pressed stevia glycoside formulations at accelerated rates. The Consumer Affairs Agency enforces strict additive disclosure rules that elevate compliance costs for imported enhancer brands. Kanto region health stores carry disproportionate margins for ginger, turmeric, and ginseng infusion variants.
Australia
Metropolitan corridors in Sydney and Melbourne attract sugar-avoidant households to clean-label stevia formulations. TGA regulatory overlap with food standards creates a multi-jurisdictional compliance burden for vitamin-fortified clinical-grade hydration claims. Specialty health retailers stock premium spice-infused variants targeting athletes and wellness consumers.
Thailand
Bangkok's 24-hour convenience store networks drive impulse liquid purchases through checkout-adjacent placement. Anticipated sugar-tax proposals across Southeast Asian economies are accelerating stevia-only sweetener system adoption. Urban commuter patterns reinforce portable-format preference hierarchies in metropolitan retail corridors.
Asia-Pacific Water Enhancer Market Competitive Environment
Player mix skews toward multinational beverage conglomerates with condiment and flavor science infrastructure, mid-size natural-formulation specialists, and domestic Asian formulators with regulatory dossier advantages. The competitive terrain splits across three strategic archetypes: legacy artificial-sweetener incumbents facing reformulation pressure, clean-label stevia-positioned challengers, and domestic regulators-preferred local producers. M&A activity targets flavor science talent and regional distribution networks, while portfolio diversification accelerates toward electrolyte-enhanced and protein-fortified functional variants.
Among multinational packaged goods conglomerates, The Kraft Heinz Company and PepsiCo occupy positions leveraging cross-category R&D infrastructure and convenience store penetration respectively. Dyla LLC (Stur) exemplifies the stevia-only formulation archetype that preempts sugar-tax exposure across multiple regional markets. These three anchors illustrate the competitive tension between scale-driven distribution power and natural-positioned regulatory agility.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| Dyla LLC (Stur) |
| The Coca-Cola Company |
| Keurig Dr Pepper Inc |
| INFUZE |
| FLAVR Group |
| AriZona Beverages USA LLC |
| Wisdom Natural Brands |
| PepsiCo Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Chinese domestic formulators and stevia glycoside suppliers lock in both raw material access and cost predictability across the Asia-Pacific water enhancer value chain. These contractual structures insulate compliant producers from spot-market volatility while legacy artificial-sweetener portfolios absorb reformulation-driven cost spikes.
Pricing Analysis
Cost-plus contracts with stevia indexation dominate procurement between extractors and finished-goods manufacturers. Three-tier pricing structure across premium herbal-infused, standard fruit-flavored, and economy powder formats reflects FSSAI certification grade and distribution channel markup. Pricing pressure stems from accelerated clean-label compliance deadlines compressing R&D amortization timelines. Powder format buyers in India's tier-two cities exhibit highest price sensitivity, while Australian health store channels tolerate substantial premiums for TGA-aligned clinical-grade positioning.
Supply Chain Analysis
China and India anchor stevia leaf cultivation and glycoside extraction capacity respectively. Formulation draws from Chinese flavor science infrastructure, Indian regulatory dossier expertise, and Japanese precision-manufacturing components. Single-source vulnerability concentrates in cold-pressed extraction equipment supplied through limited Japanese and German vendors. Distribution runs through convenience store networks in Southeast Asian metros and direct-to-consumer platforms in Indian urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flavor science talent capable of bridging condiment R&D heritage with low-calorie beverage systems commands premium compensation and represents the binding constraint on portfolio transformation timelines. Incumbents and challengers alike face capability gaps in clean-label formulation chemistry.
For Market Incumbents: Secure exclusive supply agreements with cold-pressed stevia extractors before capacity constraints tighten. Accelerate backward integration into flavor science talent pipelines through targeted recruitment from condiment and sauce R&D divisions. Defensive positioning requires preemptive FSSAI certification of full portfolios ahead of enforcement phase-ins. For New Entrants and Emerging Players: Differentiate via stevia-only positioning that preempts sugar-tax exposure across Thai and Indonesian markets. Penetrate India's tier-two and tier-three cities through bulk powder formats priced for cost-per-serve efficiency. Direct-to-consumer subscription models bypass traditional retail markups while navigating labeling requirements through digital disclosure protocols. For Investors and Strategic Acquirers: Domestic Asian formulators with established SAMR and FSSAI regulatory dossiers represent the most defensible acquisition archetype. Long-term viability hinges on clean-label certification breadth and distribution depth in convenience retail corridors. Monitor FSSAI enforcement acceleration as the primary demand-shift inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Certification Investment | FSSAI compliance unlocks premium positioning in India's emerging retail channels. |
| Stevia Supply Agreement | Long-term offtake with Chinese extractors secures cost visibility ahead of sugar-tax implementation. |
| Convenience Store Expansion | Checkout-adjacent placement in Bangkok and Jakarta corridors captures impulse liquid purchases. |
| Flavor Science Talent Acquisition | Cross-functional R&D expertise bridges condiment heritage into low-calorie beverage innovation. |
| Powder Format Localization | Cost-per-serve efficiency targets underserved households beyond China's tier-one urban centers. |
Study Parameters
The analysis maps liquid concentrates, powder sachets, effervescent tablets, and multi-dose concentrates, each validated through formulation chemists, regulatory affairs specialists at FSSAI and SAMR, convenience store category buyers, and health store procurement managers. Primary interview data triangulates against secondary sources including customs records, FSSAI additive approval registries, TGA vitamin claim substantiation filings, and Nielsen retail audit data across Asia-Pacific metropolitan corridors. Bottom-up volume builds reconcile with top-down category sizing.
Consistency checks validate segment-level outputs against external benchmarks from trade associations and regulatory disclosure databases. The modeling framework spans product type, flavor profile, distribution channel, and end-user segmentation dimensions across the projection horizon. CAGRs derive from fitted growth curves calibrated to electrolyte-enhanced adoption rates, clean-label certification penetration, and convenience retail expansion trajectories. Stevia price index movements and sugar-tax proposal timelines feed directly into demand elasticity parameters.
The analysis sits within stated boundaries; outcomes outside sustained FSSAI enforcement intensity, SAMR registration timeline stability, or Southeast Asian sugar-tax implementation would require recalibration. Forecasts embed assumptions regarding commuter pattern persistence in Chinese tier-one cities and health-conscious household expansion in Australian metros. Recalibration cycles align with material shifts in regulatory enforcement schedules and sweetener approval list revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Potting Mix Additives Market
Additives
Zinc Dialkyldithiophosphates Additive Market
Additives
Ascorbyl Stearate Market
Additives
Propyl Gallate Market
Additives
Nucleotide Premix Market
Additives
Global UV Absorbers Market
Additives
Dispersing Agents Market
Additives
Grease Additives Market
Additives
Middle East Feed Additives Market
Additives
Plastic Additives Market
Additives
Adjustive Agents Market
Additives
Middle East Lubricant Additives Market
Additives
Global Lubricating Oil Additives Market
Additives
Sodium Caprylate Market
Additives
China Sodium Reduction Ingredient Market
Additives
Polysaccharides and Oligosaccharides Market