
 1, 3, 5-Triazine Market | 2026-2036
1, 3, 5-Triazine Market Size, Share, and Industry Trends Forecast 2026-2036
1, 3, 5-Triazine Market Analysis
Melamine-formaldehyde chemistry is broadening substitution pathways for conventional phenolic resins in high-temperature laminates. BASF SE leverages its Ludwigshafen integrated site to sustain captive cyanuric chloride supply for downstream triazine derivatives. Dow Inc. competes through its agrochemical intermediates portfolio, while Eastman Chemical Company specializes in pharmaceutical-grade triazine compounds for active ingredient synthesis.
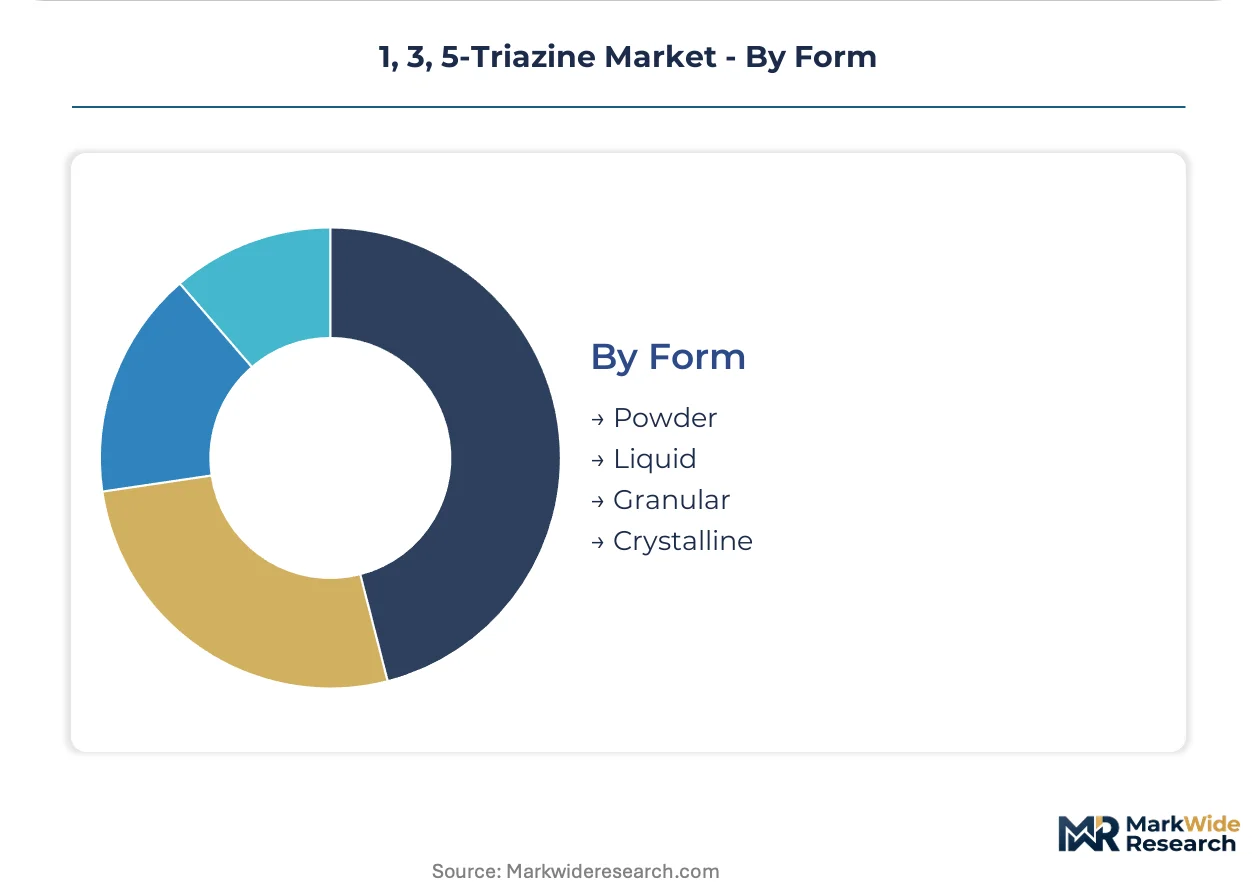
1, 3, 5-Triazine denotes a six-membered aromatic heterocycle with three nitrogen atoms alternating at the 1, 3, and 5 positions, characterized by a planar ring structure and thermal stability exceeding 300 degrees Celsius in many substituted derivatives; manufacturers produce it via trimerization of nitriles or cyanuric chloride pathways for use as a chemical scaffold in agrochemicals, pharmaceuticals, and specialty polymers. Herbicides dominate product type output owing to atrazine-class chemistry demand, while pharmaceutical compounds capture expanding margin pools as CDMOs adopt triazine linkers in kinase inhibitor programs. Powder formulations lead volume shipments for agricultural blending, though liquid concentrates gain traction in precision application systems.
EPA registration requirements under FIFRA govern triazine herbicide distribution in the United States, while REACH Annex XVII restrictions in Europe limit certain chlorinated triazine residuals in imported chemical intermediates. China's MEE enforces wastewater discharge standards that elevate treatment costs for cyanuric chloride producers. Stakeholders must monitor regulatory divergence between jurisdictions to align product specifications with diverging purity and environmental thresholds.
Market Dynamics
REACH Annex XVII restrictions on chlorinated triazine residuals are compressing import volumes into Europe while simultaneously elevating purity premiums for compliant producers, creating asymmetric competitive pressure across supply bases.
Growth Catalysts
- Specialty agrochemical formulators:These buyers seek nitrogen-heterocyclic backbones with thermal stability exceeding 300 degrees Celsius for next-generation herbicide synthesis, pulling volume through atrazine-class chemistry pipelines.
- China's MEE wastewater standards:Stricter discharge requirements for cyanuric chloride production are consolidating domestic supply toward integrated producers capable of captive treatment infrastructure.
- CDMO kinase inhibitor programs:Pharmaceutical contract manufacturers are adopting triazine linkers as scaffold elements in targeted oncology therapeutics, opening margin-rich demand channels distinct from commodity agrochemical offtake.
Market Restraints
- Cyanuric chloride feedstock concentration:Production of this critical intermediate clusters in China's Shandong and Jiangsu provinces, exposing downstream triazine derivatives to single-geography supply disruption risk.
- EPA FIFRA registration timelines:New triazine herbicide active ingredients face multi-year review cycles exceeding sixty months, compressing ROI windows for agrochemical R&D pipelines.
- Melamine-formaldehyde substitution:This alternative chemistry is capturing share in high-temperature laminate applications where phenolic resin replacement previously favored triazine-based systems.
Strategic Opportunities
- India's agrochemical manufacturing zones:The country's PLI scheme for chemical intermediates is attracting greenfield triazine capacity to serve domestic crop protection formulators and export markets.
- Pharmaceutical-grade certification tiers:FDA and EMA-compliant GMP production lines command price multiples over technical-grade output, rewarding purity-focused capital deployment.
- Precision agriculture liquid concentrates:Drone and variable-rate application systems favor formulated solutions over powder blends, reshaping distribution economics toward specialized packaging infrastructure.
Industry Challenges
- Process analytical technology integration:Real-time purity monitoring for REACH-compliant impurity thresholds requires capital-intensive PAT installations that smaller batch producers struggle to finance.
- Cross-jurisdictional specification divergence:Producers must maintain parallel inventory streams for EPA-registered, REACH-compliant, and China GB-standard grades, elevating working capital intensity.
- Cyanuric chloride byproduct handling:Hydrochloric acid recovery and neutralization systems demand specialized corrosion-resistant equipment, extending commissioning timelines for capacity expansion projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 1, 3, 5-Triazine Market |
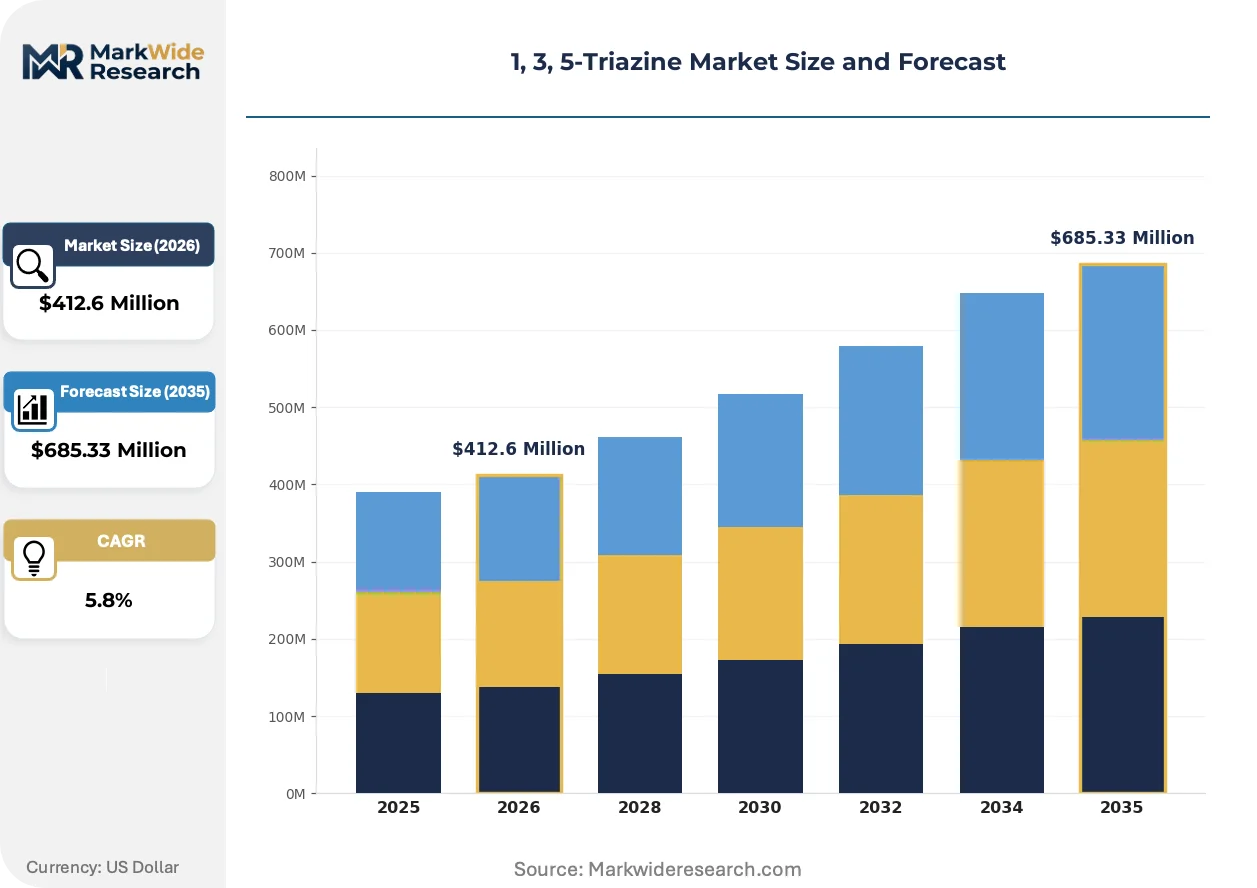
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Herbicides, Pesticides, Intermediates, Pharmaceutical Compounds Application: Agriculture, Pharmaceuticals, Chemical Synthesis, Pest Control End Use Industry: Agricultural, Pharmaceutical, Petrochemical, Specialty Chemicals Form: Powder, Liquid, Granular, Crystalline |
| Companies Covered | Evonik Industries AG, Ecolab Inc., BASF SE, SLB, Stepan Company, Hexion Inc., Dow Inc., Baker Hughes Company, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
1, 3, 5-Triazine Market Emerging Trajectories
Continuous flow reactor technology is displacing batch synthesis for cyanuric chloride trimerization, enabling tighter thermal control and reduced impurity profiles that align with tightening pharmaceutical-grade specifications.
Photoredox catalysis for direct C-H functionalization of the triazine ring is expanding into pharmaceutical intermediate production, allowing late-stage diversification of scaffolds without protecting group manipulations. CDMOs in Basel and Boston are piloting these protocols for kinase inhibitor programs, compressing synthetic step counts from twelve to seven stages. This chemistry is expanding into commercial-scale campaigns as equipment suppliers deliver photoreactors with kilogram-per-hour throughput capacity.
ECHA's 2023 update to REACH candidate list criteria for persistent, bioaccumulative, and toxic substances is forcing reformulation of legacy chlorotriazine herbicides, with downstream formulators accelerating substitution programs for atrazine-class chemistries. German and French regulators are coordinating enforcement priorities, creating synchronized compliance deadlines that favor pan-European suppliers with centralized analytical laboratories. The agrochemical segment is responding by diversifying active ingredient portfolios toward non-halogenated triazine derivatives.
Agrochemical distributors are unbundling technical advisory services from product supply contracts, converting previously bundled agronomy support to fee-based subscription models. Large-scale farming cooperatives in Brazil's Mato Grosso and Australia's wheat belt are consolidating procurement through direct manufacturer relationships, bypassing traditional distribution markups. This pattern concentrates most visibly in regions with consolidated land ownership and in-house agronomy expertise.
1, 3, 5-Triazine Market Segmentation
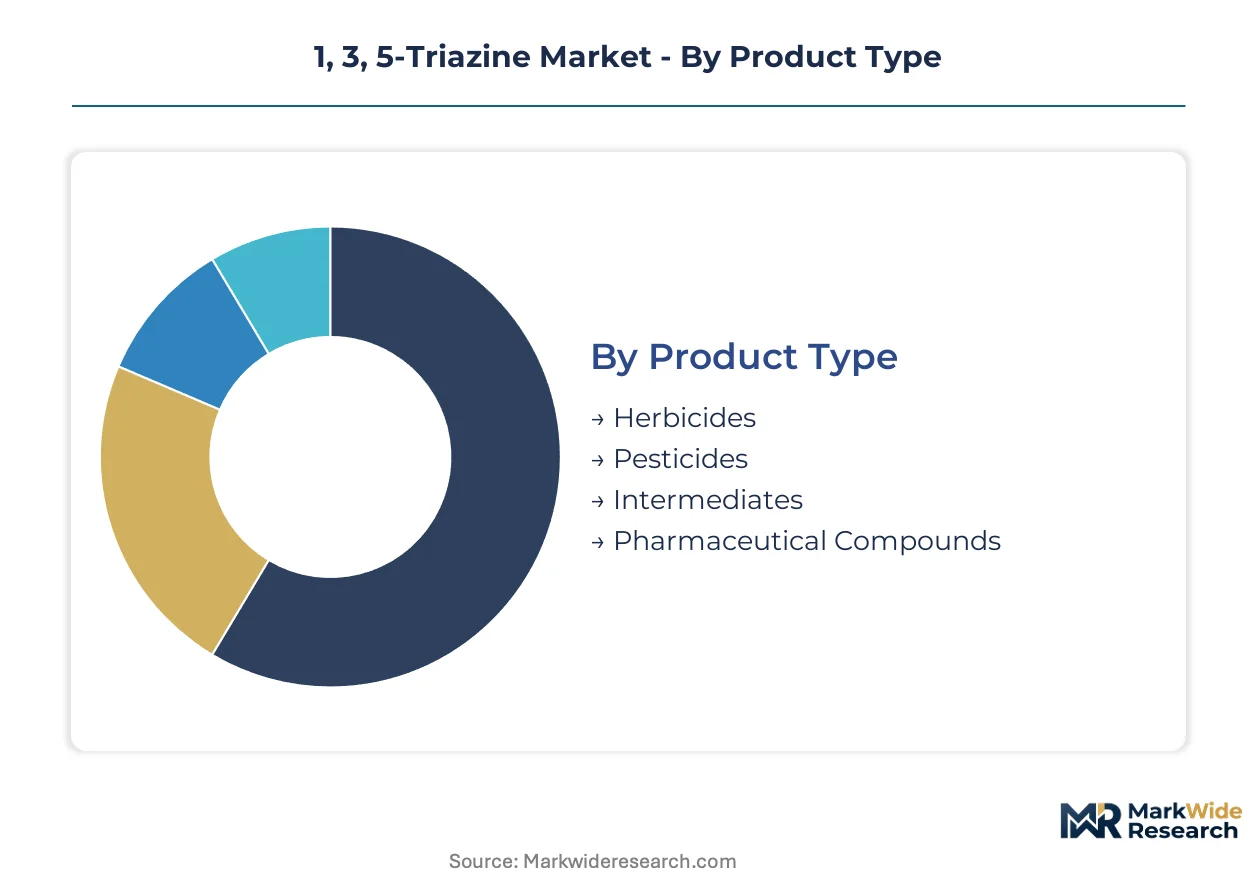
Triazine derivatives serve divergent purity and performance specifications across agrochemical and pharmaceutical value chains. Segmentation reveals how feedstock integration, regulatory thresholds, and formulation requirements reshape competitive positioning within each category.
Product Type:
Cyanuric chloride trimerization capacity concentrates in Shandong and Jiangsu provinces, creating supply asymmetry that favors integrated producers of downstream derivatives.
- Herbicides:Atrazine-class chemistry dominates commercial output, with s-triazine rings providing the nitrogen-heterocyclic backbone for photosystem II inhibitors. Specialty formulators in Brazil's Mato Grosso and Australia's wheat belt pull volume through direct procurement relationships, bypassing traditional distribution markups.
- Pharmaceutical Compounds:Kinase inhibitor programs employ triazine linkers as scaffold elements, demanding GMP-compliant production lines that command price multiples over technical-grade output. CDMOs in Basel and Boston are scaling photoredox catalysis protocols for late-stage C-H functionalization.
- Pesticides:Non-herbicidal crop protection applications include fungicidal and insecticidal triazine derivatives, with ECHA REACH candidate list criteria forcing reformulation away from persistent chlorotriazine structures.
- Intermediates:Cyanuric chloride and melamine derivatives serve as chemical building blocks for specialty polymers and flame retardants, with purity grades stratifying across industrial, technical, and pharmaceutical specifications.
Herbicides absorb the bulk of installed capacity; pharmaceutical compounds are expanding most quickly.
Application:
Cost tier differentiation separates commodity agrochemical offtake from margin-rich pharmaceutical synthesis, with regulatory compliance burden rising fastest in the higher-value tier.
- Agriculture:Precision application systems favor liquid concentrate formulations over powder blends, reshaping distribution economics toward specialized packaging infrastructure. Drone and variable-rate equipment in consolidated farming regions drive specification changes.
- Pharmaceuticals:Targeted oncology therapeutics leverage triazine scaffolds for kinase inhibition, with synthetic step counts compressing from twelve to seven stages via photoredox catalysis adoption.
- Chemical Synthesis:Melamine-formaldehyde chemistry substitutes for phenolic resins in high-temperature laminates, capturing share in applications previously favoring triazine-based systems.
- Pest Control:Professional and consumer applications span structural fumigation, vector control, and stored-product protection, with EPA FIFRA registration timelines exceeding sixty months for new active ingredients.
Agriculture commands the dominant volume position; pharmaceuticals is climbing the fastest on value terms.
End Use Industry:
Customer type fragmentation splits procurement between large-scale farming cooperatives with in-house agronomy expertise and pharmaceutical CDMOs with centralized analytical requirements.
- Agricultural:Crop protection formulators consolidate procurement through direct manufacturer relationships, with unbundling of technical advisory services converting previously bundled agronomy support to fee-based subscription models.
- Pharmaceutical:Active ingredient synthesis and intermediate production demand FDA and EMA-compliant GMP certification, with real-time purity monitoring for REACH-compliant impurity thresholds requiring capital-intensive PAT installations.
- Petrochemical:Specialty polymer applications exploit thermal stability exceeding 300 degrees Celsius in substituted derivatives, with captive cyanuric chloride supply sustaining downstream integration at major integrated sites.
- Specialty Chemicals:Flame retardants, coatings, and adhesives applications serve diverse industrial end-users, with cross-jurisdictional specification divergence forcing parallel inventory streams for EPA-registered, REACH-compliant, and China GB-standard grades.
Agricultural offtake absorbs the bulk of installed capacity; pharmaceutical is gaining share fastest.
Form:
Volume concentration in powder formulations is eroding as precision agriculture infrastructure favors liquid delivery systems.
- Powder:Agricultural blending operations favor dry formulations for compatibility with existing handling equipment, though dust exposure and uniformity challenges elevate regulatory scrutiny under OSHA and equivalent occupational standards.
- Liquid:Concentrates and suspension concentrates enable drone application and variable-rate dispensing, with packaging infrastructure investments concentrated in Brazil, Australia, and the US Midwest.
- Granular:Controlled-release formulations for soil application provide extended efficacy windows, with manufacturing clustering near major agronomic consumption regions to minimize freight costs for low-density products.
- Crystalline:Pharmaceutical-grade specifications demand precise polymorph control and particle size distribution, with crystallization process development representing a core competency for CDMO competitive differentiation.
Powder formulations retain the dominant volume position; liquid concentrates are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China absorbs the dominant share of triazine derivative consumption, with pharmaceutical intermediate output and agrochemical formulation driving regional demand concentration. The market's geographic footprint reflects feedstock integration patterns and regulatory divergence across major chemical manufacturing jurisdictions.
China
Shandong and Jiangsu provinces host concentrated cyanuric chloride capacity serving downstream herbicide and pharmaceutical synthesis. MEE wastewater discharge standards enforce treatment infrastructure investments that consolidate supply toward integrated producers. The Yangtze River Delta corridor anchors export-oriented triazine derivative manufacturing for agrochemical and CDMO offtake.
United States
Midwest farming cooperatives and precision agriculture operators pull volume through direct procurement relationships bypassing traditional distribution. EPA FIFRA registration timelines exceeding sixty months compress ROI windows for new active ingredient development. The Gulf Coast petrochemical corridor sustains captive cyanuric chloride supply for specialty polymer and flame retardant applications.
Germany
BASF SE's Ludwigshafen integrated site sustains backward integration into cyanuric chloride for captive triazine derivative production. ECHA REACH Annex XVII restrictions on chlorinated residuals elevate purity premiums for compliant producers serving pharmaceutical and agrochemical formulators. The country's centralized analytical laboratory infrastructure supports pan-European compliance coordination.
India
The PLI scheme for chemical intermediates attracts greenfield triazine capacity to serve domestic crop protection formulators and export markets. CDSCO pharmaceutical regulations and state-level pollution control mandates shape investment location decisions. Gujarat and Maharashtra industrial zones concentrate agrochemical manufacturing infrastructure with proximity to major agronomic consumption regions.
Brazil
Mato Grosso farming cooperatives consolidate procurement through direct manufacturer relationships, converting previously bundled agronomy support to fee-based models. ANVISA agrochemical registration requirements govern import and formulation activities. The country's expanding precision agriculture infrastructure favors liquid concentrate formulations over traditional powder blends.
1, 3, 5-Triazine Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated chemical majors commanding agrochemical volume while pharmaceutical-grade specialists capture margin-rich CDMO channels. The vendor base stratifies across three tiers: multinational integrated producers with captive feedstock, regional formulators with distribution depth, and purity-focused specialists serving FDA and EMA-certified synthesis. Two dominant competitive moves define current positioning: backward integration into cyanuric chloride production to secure feedstock, and GMP certification investments to access pharmaceutical-grade price multiples.
Among German integrated chemical producers, BASF SE exemplifies the captive supply archetype through its Ludwigshafen manufacturing complex. Dow Inc. and Eastman Chemical Company occupy positions spanning technical-grade agrochemical intermediates and pharmaceutical-certified synthesis, with the latter representing the purity-focused specialist tier. These three companies anchor the competitive structure without exhausting its diversity, as numerous regional formulators and emerging Indian producers compete on cost and local regulatory alignment.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Ecolab Inc. |
| BASF SE |
| SLB |
| Stepan Company |
| Hexion Inc. |
| Dow Inc. |
| Baker Hughes Company |
| Eastman Chemical Company |
| Others |
Supply Flow & Price Mechanics
Specialty agrochemical formulators in Brazil's Mato Grosso and Australia's wheat belt consolidate procurement through direct manufacturer relationships, compressing distribution markups and shifting pricing power toward integrated producers with captive cyanuric chloride supply.
Pricing Analysis
Volume-heavy herbicide applications trade on commodity spot terms while pharmaceutical-grade triazine compounds command contract-based long-term offtake with price multiples tied to FDA and EMA certification tiers. Price differentiation rests on purity grade and REACH compliance status, with technical-grade output facing cost compression from melamine-formaldehyde substitution in laminate applications. CDMO buyers exhibit the lowest price sensitivity due to kinase inhibitor program margins, while agricultural cooperatives drive aggressive tender negotiations.
Supply Chain Analysis
Freight costs for low-density granular formulations favor manufacturing clustering near major agronomic consumption regions, with production gravity centering on China's Shandong and Jiangsu provinces, Germany's Ludwigshafen complex, and India's Gujarat industrial zones. Cyanuric chloride, melamine derivatives, and hydrochloric acid recovery systems constitute critical input dependencies. Single-source vulnerability concentrates in Chinese feedstock supply. Distribution runs through direct manufacturer relationships for large-scale farming cooperatives and specialized CDMO channels for pharmaceutical synthesis.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH Annex XVII restrictions on chlorinated triazine residuals function as a cost-of-compliance moat, elevating capital requirements for real-time purity monitoring and consolidating competitive advantage toward integrated producers with centralized analytical laboratories.
For Market Incumbents: Anticipate regulatory divergence between EPA FIFRA and ECHA REACH timelines by maintaining parallel inventory streams and captive cyanuric chloride supply. Prioritize GMP certification investments to defend margin position against pharmaceutical-grade specialists, while monitoring melamine-formaldehyde substitution threats in high-temperature laminate applications. For New Entrants and Emerging Players: E-commerce platforms serving precision agriculture operators represent the most penetrable channel for liquid concentrate formulations, bypassing traditional distribution markups in Brazil and Australia. Target India's PLI scheme for chemical intermediates to access cost-competitive greenfield capacity, leveraging state-level pollution control alignment in Gujarat and Maharashtra. For Investors and Strategic Acquirers: The window for entry favors purity-focused specialists with FDA and EMA-compliant GMP production lines, as pharmaceutical-grade certification tiers widen margin spreads over technical-grade output. Monitor CDMO adoption of photoredox catalysis protocols as an inflection signal for synthetic step-count compression and capacity utilization shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cyanuric Chloride | Captive feedstock supply insulates BASF SE and Dow Inc. from Shandong-Jiangsu concentration risk. |
| GMP Certification Investment | FDA and EMA-compliant production lines unlock pharmaceutical-grade price multiples for Eastman Chemical Company. |
| Continuous Flow Reactor Deployment | Tighter thermal control aligns impurity profiles with tightening REACH pharmaceutical specifications. |
| Precision Agriculture Liquid Concentrate Expansion | Drone and variable-rate application systems in Brazil's Mato Grosso reshape distribution economics. |
| Photoredox Catalysis Scale-Up | CDMOs in Basel and Boston compress synthetic step counts from twelve to seven stages for kinase inhibitors. |
Methodological Framework
Multi-period observation of cyanuric chloride capacity utilization, REACH compliance certification rates, and CDMO kinase inhibitor program pipelines anchored the trend analysis, supplemented by interviews with plant managers at Shandong and Jiangsu production facilities, procurement leads at Brazilian farming cooperatives, technical R&D directors at agrochemical formulators, and regulatory affairs specialists at EMA-notified bodies. Secondary validation drew from ECHA candidate list updates, EPA FIFRA registration databases, customs trade data, and SEC 10-K filings from integrated chemical producers. Bottom-up triangulation across product-grade volume estimates converged with top-down macroeconomic scenario modeling.
Input-output matrices mapped feedstock cyanuric chloride availability to downstream derivative output across herbicide, pharmaceutical, and specialty polymer segments, with segmentation dimensions spanning grade tier, end-use industry, and regional production hub. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements throughout the forecast period. Industry-specific forecast inputs incorporated MEE wastewater discharge standard enforcement timelines and CDMO adoption curves for photoredox catalysis protocols.
The model holds under stable REACH Annex XVII interpretation and consistent EPA FIFRA review timelines; deviation in ECHA persistent-bioaccumulative-toxic substance criteria or sudden cyanuric chloride supply disruption would shift volume and value trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Montelukast Intermediate Market
Chemical Intermediates
Lauoryl Chloride Market
Chemical Intermediates
Metaphenoxy Benzaldehyde (MPBD) Market
Chemical Intermediates
Global Biochemical Reagents Market
Chemical Intermediates
Global Etoricoxib Intermediate Market
Chemical Intermediates
Glycidyl Methacrylate Market
Chemical Intermediates
Dimethyl Dicarbonate Market
Chemical Intermediates
Global Chromatography Reagents Market
Chemical Intermediates
3-Chloropropionyl Chloride Market
Chemical Intermediates
Tertiary Amines Market
Chemical Intermediates
Chemical Synthesizer Market
Chemical Intermediates
Ethylene Urea Market
Chemical Intermediates
API Intermediate Market
Chemical Intermediates
Ph Controlling Agents Market
Chemical Intermediates
Global Aniline Derivative Market
Chemical Intermediates
Hydroxyisobutyric Acid Market