
 Lauoryl Chloride Market | 2026-2036
Lauoryl Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Lauoryl Chloride Market Analytics
Contract formulation services is pivoting how lauoryl chloride reaches end-users, with chemical distributors bundling technical support and application testing into supply agreements. BASF leverages its integrated fatty acid derivative chain to sustain cost advantages across European and Asian delivery points. CABB anchors its position through chlorination technology leadership and captive thionyl chloride supply. Lianfeng Chemicals competes on volume scale, dominating domestic Chinese supply for surfactant intermediates.
Lauoryl chloride, the acid chloride derivative of lauric acid (C12:0), functions as a reactive intermediate in acylation chemistry, typically manufactured via thionyl chloride or phosgene-mediated chlorination of lauroyl precursors with purity grades exceeding 98 percent for pharmaceutical applications. Its primary industrial purpose centers on synthesizing surfactants, cosmetic emollients, and oilfield corrosion inhibitors where controlled hydrophobic chain length determines performance. The surfactants application leads volume consumption, though personal care products command premium pricing due to certification requirements for dermal safety. Liquid form dominates bulk logistics, while concentrate and emulsion variants capture margin pools in cosmetic manufacturer channels requiring ready-to-process inputs.
EPA oversight of chlorinated intermediate manufacturing shapes facility permitting and effluent standards in the United States, while REACH registration requirements in Europe mandate comprehensive toxicity dossiers for lauoryl chloride importers and formulators. China's SAMR enforces GB standards for chemical purity in domestic surfactant supply chains, creating divergent compliance burdens across export destinations. Stakeholders must monitor regulatory divergence between jurisdictions to determine where captive production versus merchant supply optimizes market access.
Market Dynamics
Contract formulation services are restructuring how lauoryl chloride reaches end-users, with chemical distributors bundling technical support and application testing into supply agreements. This intermediation layer is compressing traditional merchant margins while expanding addressable demand among mid-sized cosmetic formulators lacking in-house acylation expertise.
Growth Catalysts
- REACH compliance thresholds:Tightening purity requirements in Europe are filtering substandard suppliers and consolidating procurement among certified producers capable of 98 percent-plus pharmaceutical grades.
- Southeast Asian surfactant expansion:Specialty surfactant manufacturers in Thailand and Vietnam are scaling mild cleansing formulation capacity, driving merchant demand for C12 acyl chloride intermediates.
- India import substitution:Domestic chemical manufacturers are displacing imported lauoryl chloride with local chlorination capacity, redirecting volume through indigenous supply chains.
Market Restraints
- Thionyl chloride supply concentration:Captive production of this chlorinating agent among major producers limits merchant market flexibility and raises barriers for new entrants.
- EPA effluent standards:Chlorinated intermediate manufacturing in the United States faces tightening facility permitting and wastewater discharge requirements, extending compliance timelines.
- Alcohol ethoxylate substitution:Non-ionic surfactants derived from natural alcohols are capturing share in mild cleansing applications where acyl chlorides previously dominated.
Strategic Opportunities
- Brazilian cosmetic manufacturing:ANVISA certification requirements for dermal safety are creating premium pricing tiers for pharmaceutical-grade lauoryl chloride in South American personal care supply chains.
- Continuous flow chlorination:Microreactor technology is converging with traditional batch processing to reduce solvent waste and enable modular capacity expansion.
- EU Green Deal chemistry incentives:Biomass-derived lauric acid feedstocks are qualifying for sustainable chemistry procurement preferences in European surfactant applications.
Industry Challenges
- Acylation chemist scarcity:Formulation expertise in acid chloride handling and controlled hydrolysis is concentrating among aging technical workforces in Western Europe and Japan.
- Multi-jurisdiction dossier compilation:REACH registration, EPA TSCA compliance, and China's SAMR GB standard alignment require simultaneous toxicology investment, straining mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lauoryl Chloride Market |
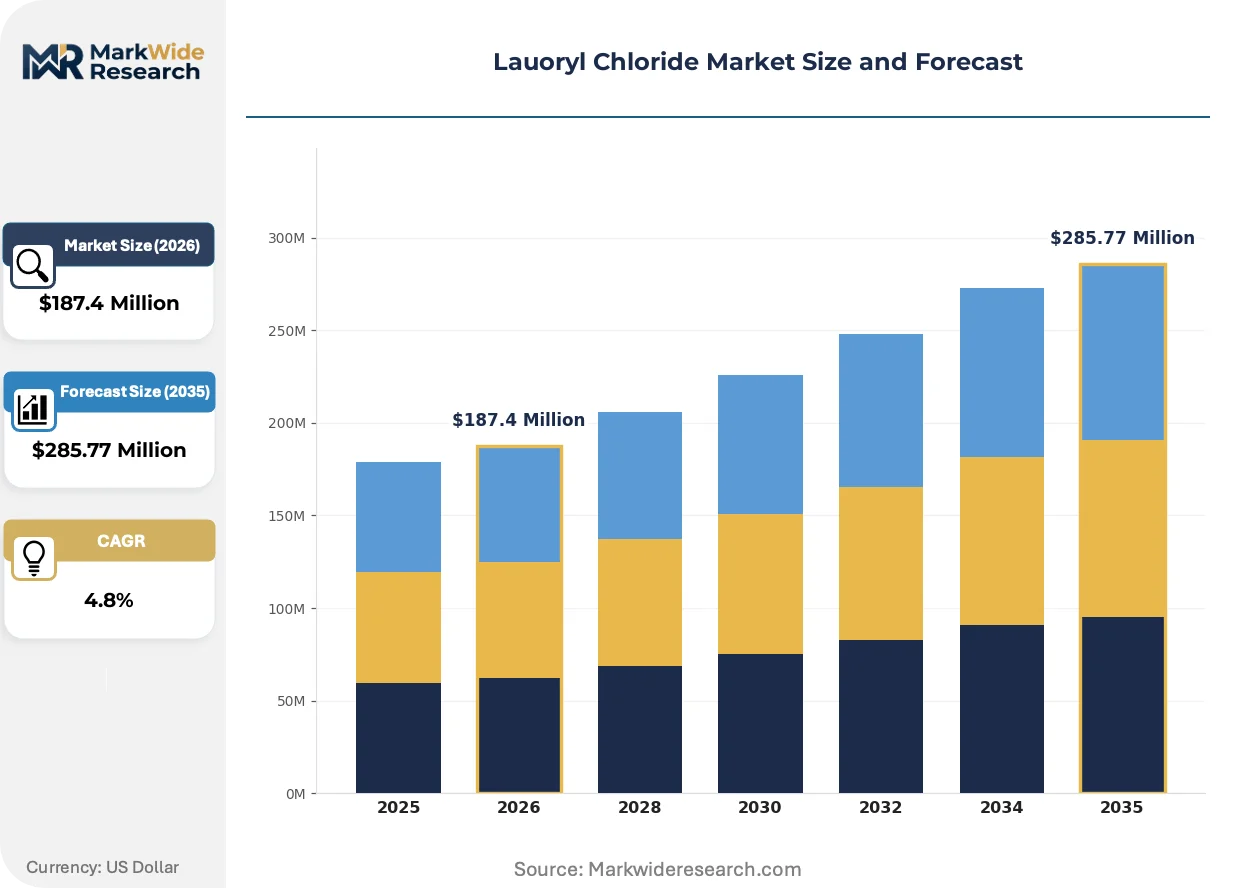
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Personal Care Products, Surfactants, Industrial Cleaners, Oil Field Chemicals Product Type: Liquid Form, Powder Form, Concentrate, Emulsion End User: Cosmetic Manufacturers, Chemical Manufacturers, Food Industry, Pharmaceutical Companies Delivery Mode: Bulk Supply, Retail Packs, Customized Solutions, Online Sales |
| Companies Covered | BASF, CABB, Lianfeng Chemicals, Lanzhou Auxiliary Agent, Triveni Chemicals, Huzhou Salon Chemical, Pingyuan Xinda Chemical, Tokyo Chemical Industry, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lauoryl Chloride Market Evolving Landscape
Reactive intermediate supply chains are fragmenting between commodity surfactant feedstocks and certified cosmetic-grade specialties. Technology, regulation, and procurement models are diverging across these tiers.
Continuous flow microreactor chlorination is converging with traditional thionyl chloride batch processing to reduce solvent inventory and enable point-source effluent treatment. Specialty chemical producers in Germany and Switzerland are piloting these systems for pharmaceutical-grade output. The technology is compressing batch cycle times from hours to minutes while tightening purity consistency.
REACH registration dossiers now mandate extended toxicity testing for respiratory sensitization, extending compliance timelines for importers without existing substance portfolios. European formulators are consolidating supplier bases to reduce registration cost duplication. Personal care applications face the steepest compliance burden due to dermal exposure scenarios.
Regional distributors are unbundling technical service from commodity supply, selling formulation support as standalone subscriptions. Mid-sized cosmetic manufacturers in India and Southeast Asia are adopting this model to access acylation expertise without captive chemistry teams. The shift is most visible in Mumbai and Bangkok, where distributor laboratories now handle pre-formulation compatibility testing.
Lauoryl Chloride Market Segmentation
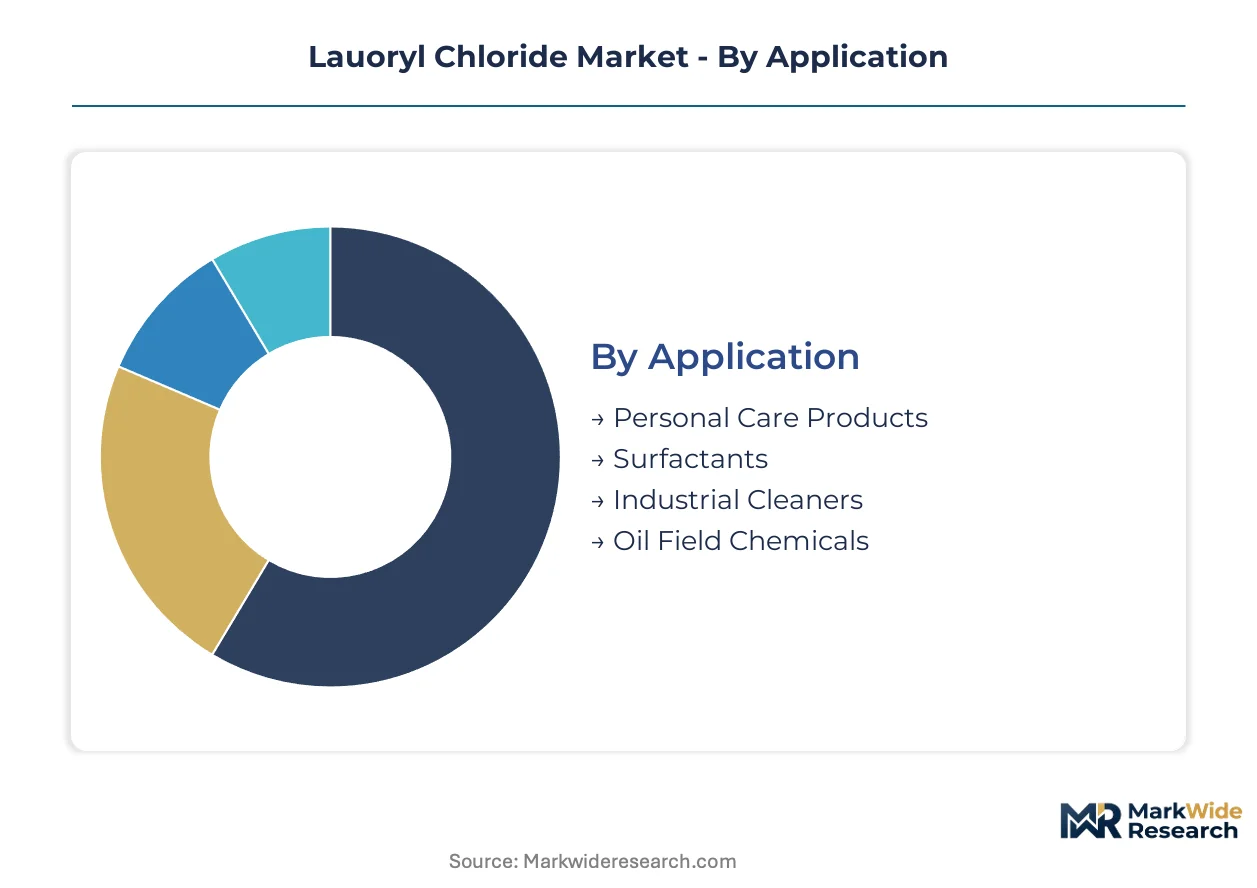
Segmentation in lauoryl chloride reveals how capital requirements, regulatory burdens, and technical specifications fragment supply chains across distinct commercial tiers. Each dimension—application, physical form, end-user category, and delivery mechanism—carries divergent margin structures and compliance thresholds that reshape competitive positioning.
Application:
Capital intensity peaks in pharmaceutical-grade production, where thionyl chlorination infrastructure and analytical certification laboratories demand the heaviest upfront investment.
- Personal Care Products:Pharmaceutical-grade lauoryl chloride with 98 percent-plus purity serves dermal-safe emollients and conditioning agents. ANVISA certification requirements in Brazil and REACH dossier compliance in Europe concentrate procurement among certified producers capable of respiratory sensitization testing.
- Surfactants:The largest volume application centers on acylation chemistry for anionic and amphoteric surfactants. Southeast Asian manufacturers in Thailand and Vietnam are scaling mild cleansing capacity, redirecting C12 acyl chloride demand toward merchant supply chains.
- Industrial Cleaners:Technical-grade material for heavy-duty degreasing and metal processing fluids. Price-sensitive procurement favors regional chlorination capacity with lower purity tolerances.
- Oil Field Chemicals:Corrosion inhibitors and emulsion breakers for upstream petroleum extraction. Demand clusters around Texas, Alberta, and the North Sea where operator specifications vary by reservoir chemistry.
Surfactants absorb the bulk of installed capacity; personal care products are expanding most quickly.
Product Type:
Physical form determines logistics economics and customer processing requirements, with liquid formats dominating bulk chemical distribution while concentrated and emulsion variants capture formulation-service margins.
- Liquid Form:Standard bulk delivery in tank containers and drum packaging for industrial surfactant manufacturers. ISO-tank logistics and temperature-controlled storage define working capital intensity for distributors.
- Powder Form:Spray-dried or crystalline material for dry-blend detergent compounds and powder cosmetic formulations. Handling protocols require dust containment infrastructure absent in liquid processing.
- Concentrate:High-activity solutions for cosmetic manufacturers seeking ready-to-process inputs. Mumbai and Bangkok distributor laboratories now bundle pre-formulation compatibility testing with concentrate supply.
- Emulsion:Pre-dispersed aqueous systems eliminating acylation chemistry handling for mid-sized formulators. Premium pricing reflects technical service bundling and reduced customer capital expenditure.
Liquid form commands the greatest installed base; emulsion variants are climbing the fastest as contract formulation services proliferate.
End User:
Customer sophistication and captive chemistry capability split the market between merchants supplying formulation-naive buyers and integrated producers serving technically advanced accounts.
- Cosmetic Manufacturers:ANVISA, FDA, and ECHA compliance requirements drive pharmaceutical-grade procurement with full toxicology dossiers. Dermal safety certification creates substantial supplier switching costs.
- Chemical Manufacturers:Integrated surfactant producers with in-house chlorination capacity or merchant acyl chloride buyers for derivative synthesis. India's domestic manufacturers are displacing imports through indigenous supply chains.
- Food Industry:Limited application in food-grade emulsifiers and processing aids. FSSAI and FDA food contact regulations impose purity thresholds distinct from industrial grades.
- Pharmaceutical Companies:Active pharmaceutical ingredient intermediates and excipient synthesis. Batch records, GMP compliance, and audit trails command the steepest documentation burdens.
Chemical manufacturers represent the deepest demand pool; cosmetic manufacturers are gaining share fastest on premium formulation growth.
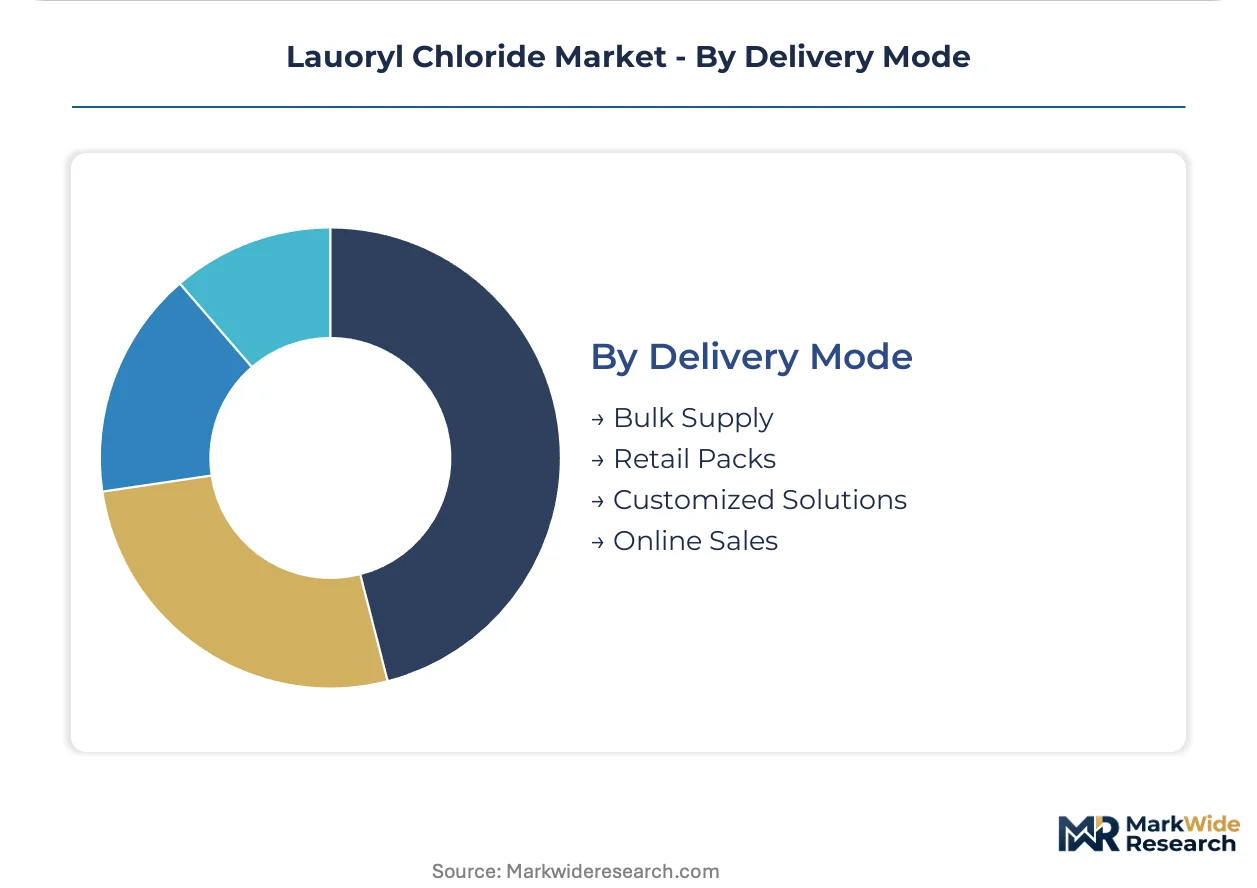
Delivery Mode:
Supply chain configuration separates commodity logistics from value-added distribution, with technical service bundling reshaping how mid-scale buyers access acylation expertise.
- Bulk Supply:Tank truck, railcar, and ISO-tank deliveries to integrated surfactant plants and large chemical manufacturers. Volume commitments and dedicated storage infrastructure lock in supplier relationships.
- Retail Packs:Drum and pail quantities for small-scale formulators and research laboratories. Higher per-unit pricing reflects handling and distribution overhead.
- Customized Solutions:Specification blending, dilution, and additive incorporation at distributor facilities. Bangkok and Mumbai laboratories exemplify this unbundling of technical service from commodity supply.
- Online Sales:E-procurement platforms for standardized grades and documented specifications. Limited penetration in pharmaceutical applications where audit trails and supplier qualification predominate.
Bulk supply anchors volume throughput; customized solutions are expanding most quickly as distributor laboratories proliferate across India and Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates lauoryl chloride production capacity while India and Southeast Asia absorb the fastest consumption growth. European demand centers on pharmaceutical-grade material under REACH compliance. North American procurement balances domestic chlorination against merchant imports.
China
Domestic surfactant manufacturers in Jiangsu and Zhejiang provinces drive merchant demand for C12 acyl chloride intermediates. SAMR enforces GB standards for chemical purity in domestic supply chains. Lianfeng Chemicals anchors volume production in the Yangtze River Delta, serving both local formulators and export markets.
India
Specialty surfactant makers in Maharashtra and Gujarat are scaling mild cleansing formulation capacity. CDSCO and FSSAI impose distinct purity thresholds for pharmaceutical versus food-contact applications. Domestic chlorination facilities in Dahej and Mundra are displacing imported lauoryl chloride with indigenous supply chains.
Germany
BASF leverages integrated fatty acid derivative chains across Ludwigshafen and Antwerp delivery points. ECHA mandates comprehensive toxicity dossiers for REACH registration, filtering substandard suppliers. Continuous flow microreactor pilots in Swiss-German border regions target pharmaceutical-grade output with compressed batch cycles.
United States
Oilfield chemical demand clusters around Texas corrosion inhibitor formulations for upstream petroleum extraction. EPA oversight shapes facility permitting and effluent standards for chlorinated intermediate manufacturing. Houston-area distributors bundle technical support with bulk supply to mid-sized surfactant formulators.
Brazil
Cosmetic manufacturers in São Paulo and Rio de Janeiro seek pharmaceutical-grade material for dermal-safe emollients. ANVISA certification requirements create premium pricing tiers for imported lauoryl chloride. Regional distributors are establishing formulation laboratories to pre-qualify suppliers for personal care applications.
Lauoryl Chloride Market Competitive Landscape
Capital-heavy producers compete with asset-light distributors across divergent margin tiers. The vendor base separates between integrated chlorination specialists and merchant acyl chloride traders. Three archetypes dominate: integrated chemical conglomerates with captive thionyl chloride supply, regional volume producers serving domestic surfactant chains, and specialty distributors bundling technical services. Competitive moves center on capacity expansion in India and Southeast Asia alongside distributor laboratory investments in Mumbai and Bangkok.
Among integrated chemical conglomerates, BASF and CABB exemplify divergent strategic positions. BASF SE occupies a position anchored in European fatty acid derivative integration, while CABB represents chlorination technology leadership with captive thionyl chloride supply. Lianfeng Chemicals sits within the volume-scale archetype, dominating domestic Chinese supply for surfactant intermediates. These three patterns—integration, technology leadership, and scale—structure competitive positioning across procurement channels.
| Leading Market Players |
|---|
| BASF |
| CABB |
| Lianfeng Chemicals |
| Lanzhou Auxiliary Agent |
| Triveni Chemicals |
| Huzhou Salon Chemical |
| Pingyuan Xinda Chemical |
| Tokyo Chemical Industry |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Lauric acid futures and spot market indices for C12 fatty acid feedstocks cascade through chlorination cost structures into tiered pricing for pharmaceutical-grade, cosmetic-grade, and technical-grade lauoryl chloride tiers across merchant and contract supply channels.
Pricing Analysis
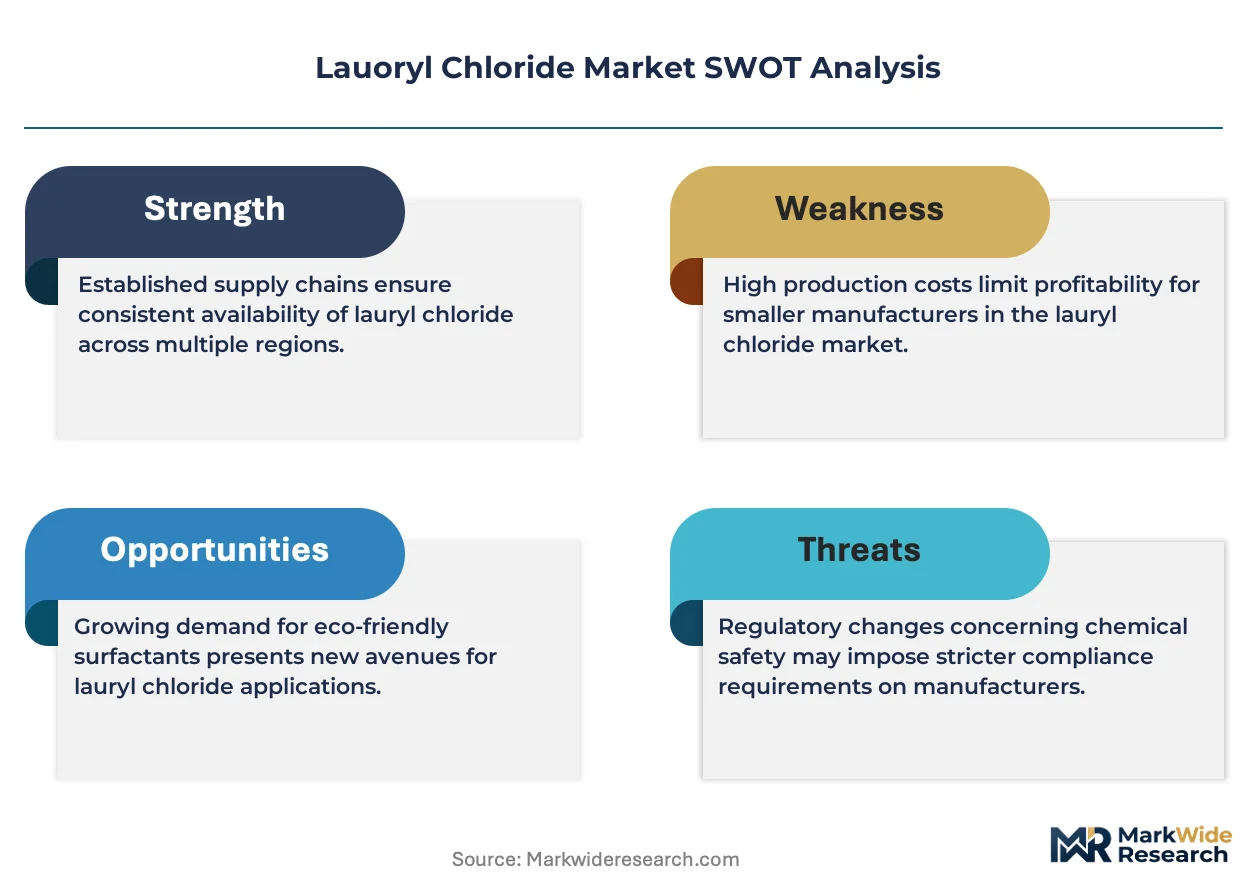
Margin tightening in technical-grade material reflects alcohol ethoxylate substitution pressure and regional chlorination overcapacity in China. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial grades separates dermal-safe certified output from commodity surfactant feedstock. Cost-down pressure on standard grades accelerates because Indian domestic producers are displacing imports with indigenous supply chains. Cosmetic manufacturers exhibit lowest price sensitivity due to ANVISA and REACH certification switching costs, while industrial cleaner buyers drive hardest bargain.
Supply Chain Analysis
REACH registration dossiers and pharmaceutical-grade GMP certifications gate supplier qualification, filtering merchant market participation toward integrated producers with captive thionyl chloride and analytical laboratories. Manufacturing concentrates in China, India, and Germany, with raw material supply drawing from palm kernel and coconut oil derivative channels across Southeast Asia. Single-source vulnerability rests on thionyl chloride production concentration among major chlorination specialists. Distribution runs through chemical distributors bundling technical formulation services with bulk supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around regulatory compliance capabilities, with REACH toxicity dossier requirements and EPA effluent standards forcing subscale chlorination operators toward exit or acquisition.
For Market Incumbents: Lock in formulation partnerships with mid-sized cosmetic manufacturers in Mumbai and Bangkok through distributor laboratory investments. Deepen backward integration into lauric acid feedstock sourcing to defend against palm oil price volatility. Prioritize continuous flow microreactor pilots for pharmaceutical-grade capacity expansion. For New Entrants and Emerging Players: Capture white-space demand in Brazilian cosmetic manufacturing where ANVISA certification creates premium pricing tiers for imported pharmaceutical-grade material. Target Southeast Asian mild cleansing formulation capacity expansion in Thailand and Vietnam. Enter through technical service subscriptions rather than commodity merchant supply. For Investors and Strategic Acquirers: The window for entry favors regional volume producers with SAMR-compliant Chinese manufacturing or CDSCO-registered Indian chlorination assets. Long-term viability hinges on regulatory dossier portfolios rather than standalone capacity. Watch for REACH registration deadline extensions as inflection signal for distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Chlorination Scale-Up | Microreactor deployment reduces solvent waste and compresses batch cycle times for pharmaceutical-grade output. |
| Backward Integration into Lauric Acid | Captive fatty acid supply hedges palm kernel oil price volatility across Southeast Asian feedstock markets. |
| Distributor Laboratory Expansion | Bangkok and Mumbai technical service hubs capture formulation-naive cosmetic manufacturer demand. |
| REACH Dossier Portfolio Investment | Respiratory sensitization testing compliance filters substandard suppliers and consolidates procurement. |
| India Domestic Chlorination Buildout | Dahej and Mundra capacity displaces imported intermediates with SAMR-aligned indigenous supply chains. |
Research Methodology
Document review covered customs trade databases, ECHA registration filings, and SEC chemical sector disclosures, complemented by interviews with chlorination plant managers, surfactant procurement leads at downstream OEMs, cosmetic formulator technical directors, and chemical distribution channel partners. Bottom-up capacity modeling triangulated against top-down consumption estimates from fatty acid derivative demand analysis.
Segment-level value and volume trajectories across the projection horizon reflect grade-tier, end-use application, and regional production hub dimensions. CAGRs derived from iterative convergence of historical trade flow analysis and forward capacity announcement tracking. Key inputs included thionyl chloride supply concentration indices and palm kernel oil price elasticity assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH registration timeline shifts and EPA effluent standard enforcement intensity. A model refresh is warranted upon material change in alcohol ethoxylate substitution rates or thionyl chloride supply disruption events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Fungal Staining Reagent Market
Chemical Intermediates
Reagent Bottle Market
Chemical Intermediates
Cytosine Market
Chemical Intermediates
Tetrahydrocurcumin Reagent Market
Chemical Intermediates
Acetamide MEA Market
Chemical Intermediates
Palmitoyl Chloride Market
Chemical Intermediates
US Acids Market
Chemical Intermediates
Acid Chlorides Market
Chemical Intermediates
Global Iron Chelates Market
Chemical Intermediates
Iodoacetonitrile Market
Chemical Intermediates
Japan Formic Acid Market
Chemical Intermediates
Global Biochemical Reagents Market
Chemical Intermediates
Enzyme Substrates Market
Chemical Intermediates
Grignard Reagents Market
Chemical Intermediates
United States Cellulose Acetate Market
Chemical Intermediates
Epoxy Silanes Market