
 Global Chromatography Reagents Market | 2026-2036
Global Chromatography Reagents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chromatography Reagents Market Foresight
REACH compliance is shifting the cost-of-entry calculus for chromatography reagent suppliers entering the European market. Thermo Fisher Scientific leverages its vertically integrated supply chain to absorb regulatory compliance costs across multiple jurisdictions. Merck KGaA anchors its position through pharmaceutical-grade solvent manufacturing at scale. Agilent Technologies differentiates via instrument-reagent bundling that locks in laboratory procurement workflows.
Chromatography reagents comprise high-purity solvents, buffers, derivatization agents, and stationary phase media formulated to achieve specific separation selectivity, with purity grades typically exceeding 99.9% for analytical applications and stringent lot-to-lot consistency for reproducible retention times. Silica gel and reverse phase media dominate consumable volumes in quality control laboratories, while affinity resin commands premium pricing in biopharmaceutical downstream processing due to protein A ligand scarcity and complex manufacturing. Ion exchange resin competes on throughput in monoclonal antibody purification trains, where resin lifetime directly impacts cost per batch.
FDA bioanalytical guidance, EMA good manufacturing practice Annex 1 revisions, and China's NMPA pharmacopoeia updates collectively tighten reagent qualification documentation and traceability requirements. These frameworks compel suppliers to invest in certificate of analysis digitization and raw material sourcing transparency. Stakeholders must monitor regulatory divergence between major jurisdictions to determine whether centralized or regional manufacturing strategies minimize compliance overhead.
Market Dynamics
Pharmaceutical-grade solvent supply is consolidating around multi-jurisdictional manufacturing footprints as REACH compliance costs and FDA bioanalytical method validation requirements simultaneously escalate. Suppliers now face binary strategic choices between centralized certificate-of-analysis digitization investments versus regional qualification redundancy.
Growth Catalysts
- FDA Bioanalytical Method Validation:Updated guidance mandates enhanced reagent qualification documentation, forcing pharmaceutical manufacturers to upgrade analytical testing capacity and expand high-purity solvent procurement volumes.
- Monoclonal Antibody Manufacturing:Ion exchange resin demand accelerates in downstream purification trains where resin lifetime optimization directly reduces per-batch production costs for biopharmaceutical contract manufacturers.
- China NMPA Pharmacopoeia Revisions:Stringent traceability requirements for chromatography reagents used in generic drug quality control are expanding domestic and import substitution opportunities for qualified suppliers.
Market Restraints
- Protein A Ligand Scarcity:Affinity resin production remains constrained by limited manufacturing capacity for critical ligand materials, creating supply bottlenecks for biopharmaceutical downstream processing applications.
- Acetonitrile Price Volatility:High-purity solvent costs fluctuate with petrochemical feedstock availability and acrylonitrile byproduct economics, compressing margins for analytical-grade reagent formulators.
- REACH Registration Burden:European Chemicals Agency compliance costs for novel chromatography media exceed EUR 100,000 per substance, elevating barriers for specialty stationary phase entrants.
Strategic Opportunities
- India CDMO Expansion:Contract development and manufacturing organization growth in Hyderabad and Mumbai clusters creates underpenetrated demand for pharmaceutical-grade buffers and derivatization agents with local qualification support.
- Continuous Chromatography Adoption:Multi-column countercurrent systems are displacing batch processing in monoclonal antibody purification, opening resin consumption volume multiples for suppliers with scalable manufacturing.
- EU Green Deal Solvent Recovery:Circular economy mandates for organic solvent recycling in pharmaceutical manufacturing create service-integrated reagent supply models with regulatory preference.
Industry Challenges
- Analytical Chemist Talent Scarcity:Method development expertise for complex biopharmaceutical impurity profiling remains concentrated among experienced practitioners, limiting laboratory expansion velocity for contract research organizations.
- Lot-to-Lot Consistency Certification:Retention time reproducibility validation across silica gel manufacturing campaigns requires extensive quality control documentation, extending new product introduction timelines by 12-18 months.
- Legacy LIMS Integration:Certificate of analysis digitization initiatives encounter friction with established laboratory information management systems lacking API compatibility for automated reagent qualification data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chromatography Reagents Market |
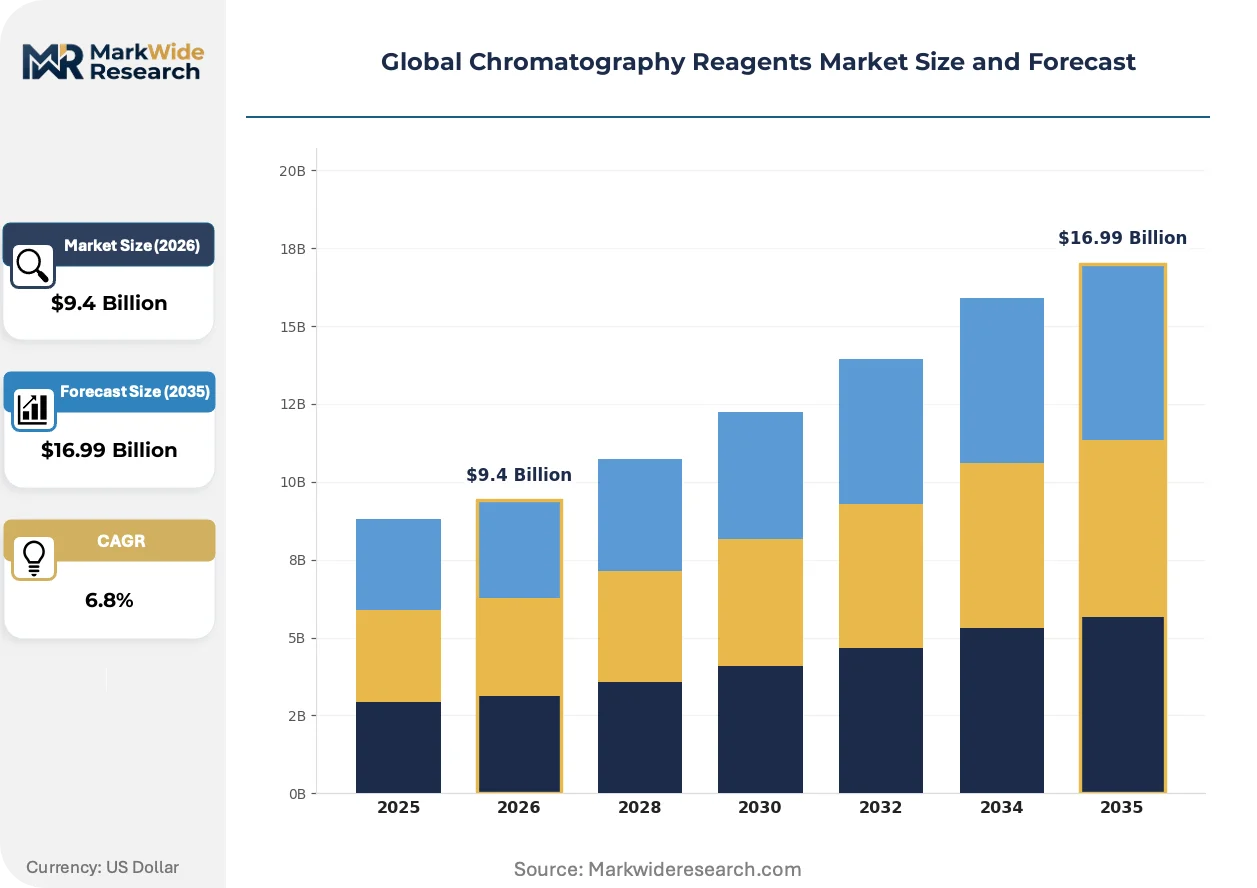
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silica Gel, Cellulose, Ion Exchange Resin, Reverse Phase, Affinity Resin, Others Application: Pharmaceutical Analysis, Food Testing, Environmental Monitoring, Forensic Science, Biochemical Separation, Petrochemical Screening End User Industry: Pharmacies, Food Safety Laboratories, Environmental Agencies, Crime Laboratories, Biotechnology Firms, Petrochemical Plants Deployment Type: Laboratory-Scale, Pilot-Scale, Production-Scale, Mobile Units, Custom Installations |
| Companies Covered | Thermo Fisher Scientific, Inc., Merck KGaA, Agilent Technologies, Inc., Waters Corporation, Avantor, Inc., Bio-Rad Laboratories, Inc., Shimadzu Corporation, Danaher Corporation, PerkinElmer, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chromatography Reagents Market Shifts & Advancements
Chromatography reagent development is converging on platform standardization and regulatory pre-certification as pharmaceutical outsourcing accelerates and quality documentation becomes a competitive differentiator rather than a compliance checkbox.
Pre-packed chromatography columns with validated stationary phase media are unifying method transfer protocols between contract manufacturing organizations and sponsor laboratories. Large-molecule drug developers in Boston, Basel, and Shanghai clusters are adopting these pre-qualified formats to compress method validation timelines. This standardization is unifying procurement specifications across multi-site manufacturing networks, reducing supplier qualification overhead for global pharmaceutical companies.
EMA Annex 1 revisions on sterile manufacturing are extending environmental monitoring requirements to chromatography reagent storage and handling conditions. Pharmaceutical manufacturers must now document particulate and bioburden controls for high-purity solvents previously exempt from sterile processing standards. Biopharmaceutical fill-finish operations in Germany, Ireland, and Singapore are responding by mandating gamma-irradiated or aseptically filtered reagent grades with enhanced certificate of analysis parameters.
Laboratory procurement consolidation through group purchasing organizations is compressing vendor panels and standardizing reagent specifications across multi-site research institutions. Academic medical centers and national research institutes in the United States and United Kingdom are shifting from site-specific supplier relationships to enterprise-wide contracts with centralized quality auditing. This concentration is most visible in National Institutes of Health-funded consortia where harmonized reagent qualification reduces redundant method validation across collaborating laboratories.
Global Chromatography Reagents Market Segmentation
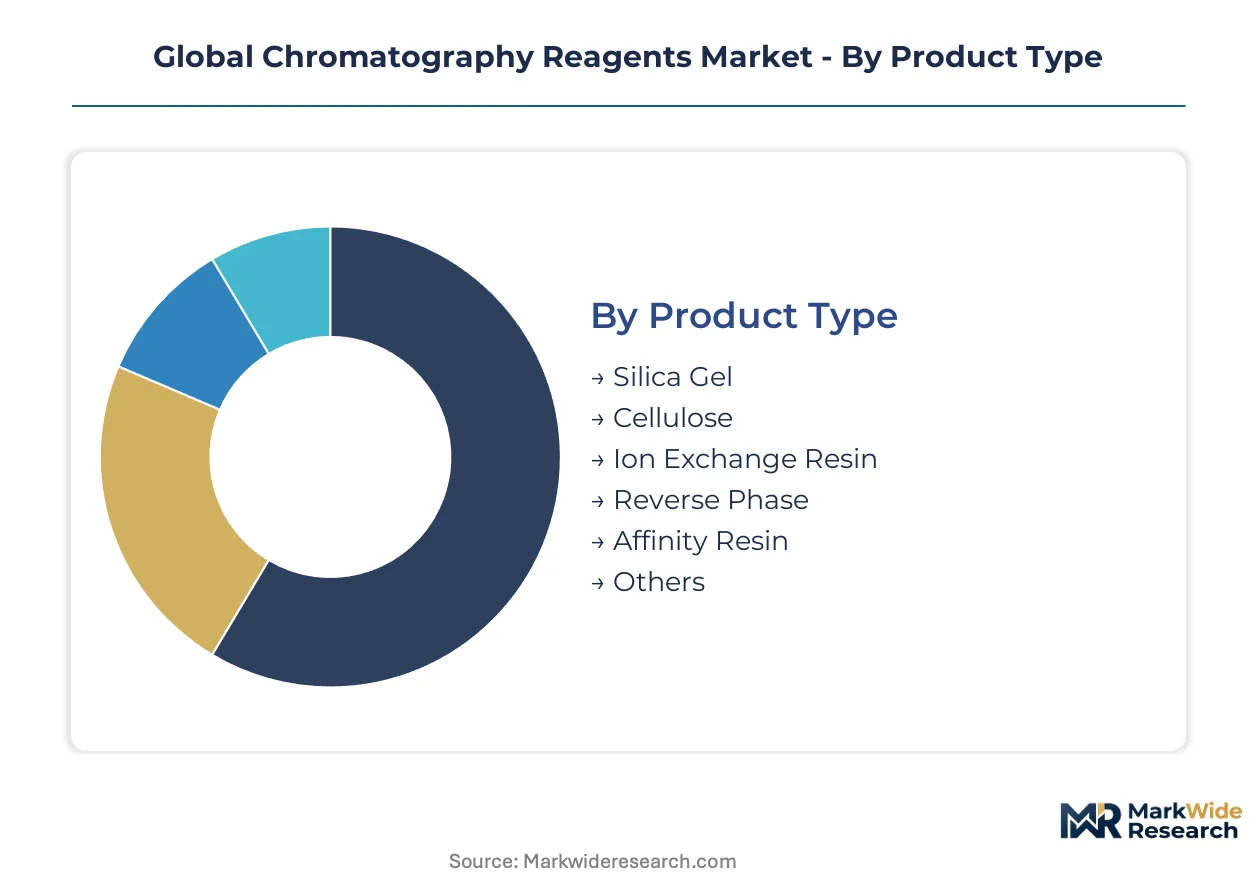
Chromatography reagent purchasing decisions cascade through technical specifications, regulatory compliance tiers, and manufacturing scale requirements. Each segmentation dimension reveals distinct margin structures and supplier qualification barriers that shape competitive positioning across pharmaceutical, environmental, and forensic end-uses.
Product Type:
Buyers prioritize separation selectivity and lot-to-lot consistency when specifying stationary phase media, with purity grades and ligand density driving per-unit pricing spreads.
- Silica Gel:Porous amorphous silicon dioxide with controlled particle size distributions (3-10 μm) and surface area specifications (300-500 m²/g). Quality control laboratories in Germany and the United States consume bulk volumes for routine pharmaceutical impurity profiling under FDA bioanalytical method validation protocols. Lot-to-lot retention time reproducibility mandates extensive certificate of analysis documentation.
- Affinity Resin:Protein A ligand-immobilized agarose or synthetic polymer matrices engineered for monoclonal antibody capture. Biopharmaceutical downstream processing in Ireland and Singapore commands premium pricing due to ligand scarcity and complex aseptic manufacturing requirements under EMA Annex 1 sterile processing standards.
- Ion Exchange Resin:Functionalized polystyrene-divinylbenzene or agarose beads with quaternary ammonium or sulfonate groups for charge-based separation.
- Reverse Phase:C18 or C8 bonded silica media for hydrophobic interaction chromatography in small-molecule drug analysis.
- Cellulose:Microcrystalline or fibrous formats for thin-layer chromatography and low-pressure separations.
- Others:Size exclusion, hydrophobic interaction, and mixed-mode specialty media for niche applications.
Silica gel leads on scale; affinity resin leads on momentum.
Application:
Regulatory stringency varies sharply across use cases, with pharmaceutical and forensic applications demanding the most extensive reagent qualification documentation.
- Pharmaceutical Analysis:High-performance liquid chromatography and gas chromatography methods for active pharmaceutical ingredient purity, impurity profiling, and dissolution testing. Contract manufacturing organizations in Basel and Boston clusters drive specification standardization as method transfers between sponsor and CMO laboratories require pre-qualified reagent formats.
- Environmental Monitoring:Persistent organic pollutant and pesticide residue detection in water and soil matrices. China's NMPA pharmacopoeia revisions and EPA methods collectively expand demand for trace-analysis-grade solvents with documented low-background contamination.
- Food Testing:Mycotoxin, veterinary drug residue, and contaminant screening for import compliance.
- Forensic Science:Toxicology and controlled substance identification requiring chain-of-custody documentation.
- Biochemical Separation:Protein, nucleic acid, and viral vector purification for research and manufacturing.
- Petrochemical Screening:Hydrocarbon fingerprinting and refinery process control applications.
Pharmaceutical analysis commands the largest revenue pool; environmental monitoring is climbing the fastest on regulatory expansion.
End User Industry:
Procurement sophistication separates centralized enterprise contracts from site-specific purchasing, with biotechnology and pharmaceutical sectors leading qualification rigor.
- Biotechnology Firms:Cell line development, process characterization, and cGMP manufacturing operations consuming affinity and ion exchange resins at production scale. Cambridge and South San Francisco clusters concentrate demand for single-use, gamma-irradiated formats with integrated certificate of analysis digitization.
- Pharmacies:Compounding quality control and medication verification testing in hospital and retail settings.
- Food Safety Laboratories:Government inspection facilities and third-party certification bodies.
- Environmental Agencies:Federal and state monitoring stations with standardized method requirements.
- Crime Laboratories:State and federal forensic facilities with evidentiary chain protocols.
- Petrochemical Plants:In-process and product quality control with high-throughput screening needs.
Biotechnology firms lead on scale; food safety laboratories lead on momentum.
Deployment Type:
Capital intensity and operational flexibility tradeoffs determine scale selection, with multi-column continuous systems disrupting traditional batch configurations.
- Production-Scale:Stainless steel or single-use chromatography systems processing thousands of liters per batch in monoclonal antibody and vaccine manufacturing. Hyderabad and Mumbai CDMO clusters in India are expanding resin consumption volumes as global pharmaceutical outsourcing accelerates.
- Laboratory-Scale:Analytical HPLC, UHPLC, and GC systems for method development and quality control testing.
- Pilot-Scale:Process development and clinical material production bridging analytical and manufacturing scales.
- Mobile Units:Field-deployable systems for environmental emergency response and on-site forensic analysis.
- Custom Installations:Integrated multi-step purification trains engineered for specific biopharmaceutical processes.
Production-scale leads on scale; pilot-scale leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Analytical chemist talent clusters in Germany, the United States, and China concentrate reagent demand around contract research organization networks and pharmaceutical manufacturing hubs. These three countries host the largest CMO/CDMO footprints and enforce the most stringent bioanalytical method validation requirements.
United States
FDA bioanalytical method validation guidelines mandate enhanced reagent qualification documentation, forcing pharmaceutical manufacturers to upgrade analytical testing capacity. The agency's updated standards tighten lot-to-lot consistency requirements for high-purity solvents used in impurity profiling. Greater Boston and South San Francisco biotech clusters drive demand for single-use, gamma-irradiated chromatography formats with integrated certificate of analysis digitization.
Germany
EMA Annex 1 revisions on sterile manufacturing extend environmental monitoring to chromatography reagent storage and handling conditions. REACH registration costs for novel stationary phase media exceed EUR 100,000 per substance, elevating barriers for specialty entrants. The Rhine-Main and Upper Bavaria pharmaceutical manufacturing corridors concentrate demand for pharmaceutical-grade solvents with documented particulate and bioburden controls.
China
NMPA pharmacopoeia revisions impose stringent traceability requirements for chromatography reagents used in generic drug quality control. The agency's updated standards expand domestic and import substitution opportunities for qualified suppliers. Shanghai and Suzhou biopharmaceutical clusters are scaling monoclonal antibody manufacturing, accelerating ion exchange resin consumption in downstream purification trains.
India
CDSCO tightening of bioanalytical standards for generic drug exports drives reagent qualification investments among contract manufacturers. The regulator's alignment with FDA and EMA guidelines compels certificate of analysis documentation upgrades. Hyderabad and Mumbai CDMO clusters are expanding resin consumption volumes as global pharmaceutical outsourcing accelerates, creating underpenetrated demand for pharmaceutical-grade buffers with local qualification support.
Singapore
EMA-equivalent standards enforced by the Health Sciences Authority mandate sterile processing documentation for biopharmaceutical fill-finish operations. The city-state's biologics manufacturing hub status attracts gamma-irradiated or aseptically filtered reagent grades with enhanced certificate of analysis parameters. Tuas Biomedical Park and one-north research precinct concentrate demand for affinity resin in monoclonal antibody capture applications.
Global Chromatography Reagents Market Competitive Landscape
The competitive structure tilts toward vertically integrated life science conglomerates with multi-jurisdictional manufacturing footprints. Consolidation around REACH compliance capabilities and FDA bioanalytical qualification standards has elevated barriers for specialty stationary phase entrants. Three archetypes dominate: diversified laboratory supply conglomerates with captive solvent manufacturing, instrument-reagent bundling specialists, and pharmaceutical-grade chemical manufacturers with scale advantages. Competitive moves concentrate on certificate-of-analysis digitization investments and regional qualification redundancy strategies.
Among diversified laboratory supply conglomerates, Thermo Fisher Scientific, Merck KGaA, and Agilent Technologies occupy positions exemplifying distinct strategic archetypes. Thermo Fisher leverages vertically integrated supply chains to absorb regulatory compliance costs across multiple jurisdictions. Merck KGaA anchors its market presence through pharmaceutical-grade solvent manufacturing at scale. Agilent Technologies sits within the instrument-reagent bundling tier, locking in laboratory procurement workflows through integrated hardware-consumable ecosystems.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| Merck KGaA |
| Agilent Technologies, Inc. |
| Waters Corporation |
| Avantor, Inc. |
| Bio-Rad Laboratories, Inc. |
| Shimadzu Corporation |
| Danaher Corporation |
| PerkinElmer, Inc. |
| Others |
Supply & Pricing Matrix
FDA bioanalytical method validation mandates for enhanced certificate of analysis documentation are forcing pharmaceutical manufacturers to consolidate procurement around suppliers with multi-jurisdictional qualification capabilities, compressing margins for regional formulators while elevating pricing power for integrated conglomerates with captive solvent manufacturing.
Pricing Analysis
Instrument-reagent bundling versus standalone consumable procurement splits the market into two pricing regimes. Three-tier pricing structure across pharmaceutical-grade, analytical-grade, and industrial-grade certification levels dominates transactional volumes, with lot-to-lot consistency certification commanding substantial premia over standard grades. Cost compression in analytical-grade solvents is intensifying because acetonitrile feedstock volatility transmits directly from petrochemical markets. Contract research organizations exhibit highest price sensitivity due to pass-through contract structures, while biopharmaceutical manufacturers prioritize qualification reliability over unit cost.
Supply Chain Analysis
Protein A ligand supply rests on limited manufacturing capacity concentrated in the United States, Germany, and Ireland, with agarose bead matrices drawing from marine-derived raw material sources in Morocco and Portugal. High-purity acetonitrile production hinges on acrylonitrile byproduct economics at Asian petrochemical complexes. Single-source vulnerability for critical affinity ligands creates supply bottlenecks during biopharmaceutical manufacturing scale-ups. Distribution runs through direct enterprise contracts with pharmaceutical manufacturers and group purchasing organizations serving academic and government laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Chromatography Reagents Market functions as a stable compounder underpinned by irreversible regulatory tightening across FDA, EMA, and NMPA jurisdictions that permanently elevates reagent qualification requirements.
For Market Incumbents: Lock in laboratory procurement workflows through instrument-reagent bundling that embeds consumable specifications into method transfer protocols. Deepen backward integration into pharmaceutical-grade solvent manufacturing to absorb REACH compliance costs internally. Defend against emerging single-use format specialists by accelerating certificate of analysis digitization investments that legacy LIMS systems cannot easily replicate. For New Entrants and Emerging Players: Continuous chromatography resin formats offer a technology-first wedge into monoclonal antibody purification trains where incumbent batch resin suppliers lack scalable manufacturing. Target India's Hyderabad and Mumbai CDMO clusters with locally qualified buffer formulations and derivatization agents. Pursue service-integrated reagent supply models aligned with EU Green Deal solvent recovery mandates to differentiate from commodity suppliers. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale pharmaceutical-grade chemical manufacturers possessing EMA Annex 1 sterile processing capabilities but lacking global distribution reach. Long-term viability centers on regulatory pre-certification assets that compound in value as qualification documentation requirements intensify. Watch FDA bioanalytical guidance revision timing as the inflection signal for accelerated analytical testing capacity investments.| Strategic Initiative | Industry Significance |
|---|---|
| Certificate of Analysis Digitization | FDA bioanalytical guidance mandates automated data ingestion compatibility with enterprise LIMS platforms. |
| Multi-jurisdictional Manufacturing Footprint | REACH registration costs exceeding EUR 100,000 per substance favor consolidated regulatory compliance investments. |
| Continuous Chromatography Resin Scale-Up | Multi-column countercurrent systems in monoclonal antibody purification multiply resin consumption volumes. |
| Gamma-Irradiated Reagent Grade Expansion | EMA Annex 1 sterile manufacturing revisions extend particulate control requirements to solvent storage. |
| Local Qualification Support in India | Hyderabad and Mumbai CDMO cluster expansion creates underpenetrated demand for pharmaceutical-grade buffers. |
Research Methodology
Bottom-up pharmaceutical manufacturing modeling reconciled against top-down solvent production tracking forms the analytical core of this study. Primary interviews with regulatory affairs directors, CMO procurement leads, analytical laboratory managers, and chromatography instrument specialists were validated against secondary sources including FDA bioanalytical guidance documents, EMA Annex 1 revision drafts, NMPA pharmacopoeia updates, and customs trade data for high-purity solvent imports. The approach triangulates demand-side consumption patterns with supply-side manufacturing capacity across the United States, Germany, China, and India.
Input-output matrices connect resin consumption volumes to monoclonal antibody manufacturing batch counts, analytical HPLC run rates, and environmental testing method frequencies across the projection horizon. Segmentation dimensions include product type, application, end-user industry, and deployment scale. CAGRs were derived from regression analysis of historical regulatory expansion patterns and pharmaceutical outsourcing trends. Industry-specific forecast inputs incorporate Protein A ligand manufacturing capacity constraints and acetonitrile feedstock price elasticity.
The model holds under continued regulatory convergence between FDA, EMA, and NMPA jurisdictions; deviation in bioanalytical guidance harmonization or REACH enforcement intensity would shift reagent qualification cost structures. Forecasts reflect assumptions of sustained pharmaceutical outsourcing to India and China CDMO clusters. A small set of named triggers warrants ongoing watch: FDA bioanalytical method validation timeline, EMA Annex 1 sterile processing implementation pace, and Protein A ligand manufacturing capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Thioesters Market
Chemical Intermediates
Methoxypropylamine (MOPA) Market
Chemical Intermediates
Phosphate Chemical Reagents Market
Chemical Intermediates
Global Textile Finishing Chemicals Market
Chemical Intermediates
Triisobutyl Phosphate Market
Chemical Intermediates
Metaphenoxy Benzaldehyde (MPBD) Market
Chemical Intermediates
Acetoacetanilide Market
Chemical Intermediates
Palmitoyl Chloride Market
Chemical Intermediates
Ph Controlling Agents Market
Chemical Intermediates
Copper Chemicals Market
Chemical Intermediates
Leather Chemicals Market
Chemical Intermediates
Ethylene Urea Market
Chemical Intermediates
API Intermediate Market
Chemical Intermediates
Enzyme Substrates Market
Chemical Intermediates
Dye Intermediates Market
Chemical Intermediates
Dimethyl Dicarbonate Market