
 3-Chloropropionyl Chloride Market | 2026-2036
3-Chloropropionyl Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
3-Chloropropionyl Chloride Market Analytics
Pharmaceutical-grade specification is bifurcating the competitive landscape as buyers enforce tighter impurity limits for active pharmaceutical ingredient synthesis. BASF SE leverages its integrated chlor-alkali infrastructure to secure backward control over feedstock costs. Evonik Industries differentiates through dedicated R&D intensity in halogenated intermediate purification. Shiyan Hongming Pharmaceutical Technology Co. Ltd. anchors regional supply to domestic antibiotic manufacturers in Hubei Province.
3-Chloropropionyl chloride functions as an acylating agent and chlorinated propionyl derivative with a molecular weight of approximately 126.97 g/mol, produced primarily via thionyl chloride-mediated chlorination of propionic acid derivatives for pharmaceutical and agrochemical intermediate applications. High Purity grades command concentrated margin pools due to stringent pharmacopeial compliance requirements, while Technical Grade volumes sustain broader chemical synthesis demand. The Pharmaceutical application segment leads value generation through beta-lactam and propranolol precursor consumption, whereas Agrochemicals represent an expanding outlet for herbicide and fungicide synthesis.
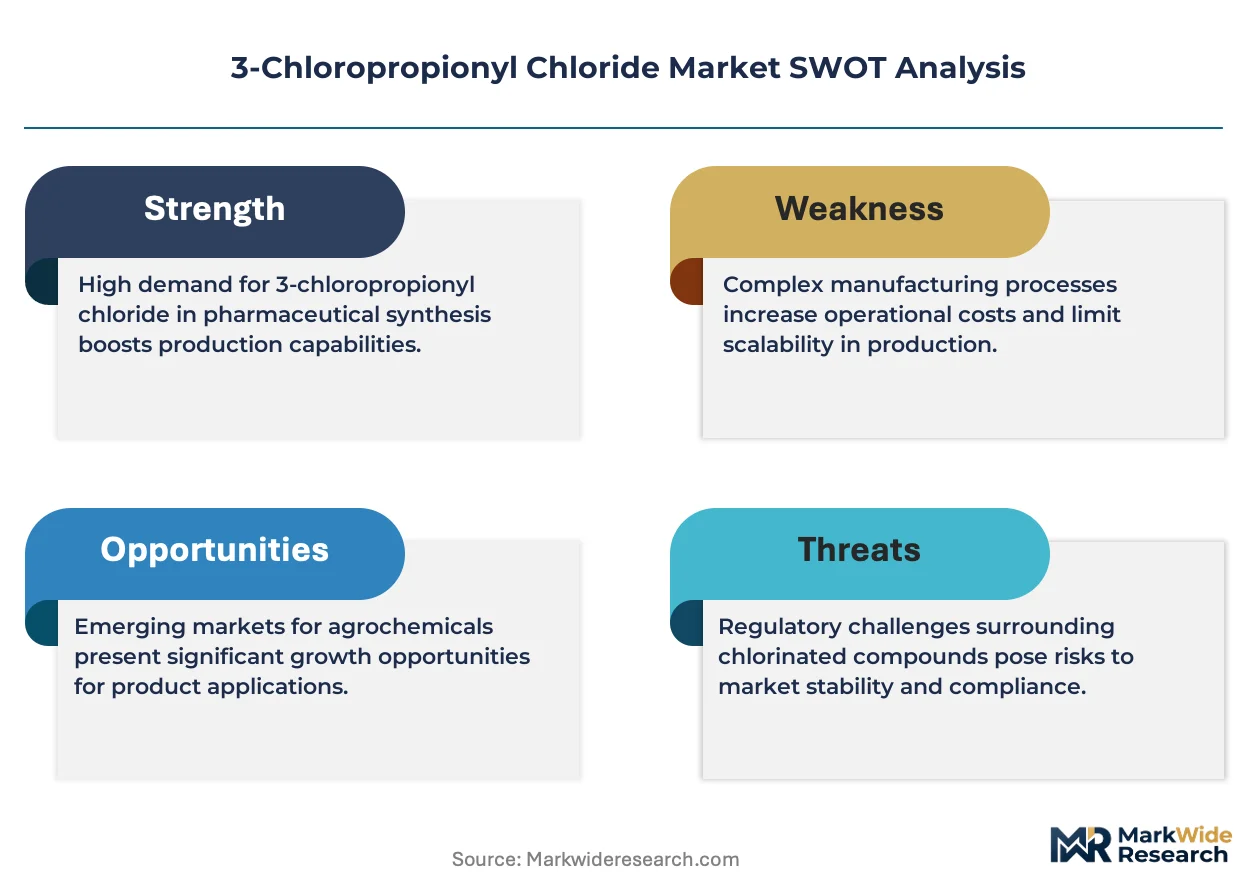
EPA oversight in the United States and REACH registration under ECHA in Europe impose escalating purity documentation and toxicological data requirements that filter out non-compliant suppliers. China's MEE enforces emission controls on chlorination facilities that elevate capital costs for small-scale producers. Stakeholders must monitor regulatory divergence between jurisdictions to align certification investments with accessible demand pools.
Market Dynamics
Pharmaceutical-grade purity mandates from CDSCO and EMA are compressing supplier margins while concentrating procurement among chlor-alkali integrated producers capable of pharmacopeial documentation.
Growth Catalysts
- REACH registration thresholds:ECHA's escalating data requirements for halogenated acyl chlorides are filtering out non-compliant traders, creating volume consolidation among certified manufacturers.
- Beta-lactam antibiotic intermediates:Indian pharmaceutical manufacturers in Gujarat and Maharashtra are expanding captive chlorination capacity to secure backward control over acylating agent supply.
- Jiangsu Province cluster effects:Integrated chlor-alkali-to-intermediate production corridors in eastern China are reducing logistics costs for agrochemical formulators.
Market Restraints
- Thionyl chloride price volatility:Feedstock cost swings for sulfur-based chlorinating agents compress margin predictability for non-integrated producers.
- Single-source dependency:European buyers face supply concentration risk from limited REACH-registered manufacturers in Germany and Switzerland.
- Aqueous quenching limitations:Conventional hydrolysis-sensitive handling protocols restrict formulation flexibility for water-based agrochemical applications.
Strategic Opportunities
- Brazilian agrochemical formulators:ANVISA registration pathways for chlorinated intermediates remain underpenetrated relative to herbicide demand growth in Mato Grosso.
- Flow chemistry chlorination:Continuous processing convergence with in-line purification is opening modular production economics for mid-scale pharmaceutical contractors.
- India PLI scheme extensions:Active pharmaceutical ingredient incentive structures are redirecting capital toward dedicated acyl chloride manufacturing assets.
Industry Challenges
- Halogenation process safety expertise:Qualified chemical engineers capable of managing exothermic chlorination protocols remain scarce in emerging manufacturing clusters.
- Pharmacopeial certification timelines:USP and EP monograph alignment for residual solvent specifications extends qualification cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3-Chloropropionyl Chloride Market |
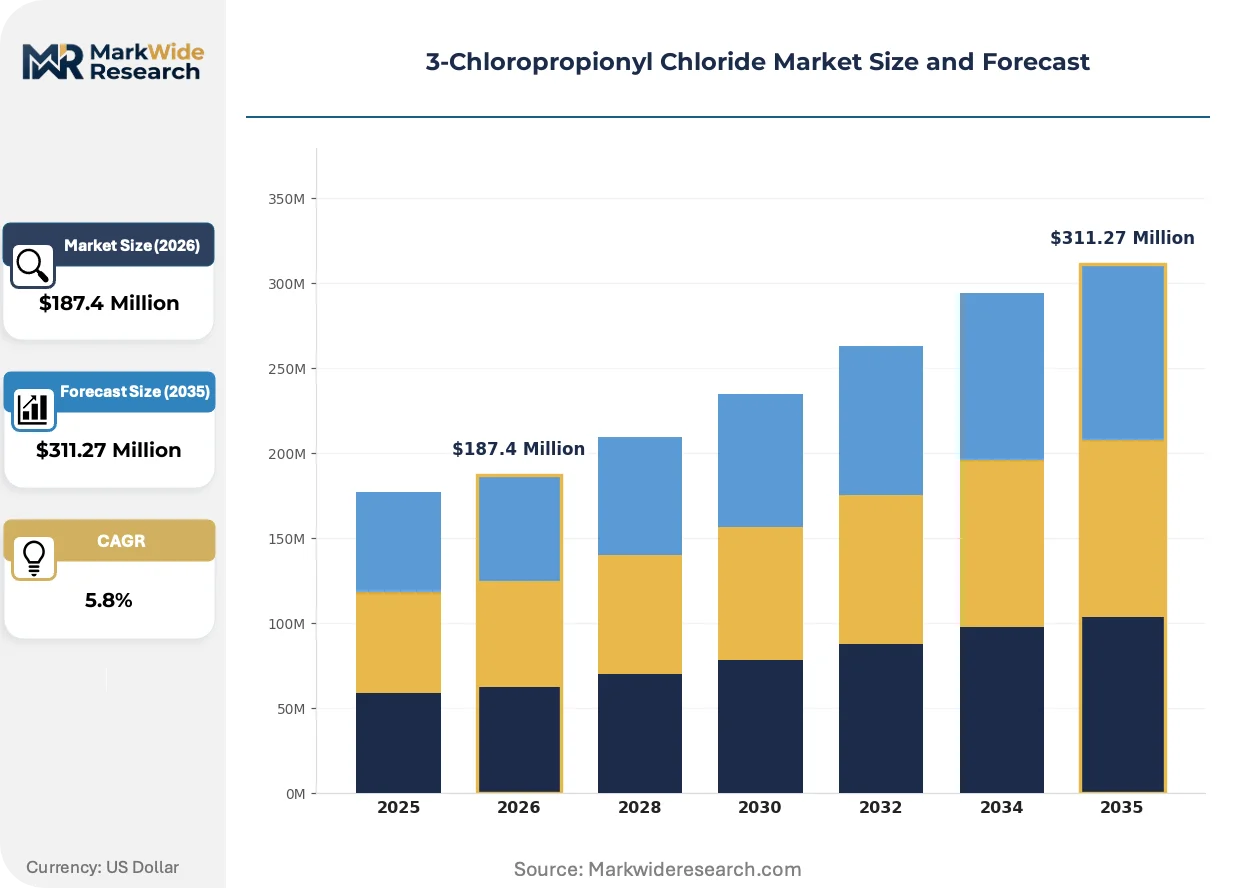
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Purity, Technical Grade, Reagent Grade, Industrial Grade Application: Pharmaceuticals, Agrochemicals, Chemical Synthesis, Plastics End User: Research Laboratories, Manufacturing Plants, Agricultural Sector, Pharmaceutical Companies Distribution Channel: Direct Sales, Online Platforms, Distributors, Wholesalers |
| Companies Covered | BASF SE, Dow Chemical Company, Evonik Industries, Shiyan Hongming Pharmaceutical Technology Co. Ltd., Novaphene Specialities Pvt. Ltd., Wanksons Chemical Industries, Cangzhou Runliqing Chemical Co. Ltd., Kanto Denka Kogyo Co. Ltd., Aditya Birla Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3-Chloropropionyl Chloride Market Evolving Landscape
Continuous processing technologies and regulatory data automation are compressing the gap between technical-grade commodity production and pharmaceutical-grade certification economics.
Membrane-based chlorine recovery systems are miniaturizing purification footprints for mid-scale acyl chloride manufacturers. Pharmaceutical contractors in Hubei and Shandong provinces are adopting skid-mounted chlorination units to bypass centralized chlor-alkali infrastructure. This distributed architecture is compressing capital barriers for qualified batch production while fragmenting regional supply concentration.
REACH Annex XIV authorization requirements for chlorinated intermediates are extending toxicological dossier obligations to downstream users. Specialty chemical distributors in the Netherlands and Belgium are absorbing compliance costs through dedicated regulatory affairs subsidiaries. Agrochemical formulators with legacy supply agreements face forced supplier requalification or formulation redesign.
Consolidated procurement desks at Indian antibiotic manufacturers are displacing spot-market purchasing with multi-year toll manufacturing contracts. CDSCO audit requirements are transferring quality assurance burden to chlorination partners. This contractual shift concentrates volume with integrated producers possessing dedicated pharmaceutical certification staff.
3-Chloropropionyl Chloride Market Segmentation
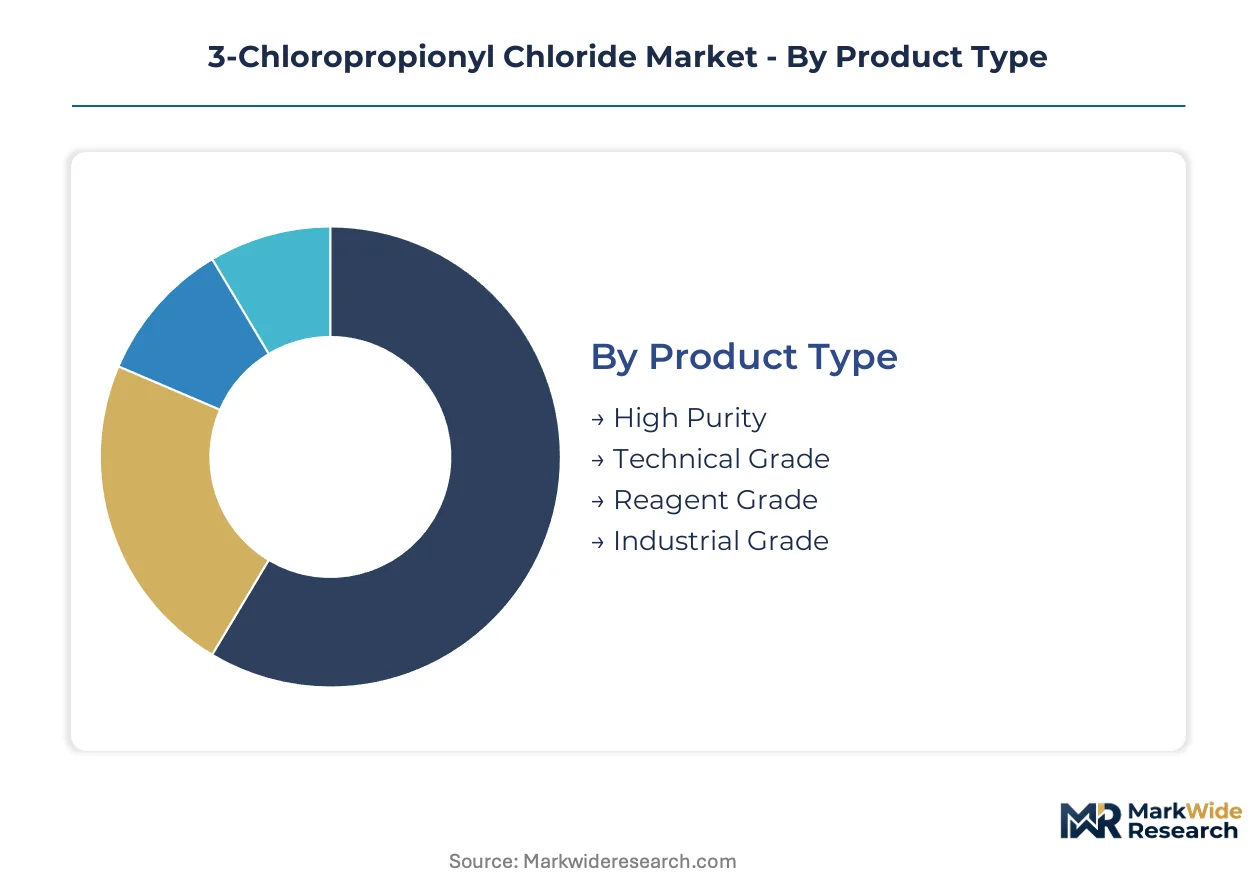
Segmentation in 3-chloropropionyl chloride reveals how purity grades and application specifications dictate channel economics. Buyers in pharmaceutical synthesis enforce pharmacopeial documentation that filters supply through qualified distributor networks, while agrochemical formulators prioritize volume throughput over certification depth.
Product Type:
Channel-mix patterns diverge sharply across purity tiers, with pharmaceutical-grade material flowing through specialized chemical distributors and technical grades reaching agrochemical formulators via direct mill relationships.
- High Purity:Specifications meeting USP and EP monograph requirements for residual solvents and heavy metals. Demand concentrates among beta-lactam antibiotic manufacturers in Gujarat State and Hubei Province where CDSCO and EMA audit protocols apply. ECHA REACH Annex XIV authorization requirements extend toxicological dossier obligations to downstream pharmaceutical contractors.
- Technical Grade:Standardized acylating agent for agrochemical intermediate synthesis with broader impurity tolerances. Procurement clusters in Jiangsu Province chlor-alkali corridors serve captive consumption by herbicide formulators. MEE emission controls on chlorination facilities elevate capital barriers for non-integrated producers.
- Reagent Grade:Laboratory-scale quantities for analytical method development and process validation studies.
- Industrial Grade:Bulk chlorinating agent for non-pharmaceutical chemical synthesis with minimal certification overhead.
High Purity dominates installed base value. Technical Grade is where expansion concentrates.
Application:
Cost-tier differentiation separates premium pharmaceutical synthesis from commodity agrochemical consumption, with certification burden determining margin capture.
- Pharmaceuticals:Beta-lactam antibiotic intermediates and propranolol precursors require pharmacopeial-grade acylating agents. Indian manufacturers under PLI scheme incentives are redirecting capital toward dedicated acyl chloride assets with integrated chlor-alkali feedstock security.
- Agrochemicals:Herbicide and fungicide synthesis drives volume demand with formulation flexibility constrained by aqueous quenching limitations. Brazilian formulators in Mato Grosso present underpenetrated demand relative to regional herbicide growth.
- Chemical Synthesis:General acylation reactions for specialty chemical production.
- Plastics:Polymer modification and additive intermediate applications.
Pharmaceuticals command margin concentration. Agrochemicals represent the steepest expansion trajectory.
End User:
Customer-type segmentation reveals how procurement scale dictates supplier relationship structure, from spot purchasing to multi-year toll manufacturing contracts.
- Research Laboratories:Small-batch requirements for method development and regulatory submission support.
- Manufacturing Plants:Integrated chlor-alkali-to-intermediate production in eastern China reduces logistics costs through captive consumption models.
- Agricultural Sector:Formulators in Brazil and India source technical grades through regional distributor networks with limited REACH-equivalent documentation.
- Pharmaceutical Companies:Consolidated procurement desks at Indian antibiotic manufacturers are displacing spot-market purchasing with multi-year toll manufacturing contracts transferring quality assurance burden to chlorination partners.
Pharmaceutical Companies anchor contract value. Manufacturing Plants drive volume throughput.
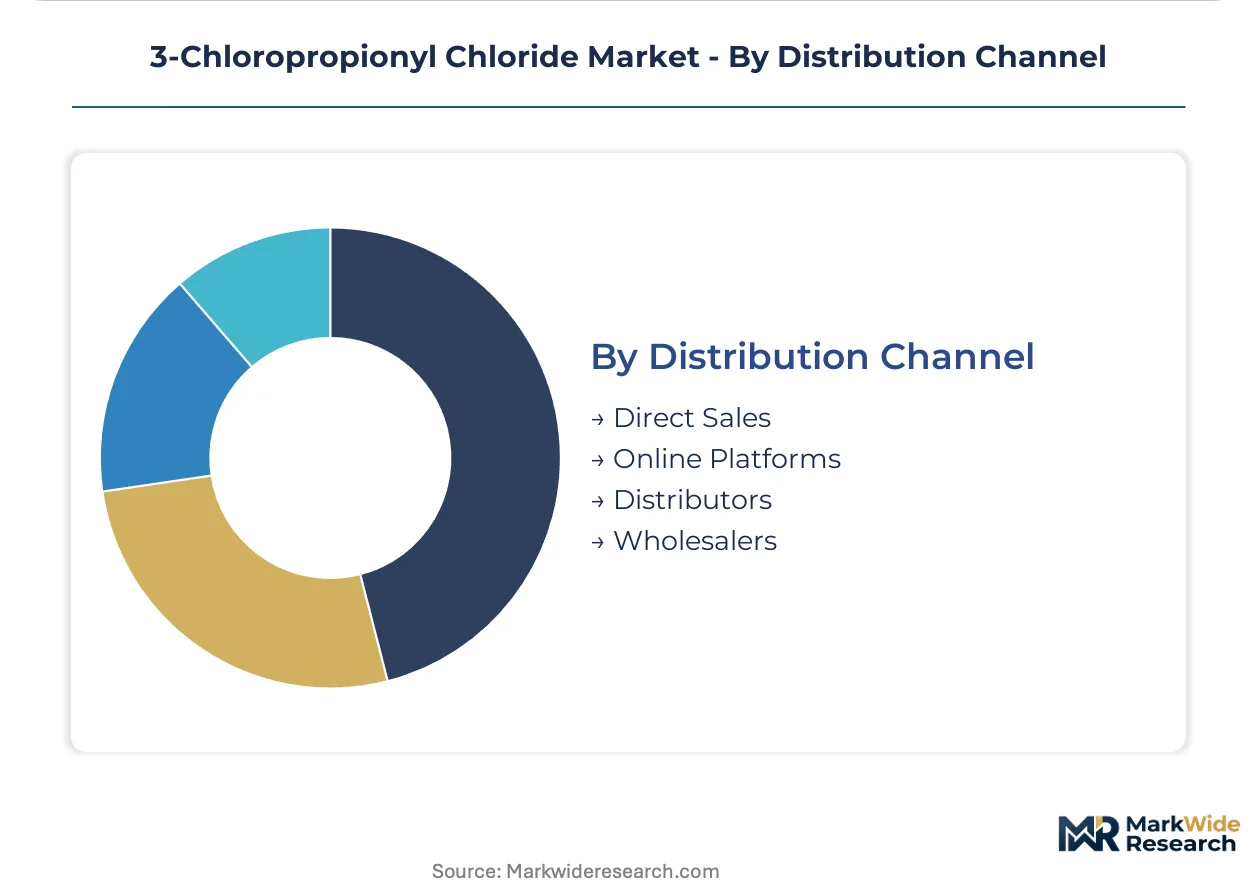
Distribution Channel:
Supply concentration geography determines channel efficiency, with chlor-alkali integrated producers favoring direct relationships and fragmented regional suppliers relying on distributor intermediation.
- Direct Sales:Preferred by chlor-alkali integrated producers for pharmaceutical-grade volumes requiring pharmacopeial documentation and audit trail maintenance.
- Online Platforms:Emerging channel for reagent-grade and small-batch technical specifications.
- Distributors:Specialty chemical distributors in the Netherlands and Belgium absorb REACH compliance costs through dedicated regulatory affairs subsidiaries serving European pharmaceutical formulators.
- Wholesalers:Volume aggregation for technical-grade agrochemical applications with standardized specifications.
Direct Sales dominates pharmaceutical value capture. Distributors manage regulatory complexity for mid-scale buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese producers in Jiangsu Province export high-purity grades to Indian pharmaceutical manufacturers in Gujarat and Maharashtra. European buyers source through REACH-registered distributors in Germany and Switzerland.
China
Beta-lactam antibiotic intermediate demand and agrochemical formulation growth drive consumption. MEE emission controls on chlorination facilities elevate capital barriers for small-scale producers. Manufacturing clusters in Jiangsu Province operate integrated chlor-alkali-to-intermediate corridors serving captive consumption by herbicide formulators.
India
PLI scheme incentives redirect capital toward dedicated acyl chloride manufacturing assets for antibiotic production. CDSCO audit requirements transfer quality assurance burden to chlorination partners. Gujarat State manufacturers expand captive chlorination capacity to secure backward control over acylating agent supply.
Germany
REACH Annex XIV authorization requirements filter supply through certified manufacturers with pharmacopeial documentation capabilities. ECHA escalating data requirements for halogenated acyl chlorides consolidate volume among registered producers. BASF SE leverages integrated chlor-alkali infrastructure in Ludwigshafen to control feedstock costs.
United States
EPA standards tighten purity thresholds and reshape supplier qualification protocols for pharmaceutical applications. Evolving toxicological data requirements extend dossier obligations to downstream users. Chemical manufacturing clusters along the Gulf Coast maintain chlorination capacity for domestic agrochemical synthesis.
Brazil
ANVISA registration pathways for chlorinated intermediates remain underpenetrated relative to herbicide demand growth in Mato Grosso. Regional formulators source technical grades through distributor networks with limited REACH-equivalent documentation. Agricultural sector expansion drives volume requirements for fungicide and herbicide synthesis intermediates.
3-Chloropropionyl Chloride Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and integration levels. The vendor base fragments between chlor-alkai integrated multinationals and regional pharmaceutical-grade specialists. Three archetypes dominate: integrated chemical conglomerates with captive feedstock security, dedicated halogenated intermediate purifiers with R&D intensity, and regional contractors serving domestic antibiotic manufacturers. Capacity expansion and pharmacopeial certification investments constitute the dominant competitive moves.
Within the integrated conglomerate tier, BASF SE and Dow Chemical Company exemplify archetypes combining chlor-alkali infrastructure with pharmaceutical-grade documentation capabilities. Evonik Industries occupies a position representing specialized purification expertise. Among Asia-Pacific-based specialists, Shiyan Hongming Pharmaceutical Technology Co. Ltd. anchors regional supply relationships with domestic pharmaceutical manufacturers in Hubei Province. Cangzhou Runliqing Chemical Co. Ltd. sits within the technical-grade volume segment serving agrochemical formulators.
| Leading Market Players |
|---|
| BASF SE |
| Dow Chemical Company |
| Evonik Industries |
| Shiyan Hongming Pharmaceutical Technology Co. Ltd. |
| Novaphene Specialities Pvt. Ltd. |
| Wanksons Chemical Industries |
| Cangzhou Runliqing Chemical Co. Ltd. |
| Kanto Denka Kogyo Co. Ltd. |
| Aditya Birla Chemicals |
| Others |
Value Network & Pricing Analysis
Thionyl chloride substitution by alternative chlorinating agents in Jiangsu Province and Gujarat State simultaneously redraws procurement geography and compresses margin structures for non-integrated acyl chloride manufacturers. This feedstock pivot transfers pricing power toward chlor-alkali conglomerates while fragmenting technical-grade spot markets.
Pricing Analysis
Batch-process versus continuous-flow chlorination technology divides pricing tiers, with legacy batch operations commanding lower unit economics against modular continuous systems. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and industrial-grade levels reflects certification depth and impurity thresholds. Cost compression in technical-grade volumes intensifies because thionyl chloride volatility feeds directly into spot-market quotations. Agrochemical formulators in Brazil exhibit highest price sensitivity, while EMA-audited antibiotic manufacturers absorb premium differentials for pharmacopeial documentation.
Supply Chain Analysis
Strategic stockpiling of thionyl chloride and sulfur-derived feedstocks dominates procurement behavior among Indian pharmaceutical manufacturers confronting CDSCO audit timelines. Manufacturing concentration centers on China, India, and Germany, with Jiangsu Province chlor-alkali corridors feeding captive consumption models. Supply security rests on thionyl chloride availability, chlorine gas supply contracts, and REACH-registered logistics partners. Single-source vulnerability from limited ECHA-registered producers in Germany and Switzerland elevates European formulator risk. Distribution runs through specialty chemical distributors in the Netherlands and Belgium for REACH-compliant pharmaceutical grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidated procurement desks at Indian antibiotic manufacturers are compressing supplier margins and transferring quality assurance burdens upstream, amplifying buyer leverage across contract negotiations.
For Market Incumbents: Fortify pharmacopeial certification depth against emerging flow-chemistry specialists threatening modular production economics. BASF SE's integrated Ludwigshafen chlor-alkali infrastructure demonstrates how backward control over thionyl chloride supply secures margin predictability. CDSCO audit requirement escalation transfers compliance costs to chlorination partners, favoring incumbents with dedicated regulatory affairs staff. For New Entrants and Emerging Players: Lead with ANVISA registration pathway completion for Brazilian agrochemical formulators in Mato Grosso, where herbicide demand growth outpaces qualified intermediate supply. Flow chemistry chlorination presents the most penetrable technology angle for mid-scale pharmaceutical contractors in Hubei and Shandong provinces. Partner with established specialty chemical distributors to absorb REACH compliance overhead rather than building in-house regulatory capabilities. For Investors and Strategic Acquirers: The market sits at a certification-intensification phase that favors chlor-alkali integrated producers with pharmacopeial documentation capabilities over pure-play technical-grade operators. Five-to-ten-year viability hinges on REACH Annex XIV authorization completion and CDSCO audit track records. Acquisition targets should demonstrate integrated feedstock security plus dedicated halogenation process safety expertise. Monitor EMA and FDA impurity threshold revisions as inflection indicators for qualification cycle extensions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali Feedstock | BASF SE's Ludwigshafen complex demonstrates how captive chlorine supply secures margin predictability against thionyl chloride volatility. |
| Flow Chemistry Chlorination Scale-Up | Modular continuous processing in Hubei Province compresses capital barriers for qualified pharmaceutical-grade batch production. |
| REACH Annex XIV Authorization Completion | ECHA toxicological dossier compliance filters European supply through certified manufacturers with dedicated regulatory subsidiaries. |
| CDSCO Audit Partnership Structures | Indian antibiotic manufacturers transfer quality assurance burden to chlorination partners through multi-year toll manufacturing contracts. |
| Brazilian ANVISA Registration Pathway | Mato Grosso herbicide formulators present underpenetrated demand relative to regional agricultural expansion and limited qualified intermediate supply. |
Research Methodology
Operator-level perspectives from chlorination plant managers, pharmaceutical procurement leads at Indian antibiotic manufacturers, specialty chemical distributors in the Netherlands and Belgium, and ECHA regulatory affairs consultants anchored the qualitative base. Primary interviews combined with secondary validation from customs and trade data, Cefic chemical industry reports, SEC 10-K filings for listed chlor-alkali producers, and ECHA registration databases. Bottom-up volume modeling triangulated against top-down market sizing across grade tiers and end-use industries.
Sensitivity analysis tested forecast robustness against thionyl chloride price volatility scenarios and REACH authorization timeline extensions across the projection horizon. The analytical framework segmented by purity grade, application, end-user type, and regional production hub, with CAGRs derived from installed base growth rates and substitution elasticity estimates. Chlor-alkali capacity expansion announcements and CDSCO audit requirement escalations served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained pharmaceutical-grade certification investment or abrupt thionyl chloride supply disruption would require recalibration. Forecasts reflect documented assumptions regarding EMA and FDA impurity threshold stability, MEE emission control enforcement continuity, and PLI scheme incentive persistence. Revision becomes warranted when REACH Annex XIV authorization timelines cross eighteen-month extension thresholds or when Indian captive chlorination capacity additions exceed projected antibiotic intermediate demand absorption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Chemical Synthesizer Market
Chemical Intermediates
Butadiene Derivatives Market
Chemical Intermediates
Nutrition Chemicals Market
Chemical Intermediates
Fungal Staining Reagent Market
Chemical Intermediates
Myristoyl Chloride Market
Chemical Intermediates
Metaphenoxy Benzaldehyde (MPBD) Market
Chemical Intermediates
Refinery Process Chemicals Market
Chemical Intermediates
Global Chromatography Reagents Market
Chemical Intermediates
Ethylene Urea Market
Chemical Intermediates
Thioesters Market
Chemical Intermediates
United States Cellulose Acetate Market
Chemical Intermediates
Organometallic Compounds Market
Chemical Intermediates
2-Acetylthiophene Market
Chemical Intermediates
Polyamide Intermediate Chemicals Market
Chemical Intermediates
Pigment Intermediates Market
Chemical Intermediates
Global Textile Finishing Chemicals Market