
 Tertiary Amines Market | 2026-2036
Tertiary Amines Market Size, Share, and Industry Trends Forecast 2026-2036
Tertiary Amines Market Analysis
Asset-light toll manufacturing is fragmenting competitive boundaries in tertiary amines, allowing regional chemical processors to enter without owning full synthesis infrastructure. Eastman Chemical Company leverages backward integration into propylene feedstocks to sustain margin control across alkyl amine grades. Albemarle Corporation anchors its position through bromine-amine chemistry leadership, while Kao Corporation dominates surfactant-grade fatty amine supply to Asian cosmetics formulators.
Tertiary amines are nitrogen-containing organic compounds with three alkyl or aryl substituents bonded to a central nitrogen atom, typically manufactured via reductive amination of alcohols or aldehydes with ammonia and hydrogen over metal catalysts at elevated pressure; they function primarily as intermediates, surfactants, pH adjusters, and phase-transfer catalysts across industrial chemistry. Fatty amines command the largest volume share due to their entrenched role in fabric softener and corrosion-inhibitor formulations, while alkoxylated amines represent the fastest-expanding category as waterborne coating formulators replace solvent-based systems. Pharmaceutical-grade aromatic amines concentrate margin pools where CDMOs demand sub-ppm impurity profiles for active pharmaceutical ingredient synthesis.
EPA registration under FIFRA shapes agrochemical amine demand by mandating ecotoxicology dossiers for each formulation grade, while REACH restricts certain alkylamine classifications based on aquatic toxicity thresholds in European imports. India's CDSCO and BIS standards govern pharmaceutical and industrial amine purity, creating dual-compliance burdens for exporters serving multiple jurisdictions. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as fluorinated tertiary amine catalysts face substitution pressure from regulators in Europe and North America.
Market Dynamics
REACH compliance in Europe and EPA registration under FIFRA are tightening purity specifications for amine imports, forcing manufacturers to reconfigure synthesis pathways and invest in analytical capabilities to meet sub-ppm impurity thresholds for agrochemical and pharmaceutical grades.
Growth Catalysts
- Agrochemical Formulation Demand:Herbicide manufacturers are expanding procurement of alkyl amines as active ingredient carriers, with EPA registration requirements under FIFRA creating durable demand for ecotoxicology-certified grades.
- Waterborne Coating Transition:Alkoxylated amines are displacing solvent-based surfactants as coating formulators respond to VOC regulations across industrial applications.
- India Manufacturing Scale-Up:Balaji Amines and Indo Amines Ltd. are scaling fatty amine output for personal care and detergent applications, concentrating regional supply capacity.
Market Restraints
- Propylene Feedstock Volatility:Eastman Chemical Company's margin control depends on captive propylene supply, exposing non-integrated producers to olefin price swings.
- Aquatic Toxicity Classifications:REACH restricts certain alkylamine classifications based on ecotoxicology thresholds, creating import friction for European destinations.
- Fluorinated Amine Substitution Pressure:Per- and polyfluoroalkyl substance restrictions in Europe and North America are forcing catalyst formulators to abandon fluorinated tertiary amine chemistries.
Strategic Opportunities
- CDMO Pharmaceutical Partnerships:Contract development and manufacturing organizations demand sub-ppm impurity profiles for active pharmaceutical ingredient synthesis, creating premium margin pools.
- Asset-Light Toll Manufacturing:Regional chemical processors are entering tertiary amine production without owning full synthesis infrastructure, fragmenting competitive boundaries.
- Surfactant-Grade Cosmetics Supply:Kao Corporation's dominance in Asian cosmetics formulators demonstrates channel control opportunities for fatty amine specialists.
Industry Challenges
- Multi-Jurisdictional Compliance Burden:India's CDSCO and BIS standards create dual-certification requirements for exporters serving pharmaceutical and industrial segments simultaneously.
- Catalyst Redesign Timelines:Substitution of fluorinated tertiary amine catalysts requires reformulation cycles that compress product development windows.
- Analytical Capability Investment:Sub-ppm impurity detection for pharmaceutical grades demands capital-intensive chromatography and mass spectrometry infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tertiary Amines Market |
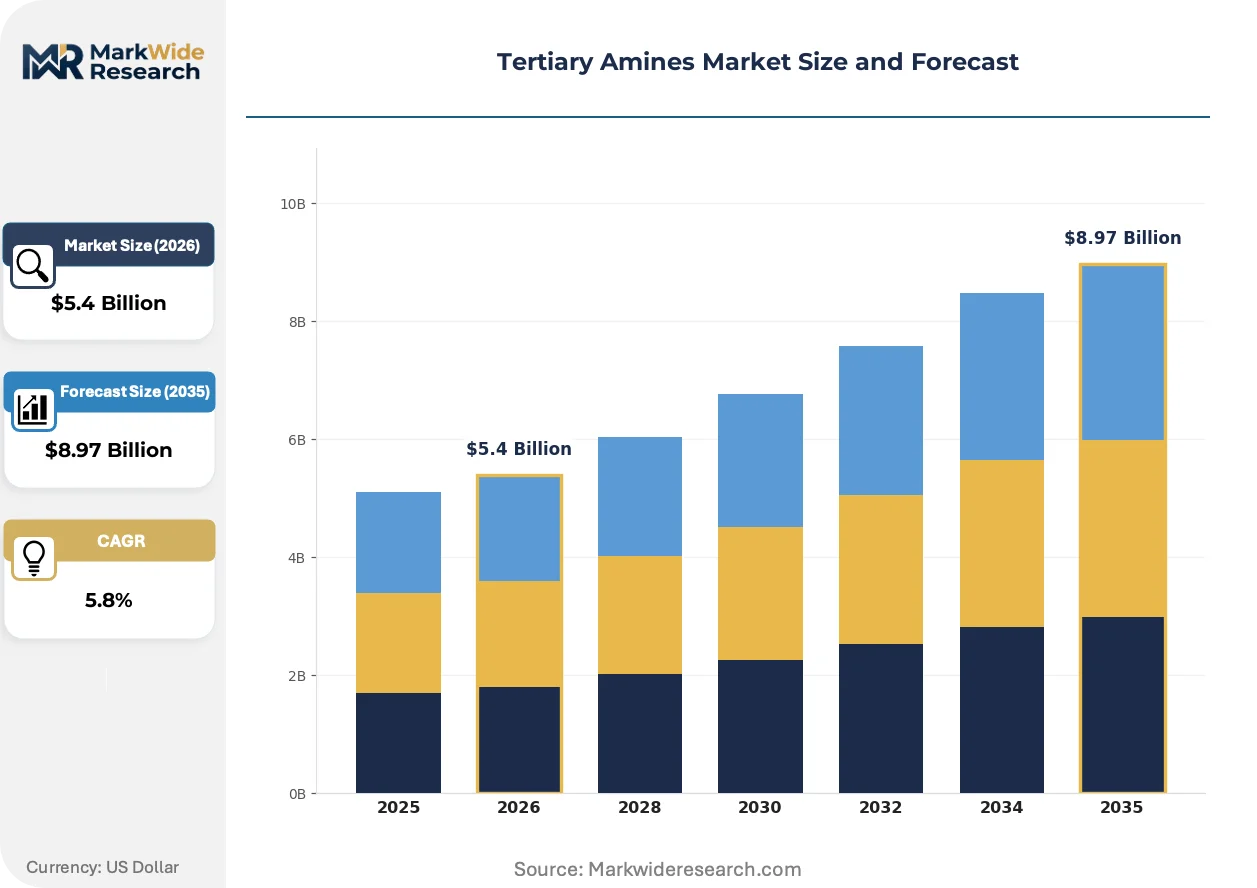
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $8.97 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkyl Amines, Aromatic Amines, Alkoxylated Amines, Fatty Amines Application: Detergents, Agriculture, Pharmaceuticals, Personal Care End User: Chemical Manufacturers, Agrochemical Firms, Cosmetics Industry, Pharmaceutical Companies Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Eastman Chemical Company, Balaji Amines, Albemarle Corporation, Indo Amines Ltd., Temix Oleo Srl, KLK Oleo, Arkema, BASF SE, Kao Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tertiary Amines Market Emerging Trajectories
Reductive amination processes are being reengineered to accommodate stricter regulatory thresholds, while downstream formulators seek amine grades that satisfy multiple jurisdiction standards without batch segregation.
Bio-based feedstock pathways for fatty amine production are hybridizing conventional petrochemical synthesis with renewable alcohol streams. Personal care formulators in Western Europe are piloting these hybrid routes to meet EU Green Deal carbon intensity targets. The structural consequence is compressing the premium gap between petroleum-derived and renewable-grade amines.
EPA registration under FIFRA is reshaping agrochemical amine specifications by mandating complete ecotoxicology dossiers for each formulation grade. This documentation burden favors incumbent suppliers with established regulatory affairs infrastructure. Agrochemical end-uses in the United States are responding by consolidating supplier relationships to reduce registration complexity.
Buyer concentration among multinational agrochemical and pharmaceutical formulators is compressing supplier negotiation cycles and unbundling technical service from material supply. Regional distributors in India are losing share to direct procurement arrangements. This pattern is most visible in the herbicide active ingredient supply chain serving North American and European crop protection markets.
Tertiary Amines Market Segmentation
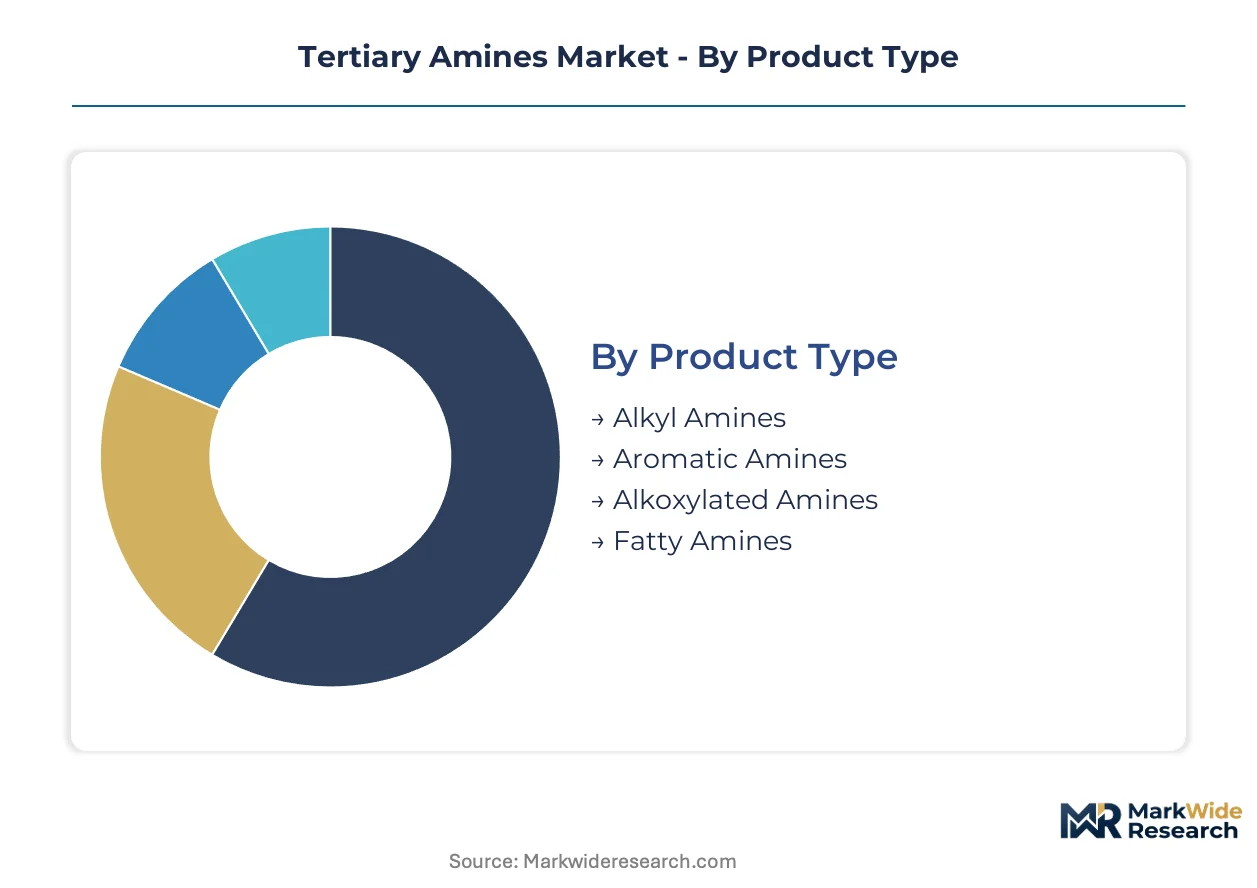
Tertiary amines serve divergent performance specifications across agrochemical carriers, pharmaceutical intermediates, and surfactant formulations. Segmentation reveals how purity grades, alkyl chain lengths, and functionalization patterns determine addressable margin pools and regulatory compliance burdens.
Product Type:
Mature commodity grades dominate volume flows while specialty derivatives capture expanding specification premiums.
- Fatty Amines:Long-chain alkyl groups (C12-C18) bonded to nitrogen deliver cationic surfactancy for fabric softener and corrosion inhibitor formulations. Demand concentrates in India where Balaji Amines scales output for detergent manufacturers responding to BIS purity standards.
- Alkoxylated Amines:Ethylene oxide or propylene oxide adducts of primary or secondary amines create water-dispersible surfactants with tunable hydrophilic-lipophilic balance. Coating formulators in Western Europe displace solvent-based systems under EU Green Deal VOC restrictions, accelerating procurement of ethoxylated tallow amine grades.
- Alkyl Amines:Short-chain methyl, ethyl, and propyl derivatives serve as pH adjusters and quaternization feedstocks for chemical manufacturers.
- Aromatic Amines:Phenyl or naphthyl substituents enable high-temperature stability in pharmaceutical intermediate synthesis where CDMOs demand sub-ppm impurity profiles.
Fatty amines retain volume leadership; alkoxylated amines hold the steepest expansion curve.
Application:
End-use concentration patterns reflect divergent regulatory stringency and formulation complexity across industrial sectors.
- Agriculture:Alkyl amine salts function as herbicide active ingredient carriers and adjuvants, with EPA registration under FIFRA mandating ecotoxicology dossiers for each formulation grade. Procurement consolidates around suppliers with established regulatory affairs infrastructure.
- Pharmaceuticals:High-purity tertiary amines serve as phase-transfer catalysts and synthetic intermediates in active pharmaceutical ingredient manufacturing. REACH compliance in Europe and CDSCO standards in India create dual-certification requirements for exporters.
- Detergents:Fatty amine quaternaries provide fabric softening and antistatic performance for household and industrial laundry formulations.
- Personal Care:Milder alkoxylated amines function as emulsifiers and conditioning agents in cosmetics formulations, with Kao Corporation dominating surfactant-grade supply to Asian formulators.
Agriculture commands the largest volume commitment; pharmaceuticals generate the highest specification premiums.
End User:
Customer scale and integration depth determine procurement channel preferences and technical service expectations.
- Agrochemical Firms:Integrated crop protection companies purchase amine grades in bulk quantities for proprietary herbicide formulations, prioritizing suppliers with FIFRA registration support and batch traceability systems.
- Pharmaceutical Companies:Multinational drug manufacturers and their CDMO partners demand sub-ppm impurity detection capabilities and dedicated quality agreements for GMP-compliant amine supply.
- Chemical Manufacturers:Commodity and specialty chemical producers source tertiary amines for downstream quaternization, oxidation, or alkylation reactions.
- Cosmetics Industry:Brand owners and contract manufacturers procure surfactant-grade fatty amines with certified sustainable palm or coconut feedstock chains.
Agrochemical firms drive the highest throughput volumes; pharmaceutical companies impose the most stringent qualification protocols.
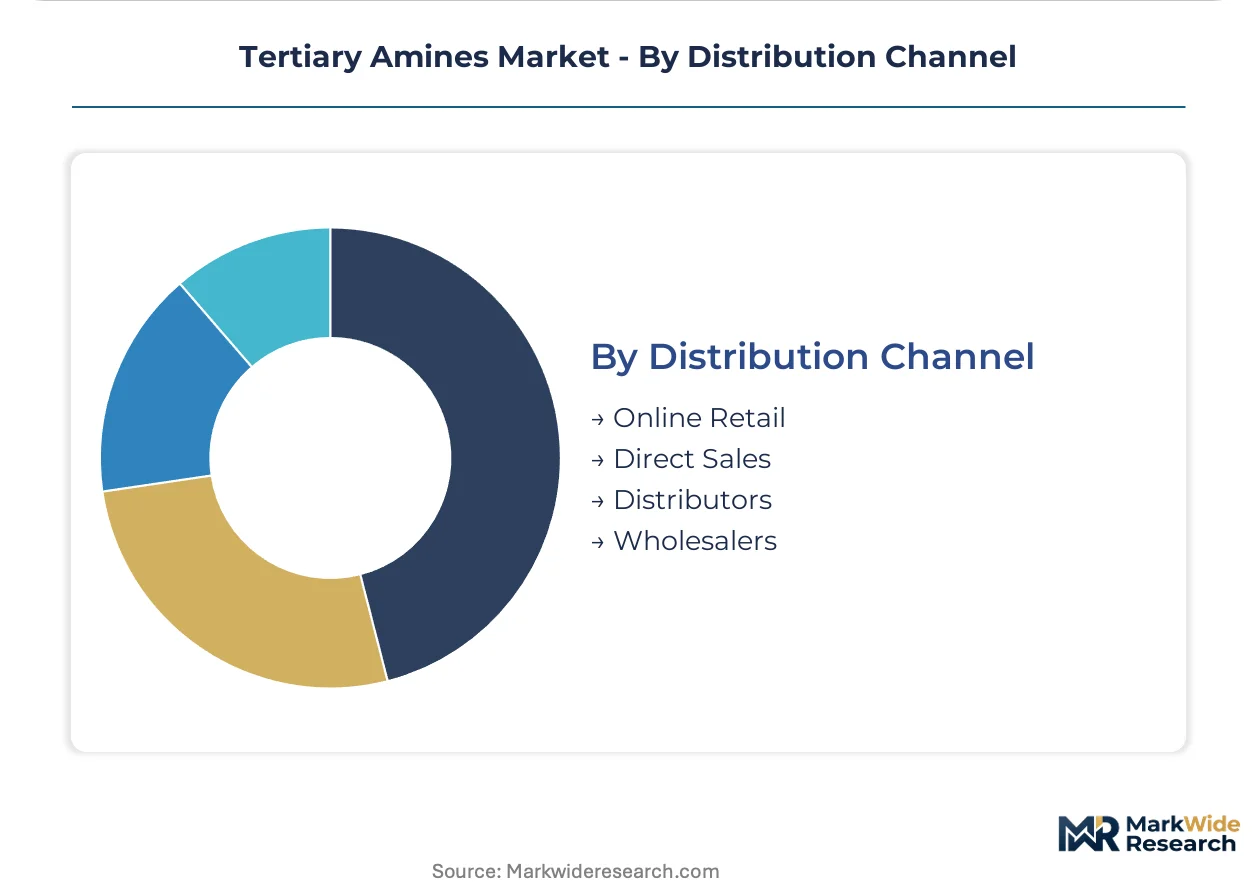
Distribution Channel:
Channel selection balances lot size requirements, technical support needs, and geographic proximity to manufacturing clusters.
- Direct Sales:Large-volume agrochemical and pharmaceutical formulators negotiate long-term supply agreements with integrated producers like Eastman Chemical Company, securing captive allocation and technical collaboration on specification development.
- Distributors:Regional chemical distributors maintain inventory positions for mid-tier chemical manufacturers and smaller cosmetics formulators requiring shorter lead times and smaller minimum order quantities.
- Online Retail:Laboratory-scale quantities and specialty grades reach research institutions and pilot-scale formulators through B2B platforms.
- Wholesalers:Bulk commodity grades flow through traditional chemical wholesale networks serving detergent and industrial cleaning compound manufacturers.
Direct sales capture the largest value concentration; distributors maintain the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances vary sharply across major economies, with amine trade flows reflecting divergent feedstock access, regulatory stringency, and end-use manufacturing concentration. Net exporters leverage olefin integration and toll manufacturing scale, while importers respond to tightening purity mandates.
United States
Agrochemical formulators drive alkyl amine consumption for herbicide adjuvants and active ingredient carriers. EPA registration under FIFRA mandates ecotoxicology dossiers for each formulation grade, consolidating procurement around established suppliers. The Gulf Coast petrochemical corridor sustains propylene-integrated amine output serving domestic crop protection manufacturers.
Germany
Waterborne coating formulators accelerate alkoxylated amine procurement as EU Green Deal VOC restrictions displace solvent-based systems. REACH compliance tightens aquatic toxicity classifications for certain alkylamine imports, creating friction for non-European suppliers. The Ruhr industrial basin maintains specialty amine capacity for pharmaceutical intermediate synthesis.
India
Personal care and detergent manufacturers scale fatty amine procurement as domestic consumption expands. CDSCO and BIS standards impose dual-certification requirements on pharmaceutical and industrial grades, complicating export logistics. Maharashtra and Gujarat host concentrated amine production clusters serving Asian surfactant markets.
China
Chemical manufacturers dominate tertiary amine consumption for downstream quaternization and phase-transfer catalysis. MIIT and GB standards govern industrial chemical purity, while NMPA oversight applies to pharmaceutical-grade material. The Yangtze River Delta concentrates alkoxylated amine capacity for coatings and textiles.
Japan
Cosmetics formulators source surfactant-grade fatty amines with certified sustainable feedstock chains. METI and PMDA standards enforce sub-ppm impurity thresholds for pharmaceutical applications. The Kansai region around Osaka maintains legacy amine production serving domestic specialty chemical demand.
Tertiary Amines Market Vendor Landscape
On the supply side, the industry is consolidating around integrated petrochemical players and regional toll manufacturers, with mid-tier specialists occupying specification niches. Three archetypes dominate: propylene-integrated majors controlling feedstock economics, asset-light toll processors fragmenting regional boundaries, and purity-focused specialists serving pharmaceutical CDMOs. Capacity expansion and backward integration into olefin feedstocks represent the dominant competitive vectors, while regulatory affairs infrastructure emerges as a non-negotiable capability for agrochemical and pharmaceutical supply.
Among integrated chemical producers, Eastman Chemical Company exemplifies the feedstock-anchored archetype through captive propylene supply. Albemarle Corporation occupies a position within the specialty chemicals tier, while Kao Corporation represents the surfactant-grade dominance model in Asian personal care channels. These three entities illustrate how competitive positioning stratifies across upstream control, functional specialization, and regional channel capture.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Balaji Amines |
| Albemarle Corporation |
| Indo Amines Ltd. |
| Temix Oleo Srl |
| KLK Oleo |
| Arkema |
| BASF SE |
| Kao Corporation |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European alkoxylated amine production is driving suppliers toward premium pricing postures while forcing buyers into longer contract commitments. This utilization squeeze concentrates negotiation leverage with propylene-integrated majors who control captive feedstock economics.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across pharmaceutical-grade, agrochemical-certified, and industrial commodity tiers. Price differentiation rests on REACH compliance certification and EPA FIFRA registration status as primary drivers. Cost compression in standard-grade fatty amines is intensifying because Indian toll manufacturers are fragmenting regional supply boundaries. Agrochemical formulators exhibit highest price sensitivity due to bulk volume procurement, while pharmaceutical CDMOs accept premium tiers for sub-ppm impurity guarantees.
Supply Chain Analysis
Toll manufacturing concentration in India, Germany, and the United States holds the majority of flexible amine processing capacity. Raw material dependencies center on propylene feedstocks, renewable alcohol streams, and ethylene oxide for alkoxylation. Single-source vulnerability runs through Gulf Coast propylene supply corridors serving North American agrochemical formulators. Distribution runs through direct sales agreements for large-volume buyers, with regional distributors serving mid-tier chemical manufacturers requiring smaller lot sizes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The tertiary amines market represents an early-cycle expansion story as waterborne coating formulators accelerate procurement of alkoxylated grades under EU Green Deal VOC mandates. This regulatory tailwind is expanding addressable specification premiums beyond traditional surfactant applications.
For Market Incumbents: Harden regulatory affairs infrastructure to defend EPA FIFRA registration moats against emerging toll manufacturers lacking ecotoxicology dossier capabilities. Prioritize backward integration into renewable alcohol feedstocks to meet EU Green Deal carbon intensity thresholds before premium-standard gaps compress further.
For New Entrants and Emerging Players: India's pharmaceutical-grade aromatic amine segment offers the most penetrable white space given CDSCO dual-certification burdens that deter established exporters. Target toll manufacturing partnerships with Maharashtra-based processors to bypass capital-intensive synthesis infrastructure. Lead with analytical capability investment as a service-layer differentiator for sub-ppm impurity detection.
For Investors and Strategic Acquirers: Capital is best deployed toward asset-light toll processors with established regulatory affairs infrastructure across multiple jurisdictions. Long-term viability hinges on positioning for fluorinated amine catalyst substitution cycles as PFAS restrictions tighten. Watch for consolidation signals when REACH aquatic toxicity reclassifications force smaller exporters to exit European destinations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Feedstocks | Eastman Chemical's captive supply secures margin control against olefin volatility. |
| Green Manufacturing Transition | Hybrid bio-based routes compress petroleum-renewable premium gaps for EU cosmetics formulators. |
| Long-term Supply Agreement | Direct procurement arrangements displace Indian distributors serving multinational agrochemical firms. |
| Joint Venture | Regional toll partnerships fragment competitive boundaries without full synthesis capital deployment. |
| Capacity Expansion | Balaji Amines scales fatty amine output to capture personal care demand concentration in Maharashtra. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with agrochemical procurement leads, pharmaceutical CDMO quality directors, surfactant plant managers, and toll manufacturing operators. Secondary validation drew from EPA FIFRA registration databases, ECHA REACH dossier filings, Indian customs trade data, and SEC 10-K disclosures from integrated chemical producers. Bottom-up volume modeling triangulated against top-down macroeconomic indicators to ensure segmentation coherence.
Calibration against historical capacity utilization rates and feedstock cost trajectories shaped projections across the analysis window. Segmentation dimensions included product grade tier, end-use industry vertical, and regional regulatory cluster. CAGRs were derived from regression analysis of shipment volumes against downstream application growth curves, with specific inputs for waterborne coating transition velocity and PFAS substitution timelines.
Practitioners should monitor REACH aquatic toxicity reclassifications and EPA FIFRA registration backlog durations for early signals of supply-side consolidation. Forecasts reflect assumptions about propylene feedstock stability and renewable alcohol cost parity. Quarterly review of Indian CDSCO enforcement patterns and EU Green Deal carbon intensity benchmark revisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Ethylene Diamine Tetra Acetic Acid (EDTA) Market
Chemical Intermediates
Bromate Substitute Market
Chemical Intermediates
Grignard Reagents Market
Chemical Intermediates
Preformulation Intermediates Market
Chemical Intermediates
Global Glycinates Market
Chemical Intermediates
Natural Chelating Agents Market
Chemical Intermediates
9-Decanoic Acid Methyl Ester Market
Chemical Intermediates
Japan Formic Acid Market
Chemical Intermediates
3-Chloropropionyl Chloride Market
Chemical Intermediates
Ethylene Urea Market
Chemical Intermediates
Global Chemical Intermediates Market
Chemical Intermediates
Molybdenum Disulfide (MoS2) Market
Chemical Intermediates
Cytosine Market
Chemical Intermediates
1, 3, 5-Triazine Market
Chemical Intermediates
Carboxylic Acid Chlorides Market
Chemical Intermediates
Refinery Process Chemicals Market