
 API Intermediate Market | 2026-2036
API Intermediate Market Size, Share, and Industry Trends Forecast 2026-2036
API Intermediate Market Analysis
Biopharmaceutical contract developers is unwinding traditional merchant purchasing patterns as sponsor companies internalize early-stage chemistry. Lonza Group AG leverages its Swiss manufacturing network to anchor high-potency intermediate production for oncology programs. WuXi AppTec Co., Ltd. competes through integrated discovery-to-commercial platforms spanning China and the United States. Divi's Laboratories Ltd. dominates bulk intermediate volumes with backward integration into key starting materials.
API intermediates are chemical compounds or biological substances that undergo further molecular transformation to become active pharmaceutical ingredients, typically requiring purity thresholds above 99.5% and compliance with ICH Q7 good manufacturing practice guidelines. These materials serve as the structural backbone for finished drug substances across small-molecule, peptide, and oligonucleotide platforms. REST-based intermediate exchange protocols now lead technology integration between sponsor and contract manufacturing organizations, while GraphQL adoption is accelerating among biotech startups seeking real-time supply chain visibility. Hybrid cloud deployment models capture the fastest expansion as manufacturers balance intellectual property protection with multi-site collaboration needs.
FDA enforces ICH Q11 guidelines on starting material designation, while EMA's updated GMP Annex 1 imposes stricter contamination controls on intermediate handling facilities. China's NMPA aligns with PIC/S standards through revised drug substance registration rules that elevate documentation burdens for imported intermediates. Stakeholders must monitor regulatory divergence between FDA's risk-based approach and EMA's prescriptive quality thresholds when selecting multi-regional manufacturing partners.
Market Dynamics
Biopharmaceutical sponsors are internalizing early-stage chemistry capabilities while simultaneously outsourcing late-stage intermediate manufacturing, creating a bifurcated procurement structure that rewards contract manufacturers with integrated regulatory dossier expertise.
Growth Catalysts
- FDA ICH Q11 Enforcement:Stricter starting material designation requirements compel sponsors to source intermediates from manufacturers with validated quality systems, concentrating demand among audit-ready suppliers.
- Oncology Pipeline Expansion:High-potency intermediate demand accelerates as antibody-drug conjugates and targeted small molecules advance through clinical trials, requiring specialized containment infrastructure.
- India CDSCO Alignment:Domestic registration rules harmonizing with PIC/S standards enable Indian manufacturers to serve EU and North American sponsors without duplicate facility inspections.
Market Restraints
- Starting Material Volatility:Petrochemical feedstock price swings compress margins for commodity intermediate producers lacking long-term offtake agreements with API manufacturers.
- China Supply Concentration:Dependence on Zhejiang and Jiangsu province hubs for key building blocks exposes sponsors to regional environmental enforcement actions and shipping disruptions.
- Legacy Batch Limitations:Traditional stirred-tank chemistry struggles to deliver the throughput and purity consistency demanded by continuous manufacturing transitions in sponsor facilities.
Strategic Opportunities
- Brazil ANVISA Localization:Underdeveloped domestic intermediate capacity creates first-mover advantages for manufacturers establishing local production to serve Latin American generic drug growth.
- Peptide-Oligonucleotide Convergence:Hybrid synthetic modalities require intermediates bridging solid-phase and solution-phase chemistries, opening specialized production niches.
- EU Green Deal Chemistry:Solvent recovery mandates and renewable feedstock incentives favor intermediate producers with demonstrated process mass intensity improvements.
Industry Challenges
- Analytical Talent Scarcity:Chromatography and mass spectrometry specialists capable of validating impurity profiles per ICH Q3A guidelines command premium compensation, constraining quality team expansion.
- Legacy ERP Integration:Sponsor demand for real-time inventory visibility via REST APIs clashes with decades-old manufacturing execution systems at established intermediate facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | API Intermediate Market |
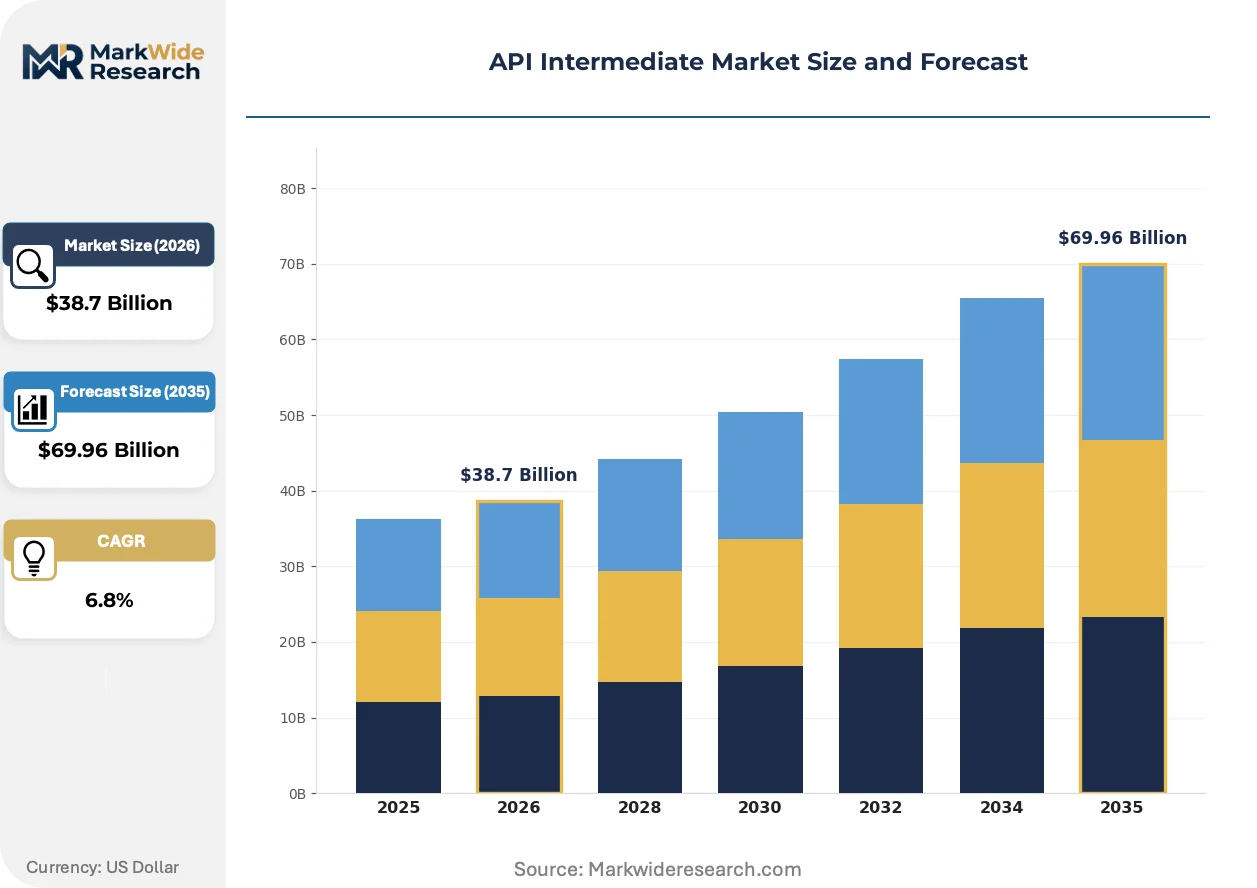
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Technology Type: REST, SOAP, GraphQL, gRPC Integration Level: Full Integration, Partial Integration, API Gateway, Middleware End User Segment: Enterprises, Startups, Government, Nonprofit |
| Companies Covered | Cambrex Corporation, Divi’s Laboratories Ltd., BASF SE, Siegfried Holding AG, Chiracon GmbH, Lonza Group AG, Sanofi S.A., Thermo Fisher Scientific Inc., WuXi AppTec Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
API Intermediate Market Emerging Trajectories
Continuous flow chemistry and biocatalysis are rewriting process economics for complex intermediate synthesis, while regulatory data integrity mandates force digitization of batch records and analytical workflows across the supply base.
Flow chemistry platforms are displacing conventional batch reactors for hazardous nitration and hydrogenation steps previously requiring extensive containment infrastructure. Mid-sized contract manufacturers in Switzerland and Singapore are retrofitting multi-purpose plants with skid-mounted continuous units to capture oncology intermediate volumes. This technology compression is enabling geographic diversification away from concentrated Asian supply zones without sacrificing unit economics.
EMA's updated GMP Annex 1 imposes mandatory contamination control strategies on all intermediate handling facilities, including rigorous environmental monitoring and closed-system requirements. Manufacturers serving European sponsors must now validate barrier isolator technology or restricted access barrier systems for potent compound operations. The sterile manufacturing segment faces the steepest compliance timeline, with facilities in Germany and Italy accelerating capital programs to meet enforcement deadlines.
Long-term offtake agreements with volume commitments are displacing spot-market purchasing for critical regulatory starting materials. Sponsor quality organizations now mandate locked supplier lists eighteen to twenty-four months before commercial launch, freezing intermediate procurement decisions early in development. This pattern is most pronounced in the United States, where FDA pre-approval inspection schedules drive immovable sourcing timelines for New Drug Application filings.
API Intermediate Market Segmentation
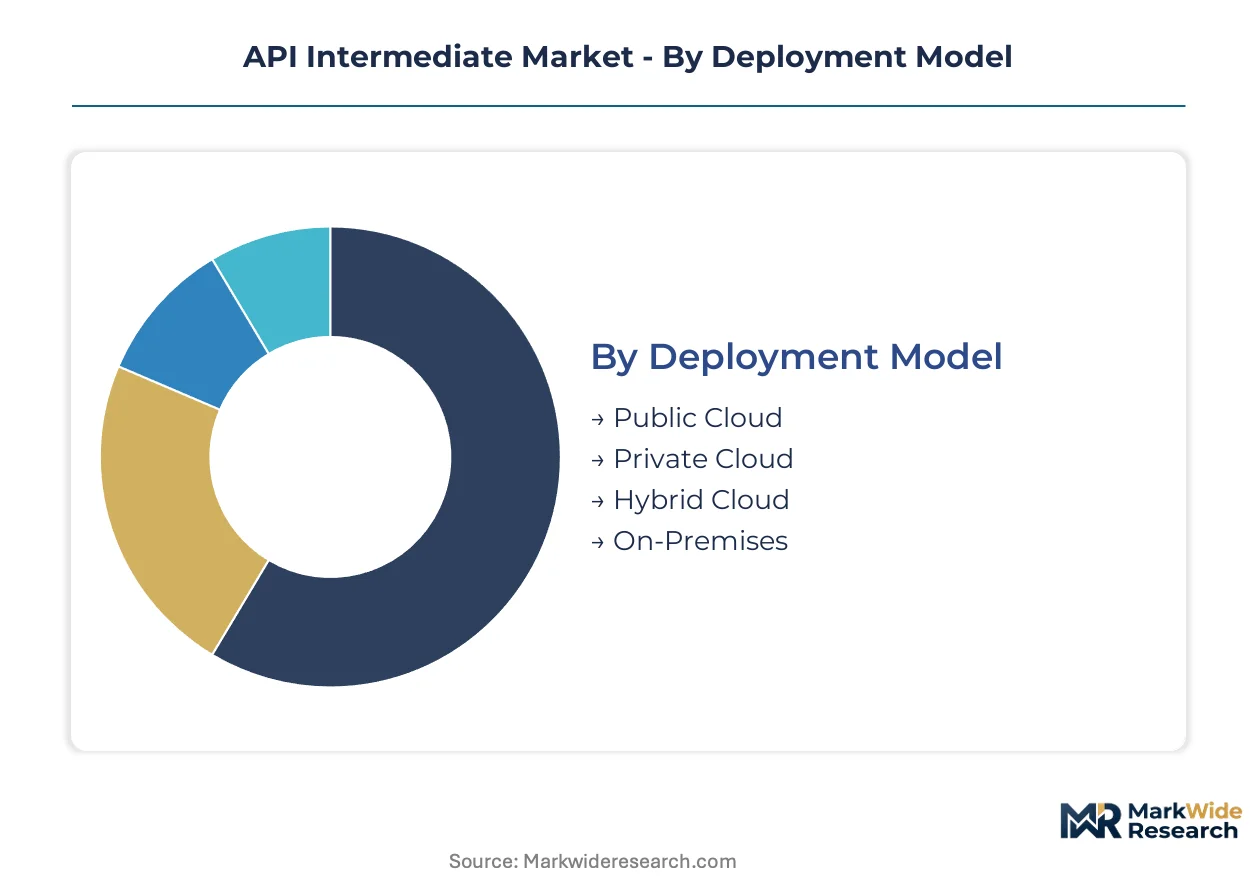
API Intermediate procurement patterns fragment sharply across integration architectures and buyer sophistication tiers. Deployment choices directly determine regulatory audit complexity and intellectual property exposure for sponsor-manufacturer data exchange.
Deployment Model:
Hybrid Cloud substitutes most aggressively against legacy On-Premises installations as manufacturers seek elastic capacity without surrendering batch record custody to third-party infrastructure.
- Public Cloud:Multi-tenant infrastructure delivers scalable compute for non-critical inventory dashboards and supplier scorecarding. Indian and Chinese contract manufacturers favor this tier for cost-sensitive sponsor engagements where data residency requirements remain permissive.
- Private Cloud:Single-tenant environments host validated manufacturing execution systems requiring 21 CFR Part 11 compliance. European sponsors mandate this architecture for high-potency intermediate programs where audit trails must remain within jurisdictional boundaries.
- Hybrid Cloud:Split architectures isolate proprietary synthesis routes on-premises while pushing demand forecasting to elastic cloud nodes. Lonza and WuXi AppTec deployments favor this model to balance sponsor IP protection with multi-site collaboration efficiency.
- On-Premises:Legacy server farms persist at established facilities with decades-old ERP investments. CDSCO-aligned Indian manufacturers face the steepest modernization pressure as sponsor demands for REST API connectivity clash with rigid legacy stacks.
Hybrid Cloud anchors the volume base while Public Cloud gains share at the steepest rate among emerging-market contract manufacturers.
Technology Type:
Cost tier separation runs deepest here, with GraphQL implementations commanding premium integration fees against commoditized SOAP legacy.
- REST:Stateless HTTP-based protocols dominate sponsor-CMO data exchange for inventory visibility and quality document transfer. FDA-regulated sponsors standardize on REST for its audit simplicity and broad middleware compatibility across multi-vendor supply chains.
- SOAP:XML-heavy messaging persists in validated environments where WS-Security standards satisfy EMA Annex 11 electronic record requirements. German and Swiss facilities maintain SOAP stacks for backward compatibility with decade-old quality management systems.
- GraphQL:Query-flexible architectures enable real-time intermediate tracking across fragmented supplier networks. Biotech startups in Boston and San Francisco drive adoption, demanding granular lot-level visibility without multiple API round-trips.
- gRPC:High-performance binary protocols serve high-frequency analytical data streaming from chromatography systems to sponsor quality dashboards. Singapore-based continuous manufacturing hubs pilot this technology for sub-second impurity alert transmission.
REST anchors the volume base while GraphQL climbs the fastest among venture-backed drug developers.
Integration Level:
Application maturity separates segments, with Full Integration reserved for late-phase commercial programs and Middleware bridging incompatible legacy systems.
- Full Integration:Direct ERP-to-ERP data pipes synchronize batch records, release specifications, and regulatory dossiers between sponsor and manufacturer. This tier locks in eighteen-to-twenty-four-month supplier commitments ahead of FDA pre-approval inspections.
- Partial Integration:Limited data feeds connect quality systems while financial and procurement modules remain siloed. Mid-sized CMOs in Italy and Spain offer this tier to balance sponsor transparency demands against internal system replacement costs.
- API Gateway:Centralized authentication and rate-limiting layers manage multiple supplier connections without point-to-point system overhauls. Sponsor quality organizations deploy gateways to maintain audit trails across twenty-plus intermediate vendors.
- Middleware:Translation layers bridge SOAP legacy systems to REST-native sponsor platforms. This segment expands fastest where established European manufacturers face pressure to connect with cloud-native biotech sponsors.
Partial Integration anchors the volume base while API Gateway expands most quickly as sponsor supplier lists lengthen.
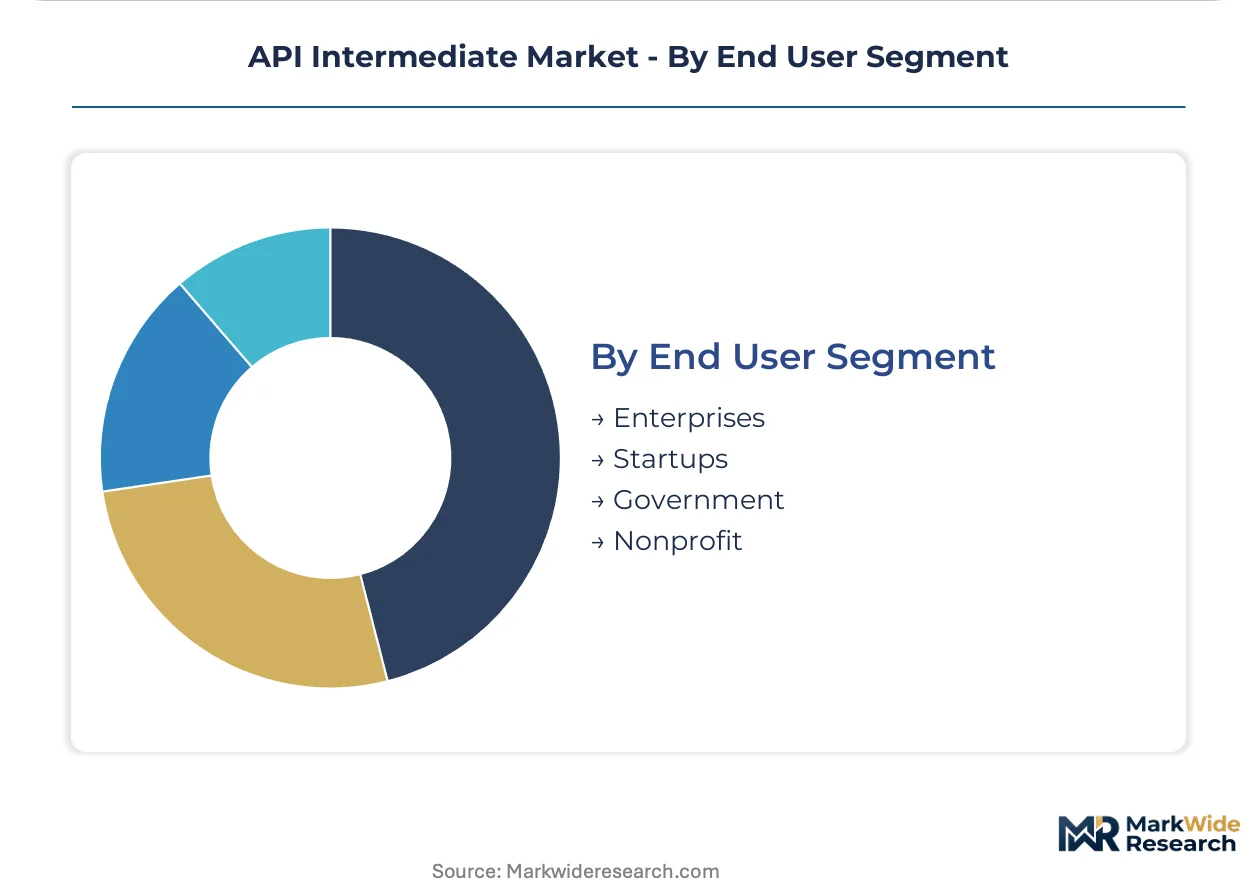
End User Segment:
Customer type determines pricing power and contract duration, with Enterprises extracting volume discounts unavailable to capital-constrained Startups.
- Enterprises:Multinational pharmaceutical sponsors demand locked supplier lists, dedicated quality agreements, and validated electronic data interchange. Their procurement teams mandate ICH Q7-compliant manufacturers with established FDA inspection histories.
- Startups:Venture-funded biotechs prioritize speed-to-IND over integration depth, accepting spreadsheet-based data exchange for early-phase intermediates. GraphQL adoption concentrates here as technical teams override procurement conservatism.
- Government:National stockpile programs and defense-related pharmaceutical procurement favor On-Premises deployment with air-gapped security. India's PLI scheme intermediates and US BARDA-funded manufacturing fall within this segment.
- Nonprofit:Global health organizations source essential medicine intermediates through pre-negotiated supplier panels with transparent cost-plus pricing. This segment drives standardization around REST APIs to minimize integration overhead across fragmented grant-funded supply chains.
Enterprises anchor the volume base while Startups gain share at the steepest rate as oncology pipeline expansion accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North American and European drug sponsors source the majority of high-potency intermediates from contract manufacturers in India and China. Indian CDSCO alignment with PIC/S standards accelerates facility qualification for export markets. Chinese environmental enforcement in Zhejiang and Jiangsu provinces periodically disrupts key building block availability.
United States
FDA pre-approval inspection schedules lock intermediate procurement decisions eighteen to twenty-four months before commercial launch. Sponsors mandate ICH Q7-compliant manufacturers with established FDA inspection histories for oncology programs. Greater Boston and San Francisco biotech clusters drive GraphQL adoption for real-time supply chain visibility.
Germany
EMA GMP Annex 1 contamination control mandates accelerate capital programs at facilities in North Rhine-Westphalia. German manufacturers maintain SOAP legacy stacks for backward compatibility with decade-old quality management systems. Bavarian chemical parks host retrofitting programs for continuous flow chemistry platforms.
Switzerland
Swissmedic oversight of high-potency compound operations reinforces demand for specialized containment infrastructure. Basel-based pharmaceutical sponsors extract volume discounts through locked supplier lists and dedicated quality agreements. Lonza leverages its Swiss manufacturing network to anchor oncology intermediate production.
India
CDSCO harmonization with PIC/S standards enables Indian manufacturers to serve EU and North American sponsors without duplicate facility inspections. Maharashtra and Gujarat house integrated API-to-intermediate hubs with backward integration into key starting materials. Divi's Laboratories dominates bulk intermediate volumes from these clusters.
China
NMPA alignment with international standards elevates documentation burdens for imported intermediates while tightening domestic registration rules. Zhejiang and Jiangsu province concentration exposes sponsors to regional environmental enforcement actions. WuXi AppTec competes through integrated discovery-to-commercial platforms spanning China and the United States.
API Intermediate Market Vendor Landscape
Player mix skews toward integrated contract manufacturers with validated regulatory dossier expertise. Tiered competition separates audit-ready suppliers serving commercial-stage sponsors from spreadsheet-dependent vendors supporting early-phase programs. Two archetypes dominate: Swiss and German specialists in high-potency containment, and Indian and Chinese scale players with backward-integrated starting material control. Competitive moves center on long-term offtake agreements with volume commitments and continuous flow chemistry retrofitting for hazardous synthesis steps.
Within the high-potency specialist tier, Lonza Group AG and Siegfried Holding AG represent Swiss-anchored containment expertise for oncology programs. Divi's Laboratories Ltd. and WuXi AppTec Co., Ltd. exemplify Asian scale players with integrated platforms spanning discovery through commercial manufacturing. Cambrex Corporation occupies a position among North American contract developers unwinding traditional merchant purchasing patterns. These named entities anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| Cambrex Corporation |
| Divi's Laboratories Ltd. |
| BASF SE |
| Siegfried Holding AG |
| Chiracon GmbH |
| Lonza Group AG |
| Sanofi S.A. |
| Thermo Fisher Scientific Inc. |
| WuXi AppTec Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Continuous flow chemistry retrofits are displacing conventional batch reactors for hazardous nitration and hydrogenation steps, simultaneously shifting production geography toward Swiss and Singaporean multi-purpose plants and compressing unit economics for high-potency intermediates previously concentrated in Asian manufacturing zones.
Pricing Analysis
Long-term offtake agreements with petrochemical feedstock indexation anchor contract pricing for regulatory starting materials, locking volume commitments eighteen to twenty-four months ahead of commercial launch. Three-tier pricing structure across premium containment-grade, standard GMP-compliant, and economy merchant-market levels separates audit-ready suppliers from spreadsheet-dependent vendors. Cost compression in commodity intermediate tiers is intensifying because petrochemical feedstock volatility erodes margins for producers lacking backward integration into key starting materials. Early-phase biotech startups exhibit highest price sensitivity, accepting higher per-unit costs for flexibility, while multinational pharmaceutical sponsors prioritize locked supplier lists over unit price negotiation.
Supply Chain Analysis
Eighteen-to-twenty-four-month inventory lead times for critical regulatory starting materials now precede FDA pre-approval inspection schedules, freezing procurement decisions early in development cycles. Manufacturing concentrates in India, China, and Switzerland, with Zhejiang and Jiangsu province hubs in China exposing sponsors to regional environmental enforcement disruptions. Supply chains draw from petrochemical feedstocks, specialized containment equipment, and chromatography-grade solvents. Single-source vulnerability runs through concentrated Chinese building block production. Distribution runs through contract manufacturing organization direct-to-sponsor channels with validated electronic data interchange for quality document transfer.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
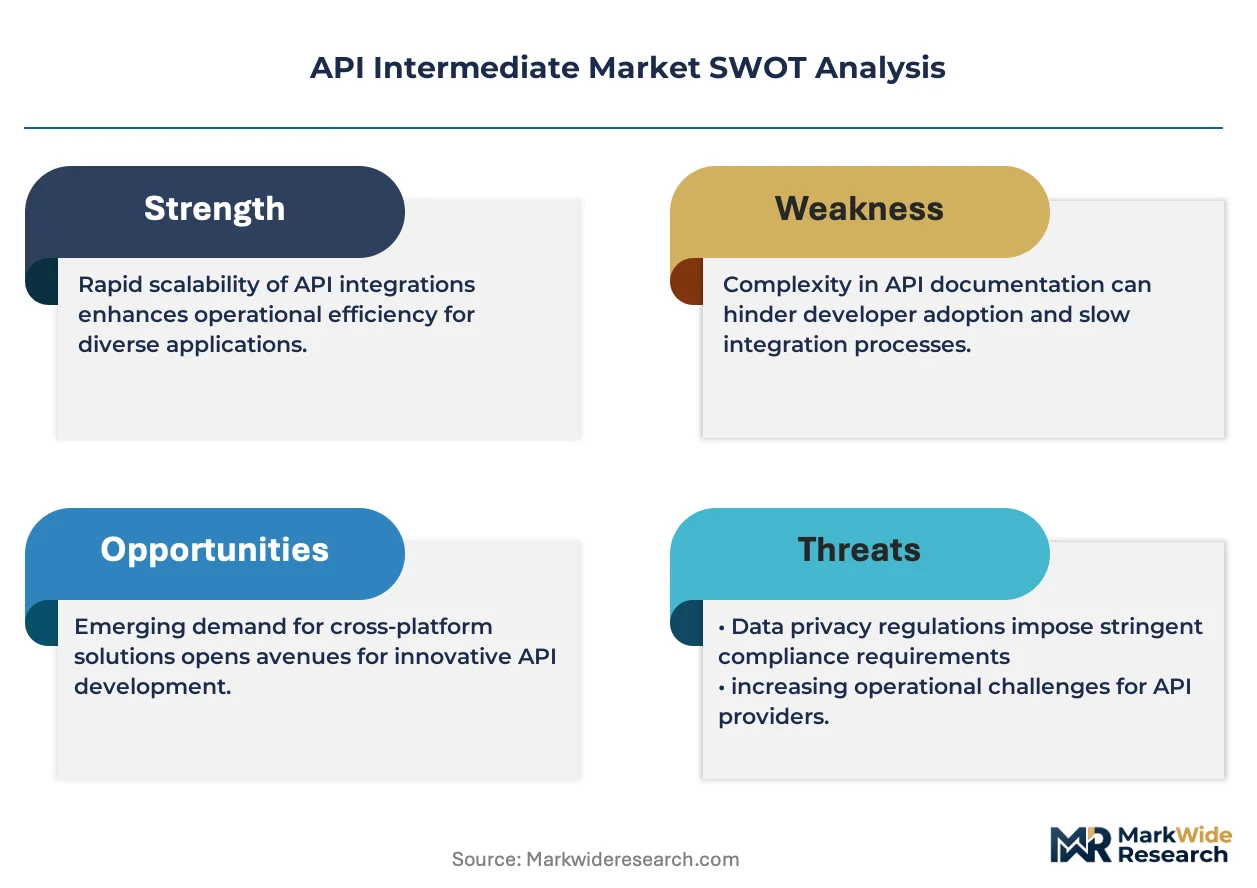
Biocatalysis platforms threaten incumbent batch chemistry positions as enzymatic routes rewrite process economics for complex chiral intermediates, forcing traditional manufacturers to defend substitution or risk volume erosion to specialized bioprocess competitors.
For Market Incumbents: Consolidate regulatory dossier expertise through dedicated quality agreements and locked supplier list positioning ahead of FDA pre-approval inspection windows. Backward integration into key starting materials anchors margin control against petrochemical feedstock volatility. Containment infrastructure investment for high-potency oncology programs defends against Swiss and German specialist encroachment. For New Entrants and Emerging Players: CDSCO-PIC/S alignment fast-tracks facility qualification for Indian manufacturers seeking EU and North American sponsor relationships without duplicate inspection burdens. Brazil ANVISA localization offers first-mover advantages in Latin American generic drug growth corridors. Peptide-oligonucleotide hybrid modalities present penetrable specialized production niches bridging solid-phase and solution-phase chemistries. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Indian and Chinese contract manufacturers possessing integrated API-to-intermediate platforms but lacking global regulatory dossier depth. Five-to-ten-year viability hinges on continuous flow chemistry retrofit completion and EMA GMP Annex 1 contamination control compliance. Watch for locked supplier list announcements from Boston and San Francisco biotech clusters as inflection indicators for intermediate demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Chemistry Retrofit | Skid-mounted units enable hazardous synthesis without extensive containment infrastructure investment. |
| Backward Integration into Starting Materials | Captive supply of key building blocks insulates margins from petrochemical feedstock price swings. |
| CDSCO-PIC/S Alignment Certification | Indian manufacturers qualify for EU and North American sponsor engagements without duplicate inspections. |
| Long-term Offtake Agreement Structuring | Volume commitments lock procurement decisions eighteen to twenty-four months before commercial launch. |
| Hybrid Cloud Deployment Migration | Lonza and WuXi AppTec architectures balance sponsor IP protection with multi-site collaboration efficiency. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interviews with drug development executives, regulatory affairs leads, contract manufacturing procurement managers, and quality assurance directors. Secondary validation drew from FDA filings, EMA submissions, CDSCO registration databases, and ICH Q7 audit inspection records. Bottom-up volume modeling triangulated against top-down market sizing from customs trade data and SEC 10-K manufacturing disclosures.
Across the analysis window, the forecast framework modeled deployment architecture, integration level, technology protocol, and end-user segment dimensions alongside regional regulatory cluster patterns. CAGRs were derived from weighted average growth assumptions across segment trajectories. Continuous manufacturing transition rates and EMA GMP Annex 1 compliance timelines served as pharmaceutical-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside ICH Q11 starting material designation stability or sustained CDSCO-PIC/S harmonization would require recalibration. Forecasts reflect documented assumptions regarding sponsor internalization trends and environmental enforcement intensity in Chinese manufacturing zones. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Methoxypropylamine (MOPA) Market
Chemical Intermediates
Pharmaceutical Intermediates Market
Chemical Intermediates
Ph Controlling Agents Market
Chemical Intermediates
Iodoacetonitrile Market
Chemical Intermediates
Leather Chemicals Market
Chemical Intermediates
Metaphenoxy Benzaldehyde (MPBD) Market
Chemical Intermediates
Nutrition Chemicals Market
Chemical Intermediates
Grignard Reagents Market
Chemical Intermediates
Global Textile Finishing Chemicals Market
Chemical Intermediates
Global Chromatography Reagents Market
Chemical Intermediates
Tetrahydrocurcumin Reagent Market
Chemical Intermediates
Global Chemical Intermediates Market
Chemical Intermediates
Carboxylic Acid Chlorides Market
Chemical Intermediates
US Acids Market
Chemical Intermediates
Glycidyl Methacrylate Market
Chemical Intermediates
Reagent Bottle Market