
 Global Etoricoxib Intermediate Market | 2026-2036
Global Etoricoxib Intermediate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Etoricoxib Intermediate Market Analysis
Buyer concentration among pharmaceutical companies is consolidating as large formulation labs and contract manufacturers narrow supplier lists to secure compliant etoricoxib intermediate streams. Sun Pharmaceutical anchors Indian API manufacturing with backward integration into key precursor synthesis. Bayer competes through European REACH-certified production networks that sustain quality premiums across regulated markets.
Etoricoxib intermediate denotes the synthetic precursors and active pharmaceutical ingredient (API) building blocks used in manufacturing the selective COX-2 inhibitor, typically requiring chiral purity above 99.5% and controlled crystallization to meet pharmacopeial standards. The API segment dominates value capture due to stringent regulatory filing requirements and validation costs that lock in qualified suppliers. Advanced intermediates represent the fastest-expanding category as contract manufacturers outsource later-stage synthesis to reduce capital intensity.
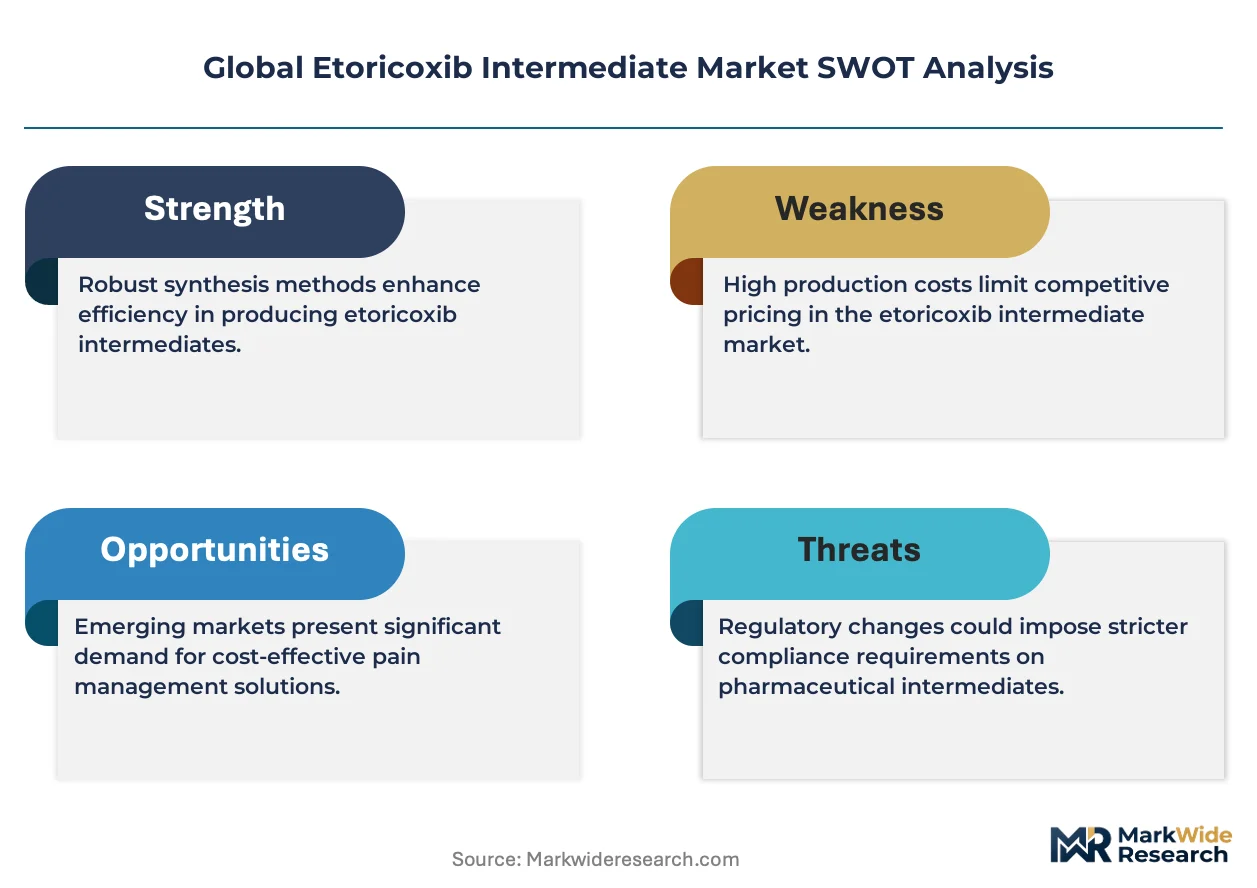
FDA, EMA, and REACH frameworks collectively shape market access through impurity profiling mandates and environmental release controls that filter subscale producers. India's CDSCO and China's NMPA impose parallel certification burdens that extend qualification timelines for cross-border shipments. Stakeholders must monitor evolving ICH Q3D elemental impurity guidelines and carbon-intensive process audits that threaten cost structures for uncertified suppliers.
Market Dynamics
Pharmaceutical contract manufacturers are consolidating supplier relationships to secure REACH-certified and FDA-validated etoricoxib intermediate streams, compressing qualification timelines while raising purity thresholds above 99.5% chiral standards.
Growth Catalysts
- REACH compliance mandates:European ECHA enforcement is filtering subscale producers and concentrating procurement among certified API manufacturers.
- India:CDSCO-aligned production clusters in Mumbai and Hyderabad are expanding backward integration into precursor synthesis to capture value from formulation labs.
- Continuous flow chemistry:Advanced manufacturing technologies are reducing solvent waste and accelerating batch validation for high-purity intermediates.
Market Restraints
- Acetonitrile and palladium catalyst volatility:Input cost swings for specialty solvents and transition metal catalysts compress margin structures for non-integrated producers.
- Indian supply concentration:Overreliance on Mumbai-Thane API corridors creates geographic vulnerability to monsoon logistics disruptions and port congestion.
- Genotoxic impurity profiling:ICH M7 guideline enforcement requires expensive analytical infrastructure that excludes smaller synthesis houses.
Strategic Opportunities
- Brazil:ANVISA's accelerating NSAID registration pathways open import channels for pre-qualified intermediate suppliers.
- Biocatalytic resolution:Enzymatic chiral separation technologies are converging with traditional chemical synthesis to reduce step counts and solvent intensity.
- Direct-to-CDMO contracting:Bypassing traditional distributor networks allows intermediate producers to capture service premiums from European formulation labs.
Industry Challenges
- Analytical chemist scarcity:ICP-MS and NMR spectroscopy expertise gaps delay impurity method development and regulatory submission timelines.
- Multi-site inspection coordination:Simultaneous FDA, EMA, and CDSCO audits strain quality assurance bandwidth and documentation systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Etoricoxib Intermediate Market |
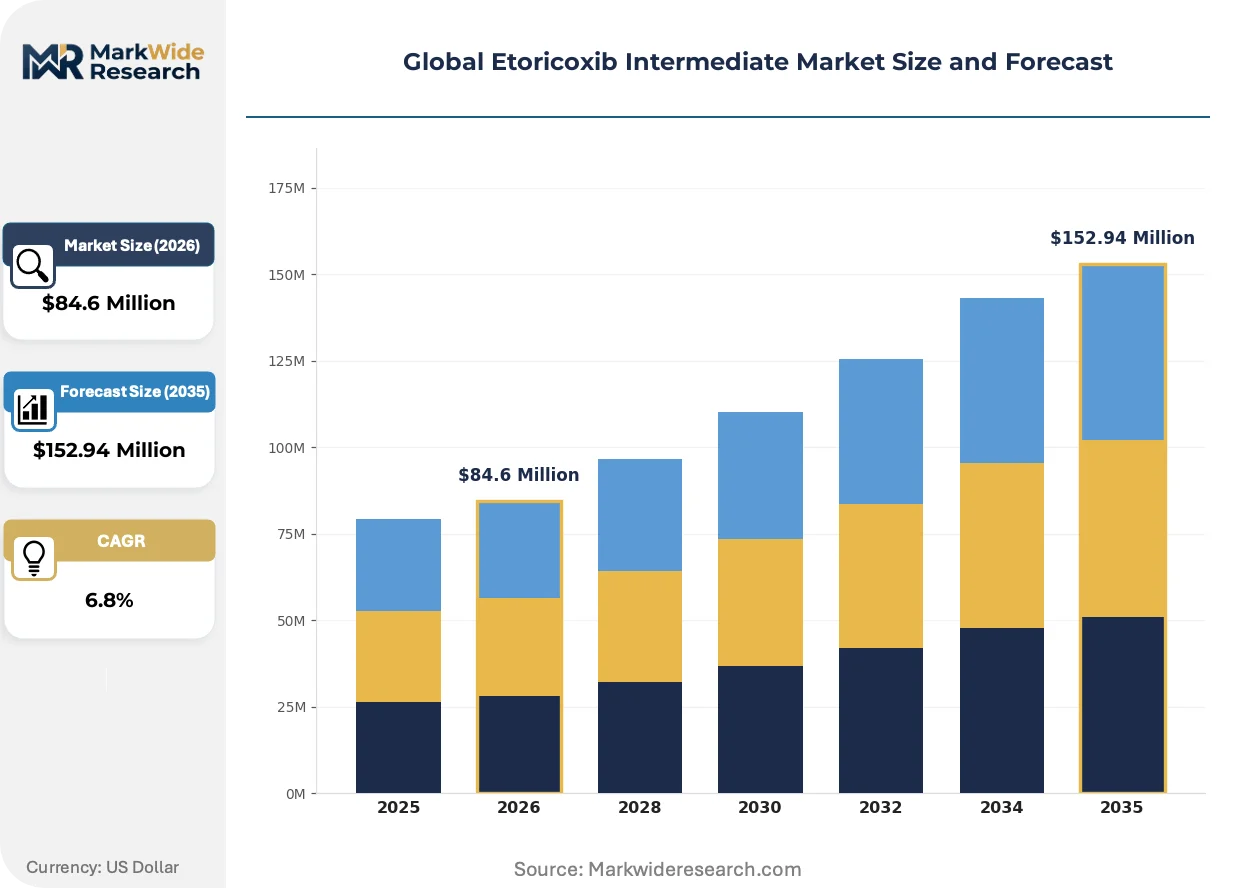
| Market Size in 2026 | $84.6 Million |
| Market Size in 2035 | $152.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: API, Advanced Intermediates, Raw Materials, Reagents Application: Pharmaceuticals, Biotechnology, Research, Chemical Manufacturing End User: Formulation Labs, Contract Manufacturers, Research Institutions, Pharmaceutical Companies Distribution Channel: Direct Sales, Online Marketplaces, Wholesalers, Distributors |
| Companies Covered | Sun Pharmaceutical, Abbott, Bayer, GlaxoSmithKline, Novacap, Merck, Kopran, Perrigo, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Etoricoxib Intermediate Market Emerging Trajectories
Process intensification and regulatory digitization are compressing development cycles for etoricoxib intermediates while chiral manufacturing technologies unlock new purity benchmarks.
Continuous manufacturing systems are expanding into late-stage intermediate production, replacing batch reactors with plug-flow architectures that halve solvent volumes. European CDMOs are piloting these installations to meet EMAS environmental audit requirements. The technology is expanding into cost-sensitive Indian producers seeking REACH certification without capital-heavy greenfield builds.
EMA's revised ICH Q3D elemental impurity guidelines are forcing metal catalyst residue testing at parts-per-billion detection limits. Synthesis houses must retrofit ICP-MS capability or outsource analytics to certified contract labs. API manufacturers in Germany and Switzerland are absorbing these costs through premium pricing to European formulation clients.
Long-term offtake agreements are displacing spot market transactions as Bayer and Sun Pharmaceutical lock in three-to-five-year intermediate supply contracts. CDMO procurement teams are trading price flexibility for supply security and audit co-certification. This behavioral shift is most visible in India, where backward-integrated API producers are capturing captive demand from multinational formulation networks.
Global Etoricoxib Intermediate Market Segmentation
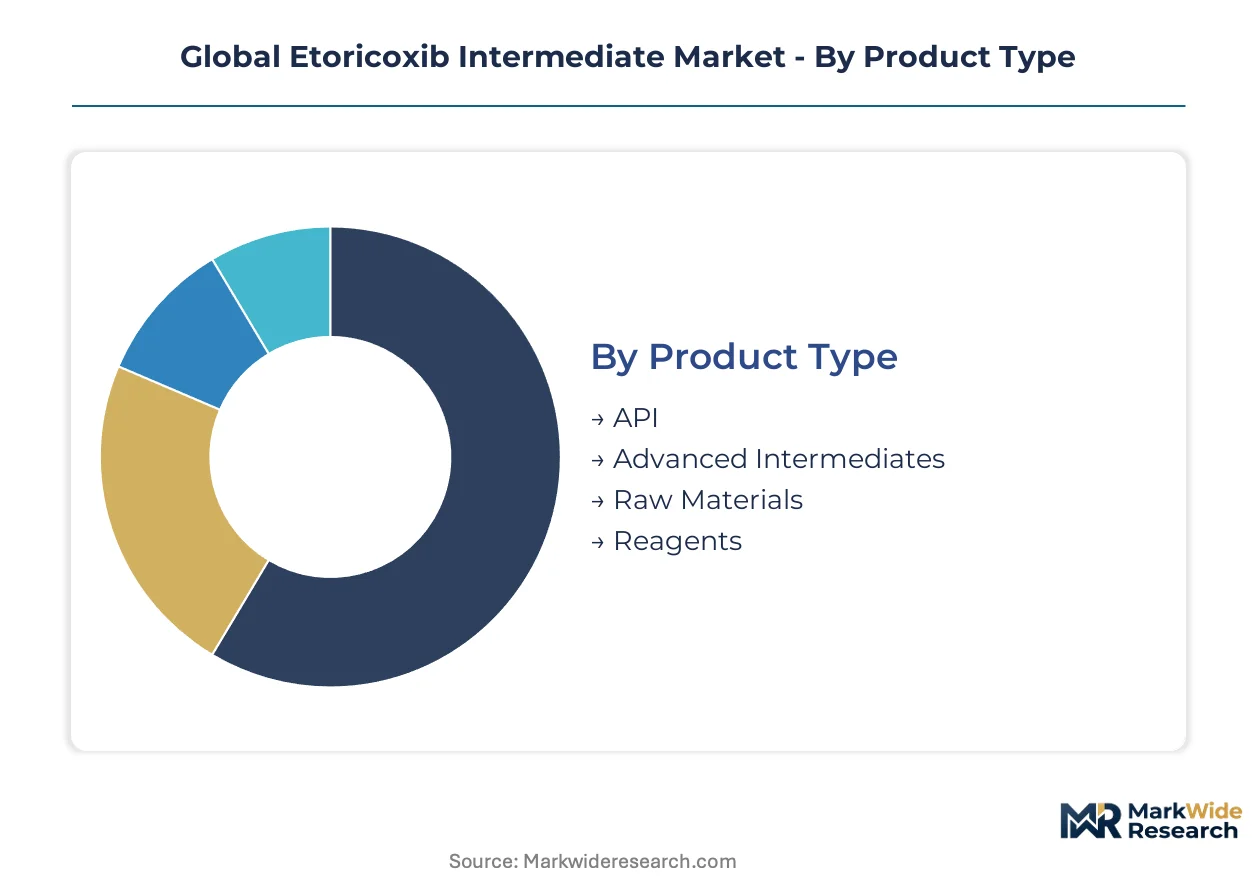
Etoricoxib intermediate supply chains stratify sharply by product maturity and regulatory burden. Procurement teams segment suppliers based on validation depth, chiral purity thresholds, and backward integration into precursor synthesis.
Product Type:
Supply concentration tilts heavily toward validated API streams as contract manufacturers outsource synthesis steps to reduce capital intensity.
- API:Finished active pharmaceutical ingredient meeting pharmacopeial monographs with chiral purity above 99.5%. CDSCO-aligned production clusters in Mumbai and Hyderabad anchor global supply for multinational formulation networks.
- Advanced Intermediates:Late-stage synthetic precursors requiring controlled crystallization and impurity profiling. European CDMOs are expanding procurement of these streams to compress development timelines while maintaining REACH certification.
- Raw Materials:Early-stage chemical inputs including acetonitrile solvents and palladium catalysts.
- Reagents:Specialty chemicals employed in chiral resolution and functional group transformations.
API absorbs the bulk of installed capacity; advanced intermediates are expanding most quickly.
Application:
Cost tier differentiation separates mass-market NSAID production from high-complexity biologics conjugation.
- Pharmaceuticals:Dominant consumption channel for etoricoxib intermediates in selective COX-2 inhibitor synthesis. FDA and EMA filing requirements lock in qualified suppliers through expensive validation protocols.
- Biotechnology:Emerging demand for chiral building blocks in antibody-drug conjugate linker chemistry. Swiss and German CDMOs are piloting biocatalytic resolution to reduce solvent intensity in these applications.
- Research:Small-volume procurement for method development and impurity reference standard synthesis.
- Chemical Manufacturing:Industrial-scale offtake for process development and scale-up validation.
Pharmaceuticals commands the dominant cost tier; biotechnology is climbing the fastest.
End User:
Customer type determines procurement modality, with large formulation labs trading price flexibility for multi-year supply security.
- Formulation Labs:Primary demand anchor for high-purity etoricoxib API. Sun Pharmaceutical and Bayer have locked in three-to-five-year offtake agreements with intermediate producers to secure audit co-certification.
- Contract Manufacturers:Fastest-expanding customer segment as pharmaceutical companies outsource NSAID synthesis. Indian CDMOs in the Mumbai-Thane corridor are backward-integrating into precursor production to capture value.
- Research Institutions:Fragmented demand for analytical standards and method development materials.
- Pharmaceutical Companies:Integrated producers maintaining captive intermediate supply for proprietary formulations.
Formulation labs absorb the bulk of validated capacity; contract manufacturers are gaining share fastest.
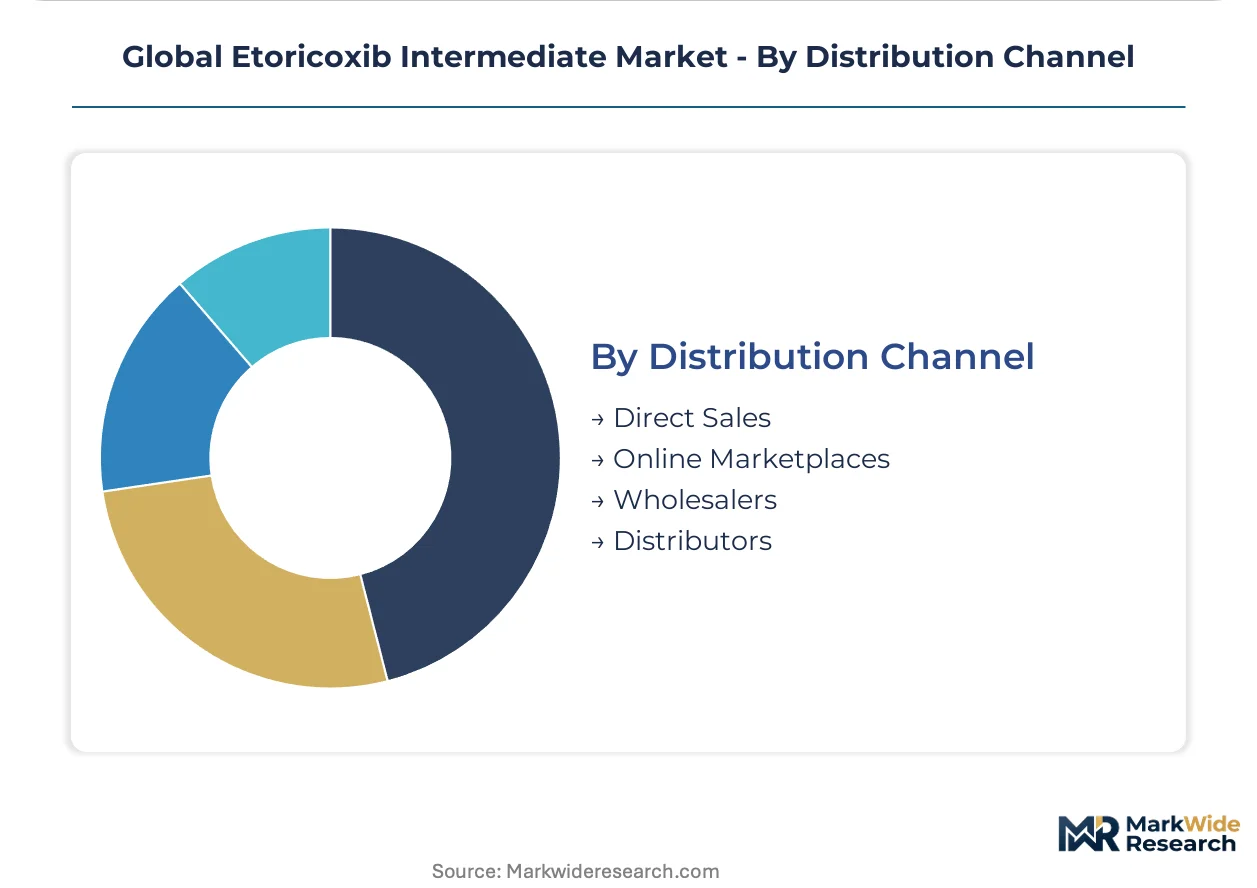
Distribution Channel:
Margin compression in traditional distributor networks is forcing intermediate producers toward direct engagement with qualified buyers.
- Direct Sales:Preferred channel for REACH-certified and FDA-validated etoricoxib streams. Long-term offtake agreements displace spot transactions as producers capture service premiums from European formulation labs.
- Online Marketplaces:Limited to raw materials and reagents where specification standardization reduces qualification burden.
- Wholesalers:Intermediary role for non-regulated research-grade materials.
- Distributors:Traditional channel for small-volume procurement by research institutions and regional pharmaceutical companies.
Direct sales commands the steepest margin structure; online marketplaces are expanding most quickly in the raw materials tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates the bulk of etoricoxib intermediate procurement as Sun Pharmaceutical and Kopran anchor API production clusters in Mumbai and Hyderabad. Contract manufacturers in these corridors are backward-integrating into precursor synthesis to capture value from multinational formulation networks.
India
CDSCO-aligned production clusters in Mumbai and Hyderabad dominate global etoricoxib intermediate supply for selective COX-2 inhibitor synthesis. The country's national pharmaceutical regulator enforces impurity profiling mandates that extend qualification timelines for cross-border shipments. Mumbai-Thane API corridors face geographic vulnerability to monsoon logistics disruptions and port congestion.
Germany
Bayer operates REACH-certified production networks that sustain quality premiums across regulated European markets. ECHA enforcement filters subscale producers and concentrates procurement among certified API manufacturers. Bavarian and North Rhine-Westphalian CDMOs pilot continuous manufacturing systems to meet EMAS environmental audit requirements.
United States
FDA purity standards tighten quality thresholds for etoricoxib intermediate import qualification. The agency's evolving ICH Q3D elemental impurity guidelines force metal catalyst residue testing at parts-per-billion detection limits. Greater Boston and New Jersey formulation labs lock in three-to-five-year offtake agreements with intermediate producers.
Switzerland
Swiss CDMOs pilot biocatalytic resolution technologies to reduce solvent intensity in chiral building block production. Swissmedic certification requirements lock in qualified suppliers through expensive validation protocols. Basel-Zurich pharmaceutical corridors absorb analytical infrastructure costs through premium pricing to European formulation clients.
Brazil
ANVISA's accelerating NSAID registration pathways open import channels for pre-qualified intermediate suppliers. The country's national pharmaceutical regulator imposes parallel certification burdens that extend qualification timelines. São Paulo pharmaceutical manufacturing clusters expand procurement of REACH-certified etoricoxib streams.
Global Etoricoxib Intermediate Market Vendor Landscape
Indian producers anchor the high-volume tier; European specialists hold the premium-certification segment. The vendor base stratifies sharply between REACH-validated CDMOs and cost-focused API houses serving emerging markets. Three archetypes dominate: backward-integrated pharmaceutical giants, dedicated intermediate specialists, and contract research manufacturing organizations. Capacity expansion and long-term offtake agreements constitute the dominant competitive moves.
Within the integrated pharmaceutical tier, Sun Pharmaceutical and Bayer exemplify divergent geographic strategies. Kopran occupies a position among India-based API specialists serving formulation networks. These three anchors represent the spectrum from captive supply to merchant market exposure.
| Leading Market Players |
|---|
| Sun Pharmaceutical |
| Abbott |
| Bayer |
| GlaxoSmithKline |
| Novacap |
| Merck |
| Kopran |
| Perrigo |
| Pfizer |
| Others |
Supply Flow & Price Mechanics
Multi-year offtake agreements from Bayer and Sun Pharmaceutical are compressing spot market liquidity and forcing intermediate producers to absorb certification costs upfront, which stratifies pricing across REACH-validated and non-certified supply tiers.
Pricing Analysis
Volume concentration among contract manufacturers splits margin capture between high-throughput API producers and specialized advanced intermediate houses. Three-tier pricing structure across REACH-certified premium, CDSCO-aligned standard, and uncertified economy levels reflects validation depth and chiral purity thresholds. Cost compression in the economy tier is intensifying because genotoxic impurity profiling mandates require expensive ICP-MS infrastructure. Research institutions and small synthesis houses exhibit highest price sensitivity, while European formulation labs absorb premiums for audit co-certification.
Supply Chain Analysis
Reverse-logistics flows for palladium catalyst recovery and solvent reclamation are tightening as EMAS environmental audits mandate closed-loop processing at German and Swiss CDMOs. Supply concentrates in India, Germany, and Switzerland, with Mumbai-Thane corridors feeding multinational formulation networks. The chain draws from acetonitrile solvents, palladium catalysts, and chiral resolution reagents. Single-source vulnerability in Indian monsoon corridors threatens just-in-time delivery to European REACH-certified facilities. Distribution runs through direct sales channels for validated intermediates and traditional distributors for research-grade materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified supplier scarcity is propping pricing power for REACH-certified and FDA-validated producers, as ICH Q3D elemental impurity guidelines and ICH M7 genotoxic profiling requirements filter subscale competitors from the approval pipeline.
For Market Incumbents: Deploy long-term offtake agreement structures to lock in formulation lab demand and preempt spot market erosion. Incumbents should deepen backward integration into precursor synthesis to capture value from contract manufacturers outsourcing late-stage steps, while investing in continuous flow chemistry to meet tightening EMAS solvent reduction mandates and defend margin position against biocatalytic resolution entrants. For New Entrants and Emerging Players: CDMO procurement teams represent the most accessible entry channel, particularly in Brazil where ANVISA's accelerating NSAID registration pathways create first-mover advantages for pre-qualified suppliers. Entrants should target biotechnology applications for antibody-drug conjugate linker chemistry, where Swiss and German pilot programs demonstrate unmet demand for enzymatic chiral separation, and pursue direct-to-CDMO contracting to bypass margin-stripping distributor networks. For Investors and Strategic Acquirers: The window for entry favors backward-integrated Indian API specialists with captive demand from multinational formulation networks. Acquisition targets should demonstrate CDSCO alignment plus progress toward REACH certification, with three-to-five-year offtake agreement visibility as the inflection signal indicating pricing power sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Certification Investment | Unlocks premium pricing to European formulation labs under ECHA enforcement. |
| Backward Integration into Precursor Synthesis | Captures value from contract manufacturers outsourcing late-stage steps in Mumbai-Hyderabad clusters. |
| Continuous Flow Chemistry Adoption | Reduces solvent volumes to meet EMAS environmental audit requirements. |
| Biocatalytic Resolution Piloting | Enables enzymatic chiral separation for antibody-drug conjugate applications. |
| Direct-to-CDMO Contracting | Bypasses distributor networks to capture service premiums from European buyers. |
Methodological Framework
Document review covered FDA filings, EMA submissions, CDSCO regulatory circulars, and REACH compliance databases, complemented by interviews with API manufacturing executives, regulatory affairs leads at contract manufacturers, pharmaceutical procurement managers, and analytical chemistry specialists. Secondary validation drew from customs trade data, SEC 10-K disclosures, and ICH guideline documentation. Bottom-up capacity assessments and top-down demand modeling were triangulated against cross-border shipment records.
Historical volume trajectories were cross-referenced against expert panel inputs to anchor growth assumptions across the projection horizon. The analytical framework modeled segmentation by product type, application, end user, and distribution channel, with additional stratification by regional regulatory cluster. CAGRs were derived from fitted trend analysis adjusted for qualification timeline delays and certification cost absorption rates.
Several conditions sit outside the modeled scope, including sudden ICH guideline revisions, force majeure disruptions in Mumbai-Thane logistics corridors, and abrupt shifts in palladium catalyst commodity pricing. Forecasts reflect assumptions about sustained ECHA enforcement intensity and stable CDSCO-EMA mutual recognition pathways. Practitioners should monitor ICH Q3D detection limit tightening and ANVISA registration acceleration for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Penicillin Intermediate Market
Chemical Intermediates
Octenylsuccinate Market
Chemical Intermediates
Hydroxyisobutyric Acid Market
Chemical Intermediates
API Intermediate Market
Chemical Intermediates
Ethylene Diamine Tetra Acetic Acid (EDTA) Market
Chemical Intermediates
Methacrylic Ester Market
Chemical Intermediates
Reagent Bottle Market
Chemical Intermediates
Phosphate Chemical Reagents Market
Chemical Intermediates
Isosafrole Market
Chemical Intermediates
Duloxetine Intermediate and Atorvastatin Intermediates Market
Chemical Intermediates
Metal Alkyls Market
Chemical Intermediates
Enzyme Substrates Market
Chemical Intermediates
Molybdenum Disulfide (MoS2) Market
Chemical Intermediates
Diketene Derivatives Market
Chemical Intermediates
Ph Controlling Agents Market
Chemical Intermediates
Fungal Staining Reagent Market