
 Oat Flour Market | 2026-2036
Oat Flour Market Size, Share, and Industry Trends Forecast 2026-2036
Oat Flour Market Analysis
The oat flour market is rebalancing between premium certified-gluten-free grades and commodity milling streams as price spreads widen and buyer specifications diverge. General Mills Inc. leverages its supply chain scale to secure contract acres of identity-preserved oats across the upper Midwest. Bob's Red Mill Natural Foods Inc. differentiates through dedicated gluten-free facilities and third-party certification protocols that command shelf price premiums. Avena Foods Ltd. anchors its position in organic oat flour with backward integration into Canadian prairie grain procurement.
Oat flour consists of finely milled groats or rolled oats with typical particle sizes below 150 microns and beta-glucan content ranging from 2.5% to 5.0% depending on cultivar and processing method, functioning primarily as a viscosity-building, water-binding ingredient in baked goods, meat analogues, and beverage formulations. Organic oat flour occupies the strongest margin pool as supply constraints on certified organic oat acreage outpace demand expansion from natural channel buyers. Gluten-free oat flour represents the fastest-growing product type as coeliac-safe protocols spread from North American retail into European foodservice channels. Bakeries as an end-user segment sustain the largest volume absorption, though food manufacturers are shifting procurement toward bulk container formats to support continuous-process plant bakery operations.
The FDA gluten-free labeling rule and USDA organic certification standards govern product claims and market access in the United States, while the EU Green Deal and EFSA novel food guidance shape import requirements and sustainability benchmarks for European buyers. Health Canada and CFIA oversight on oat purity for gluten-free designation creates additional compliance layers for cross-border North American trade. Stakeholders must monitor evolving threshold definitions for gluten cross-contamination as regulatory harmonization pressures mount across major import jurisdictions.
Market Dynamics
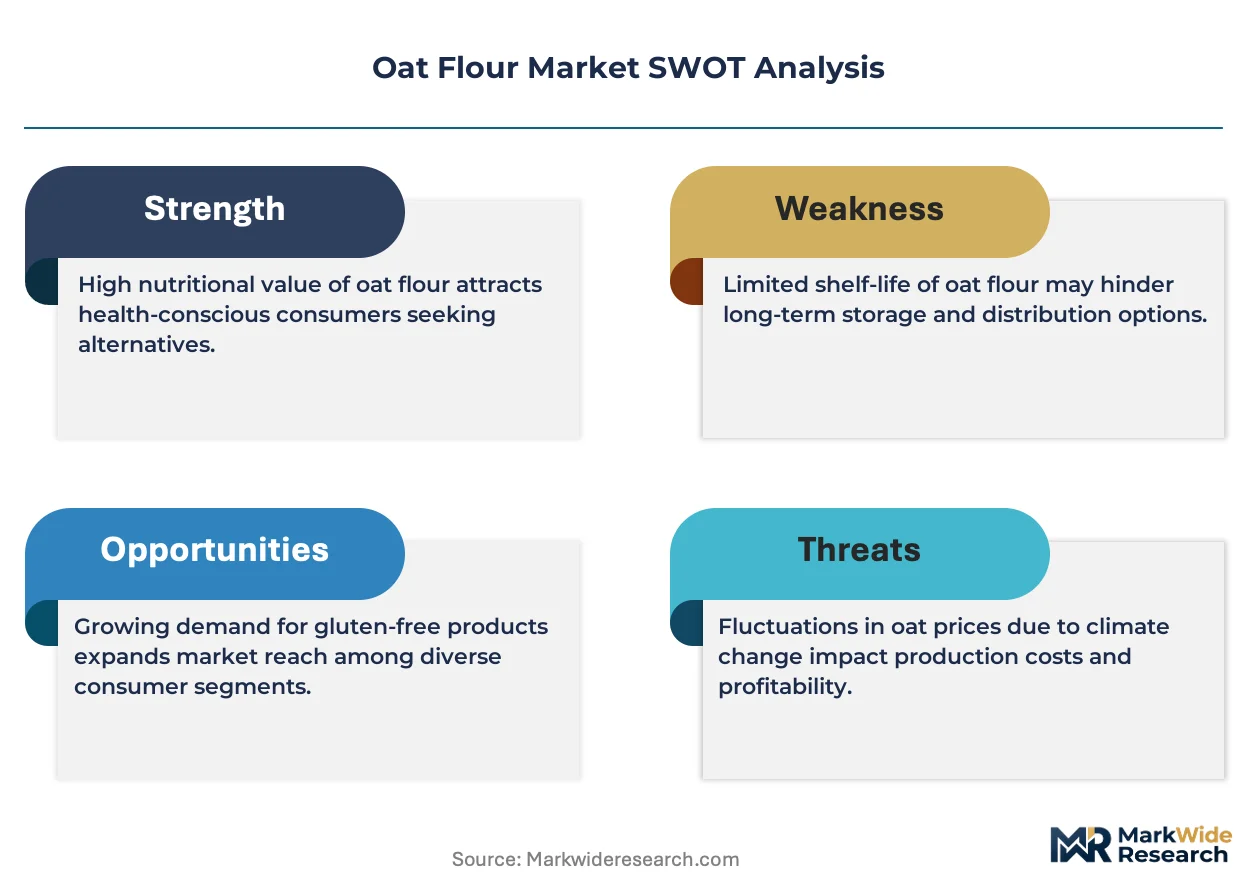
The oat flour market is experiencing acute price stratification as FDA gluten-free purity thresholds tighten and certified organic oat acreage fails to expand at pace with clean-label demand from North American food manufacturers.
Growth Catalysts
- Clean-label reformulation mandates:Major food manufacturers in the United States are replacing wheat flour with oat flour in mainstream bakery lines to meet retailer clean-label requirements.
- EU Green Deal sustainability benchmarks:European buyers now require documented carbon intensity scores for imported oat ingredients, favoring suppliers with verified low-tillage cultivation protocols.
- Canada:Avena Foods Ltd. and other prairie processors leverage Health Canada gluten-free certification to capture cross-border demand from US coeliac-safe product lines.
Market Restraints
- Input cost volatility:Certified organic oat premiums swing with weather-induced yield variability across the Canadian prairies and upper Midwest.
- Supply concentration risk:Identity-preserved gluten-free oat streams depend on a limited corridor of dedicated elevator and milling infrastructure in Minnesota, North Dakota, and Manitoba.
- Substitution threat:Rice flour and tapioca starch compete aggressively in cost-sensitive bakery applications where beta-glucan functionality is not specified.
Strategic Opportunities
- Underpenetrated foodservice channels:European commercial bakeries remain underserved by certified-gluten-free oat flour suppliers accustomed to retail-packaging formats.
- Plant-based meat analogues:Oat flour's water-binding properties position it as a preferred texturizer in next-generation burger and sausage formulations.
- Technology convergence:Near-infrared spectroscopy combined with blockchain traceability enables real-time beta-glucan verification and origin authentication for premium buyers.
Industry Challenges
- Certification timeline compression:Third-party gluten-free audits require 12-18 month facility validation cycles that delay new entrant market access.
- Skill scarcity in oat-specific milling:Particle size distribution control below 150 microns demands specialized training absent from conventional grain milling programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oat Flour Market |
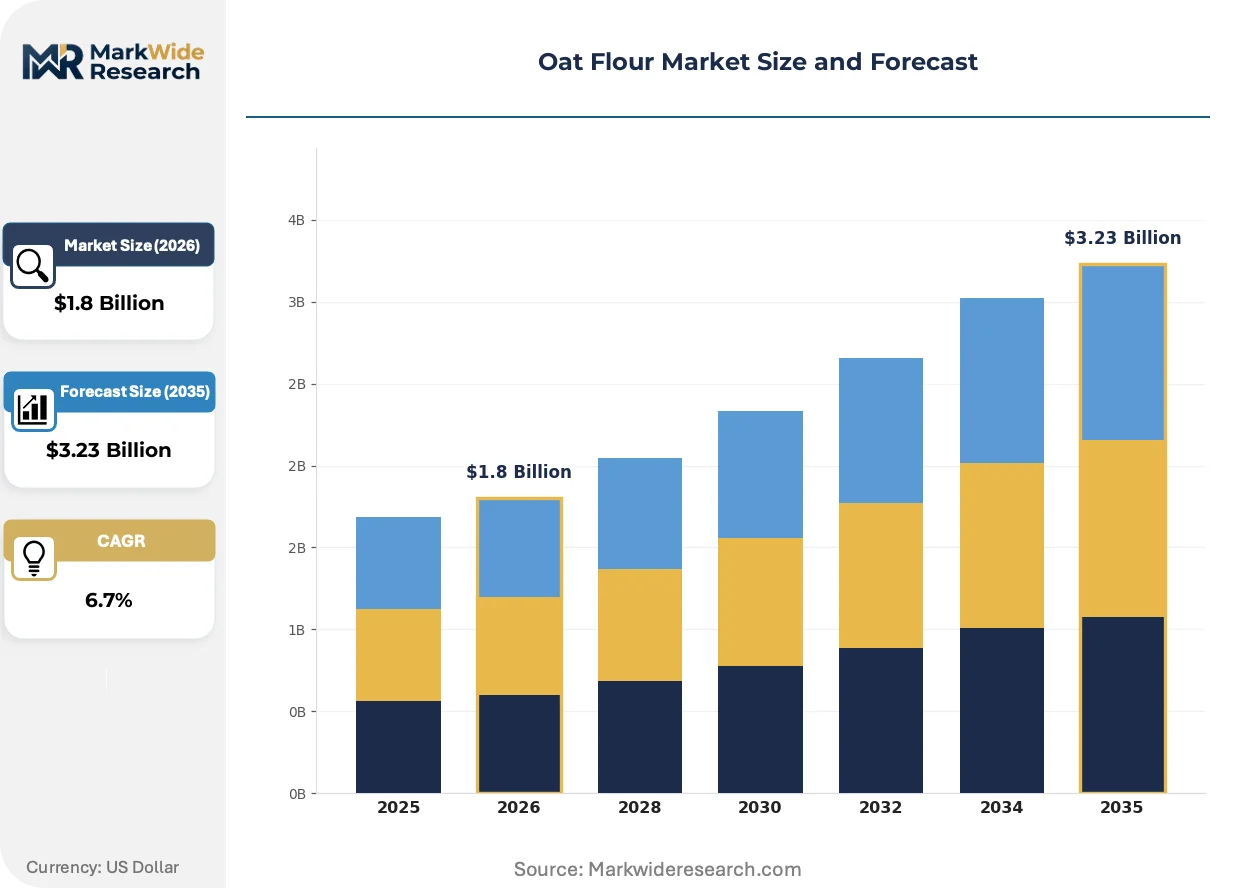
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Oat Flour, Gluten-Free Oat Flour, Whole Grain Oat Flour, Instant Oat Flour End User: Bakeries, Food Manufacturers, Restaurants, Home-Cooks Packaging Type: Bags, Bulk Containers, Boxes, Sachets Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Wholesale |
| Companies Covered | General Mills Inc., Bob's Red Mill Natural Foods Inc., Avena Foods Ltd., Grain Millers Inc., Richardson International, Blue Lake Milling Pty Ltd., Nestle S.A., Quaker Oats Company, Swedish Oat Fiber AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oat Flour Market Emerging Trajectories
Processing technology and certification protocols are diverging oat flour into distinct quality tiers, with premium streams commanding substantial markups over commodity grades as buyer specifications harden.
Precision roller milling with integrated air classification is expanding into commercial oat flour production, enabling processors to isolate beta-glucan-enriched fractions for functional beverage applications. Nutraceutical manufacturers in the United States and Germany are adopting these systems to secure consistent viscosity profiles for oat milk concentrates. The technology is expanding into mid-scale regional mills previously limited to whole-grain flours, compressing the supply base for specialty grades.
The FDA's updated gluten-free labeling rule tightens allowable gluten cross-contamination thresholds for oat-based ingredients, forcing importers to verify purity protocols at origin. Domestic US suppliers with dedicated gluten-free facilities gain preferential access to coeliac-safe product lines. European foodservice distributors now require documentation aligned with both FDA and EFSA standards, creating compliance complexity for single-territory processors.
Food manufacturers are consolidating purchasing through direct container contracts rather than spot market or distributor channels, compressing intermediary margins. Bulk procurement of certified-gluten-free oat flour in 20-tonne totes now dominates continuous-process plant bakery operations. This concentration is most visible in the United States, where General Mills Inc. and similar scale buyers negotiate multi-year supply agreements locking up identity-preserved acreage.
Oat Flour Market Segmentation
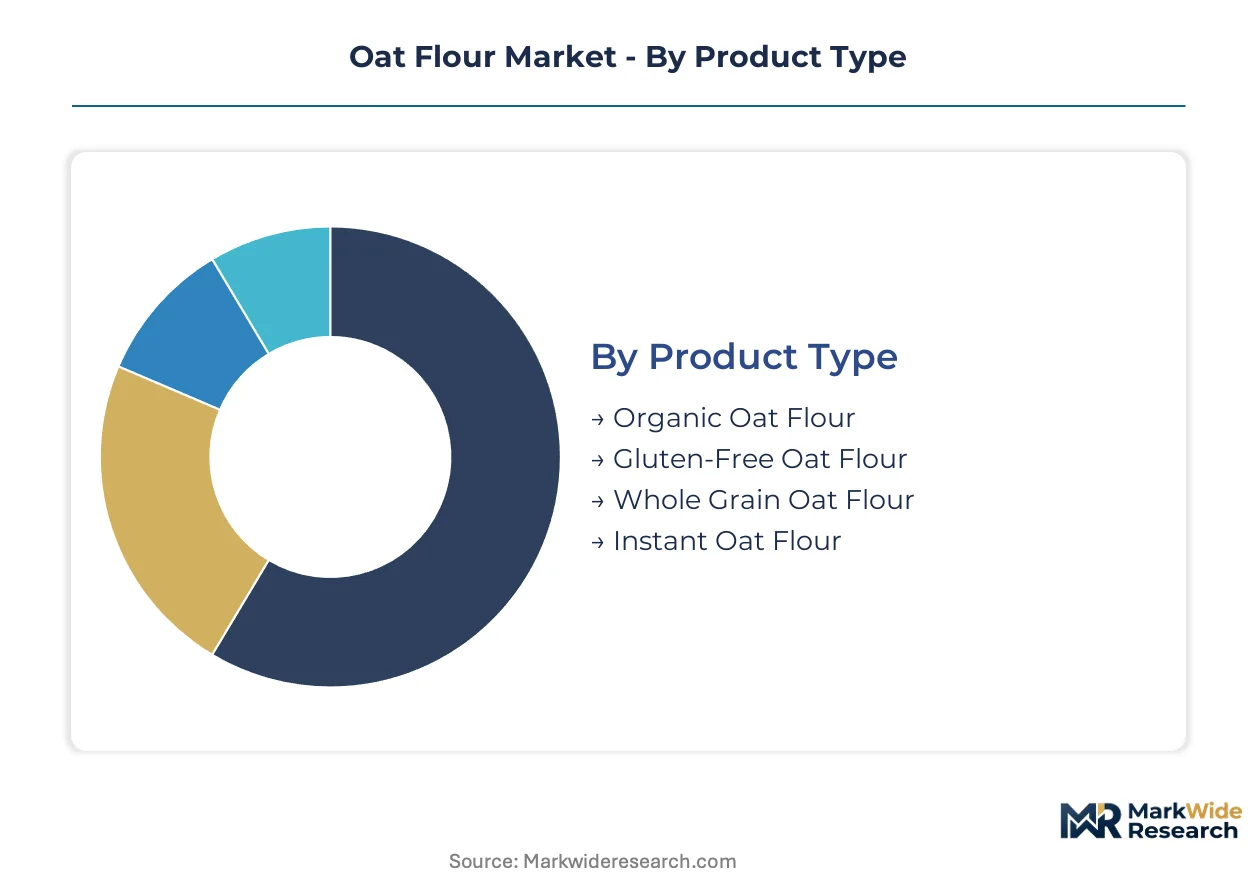
Oat flour segmentation reflects diverging supply chain investments between premium certified grades and commodity milling streams. Buyer specifications now harden around gluten-free purity thresholds and organic provenance, compressing margins for undifferentiated processors.
Product Type:
Supply concentration for certified grades tightens as identity-preserved oat acreage fails to expand at pace with clean-label demand from North American food manufacturers.
- Organic Oat Flour:Milled from certified organic groats with beta-glucan content preserved through low-temperature processing. Demand concentrates in natural channel retail across the United States and Germany where clean-label premiums justify input cost volatility. Supply constraints on certified organic acreage across the Canadian prairies sustain margin premiums.
- Gluten-Free Oat Flour:Produced under dedicated facility protocols with third-party certification verifying sub-20ppm gluten thresholds. Food manufacturers in the United States absorb the fastest volume expansion as FDA labeling rules tighten purity requirements. Coeliac-safe bakery lines now specify this grade exclusively.
- Whole Grain Oat Flour:Retains bran and germ fractions with particle sizes typically above 150 microns. Commodity baking applications in cost-sensitive segments.
- Instant Oat Flour:Pre-gelatinized through steam treatment for rapid hydration in beverage formulations. Convenience-oriented home cooking channels.
Today's leader: Organic Oat Flour. Tomorrow's challenger: Gluten-Free Oat Flour.
End User:
Procurement patterns diverge sharply between continuous-process industrial buyers and intermittent retail-channel purchasers.
- Food Manufacturers:Negotiate multi-year container contracts for 20-tonne bulk totes supporting plant bakery operations. General Mills Inc. and similar scale buyers lock up identity-preserved acreage through direct supply agreements, bypassing distributor channels entirely.
- Bakeries:Sustain the largest absolute volume absorption through hybrid procurement blending bulk containers for production runs with bagged formats for specialty batches. Artisan operators in European foodservice channels remain underserved by certified-gluten-free suppliers.
- Restaurants:Source through wholesale distributors with limited specification control. Menu innovation in plant-based analogues drives intermittent premium oat flour demand.
- Home-Cooks:Purchase retail-packaged formats through supermarkets and online channels. Price sensitivity limits penetration of certified-organic grades.
Food Manufacturers command supply priority. Bakeries represent the expansion frontier for certified-grade penetration.
Packaging Type:
Format selection tracks operational scale and inventory velocity across diverging buyer segments.
- Bulk Containers:20-tonne totes dominate continuous-process operations where pneumatic handling systems integrate directly with milling infrastructure. Food manufacturers consolidate purchasing through this format to minimize handling costs.
- Bags:Standard 25-50 pound multiwall paper sacks serve mid-scale bakeries with batch processing workflows. Distribution runs through regional distributors with warehousing capabilities.
- Boxes:Retail-oriented formats for club store and natural channel placement. Bob's Red Mill Natural Foods Inc. utilizes this packaging for shelf differentiation.
- Sachets:Single-serve portions targeting convenience channels and foodservice portion control. Limited volume but high margin per unit weight.
Bulk Containers anchor industrial procurement. Sachets climb fastest as foodservice operators seek portion precision.
Distribution Channel:
Channel configuration determines certification documentation requirements and margin capture for processors.
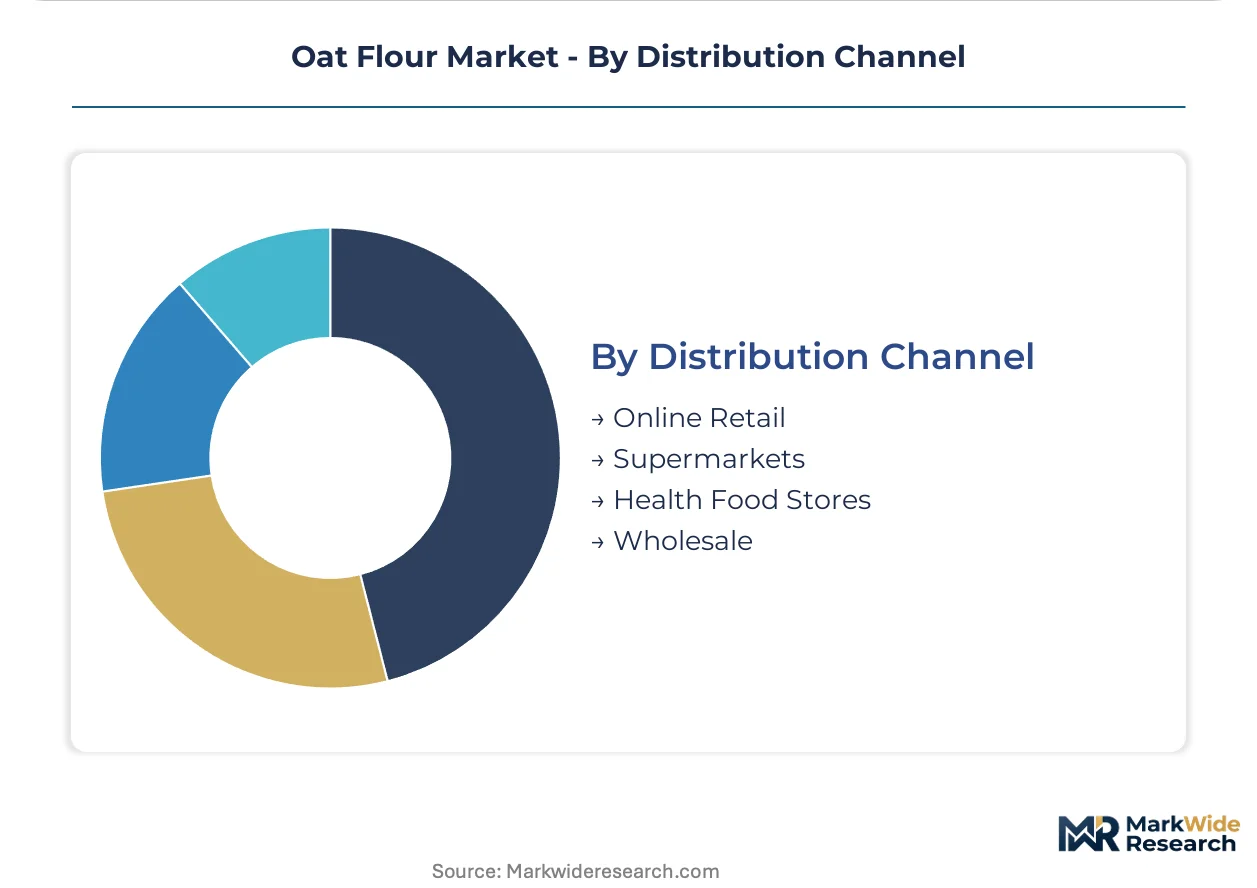
- Wholesale:Primary pathway for bulk container movement to food manufacturers and commercial bakeries. Avena Foods Ltd. leverages direct wholesale relationships to secure multi-year supply agreements.
- Supermarkets:Control retail shelf placement for bagged and boxed formats. Clean-label positioning requires third-party certification visibility on packaging.
- Health Food Stores:Curated assortment emphasizing organic and gluten-free credentials. Staff expertise drives premium grade conversion.
- Online Retail:Expanding fastest for specialty grades with subscription models capturing recurring home-cook demand. Direct-to-consumer fulfillment bypasses traditional distributor markups.
Wholesale commands volume leadership. Online Retail gains share fastest as subscription models lock in recurring purchasers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands premium oat flour volumes through clean-label reformulation mandates, while Germany absorbs certified-organic grades for natural channel retail expansion across Central Europe.
United States
Food manufacturers in Minneapolis-St. Paul and Chicago corridors drive bulk procurement of identity-preserved gluten-free streams. FDA labeling rule tightening creates compliance barriers for imported oat ingredients. Upper Midwest elevator infrastructure in Minnesota and North Dakota concentrates dedicated gluten-free handling capacity.
Germany
Natural channel retailers in Berlin and Munich sustain demand for certified-organic oat flour with beta-glucan preservation claims. EU Green Deal carbon intensity documentation requirements favor low-tillage Canadian suppliers. Hamburg port facilities handle expanding container volumes for organic prairie oat ingredients.
Canada
Prairie processors leverage Health Canada gluten-free certification to capture cross-border demand from US coeliac-safe product lines. CFIA oversight on oat purity creates additional compliance layers for Manitoba and Saskatchewan exports. Winnipeg and Regina milling clusters anchor backward integration into certified organic acreage procurement.
Sweden
Nordic foodservice distributors require dual FDA-EFSA documentation alignment for oat flour imports. Swedish Oat Fiber AB and similar specialists concentrate beta-glucan extraction expertise in southern industrial zones. Stockholm commercial bakeries represent underserved channels for certified-gluten-free bulk formats.
United Kingdom
Post-Brexit regulatory divergence complicates EU oat flour import certification for London and Manchester food manufacturers. UK retailers maintain clean-label positioning through third-party organic and gluten-free credential visibility. Midlands distribution hubs consolidate wholesale movement of bagged formats to regional bakeries.
Oat Flour Market Vendor Landscape
Top-tier vendors anchor multi-year supply agreements with identity-preserved acreage, while mid-scale specialists compete through dedicated facility certification and third-party audit protocols. The vendor base stratifies across three functional tiers: integrated grain processors with captive oat streams, independent millers with gluten-free protocol investments, and diversified food conglomerates with internal flour requirements. Two dominant competitive moves define current positioning: backward integration into certified organic prairie acreage, and technology convergence pairing near-infrared spectroscopy with blockchain traceability systems.
Within the integrated processor tier, General Mills Inc. and Grain Millers Inc. occupy positions defined by supply chain scale and direct elevator relationships across the upper Midwest and Canadian prairies. Among certification-focused specialists, Bob's Red Mill Natural Foods Inc. exemplifies the dedicated gluten-free facility archetype, while Avena Foods Ltd. represents backward integration into organic prairie grain procurement. These three anchors illustrate diverging strategic bets on premium grade specialization versus commodity volume aggregation.
| Leading Market Players |
|---|
| General Mills Inc. |
| Bob's Red Mill Natural Foods Inc. |
| Avena Foods Ltd. |
| Grain Millers Inc. |
| Richardson International |
| Blue Lake Milling Pty Ltd. |
| Nestle S.A. |
| Quaker Oats Company |
| Swedish Oat Fiber AB |
| Others |
Supply Flow & Price Mechanics
Chicago oat futures volatility cascades through the supply chain into three distinct pricing tiers, with certified-gluten-free premiums widening against commodity grades as FDA purity thresholds tighten and identity-preserved acreage contracts command multi-year lockups.
Pricing Analysis
Capacity additions in Manitoba and Saskatchewan are reshaping price floors for organic oat flour while contract-based long-term offtake agreements dominate food manufacturer procurement. Three-tier pricing structure across premium, standard, and economy levels separates certified-gluten-free from organic from conventional grades, with beta-glucan content and third-party certification as primary price differentiation drivers. Cost compression in commodity whole grain streams is intensifying because rice flour and tapioca starch substitution erodes volume leverage. Home-cooks through retail channels exhibit highest price sensitivity, while continuous-process plant bakeries absorb premiums for supply security.
Supply Chain Analysis
Health Canada gluten-free certification and FDA labeling rule compliance now gate market access, forcing upstream consolidation around dedicated elevator infrastructure. Supply concentrates in the United States, Canada, and Sweden, with prairie oat groats, specialized milling equipment, and third-party audit services as critical input dependencies. Single-source vulnerability runs through the Minnesota-North Dakota-Manitoba corridor where identity-preserved handling capacity is finite. Distribution runs through direct container contracts to food manufacturers, compressing traditional distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oat flour has entered a late-cycle quality phase where specification premiums widen and undifferentiated volume faces margin compression, as coeliac-safe and organic certifications displace commodity grades in North American food manufacturer procurement.
For Market Incumbents: Deploy backward integration into certified organic prairie acreage to lock supply before competitor contract cycles renew. Secure dedicated gluten-free elevator capacity in the upper Midwest corridor to preempt substitution threats from rice flour processors. Invest in near-infrared spectroscopy systems to verify beta-glucan content in real-time for beverage formulation customers. For New Entrants and Emerging Players: EU Green Deal carbon intensity documentation requirements in Germany open a window for low-tillage Canadian suppliers to capture natural channel retail expansion across Central Europe. European commercial bakeries remain the most penetrable segment, underserved by certified-gluten-free bulk format suppliers accustomed to retail packaging. Pursue direct foodservice distributor partnerships with dual FDA-EFSA documentation capabilities as primary go-to-market angle. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale organic processors with captive prairie acreage and Health Canada certification already in place. Over the projection horizon, facility-validated gluten-free infrastructure becomes scarce as audit timelines extend. Watch for FDA threshold tightening announcements as inflection signal for premium grade margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Acreage | Secures supply priority ahead of competitor contract renewals across prairie provinces. |
| Dual FDA-EFSA Certification Investment | Unlocks cross-border European foodservice channels previously inaccessible to single-territory processors. |
| Near-Infrared Spectroscopy Deployment | Enables real-time beta-glucan verification for nutraceutical and oat milk concentrate buyers. |
| Direct Container Contract Consolidation | Bypasses distributor markups to capture margin in continuous-process plant bakery procurement. |
| Low-Tillage Cultivation Protocol Documentation | Aligns with EU Green Deal carbon intensity benchmarks for German natural channel retail placement. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with grain procurement directors at food manufacturers, milling operations managers, third-party certification auditors, and natural channel retail buyers with secondary validation from FDA labeling guidance documents, USDA organic certification databases, Health Canada gluten-free standards, EU EFSA novel food guidance, and customs trade flow records. Bottom-up oat flour volume estimates triangulated against top-down clean-label reformulation trends across bakery and beverage categories.
Segment-weighting approaches applied product type, end user, packaging format, and distribution channel dimensions across the modeling period, with organic versus gluten-free versus conventional grade splits as the industry-specific overlay. CAGRs derived from elasticity-adjusted demand projections incorporating beta-glucan functionality premiums and regulatory threshold evolution. Forecast inputs included identity-preserved oat acreage expansion rates, elevator infrastructure capacity additions, and certification audit timeline compression.
Revisions become necessary when FDA gluten-free threshold adjustments, EU Green Deal carbon benchmarking implementation delays, or prairie weather-induced yield shocks materialize. Forecasts reflect documented assumptions on clean-label reformulation velocity and coeliac-safe product line expansion. A model refresh is warranted upon material change in Health Canada or CFIA purity protocol harmonization with US standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Wild Rice Market
Grains
Global Maize Market
Grains
Organic Cereals Market
Grains
Soya Flour Market
Grains
Green Pea Grits Market
Grains
Barley Grass Market
Grains
Sorghum Market
Grains
Grain and Cereal Crop Market
Grains
Lentil Market
Grains
Wheat Fiber Market
Grains
Whole-Wheat Flour Market
Grains
Global Precooked Corn Flour Market
Grains
Wheat Flour Market
Grains
Barley Market
Grains
GCC Basmati Rice Market
Grains
Guar Complex Market