
 Global Maize Market | 2026-2036
Global Maize Market Size, Share, and Industry Trends Forecast 2026-2036
Global Maize Market Outlook
Non-GMO identity-preserved maize is reorganizing procurement premiums across the value chain. Archer Daniels Midland Company leverages its origination network across the US Corn Belt to secure contracted acreage. Cargill sustains crush margin advantages through its integrated ethanol-starch platform. Louis Dreyfus Company competes on ocean freight optimization and South American port logistics.
Maize (Zea mays L.) is a C4 cereal grain with kernel moisture content typically dried to 15.5 percent for commercial trade, serving as the primary feedstock for starch extraction, high-fructose syrup production, and livestock energy rations. Field corn dominates volume flows into animal feed and biofuel channels, where margin pools concentrate around dry-mill ethanol economics. Sweet corn occupies distinct retail and foodservice segments with shorter supply cycles and premium pricing. Seed grade classifications attract biotechnology licensing fees and varietal IP revenues that outstrip commodity trading returns.
The US EPA Renewable Fuel Standard, Brazil's RenovaBio program, and the EU Green Deal Farm-to-Fork strategy collectively determine biofuel-driven maize demand trajectories and sustainability certification requirements. China's GB standards for grain imports and India's FSSAI food safety codes shape cross-border market access conditions for differentiated grades. Stakeholders must monitor carbon intensity scoring systems and deforestation-free supply chain mandates as these frameworks harden into trade prerequisites.
Market Dynamics
Carbon intensity scoring systems are restructuring procurement premiums across biofuel and feed supply chains, forcing originators to document deforestation-free sourcing and embedded emissions at farm gate.
Growth Catalysts
- Brazil's RenovaBio program:The carbon credit mechanism rewards ethanol producers sourcing low-carbon intensity maize, redirecting crush capacity toward identity-preserved supply chains with verified sustainability credentials.
- EU Green Deal Farm-to-Fork strategy:Mandatory sustainability certification for imported feed grains creates compliant premium channels that bypass conventional commodity arbitrage.
- Enzymatic dry-grind processing:Next-generation cellulase cocktails enable higher ethanol yields per bushel, improving plant economics and extending crush margins across US Corn Belt facilities.
Market Restraints
- Nitrogen fertilizer cost volatility:Ammonia and urea price swings driven by natural gas feedstock exposure compress farm-level margins and constrain acreage expansion in Ukraine's Black Sea corridor.
- Single-origin dependence in Argentina's Pampas:Concentrated export elevation through Rosario and Bahía Blanca creates bottleneck risk during labor disputes or river draft restrictions.
- Regulatory friction from EU F-Gas Regulation:Phasedown of HFC refrigerants raises cold storage costs for identity-preserved maize, eroding premium capture in specialty feed channels.
Strategic Opportunities
- India's ethanol blending mandate:The 20 percent blending target by 2025 opens import demand for feedstock-grade maize as domestic coarse grain supplies prove insufficient for distillery expansion.
- Regenerative agriculture certification:Soil carbon protocols in Australia and the US create verified low-carbon grain premiums that biofuel refiners purchase to meet compliance obligations.
- Blockchain-enabled provenance tracking:Distributed ledger systems converge with satellite imagery to automate deforestation-free documentation, reducing audit costs for EU-bound shipments.
Industry Challenges
- Carbon accounting skill scarcity:Farm cooperatives and grain elevators lack personnel trained in lifecycle assessment methodologies required for EU carbon border compliance.
- Identity-preserved segregation infrastructure:Dedicated storage and handling systems for non-GMO and specialty trait maize demand capital deployment that commodity handlers resist without contracted offtake guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Maize Market |
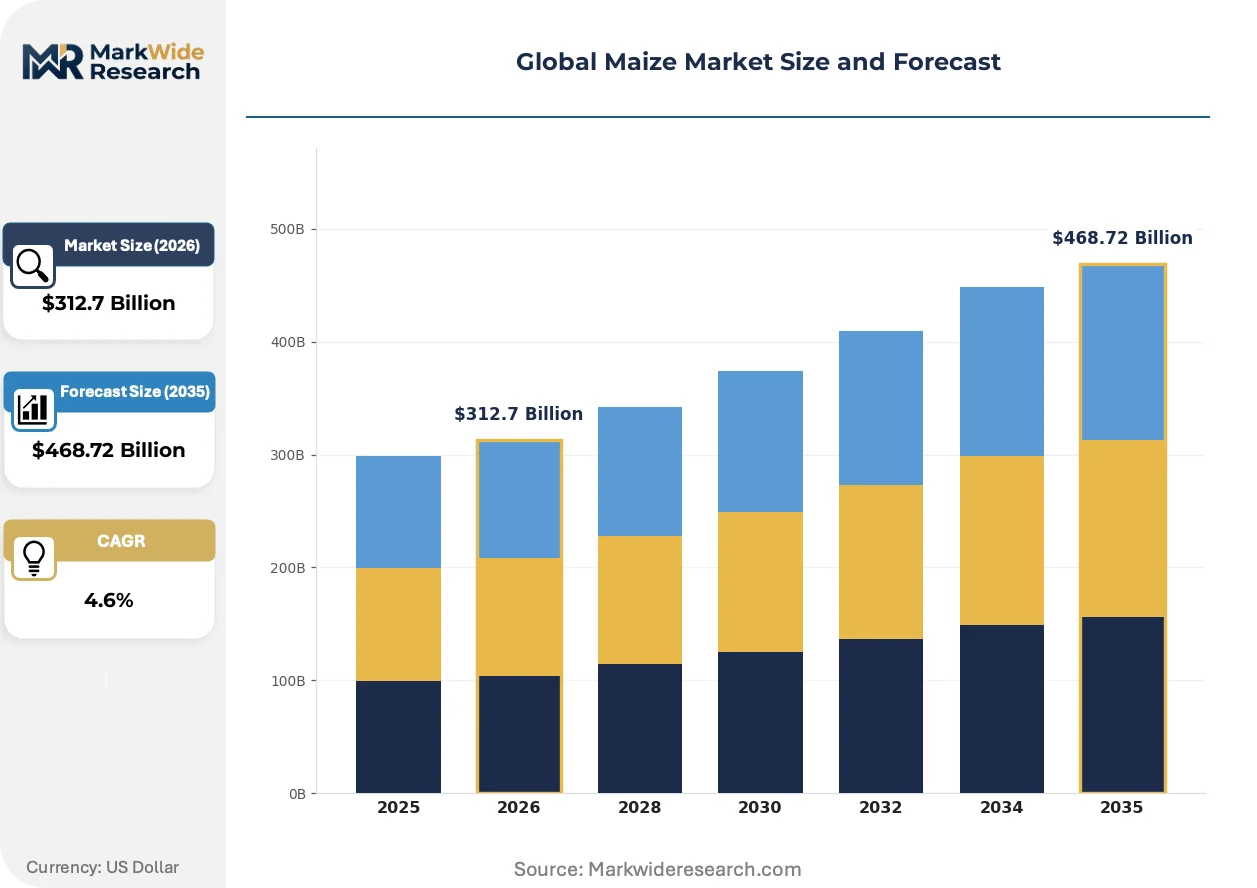
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $468.72 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweet Corn, Field Corn, Popcorn, Baby Corn End Use Industry: Food Processing, Animal Feed, Biofuels, Starch Production Grade: Commercial, Organic, Food Grade, Seed Grade Distribution Channel: Direct Sale, Retail, Online, Wholesalers |
| Companies Covered | Louis Dreyfus Company, Glencore plc, Archer Daniels Midland Company, CHS Inc., Viterra, Cargill, COFCO International, Syngenta Group, Bunge Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Maize Market Strategic Shifts
Gene editing and precision fermentation are diverging from transgenic commodity breeding, creating parallel innovation tracks that serve distinct regulatory and end-use markets with incompatible approval frameworks.
CRISPR-Cas9 edited maize varieties with altered starch profiles are bifurcating the industrial processing segment. Wet millers seeking high-amylose fractions for biodegradable packaging adopt edited lines faster than food manufacturers bound by stricter novel food regulations. This technology split is compressing time-to-market for industrial applications while extending regulatory timelines for human food channels.
The EU F-Gas Regulation and associated carbon border adjustment mechanism are tightening import documentation requirements for feed grains. Industrial livestock producers must now verify embedded emissions and land-use change status for maize entering European supply chains. Feed compounders in the Netherlands and Denmark are responding by sourcing from certified low-carbon programs in France and Romania rather than conventional Black Sea origins.
Livestock integrators are consolidating feed procurement through direct origination contracts that bypass traditional merchant intermediaries. Large protein producers in Vietnam and Indonesia now contract directly with Argentine and Brazilian farm cooperatives for containerized shipments. This disintermediation concentrates volume risk with end-users while compressing trading margins for legacy grain houses dependent on speculative position-taking.
Global Maize Market Segmentation
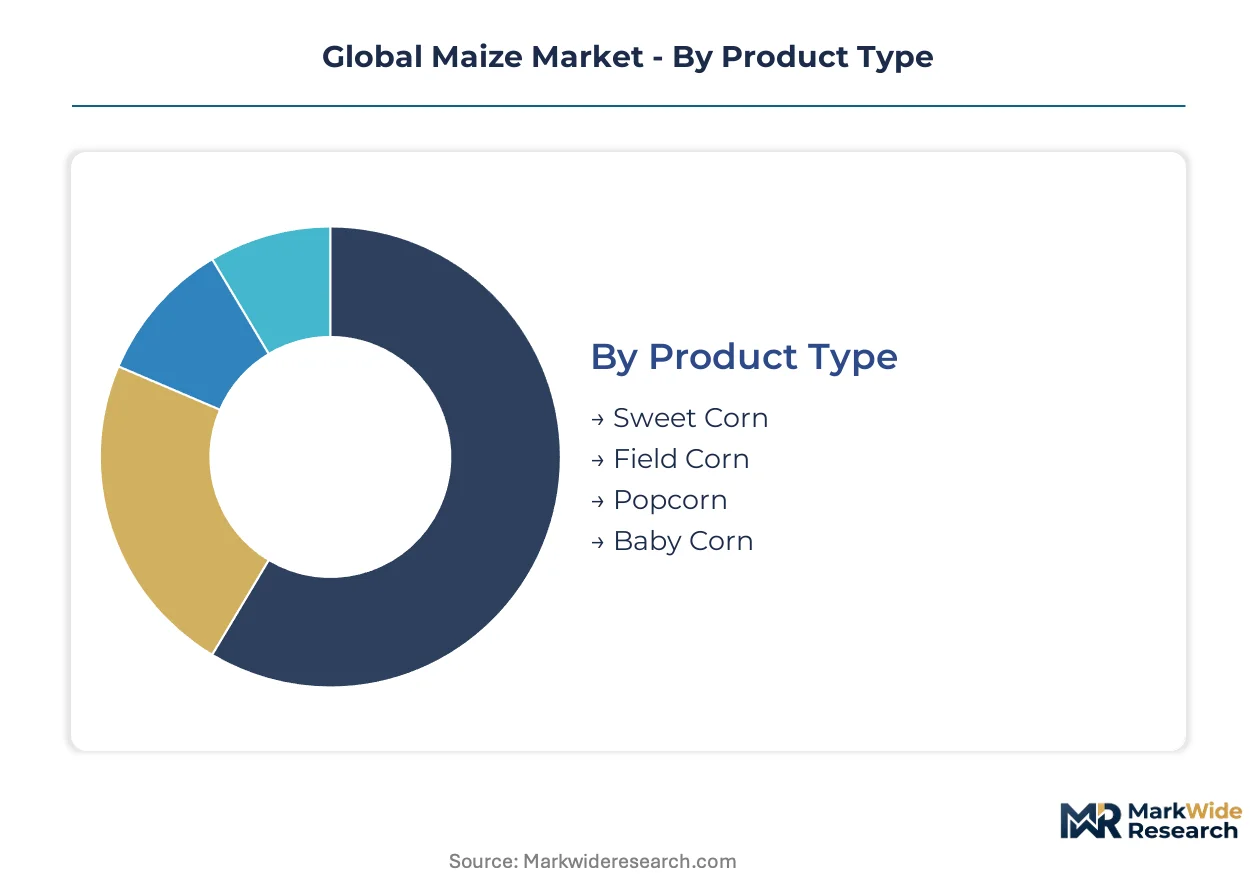
Maize segmentation determines margin capture across fundamentally divergent regulatory regimes. The EU Green Deal Farm-to-Fork strategy, US EPA Renewable Fuel Standard, and India's FSSAI codes each privilege different grade classifications and end-use channels, forcing suppliers to maintain parallel inventory systems.
Product Type:
Regulatory frameworks distinguish product types through moisture specifications, GMO tolerance thresholds, and novel food approval pathways that gate market access.
- Field Corn:Kernel moisture content standardizes at 15.5 percent for commercial trade. EPA biofuel mandates and Brazil's RenovaBio carbon credits concentrate demand in US Corn Belt and Brazilian Cerrado ethanol corridors, where crush margins reward volume throughput.
- Sweet Corn:Higher sugar content and perishable harvest windows require chilled supply chains. Retail and foodservice channels in Japan and the EU drive premium pricing, though F-Gas Regulation refrigerant phase-downs compress cold storage economics.
- Popcorn:Specialized expansion characteristics command snack food premiums. Microwave and ready-to-eat segments in North American multiplex and home entertainment channels sustain contracted acreage programs.
- Baby Corn:Immature ear harvesting demands labor-intensive cultivation. Thai and Indian export processing zones supply canned and fresh segments to European and Middle Eastern import markets.
Established volume favors Field Corn; emerging adoption favors Sweet Corn.
End Use Industry:
Cost tier differentiation separates commodity feedstock flows from certified premium channels with documented carbon intensity scores.
- Animal Feed:Energy ration formulation dominates volume consumption. China's GB standards and EU deforestation-free mandates are redirecting procurement from Black Sea origins to certified Brazilian and Argentine supply chains with verified land-use documentation.
- Food Processing:Wet milling fractions serve high-fructose syrup, cornmeal, and beverage alcohol channels. FDA GRAS determinations and EFSA novel food opinions create asynchronous approval timelines for modified starch varieties.
- Biofuels:Dry-mill ethanol economics hinge on crush margins and carbon intensity scoring. RenovaBio credits in Brazil and California LCFS compliance markets reward feedstock sourcing from low-carbon intensity production systems.
- Starch Production:Industrial amylose and amylopectin fractions supply paper, textile, and biodegradable packaging applications. CRISPR-edited high-amylose lines are accelerating industrial adoption faster than food channels bound by stricter regulatory review.
Margin concentration sits with Starch Production; steepest expansion trajectory belongs to Biofuels.
Grade:
Customer type stratification separates commodity handlers from identity-preserved specialists with segregated infrastructure investments.
- Commercial:Standard trading specifications govern bulk elevator flows. Fungal toxin thresholds and moisture penalties enforce quality discipline at export terminals in Rosario, New Orleans, and Santos.
- Food Grade:Aflatoxin and fumonisin limits tighten for direct human consumption. EU contaminants regulation and Codex Alimentarius standards shape import acceptance protocols.
- Organic:Certification prohibits synthetic inputs and GMO presence. Premium capture depends on three-year transition protocols and accredited body audits that constrain supply elasticity.
- Seed Grade:Genetic purity standards and germination rates support varietal IP licensing. Trait fees and technology use agreements generate revenue streams that outstrip commodity trading returns for major seed developers.
Volume scale favors Commercial; certification premiums favor Organic.
Distribution Channel:
Supply concentration patterns determine channel economics, with containerized direct contracts displacing traditional bulk handling in premium segments.
- Direct Sale:Origination contracts link processors to farm cooperatives. Vietnamese and Indonesian livestock integrators now contract directly with Argentine Pampas producers, bypassing legacy merchant intermediaries.
- Wholesalers:Aggregated volume and credit facilitation serve smallholder access. Regional grain elevators in Ukraine's Black Sea corridor and India's surplus states perform assembly and quality blending functions.
- Retail:Packaged sweet corn and specialty varieties reach consumers through supermarket and farm shop channels. Cold chain requirements limit geographic reach.
- Online:E-commerce platforms connect specialty and organic producers to niche buyers. Blockchain-enabled provenance documentation supports premium positioning for sustainability-verified shipments.
Legacy infrastructure favors Wholesalers; disintermediation momentum favors Direct Sale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export surplus positions concentrate in three surplus belts while import demand clusters in deficit regions with feed and fuel mandates. Trade flows increasingly pivot on carbon intensity documentation and deforestation-free certification rather than price alone. Currency volatility and freight rate swings amplify margin pressure at origin.
United States
EPA Renewable Fuel Standard mandates sustain ethanol crush demand across Iowa and Illinois processing corridors. Farm Bill conservation programs incentivize cover-crop adoption that lowers carbon intensity scores for California LCFS compliance. Gulf Coast export elevators at New Orleans and Houston handle bulk shipments to Mexico and Japan.
Brazil
RenovaBio carbon credits redirect Cerrado and Mato Grosso crush capacity toward identity-preserved supply chains with verified sustainability credentials. ANVISA and MAPA regulations govern GMO approval timelines that lag behind US and Argentine frameworks. Santos port infrastructure expansions target containerized specialty grain exports to Southeast Asian livestock integrators.
Argentina
Pampas grain belt concentration creates bottleneck risk through Rosario and Bahía Blanca export terminals during labor disputes or Paraná river draft restrictions. Export taxes and currency controls distort farm-gate pricing signals. Bahía Blanca crushing complexes serve Brazilian and Chilean deficit markets with processed meal and oil.
China
GB standards for grain imports and stockpiling policies shape commercial access conditions for feed-grade maize from Ukraine and Brazil. Domestic ethanol blending mandates compete with food security priorities for coarse grain allocation. Dalian and Guangzhou port zones handle bulk discharge for state reserve procurement and private feed mill sourcing.
India
FSSAI food safety codes and DGFT import tariffs structure market access for feedstock-grade shipments as the 20 percent ethanol blending target by 2025 outstrips domestic coarse grain supplies. Distillery expansion in Maharashtra and Karnataka opens import demand from Argentina and Brazil. Containerized direct contracts bypass traditional bulk handling infrastructure.
Global Maize Market Competitive Environment
Listed leaders compete with private specialists across origination networks and processing infrastructure. The vendor base concentrates around integrated agribusiness conglomerates with captive logistics assets and regional cooperatives with localized origination strength. Three archetypes dominate: multinational traders with ocean freight optimization, processor-integrators with crush margin capture, and seed-tech licensors with varietal IP revenues. Competitive moves center on backward integration into farm-level origination and strategic partnerships for carbon accounting compliance.
Within the multinational trading tier, Archer Daniels Midland Company and Cargill exemplify scale-driven positioning through integrated ethanol-starch platforms and US Corn Belt origination networks. Louis Dreyfus Company occupies a position emphasizing South American port logistics and ocean freight optimization. Among state-linked enterprises, COFCO International anchors Chinese import demand origination. These entities represent divergent responses to carbon intensity scoring requirements and identity-preserved segregation infrastructure investments.
| Leading Market Players |
|---|
| Louis Dreyfus Company |
| Glencore plc |
| Archer Daniels Midland Company |
| CHS Inc. |
| Viterra |
| Cargill |
| COFCO International |
| Syngenta Group |
| Bunge Limited |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between Brazilian ethanol refineries and Mato Grosso farm cooperatives lock in both supply access and carbon intensity score visibility, insulating crush margins from spot price volatility while embedding deforestation-free documentation costs into the contract structure.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the Global Maize Market. Price differentiation rests on certification grade and carbon intensity scoring, with RenovaBio-compliant identity-preserved lots commanding premiums over conventional commodity flows. Cost compression in standard-grade channels is intensifying because nitrogen fertilizer volatility compresses farm-gate margins. Feed compounders in the Netherlands and Denmark demonstrate the highest price sensitivity, while biofuel refiners chasing California LCFS compliance show relative inelasticity.
Supply Chain Analysis
Container availability constraints on the Santos-Southeast Asia trade lane are reshaping procurement patterns for Vietnamese and Indonesian livestock integrators. Geographic supply concentration centers on the United States, Brazil, and Argentina, with Ukrainian Black Sea flows disrupted by logistics chokepoints. Raw material dependencies include ammonia-based nitrogen fertilizers, diesel for field operations, and maritime bunker fuel for ocean freight. Single-origin dependence through Rosario and Bahía Blanca creates bottleneck risk during labor disputes or Paraná river draft restrictions. Distribution runs through direct origination contracts that bypass traditional merchant intermediaries in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon accounting expertise scarcity defines competitive positioning in this market, as farm cooperatives and grain elevators lack personnel trained in lifecycle assessment methodologies required for EU carbon border compliance.
For Market Incumbents: Shield crush margin capture by securing contracted acreage programs with embedded sustainability documentation before emerging carbon-accounting specialists capture origination relationships. Prioritize backward integration into identity-preserved segregation infrastructure in Brazil's Cerrado to preempt RenovaBio credit competition. Channel control through dedicated storage systems for non-GMO and specialty trait maize defends against commodity handler encroachment. For New Entrants and Emerging Players: Blockchain-enabled provenance tracking services represent a service-layer gap where incumbents under-serve, creating white-space opportunity for automated deforestation-free documentation platforms. Target India's distillery expansion corridor as the most penetrable geography, where the 20 percent ethanol blending mandate outstrips domestic coarse grain supplies. Pursue direct containerized contracting with Maharashtra and Karnataka processors as the go-to-market angle. For Investors and Strategic Acquirers: Regional cooperatives with accredited carbon accounting capabilities and existing EU-bound shipment relationships represent the priority acquisition target archetype. Long-term viability hinges on positioning upstream of tightening sustainability certification requirements across the projection horizon. Watch for RenovaBio carbon credit price inflection as the signal indicating accelerated capital deployment into low-carbon intensity supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Accounting Services | Captures margin pools from EU Green Deal Farm-to-Fork compliance documentation requirements. |
| Identity-Preserved Segregation Infrastructure Investment | Enables RenovaBio credit eligibility and California LCFS premium capture for Brazilian crush facilities. |
| Blockchain-Enabled Provenance Tracking Platform | Reduces audit costs for EU-bound shipments while automating deforestation-free supply chain verification. |
| Direct Origination Contract Expansion | Bypasses legacy merchant intermediaries to capture disintermediation momentum in Southeast Asian livestock feed channels. |
| Regenerative Agriculture Certification Program | Creates verified low-carbon grain premiums that biofuel refiners purchase to meet compliance obligations in Australia and the US. |
Study Parameters
Operator-level perspectives from grain elevator managers, biofuel refinery procurement leads, farm cooperative agronomists, and maritime freight operators anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from customs and trade data, USDA and CONAB production reports, EPA Renewable Fuel Standard filings, and EU Green Deal regulatory documentation. Bottom-up acreage and crush capacity modeling triangulated against top-down consumption projections across animal feed, biofuel, and starch production channels.
Sensitivity analysis tested forecast robustness across nitrogen fertilizer price scenarios, RenovaBio carbon credit valuation bands, and EU F-Gas Regulation compliance cost assumptions over the projection horizon. Segmentation dimensions modeled include product type, end-use industry, grade classification, and distribution channel, with carbon intensity scoring treated as a cross-cutting attribute. CAGRs derived from historical volume trajectories adjusted for policy mandate acceleration and sustainability certification penetration curves.
Material uncertainties — abrupt regulatory shifts in EU deforestation-free enforcement, Paraná river navigability disruptions, and RenovaBio program modifications — sit outside the modeled envelope. Forecasts reflect assumptions about carbon intensity scoring adoption timelines and identity-preserved infrastructure deployment rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Corn Flour Market
Grains
Ancient Grain Market
Grains
China Maize Market
Grains
Brazil Maize Market
Grains
Barley Market
Grains
Africa Wheat Flour Market
Grains
Organic Rice Flour Market
Grains
Europe Rice Market
Grains
China Wheat Protein Market
Grains
Uganda Grains Market
Grains
Grain Storage Silos Market
Grains
Asia-Pacific Guar Market
Grains
Barley Grass Market
Grains
South American Maize Market
Grains
South America Rice Market
Grains
Mesquite Flour Market