
 Duck Medicine and Vaccines Market | 2026-2036
Duck Medicine and Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Duck Medicine and Vaccines Market Insights
mRNA platform technology is recalibrating vaccine development economics for waterfowl health. Boehringer Ingelheim International GmbH leverages its mammalian vaccine expertise to extend into avian vector platforms. Ceva anchors its position through specialized duck disease portfolios across European and Asian markets. Merck & Co., Inc. competes on manufacturing scale for multivalent avian vaccines.
Duck medicine and vaccines comprise pharmaceutical and biological products formulated for disease prevention, treatment, and nutritional support in Anatidae species, typically administered as oil-adjuvanted injectables or live attenuated preparations with specified titers and stability profiles. These products serve commercial waterfowl operations, veterinary clinics, and research facilities managing flock health, meat safety compliance, and zoonotic risk mitigation. Vaccines command the dominant margin pool due to recurring preventive protocols, while oral delivery modes gain traction in large-scale farm settings where labor costs constrain injectable administration. Nutritional supplements represent the fastest-expanding category as producers integrate gut health management into antibiotic reduction strategies.
USDA and FDA oversight in the United States mandates withdrawal periods for antibiotic residues and establishes biologics licensing standards for avian vaccines. China's NMPA and Ministry of Agriculture enforce compulsory immunization programs against notifiable avian diseases while restricting growth-promoter antibiotics in feed. Veterinary practitioners and farm operators must monitor regulatory divergence between export-market residue limits and domestic production standards to avoid trade disqualification.
Market Dynamics
China's NMPA compulsory immunization mandates against Newcastle disease and avian influenza are compressing vaccine procurement cycles across Southeast Asian commercial duck operations, forcing producers to integrate preventive health protocols into flock management systems.
Growth Catalysts
- Live Attenuated Vaccine Platforms:Oil-adjuvanted injectable formulations with extended stability profiles are reducing cold-chain dependency for large-scale waterfowl operations in Vietnam and Indonesia.
- EU Green Deal Residue Standards:Tighter veterinary drug residue limits on duck meat exports are accelerating preventive vaccination adoption over therapeutic antibiotic interventions in European-destined supply chains.
- Thailand:Commercial duck farm consolidation around Bangkok and Nakhon Pathom is creating concentrated demand for multivalent vaccine protocols serving integrated meat processing operations.
Market Restraints
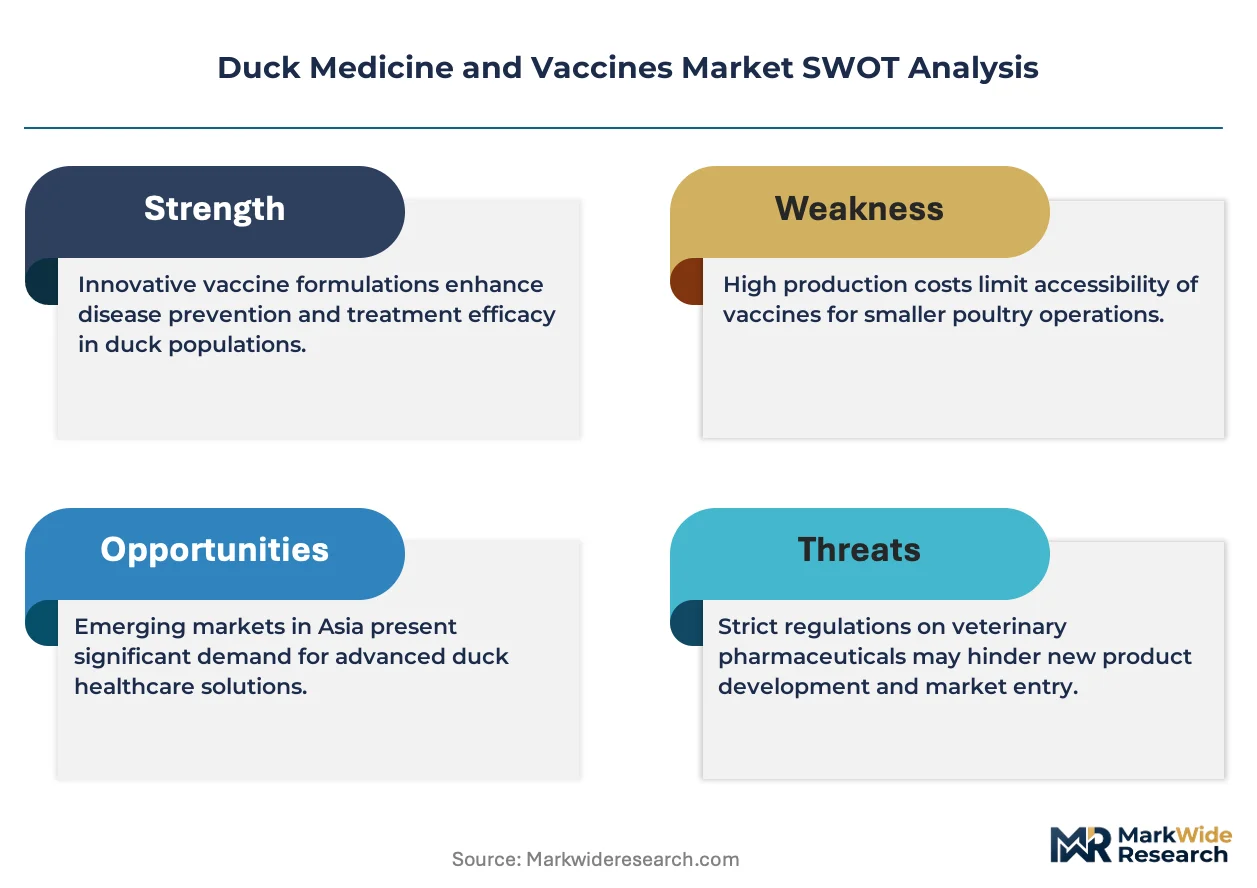
- Adjuvant Oil Price Volatility:Mineral oil and squalene derivative costs fluctuate with petrochemical feedstock markets, squeezing margin structures for injectable vaccine manufacturers.
- Single-Source Live Virus Supply:Attenuated strain production concentrates in a limited number of certified biologics facilities, creating vulnerability in outbreak response capacity.
- Withdrawal Period Complexity:Divergent residue limits between China's domestic GB standards and destination-market EMA requirements force dual compliance protocols on export-oriented producers.
Strategic Opportunities
- Myanmar and Cambodia:Underpenetrated commercial duck sectors lack established veterinary service networks, creating first-mover advantage for oral delivery vaccine formats.
- mRNA-Nanoparticle Convergence:Mammalian platform technology transfer into avian applications promises accelerated strain-matching against emerging influenza variants.
- Direct Farm Distribution:Bypassing traditional veterinary clinic channels through producer cooperative purchasing platforms reduces procurement friction for mid-scale operations.
Industry Challenges
- Avian Vaccinology Specialization Gap:Limited university programs produce waterfowl-specific immunologists, constraining R&D pipeline velocity for duck-adapted formulations.
- Biologics Licensing Timelines:NMPA and USDA approval pathways for novel vector platforms extend development cycles, delaying market entry for next-generation products.
- Legacy Cold-Chain Infrastructure:Rural farm storage capacity gaps in Guangxi and Hunan provinces compromise vaccine titer integrity through last-mile distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Duck Medicine and Vaccines Market |
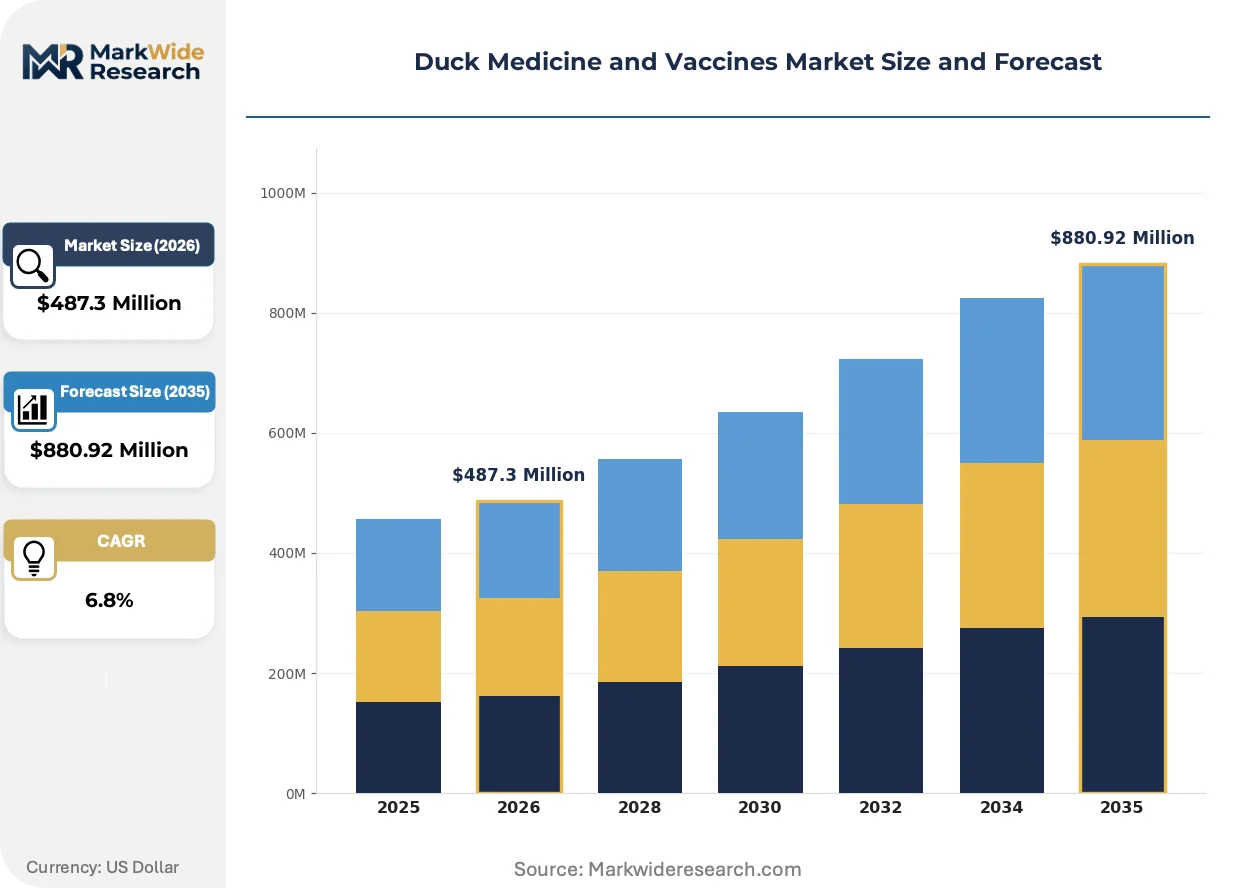
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Vaccines, Antiparasitics, Nutritional Supplements Delivery Mode: Oral, Injectable, Topical, Inhalation End User: Veterinarians, Farms, Animal Hospitals, Research Institutions Species: Ducks, Waterfowl, Geese, Others |
| Companies Covered | Boehringer Ingelheim International GmbH, Ceva, YEBIO BIOENGINEERING CO., LTD., NAVETCO, Shangqiu Meilan Biological Engineering Co.,Ltd., Merck & Co., Inc., EGAVET, Bioveta, a.s., Jilin Zhengye Biological Products company limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Duck Medicine and Vaccines Market Trends and Innovations
Waterfowl health management is pivoting from reactive treatment to predictive prevention, with digital flock monitoring and novel delivery technologies compressing the interval between disease emergence and immune response deployment.
Needle-free intradermal delivery systems using high-pressure liquid jet injectors are automating mass vaccination workflows in Thai and Vietnamese commercial operations. Contract farming integrators operating 50,000-plus bird facilities have adopted these systems to reduce labor costs and eliminate needle-stick injuries. The technology is automating throughput rates that previously required dedicated vaccination crews, enabling single-operator management of 10,000-bird daily protocols.
China's Ministry of Agriculture restrictions on growth-promoter antibiotics in feed, enacted under dual carbon goals and food safety mandates, are redirecting producer investment toward gut health nutritional supplements. Duck meat processors supplying domestic retail chains must now document antibiotic-free rearing periods. The policy shift most affects integrated operations in Shandong and Jiangsu provinces, where producers are reformulating rations with probiotic and prebiotic additives.
Large-scale farm operators are consolidating vaccine procurement through cooperative purchasing agreements rather than individual veterinary clinic relationships. This channel migration concentrates buying power among producer associations in Indonesia's Java region and the Philippines' Central Luzon corridor. The behavioral shift is most visible in Vietnam's Mekong Delta, where duck farming cooperatives now negotiate directly with vaccine distributors, bypassing traditional intermediary margins and securing volume-based pricing tiers.
Duck Medicine and Vaccines Market Segmentation
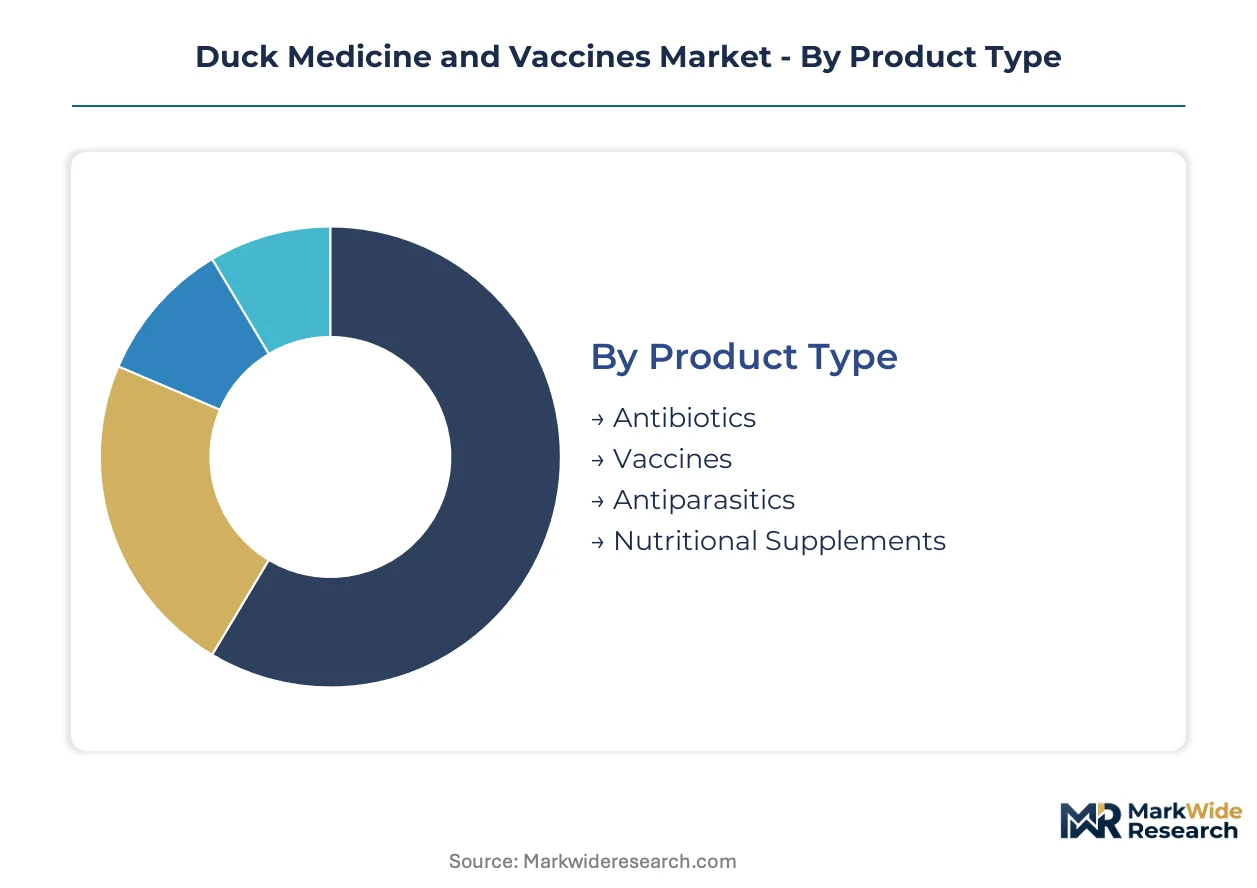
Duck medicine and vaccines segment along four functional dimensions that determine procurement patterns and margin structures. Product type and delivery mode splits reflect the tension between preventive health economics and labor constraints in commercial operations. End user and species categories capture channel dynamics and formulation specialization requirements across Anatidae species.
Product Type:
Vaccines dominate procurement volume while nutritional supplements command premium pricing tiers in antibiotic-restricted supply chains.
- Vaccines:Oil-adjuvanted injectables and live attenuated preparations with specified titers serve Newcastle disease and avian influenza protocols. China's NMPA compulsory immunization mandates compress procurement cycles across Southeast Asian commercial duck operations, forcing integration of preventive health into flock management.
- Nutritional Supplements:Probiotic and prebiotic formulations support gut health management in antibiotic reduction strategies. Shandong and Jiangsu province processors supplying domestic retail chains document antibiotic-free rearing periods, redirecting producer investment toward these additives.
- Antibiotics:Therapeutic formulations face tightening residue limits under EU Green Deal standards and China's dual carbon goals, constraining growth-promoter applications in feed.
- Antiparasitics:Deworming and ectoparasite control products maintain steady demand in free-range and semi-intensive waterfowl operations.
Mature deployment sits with vaccines. Newer deployment is concentrated in nutritional supplements.
Delivery Mode:
Injectable formats retain efficacy advantages while oral delivery gains share in labor-constrained large-scale farm settings.
- Injectable:Oil-adjuvanted formulations with extended stability profiles reduce cold-chain dependency for Vietnamese and Indonesian waterfowl operations. High-pressure liquid jet injectors automate mass vaccination workflows in Thai commercial facilities, enabling single-operator management of high-throughput protocols.
- Oral:Water-soluble and feed-additive formats bypass veterinary clinic channels through producer cooperative purchasing. Myanmar and Cambodia's underpenetrated commercial duck sectors lack established veterinary service networks, creating first-mover advantage for oral formats.
- Topical:External parasite control and wound management applications serve smaller-scale operations and backyard flocks.
- Inhalation:Aerosol delivery systems target respiratory disease prevention in confined housing environments with controlled ventilation systems.
Volume concentration favors injectable formats in integrated processing operations. Oral delivery is expanding most quickly in cooperative purchasing channels.
End User:
Farms drive procurement scale while veterinarians retain influence over protocol design and product selection.
- Farms:Commercial operations with 50,000-plus bird facilities consolidate vaccine procurement through cooperative purchasing agreements. Indonesia's Java region and the Philippines' Central Luzon corridor producer associations negotiate directly with distributors, bypassing traditional intermediary margins.
- Veterinarians:Private practitioners and government veterinary services design immunization schedules and certify health status for export compliance. They monitor regulatory divergence between China's domestic GB standards and destination-market EMA residue limits.
- Animal Hospitals:Clinical facilities handle individual bird treatment and diagnostic services, primarily serving exhibition and specialty waterfowl operations.
- Research Institutions:Universities and biologics development centers maintain reference strain collections and conduct field efficacy trials for novel formulations.
Procurement volume concentrates with farms. Technical specification authority remains with veterinarians.
Species:
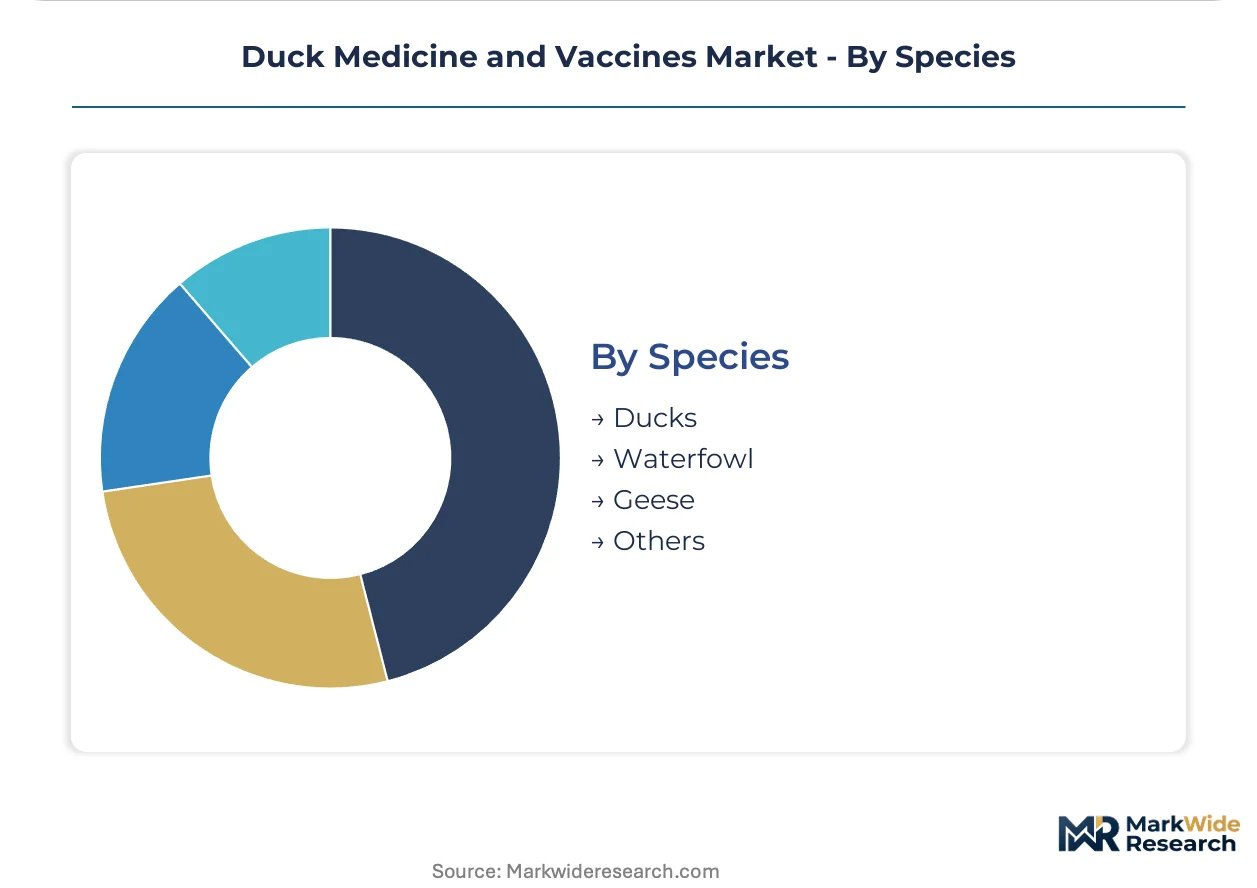
Duck-specific formulations capture commercial volume while multi-species waterfowl products serve diversified operations.
- Ducks:Formulations optimized for meat and egg production strains dominate procurement, with China's position as largest global producer driving bulk procurement patterns for Newcastle disease and avian influenza vaccines.
- Waterfowl:Multi-species products serve mixed operations and wildlife management contexts where Anatidae species comingle.
- Geese:Larger body mass requires adjusted dosing protocols and specialized equipment for mass administration in European and Asian production systems.
- Others:Swan and ornamental waterfowl applications represent niche demand with premium pricing and specialized veterinary service requirements.
Commercial scale sits with duck-specific formulations. Multi-species flexibility is gaining relevance in diversified agricultural operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate vaccine manufacturing infrastructure for waterfowl health products. Southeast Asian commercial duck operations cluster around Bangkok, Ho Chi Minh City, and Jakarta metropolitan corridors.
China
Shandong and Jiangsu province processors drive bulk procurement of Newcastle disease and avian influenza vaccines. NMPA compulsory immunization mandates compress procurement cycles across commercial operations. Yangtze River Delta biologics facilities in Shanghai and Suzhou manufacture attenuated strain preparations for domestic distribution.
Vietnam
Mekong Delta duck farming cooperatives negotiate directly with vaccine distributors, bypassing traditional veterinary clinic channels. The country's national agricultural regulator enforces residue limits aligned with export market requirements. Commercial operations around Can Tho and An Giang provinces deploy high-pressure liquid jet injectors for mass vaccination protocols.
Thailand
Bangkok and Nakhon Pathom commercial farm consolidation creates concentrated demand for multivalent vaccine protocols. EU Green Deal residue standards on duck meat exports accelerate preventive vaccination adoption over therapeutic antibiotics. Integrated meat processing operations in the Central Plains region source directly from biologics distributors.
Indonesia
Java region producer associations consolidate vaccine procurement through cooperative purchasing platforms. The country's national veterinary authority monitors divergence between domestic standards and destination-market requirements. Large-scale operations in West Java and East Java provinces integrate preventive health protocols into flock management systems.
Myanmar
Underpenetrated commercial duck sectors lack established veterinary service networks, creating first-mover advantage for oral delivery formats. The national livestock development program builds cold-chain infrastructure for biologics distribution. Yangon and Mandalay corridors represent emerging demand centers as commercial operations formalize.
Duck Medicine and Vaccines Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated biologics developers commanding premium positioning in vaccine formulations while regional distributors capture margin in last-mile delivery. Market structure concentrates around three tiers: multinational mammalian vaccine platforms extending into avian applications, Asian specialists in waterfowl-specific disease portfolios, and state-affiliated biologics facilities serving domestic compulsory immunization programs. Dominant competitive moves include geographic licensing partnerships for novel delivery technologies and backward integration into attenuated strain production capacity.
Within the multinational platform tier, Boehringer Ingelheim International GmbH and Merck & Co., Inc. exemplify scale-driven manufacturing archetypes, while Ceva occupies a position among European specialists with concentrated waterfowl disease expertise. Chinese limited companies including YEBIO BIOENGINEERING CO., LTD. and Jilin Zhengye Biological Products company limited represent the state-proximate biologics fabrication segment serving NMPA-mandated procurement programs.
| Leading Market Players |
|---|
| Boehringer Ingelheim International GmbH |
| Ceva |
| YEBIO BIOENGINEERING CO., LTD. |
| NAVETCO |
| Shangqiu Meilan Biological Engineering Co.,Ltd. |
| Merck & Co., Inc. |
| EGAVET |
| Bioveta, a.s. |
| Jilin Zhengye Biological Products company limited |
| Others |
Pricing and Supply Chain Analysis
China's dual carbon goals and antibiotic-free rearing mandates gate qualified supply for premium-tier duck health products, compressing margin structures for non-compliant manufacturers while elevating pricing power among certified biologics producers serving export-oriented meat processors.
Pricing Analysis
Short lead-time premiums distinguish contract-based procurement from spot inventory discounts in Southeast Asian vaccine markets. Three-tier pricing structure across premium, standard, and economy levels reflects titer stability profiles and cold-chain certification grades. Price differentiation hinges on NMPA biologics licensing status and EU Green Deal residue compliance documentation. Cost compression in economy-tier oral delivery formats is intensifying because Myanmar and Cambodian farm cooperatives prioritize volume-scale procurement over brand premiums.
Supply Chain Analysis
Domestic-content mandates in China's NMPA compulsory immunization programs are reshaping sourcing patterns for attenuated strain production. Supply concentrates in China, Vietnam, and Thailand for live virus seed stock and oil-adjuvant formulation capacity. Raw material dependencies include mineral oil derivatives, embryonated chicken eggs, and squalene-based immunostimulants. Single-source vulnerability in certified biologics facilities creates outbreak response bottlenecks. Distribution runs through producer cooperative platforms in Indonesia's Java region and direct farm contracts in Vietnam's Mekong Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The duck medicine and vaccines market sits in a technology-transition phase, with mRNA platform development displacing legacy live attenuated production methods across R&D pipelines.
For Market Incumbents: To counter mRNA platform entrants, Boehringer Ingelheim and Ceva should accelerate backward integration into attenuated strain production capacity in Yangtze River Delta biologics zones. NMPA licensing timeline compression represents a secondary threat requiring dedicated regulatory affairs investment in Beijing and Shanghai. For New Entrants and Emerging Players: Begin with oral delivery vaccine formats in Myanmar and Cambodia's underpenetrated commercial duck sectors, where veterinary service network gaps eliminate incumbent channel advantages. Direct farm distribution through producer cooperatives offers the most penetrable go-to-market angle, bypassing traditional clinic intermediary margins. For Investors and Strategic Acquirers: First NMPA approval for an avian mRNA vaccine platform is the leading indicator that manufacturing scale economics will shift decisively toward mammalian-derived production methods. Acquisition targets should emphasize state-proximate Chinese biologics fabricators with established compulsory immunization procurement relationships. Long-term viability favors integrated developers controlling both strain production and last-mile cold-chain distribution.| Strategic Initiative | Industry Significance |
|---|---|
| Attenuated Strain Production Capacity Expansion | Yangtze River Delta facilities secure NMPA-mandated procurement contracts against supply shortages. |
| Oral Delivery Format Development | Water-soluble vaccines bypass veterinary clinic channels in Myanmar's emerging commercial sector. |
| mRNA Platform Technology Transfer | Mammalian expertise from human health applications accelerates avian influenza strain-matching velocity. |
| Producer Cooperative Distribution Partnerships | Java region farm associations concentrate buying power for volume-based pricing negotiations. |
| Cold-Chain Infrastructure Investment | Guangxi and Hunan last-mile storage gaps compromise vaccine titer integrity in rural distribution. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with veterinary biologics manufacturing executives, farm operations managers, and NMPA regulatory affairs specialists. NMPA biologics licensing databases, USDA APHIS veterinary services records, and ASEAN livestock trade statistics provided validation layers. Bottom-up farm-level procurement modeling and top-down vaccine production capacity estimates were triangulated for consistency.
Granularity-level modeling tracked product type, delivery mode, end user category, and species-specific formulation requirements across the projection horizon. CAGRs were derived from segment-level volume trajectories and value-per-dose trends. NMPA compulsory immunization program expansions, EU Green Deal residue standard adoptions, and antibiotic-free rearing mandate compliance rates served as industry-specific forecast inputs.
Attenuated strain supply disruptions, mRNA platform approval delays, and ASEAN veterinary service network expansion pace are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding regulatory pathway timelines and farm consolidation rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Animal Health
Companion Animal Medicine Market
Animal Health
Companion Animal Ear Infection Treatment Market
Animal Health
Canine Mammary Tumor Treatment Market
Animal Health
Cattle Health Market
Animal Health
Global Poultry Healthcare Market
Animal Health
US Companion Animal Health Market
Animal Health
Global Farm Animal Healthcare Market
Animal Health
Global Companion Animal Health Market
Animal Health
Animal Blood Plasma Products and Derivatives Market
Animal Health
Equine Fluid Therapy Market
Animal Health
Canine Arthritis Treatment Market
Animal Health
Animal Healthcare Market
Animal Health
Companion Animal Healthcare Market
Animal Health
Cattle Healthcare Market
Animal Health
Animal Health Software Market
Animal Health
Canine Influenza Treatment Market