
 Swine Health Market | 2026-2036
Swine Health Market Size, Share, and Industry Trends Forecast 2026-2036
Swine Health Market Analytics
Commercial pork production is pivoting toward vertically integrated operations with dedicated veterinary protocols and captive breeding programs. Zoetis leverages its vaccine portfolio to anchor positions in North American sow herds, while Boehringer Ingelheim dominates respiratory disease prophylaxis through specialized injectable platforms. Elanco Animal Health extends its reach via nutritional additives that reduce antimicrobial dependence in finishing operations.
Swine health encompasses preventive, diagnostic, and therapeutic interventions designed to maintain herd productivity, with vaccines typically requiring cold-chain distribution at two to eight degrees Celsius and diagnostics relying on polymerase chain reaction or enzyme-linked immunosorbent assay methods for pathogen detection. The product type dimension shows vaccines capturing the largest revenue pool due to recurring sow-cycle administration, while nutritional additives represent the fastest-expanding category as producers substitute zinc oxide and antibiotic growth promoters with phytogenic and acidifier alternatives. Among end users, pig farmers command the dominant procurement volume, though feed manufacturers are gaining influence as premix delivery modes consolidate nutritional and therapeutic functions into single ration formulations.
The FDA's Veterinary Feed Directive and the USDA's National Animal Health Monitoring System shape product registration pathways and on-farm usage documentation requirements for antimicrobial and vaccine applications. China's Ministry of Agriculture and Rural Affairs enforces compulsory immunization schedules for classical swine fever and foot-and-mouth disease, creating baseline demand that foreign suppliers must navigate through joint ventures or local manufacturing partnerships. Stakeholders must monitor evolving residue tolerance standards and alternative protein feed regulations that will determine which health interventions retain commercial viability across major producing regions.
Market Dynamics
The swine health market pivots on antimicrobial stewardship mandates from the FDA and USDA, which are compressing antibiotic use windows and forcing producers toward preventive vaccine protocols and nutritional additives that maintain growth performance without residue risks.
Growth Catalysts
- FDA Veterinary Feed Directive:Restrictions on medically important antibiotics in feed create immediate substitution demand for phytogenic acidifiers and probiotic formulations in finishing operations.
- China's compulsory immunization schedules:Classical swine fever and foot-and-mouth disease mandates generate baseline vaccine procurement volumes that joint-venture manufacturers must fulfill through local production partnerships.
- Cold-chain infrastructure expansion:Refrigerated logistics networks in Brazil and Vietnam now sustain two-to-eight-degree Celsius distribution for mRNA and subunit vaccines previously limited to temperate markets.
Market Restraints
- Active pharmaceutical ingredient concentration:Over 70% of antibiotic and vaccine adjuvant precursors originate from Chinese chemical manufacturers, exposing formulators to supply disruption and price volatility.
- Regulatory friction from residue tolerance divergence:The EU's maximum residue limits for tetracyclines and sulfonamides remain stricter than Codex Alimentarius standards, forcing exporters to maintain dual formulation inventories.
- Biosecurity capital intensity:Danish-style compartmentalized production systems require perimeter fencing, shower-in protocols, and air filtration that independent farms in Eastern Europe cannot finance.
Strategic Opportunities
- Vietnam's herd modernization:African swine fever restocking programs favor suppliers offering integrated diagnostic-vaccine-nutrition packages over single-product vendors.
- EU Green Deal farm-to-fork targets:The 50% antimicrobial reduction mandate by 2030 creates guaranteed demand for novel feed enzymes and immunomodulatory additives that replace growth-promoting antibiotics.
- Point-of-care PCR convergence:Portable thermocycler technology combined with smartphone result interpretation allows veterinarians to bypass centralized laboratory bottlenecks in remote Canadian prairie operations.
Industry Challenges
- Veterinary diagnostic specialization gaps:Swine-specific molecular pathogen identification requires training programs that universities in Poland and Romania have not scaled to match commercial laboratory demand.
- Legacy farm management software integration:Health intervention data from smart syringes and electronic ear tags must reconcile with decades-old herd recording systems that dominate independent farm operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Swine Health Market |
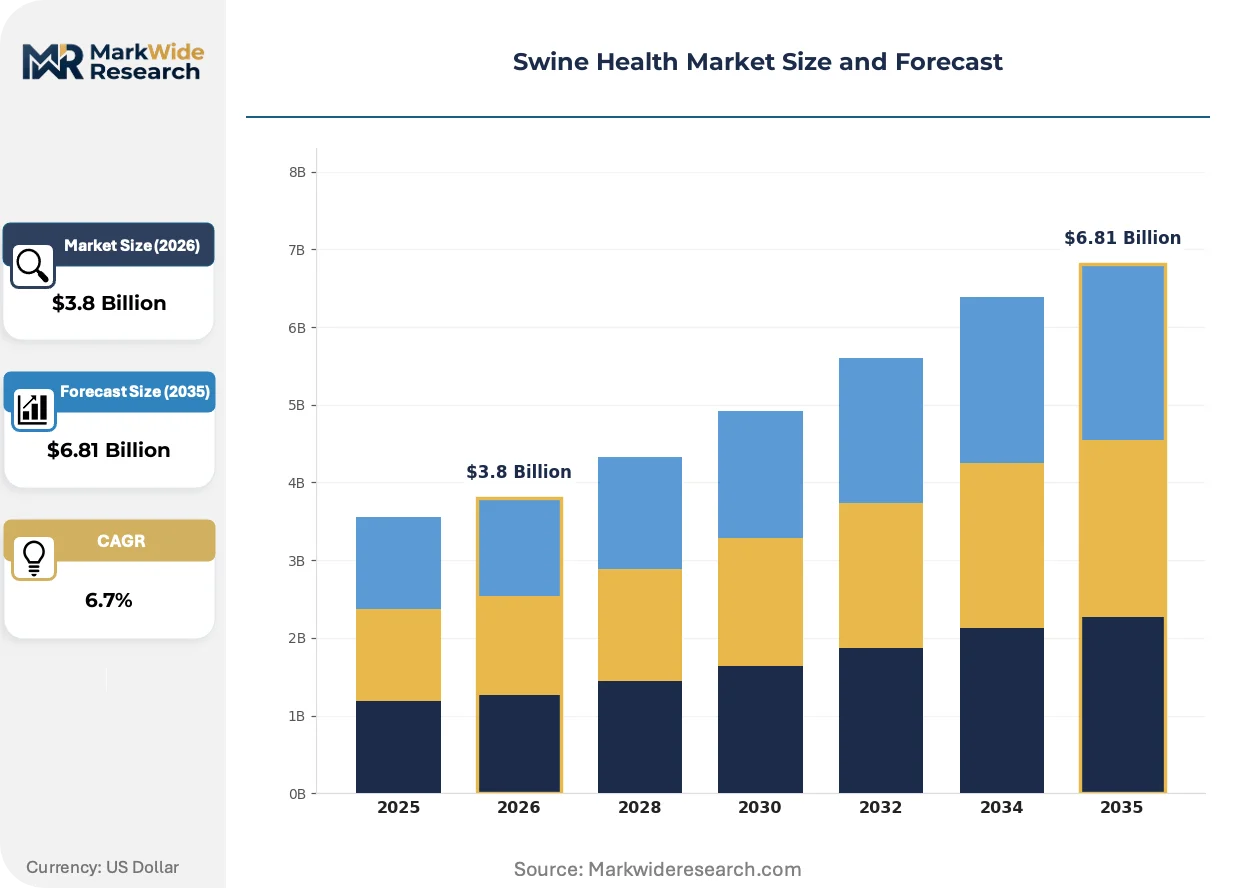
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccines, Diagnostics, Therapeutics, Nutritional Additives End User: Pig Farmers, Veterinarians, Research Institutions, Feed Manufacturers Application: Preventive Healthcare, Disease Management, Nutritional Support, Biosecurity Delivery Mode: Injections, Oral, Feed Additives, Topical |
| Companies Covered | Elanco Animal Health, Virbac, Zoetis, HIPRA, Vetoquinol, Merck, Ceva Sante Animale, Phibro Animal Health, Boehringer Ingelheim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Swine Health Market Evolving Landscape
Digital traceability and precision dosing technologies are compressing the feedback loop between pathogen detection and intervention deployment, collapsing response times from days to hours in integrated production systems.
mRNA vaccine platforms are unifying antigen design flexibility with rapid strain-matching capabilities. Large-scale sow operations in Iowa and North Carolina adopt these formulations within 18-month approval windows. The technology is unifying previously separate vaccine development timelines for emerging porcine reproductive and respiratory syndrome variants.
The EU's F-Gas Regulation and delegated acts on fluorinated greenhouse gases now restrict hydrofluorocarbon use in vaccine refrigeration equipment. Pharmaceutical cold-chain operators must retrofit transport containers with natural refrigerant alternatives or face equipment obsolescence. Spanish and Italian distribution hubs are converting to propane-based cooling systems ahead of the 2030 phase-down deadlines.
Feed mill consolidation is compressing premix procurement decisions into fewer technical buyers who specify health additive bundles rather than discrete ingredients. This concentrates vendor negotiation leverage with integrated pork processors in Germany and the Netherlands that operate captive feed manufacturing. The shift is most visible in Denmark, where two cooperatives control 80% of national compound feed volume and demand multi-year performance guarantees from additive suppliers.
Swine Health Market Segmentation
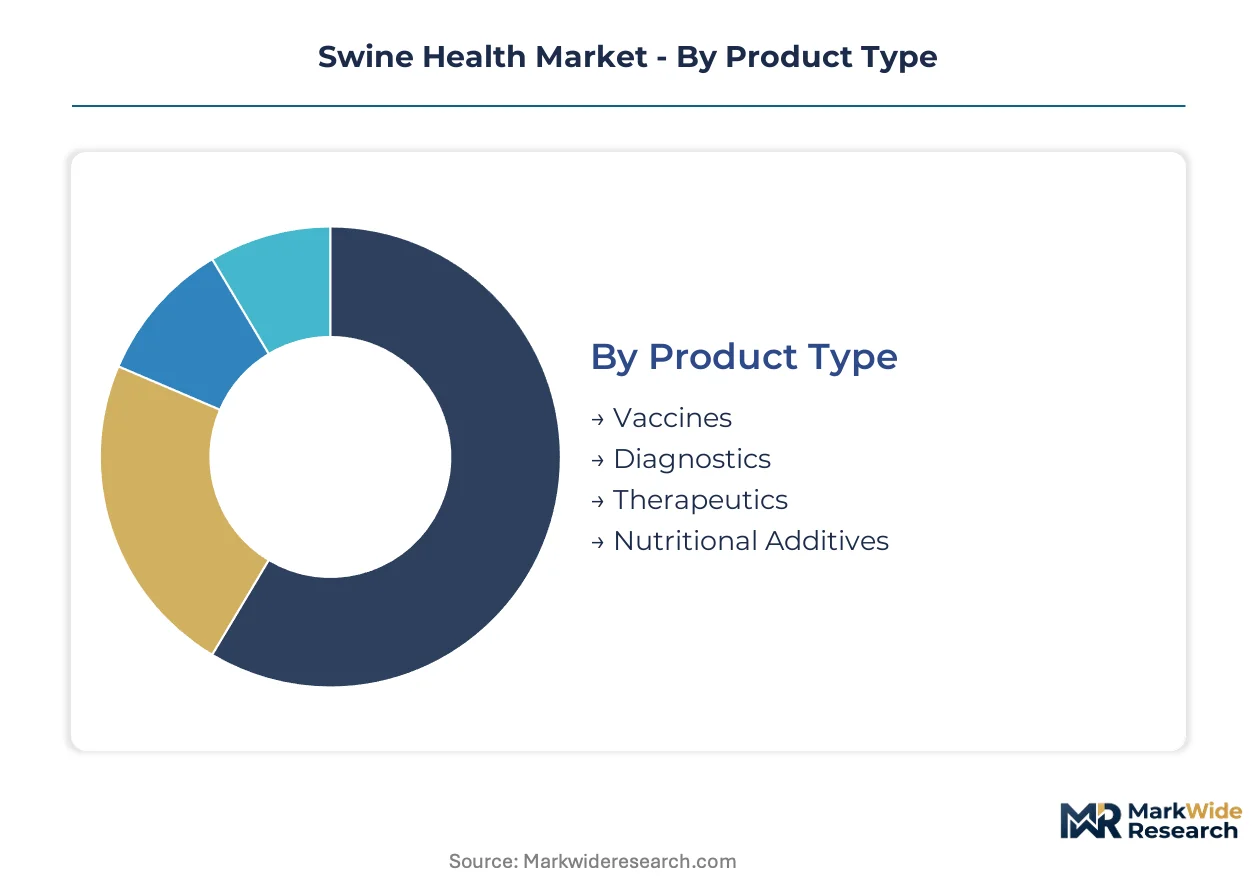
Swine health procurement varies sharply by production scale and biosecurity sophistication. Large integrated operations demand bundled preventive solutions, while independent farms prioritize discrete therapeutic interventions. Understanding these segment boundaries clarifies where formulation innovation meets purchasing power.
Product Type:
Standardized commodity formulations dominate volume sales, yet customized strain-specific vaccines command premium positioning in breeding herds.
- Vaccines:Multivalent formulations targeting porcine reproductive and respiratory syndrome, circovirus, and Mycoplasma hyopneumoniae require cold-chain distribution at two to eight degrees Celsius. Sow-cycle revaccination schedules in Iowa and North Carolina generate recurring demand that anchors manufacturer revenue stability.
- Nutritional Additives:Phytogenic extracts, organic acids, and probiotic cultures replace zinc oxide and antibiotic growth promoters in finishing rations. German and Dutch feed manufacturers specify these additives to meet EU Green Deal residue reduction mandates.
- Diagnostics:PCR and ELISA platforms detect classical swine fever, African swine fever, and foot-and-mouth disease antigens. China's Ministry of Agriculture and Rural Affairs mandates testing protocols that sustain baseline procurement volumes.
- Therapeutics:Antimicrobial injections and anti-inflammatory formulations face compressed use windows under FDA Veterinary Feed Directive restrictions.
Most installed capacity flows through Vaccines. Expansion is steepest in Nutritional Additives.
End User:
Procurement authority concentrates with technical buyers who specify health intervention bundles rather than discrete ingredients.
- Pig Farmers:Large-scale sow operations in Denmark and Spain deploy dedicated veterinary protocols with captive breeding programs. These operators negotiate multi-year supply agreements covering vaccines, diagnostics, and nutritional premixes.
- Feed Manufacturers:German and Dutch compound feed producers consolidate additive procurement decisions for integrated pork processors. Two Danish cooperatives control eighty percent of national feed volume and demand performance guarantees from suppliers.
- Veterinarians:Field practitioners in Poland and Romania prescribe treatment protocols but face diagnostic specialization gaps that limit molecular pathogen identification capacity.
- Research Institutions:Universities and government laboratories in Brazil and Vietnam validate vaccine efficacy for local strain variants.
Procurement volume concentrates with Pig Farmers. Technical influence is shifting fastest toward Feed Manufacturers.
Application:
Cost-tier stratification separates premium preventive protocols from reactive disease management interventions.
- Preventive Healthcare:Vaccination schedules and nutritional optimization protocols maintain herd productivity before pathogen exposure. Brazilian integrated producers invest in perimeter fencing, shower-in protocols, and air filtration systems that reduce therapeutic dependence.
- Disease Management:Therapeutic interventions target active infections with antimicrobial or antiviral formulations. African swine fever restocking programs in Vietnam favor suppliers offering integrated diagnostic-vaccine-nutrition packages.
- Nutritional Support:Feed additives address gut health, immune modulation, and growth performance without pharmaceutical residues.
- Biosecurity:Danish-style compartmentalized production systems require capital investments that independent Eastern European farms cannot finance.
Capital deployment concentrates in Preventive Healthcare. Policy pressure is intensifying fastest around Disease Management.
Delivery Mode:
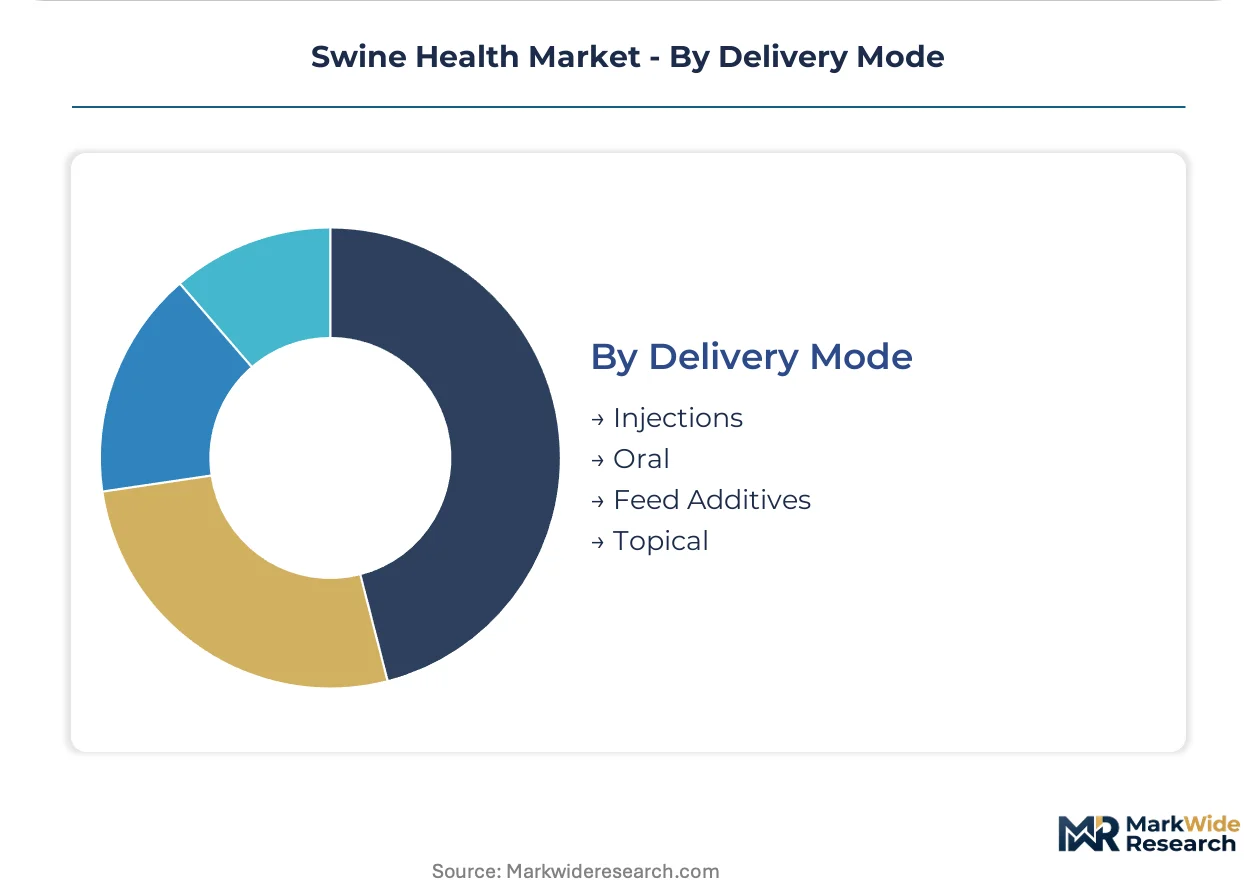
Volume scale separates mass-administration feed routes from precision injectable platforms requiring veterinary oversight.
- Injections:Intramuscular and subcutaneous delivery ensures precise dosing for vaccines and therapeutic formulations. Boehringer Ingelheim's respiratory disease prophylaxis platforms target this route in North American sow herds.
- Feed Additives:Premix incorporation at compound feed mills enables mass administration across finishing populations. Elanco Animal Health extends reach through nutritional additives distributed via this channel.
- Oral:Water-soluble medications and oral vaccines suit nursery and grower populations with limited handling infrastructure.
- Topical:External parasiticides and wound treatments address localized conditions in outdoor farrowing systems.
Administration volume concentrates in Feed Additives. Precision requirements are expanding fastest in Injections.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping swine health procurement as integrated producers migrate toward jurisdictions with harmonized residue standards and subsidized biosecurity infrastructure. Cost-of-compliance gaps between the FDA's Veterinary Feed Directive and China's compulsory immunization schedules are accelerating cross-border investment in captive breeding facilities.
United States
Iowa and North Carolina sow operations drive demand for multivalent respiratory vaccines and precision dosing technologies. The FDA's Veterinary Feed Directive restricts medically important antibiotics in feed, forcing finishing operations toward phytogenic acidifiers and probiotic formulations. Des Moines-based feed manufacturers negotiate multi-year supply agreements covering vaccine portfolios and nutritional premixes.
China
Herd recovery programs following African swine fever outbreaks sustain baseline procurement of classical swine fever and foot-and-mouth disease vaccines. The Ministry of Agriculture and Rural Affairs enforces compulsory immunization schedules that joint-venture manufacturers must fulfill through local production partnerships. Guangdong Province biosecurity upgrades concentrate demand for diagnostic platforms and perimeter fencing systems.
Germany
EU Green Deal farm-to-fork targets mandate 50% antimicrobial reduction by 2030, creating guaranteed demand for novel feed enzymes and immunomodulatory additives. Lower Saxony compound feed producers consolidate procurement decisions for integrated pork processors operating captive feed manufacturing. EFSA residue tolerance standards exceed Codex Alimentarius thresholds, forcing exporters to maintain dual formulation inventories.
Brazil
Large-scale integrated producers in Mato Grosso and Santa Catarina invest in Danish-style compartmentalized production systems with perimeter fencing and air filtration. Cold-chain infrastructure expansion now sustains two-to-eight-degree Celsius distribution for mRNA and subunit vaccines previously limited to temperate markets. ANVISA registration pathways determine which health interventions retain commercial viability across major producing regions.
Vietnam
African swine fever restocking programs favor suppliers offering integrated diagnostic-vaccine-nutrition packages over single-product vendors. Refrigerated logistics networks in the Mekong Delta sustain vaccine distribution for sow-cycle revaccination schedules. Government-funded veterinary diagnostic laboratories validate vaccine efficacy for local strain variants.
Swine Health Market Competitive Landscape
Portfolio diversification dominates the current landscape as animal health conglomerates consolidate vaccine, diagnostic, and nutritional additive capabilities under unified technical service organizations. The vendor base clusters around three strategic archetypes: multinational pharmaceutical conglomerates with captive R&D infrastructure, regional specialists leveraging local strain knowledge, and feed-additive pure-plays riding premix consolidation trends. M&A activity and technology licensing agreements represent the dominant competitive moves, with acquisitions targeting molecular diagnostic platforms and novel adjuvant formulations.
Within the multinational conglomerate tier, Zoetis and Boehringer Ingelheim exemplify integrated vaccine-platform strategies, while Elanco Animal Health occupies a position bridging pharmaceutical and nutritional intervention categories. These entities anchor the competitive structure through multi-year supply agreements with large-scale sow operations and feed manufacturing cooperatives.
| Leading Market Players |
|---|
| Elanco Animal Health |
| Virbac |
| Zoetis |
| HIPRA |
| Vetoquinol |
| Merck |
| Ceva Sante Animale |
| Phibro Animal Health |
| Boehringer Ingelheim |
| Others |
Value Network & Pricing Analysis
Feed manufacturing cooperatives in Denmark and the Netherlands concentrate procurement leverage for nutritional additives, compressing vendor margins through multi-year performance guarantees and bundled contract structures. This buyer consolidation forces suppliers to absorb cold-chain logistics costs within headline pricing rather than passing through distribution premiums.
Pricing Analysis
Distributor margins on veterinary vaccines absorb cold-chain logistics premiums that manufacturers cannot pass through to integrated sow operations. Pricing stratifies across strain-specific premium formulations, standard multivalent platforms, and economy-tier commodity vaccines based on adjuvant sophistication and local registration status. Cost compression in standard-grade vaccines intensifies as Chinese joint-venture producers expand regional manufacturing capacity. Independent pig farmers in Eastern Europe exhibit highest price sensitivity, while Danish cooperatives negotiate value-based contracts tied to herd performance metrics.
Supply Chain Analysis
Regional distribution centers in Iowa, North Carolina, and Guangdong Province operate hub-and-spoke patterns for temperature-controlled vaccine logistics. Active pharmaceutical ingredient production draws from Chinese chemical manufacturers, Indian adjuvant suppliers, and German fermentation specialists. Single-source vulnerability concentrates in mRNA lipid nanoparticle precursors where qualified alternative suppliers remain limited. Distribution runs through pharmaceutical wholesalers with veterinary specialization, though direct manufacturer-to-feed-mill channels are gaining share for nutritional additives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between the FDA's Veterinary Feed Directive and China's compulsory immunization schedules creates geographic-arbitrage opportunities for suppliers with dual-registration capabilities. Producers can capture margin premiums by locating formulation capacity in jurisdictions with harmonized residue standards.
For Market Incumbents: Hedge against API supply disruption by securing captive manufacturing partnerships for adjuvant precursors in India and alternative lipid nanoparticle sources outside China. Reinforce channel control through direct technical service deployments to Danish and Dutch feed manufacturing cooperatives, converting transactional supply relationships into multi-year performance contracts that lock out competitor access. For New Entrants and Emerging Players: Capture white-space opportunity in Vietnam's African swine fever restocking programs by offering integrated diagnostic-vaccine-nutrition packages that incumbent single-product vendors cannot match. Target Poland and Romania's veterinary diagnostic specialization gaps through portable PCR platforms with smartphone result interpretation, bypassing centralized laboratory infrastructure requirements. For Investors and Strategic Acquirers: Animal health conglomerates with captive R&D infrastructure are the most active acquirers in this space, prioritizing molecular diagnostic platforms and novel adjuvant formulations that fill portfolio gaps. Long-term viability hinges on exposure to preventive healthcare substitution trends rather than therapeutic antimicrobial dependence. Watch for EU Green Deal implementation acceleration as the inflection signal for immunomodulatory additive demand.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Manufacturing | Local production partnerships in China satisfy compulsory immunization procurement mandates from the Ministry of Agriculture and Rural Affairs. |
| Cold-Chain Infrastructure Expansion | Refrigerated logistics networks in Brazil and Vietnam enable mRNA vaccine distribution previously limited to temperate markets. |
| Diagnostic Platform Acquisition | Portable PCR technology allows veterinarians to bypass centralized laboratory bottlenecks in remote Canadian prairie operations. |
| Nutritional Additive Portfolio Expansion | Phytogenic and acidifier formulations replace zinc oxide growth promoters under EU Green Deal residue reduction mandates. |
| Technical Service Organization Buildout | Dedicated veterinary protocols anchor multi-year supply agreements with large-scale sow operations in Iowa and North Carolina. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region combined with secondary validation. Interviews with swine health product managers, feed manufacturing procurement leads, veterinary diagnostic laboratory directors, and regulatory affairs specialists informed demand-side assumptions. Secondary sources included FDA Veterinary Feed Directive filings, USDA National Animal Health Monitoring System reports, EMA veterinary product registrations, and China's Ministry of Agriculture compulsory immunization schedules. Bottom-up segment sizing triangulated against top-down market value estimates.
Rate-of-change decomposition separated volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, end user category, application purpose, and delivery mode, with additional granularity on cold-chain requirements and regulatory registration pathways. CAGRs were derived from installed base expansion, replacement cycle analysis, and policy-driven substitution elasticities. Forecast inputs incorporated African swine fever restocking trajectories, antimicrobial stewardship implementation timelines, and feed mill consolidation patterns.
African swine fever recurrence, regulatory residue tolerance divergence, and API supply disruption are the dominant revision risks to baseline projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Animal Health
African Horse Sickness Treatment Market
Animal Health
US Companion Animal Health Market
Animal Health
Companion Animal Medicine Market
Animal Health
Swine Healthcare Market
Animal Health
Canine Influenza Treatment Market
Animal Health
Equine Healthcare Market
Animal Health
Animal Health Market
Animal Health
Canada Animal Health Care Market
Animal Health
Rat Model Market
Animal Health
Global Farm Animal Healthcare Market
Animal Health
Canine Mammary Tumor Treatment Market
Animal Health
Companion Animal Healthcare Market
Animal Health
Global Companion Animal Health Market
Animal Health
Equine Fluid Therapy Market
Animal Health
Duck Medicine and Vaccines Market
Animal Health
Companion Animal Ear Infection Treatment Market