
 Artificial Intelligence (AI) in Animal Health Market | 2026-2036
Artificial Intelligence (AI) in Animal Health Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence (AI) in Animal Health Market Analytics
Aftermarket service revenue from AI model retraining and diagnostic algorithm updates is reconfiguring profitability away from one-time hardware sales. Zoetis Services LLC leverages its installed base of diagnostic instruments to secure recurring software subscription income. IDEXX Laboratories, Inc. anchors its competitive position through deep integration of machine learning into reference laboratory workflows. Heska Corporation differentiates by concentrating on point-of-care AI tools for companion animal practices.
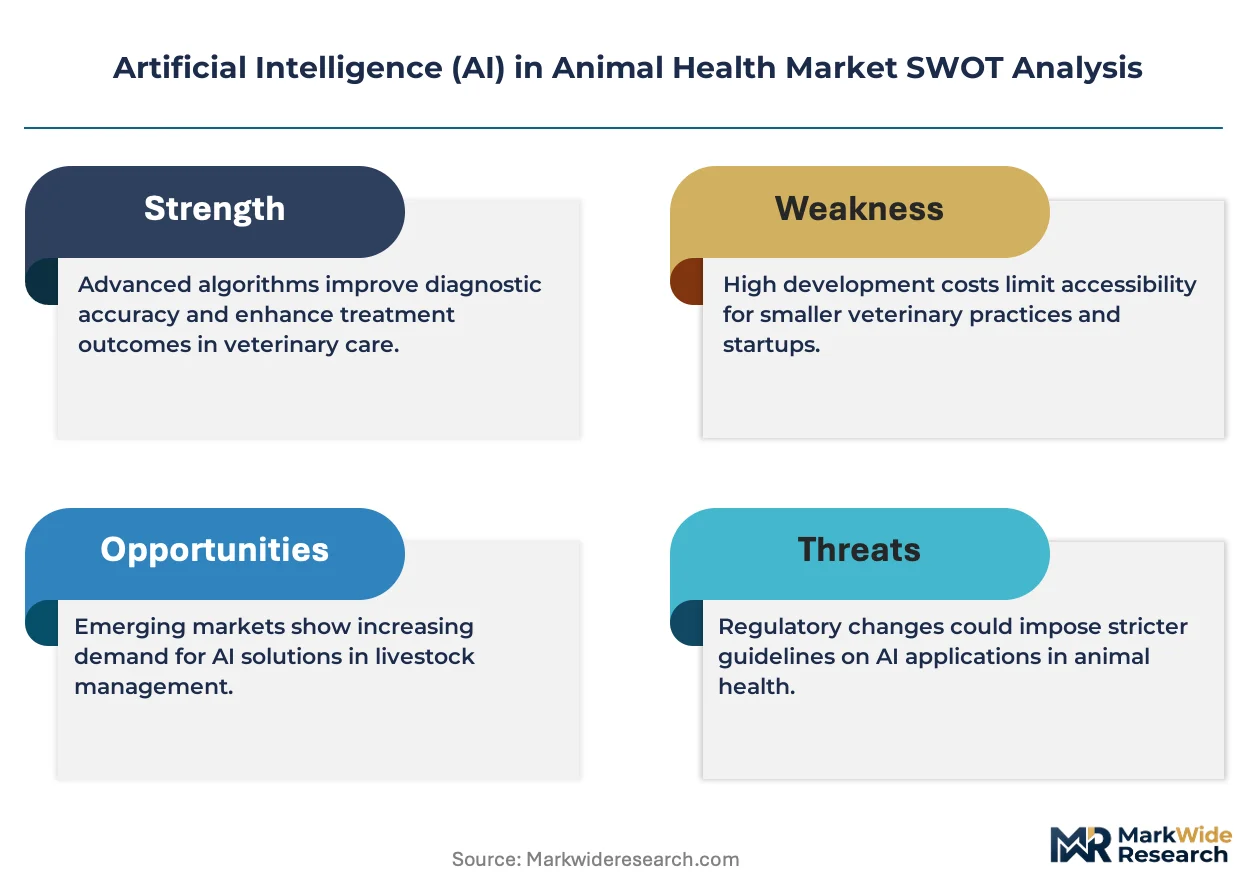
Artificial Intelligence in Animal Health encompasses computational systems that process veterinary imaging, acoustic sensor data, and electronic health records through machine learning architectures to detect pathologies, predict disease onset, and optimize treatment protocols. Neural networks trained on radiographic datasets now achieve diagnostic sensitivity comparable to board-certified veterinary radiologists for select conditions. Diagnostic Tools command the largest revenue share as practices replace conventional microscopy and culture methods with automated AI interpretation. Predictive Analytics is expanding fastest among technology segments, driven by farm-level demand for early mastitis and metabolic disorder detection in dairy cattle. Monitoring Systems targeting livestock environments are maturing as hardware commoditizes, pushing margin pools toward the data analytics layers that aggregate multisource sensor inputs.
FDA's Center for Veterinary Medicine applies software-as-a-medical-device criteria to AI diagnostic platforms, creating compliance costs that favor established players with regulatory affairs infrastructure. USDA's Animal and Plant Health Inspection Service coordinates with state veterinarians on AI-enabled disease surveillance reporting standards for notifiable conditions. The European Medicines Agency's veterinary regulatory framework through the Committee for Medicinal Products for Veterinary Use is developing guidelines for AI-supported pharmacovigilance signal detection. Stakeholders must monitor whether regulatory divergence between FDA and EMA veterinary AI pathways fragments product development strategies or creates harmonization opportunities through mutual recognition agreements.
Market Dynamics
The transition from capital-intensive hardware sales to recurring software subscriptions is restructuring profitability pools across veterinary diagnostics, with algorithm update revenue now commanding margin premiums over instrument placements.
Growth Catalysts
- Software-as-a-Medical-Device Framework:FDA's evolving criteria for veterinary AI platforms creates regulatory clarity that accelerates product commercialization timelines for diagnostic developers.
- Dairy Precision Livestock Farming:Farm operators in the United States deploy acoustic sensors and computer vision for automated mastitis detection, reducing labor-intensive manual screening.
- Neural Network Architectures:Deep learning models trained on expanding radiographic datasets achieve diagnostic parity with specialist veterinarians for select orthopedic and thoracic conditions.
Market Restraints
- Regulatory Compliance Costs:FDA's software-as-a-medical-device pathway imposes documentation and clinical validation burdens that disadvantage early-stage developers lacking regulatory affairs infrastructure.
- Data Silo Fragmentation:Electronic health record systems across companion animal practices lack interoperability standards, constraining multi-source training data aggregation for algorithm development.
- Hardware Commoditization:Sensor and edge computing component costs decline rapidly, compressing margins for monitoring system manufacturers unable to migrate revenue to analytics layers.
Strategic Opportunities
- EU AI Act Alignment:Veterinary AI developers can leverage emerging European Union artificial intelligence regulations to establish compliance templates that accelerate multi-jurisdiction market access.
- Pharmacovigilance Signal Detection:EMA's Committee for Medicinal Products for Veterinary Use is developing frameworks for AI-supported adverse event monitoring, opening specialized service revenue streams.
- Point-of-Care Convergence:Integration of machine learning interpretation with portable imaging devices enables diagnostic capability extension into rural and mobile veterinary settings.
Industry Challenges
- Veterinary Data Science Talent Scarcity:The intersection of clinical veterinary expertise and machine learning engineering remains underpopulated, slowing algorithm development cycles and increasing compensation costs for qualified personnel.
- Legacy System Integration Friction:Established practice management software architectures resist API connectivity with cloud-based AI diagnostic platforms, forcing costly middleware development or workflow disruption.
- Algorithm Validation Protocol Standardization:Absence of harmonized benchmark datasets and performance metrics across species and pathology types complicates regulatory submission preparation and cross-product comparability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence (AI) in Animal Health Market |
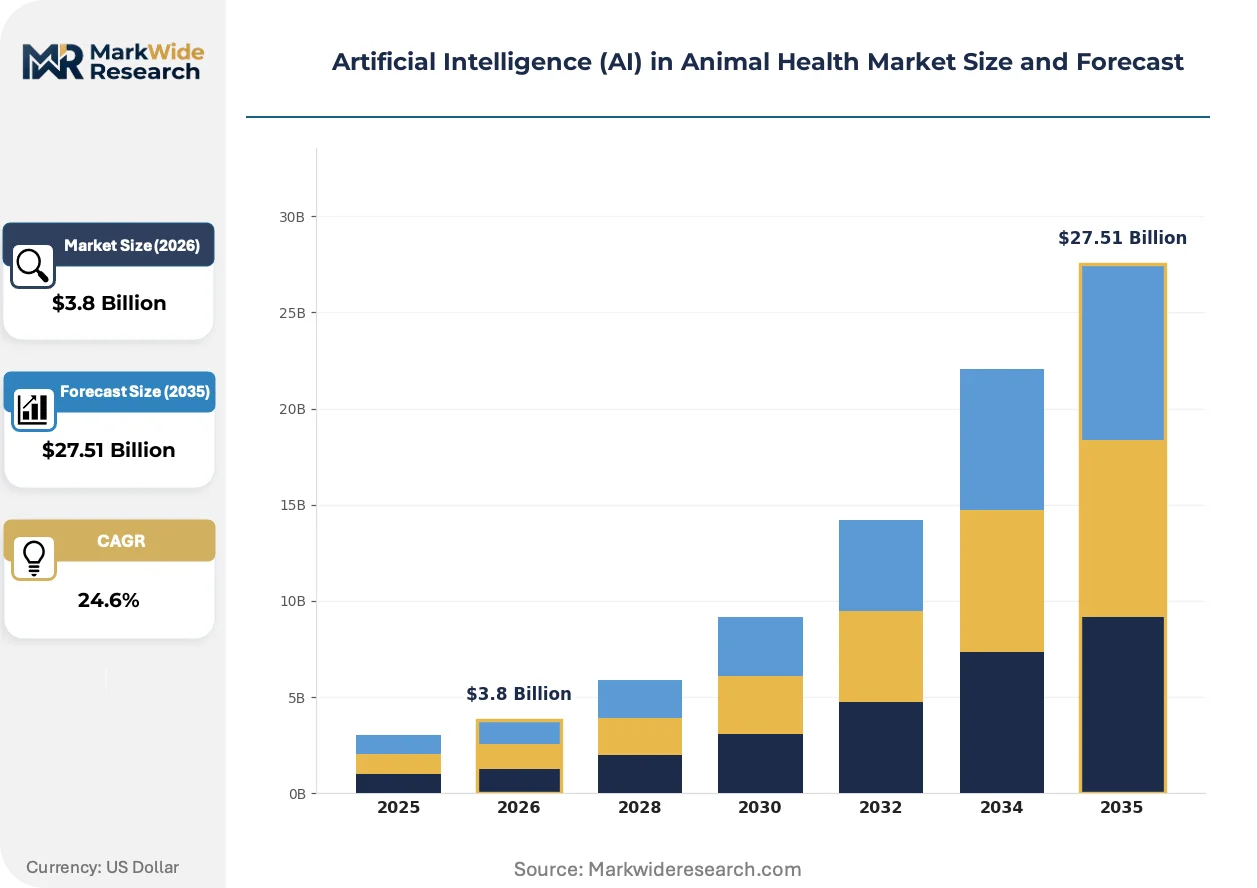
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.51 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Tools, Treatment Solutions, Monitoring Systems, Data Analytics Software Application: Livestock Management, Veterinary Diagnostics, Pet Care, Disease Prediction End User: Veterinarians, Animal Clinics, Research Institutions, Farms Technology: Machine Learning, Neural Networks, Natural Language Processing, Predictive Analytics |
| Companies Covered | Merck & Co., Inc., Heska Corporation, Zoetis Services LLC, Vetology LLC, ImpriMed, Inc., IDEXX Laboratories, Inc., SignalPET, Connecterra, Mars Petcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence (AI) in Animal Health Market Evolving Landscape
Computational architectures are converging with sensor hardware to enable real-time pathology detection at the network edge, displacing batch-processing workflows that required cloud transmission and specialist interpretation delays.
Multimodal deep learning is hybridizing radiographic imaging with acoustic biomarker analysis and electronic health record temporal patterns to generate holistic diagnostic scores that exceed single-modality accuracy thresholds. Large dairy cooperatives in Denmark and the Netherlands deploy these integrated systems for metabolic disorder prediction, compressing the interval between physiological deviation and therapeutic intervention from days to hours. The structural consequence is a shift from reactive treatment protocols toward preemptive nutritional and pharmaceutical adjustments that preserve milk yield curves.
EMA's veterinary regulatory framework through CVMP is developing explicit guidelines for AI-supported pharmacovigilance signal detection, mandating algorithmic transparency and training data documentation standards that will reshape post-market surveillance obligations. Pharmaceutical manufacturers must now embed machine learning modules within adverse event reporting systems or outsource to specialized analytics providers, increasing compliance operational expenditures. Companion animal vaccine developers face the steepest adaptation curve given the volume and heterogeneity of spontaneous reporting data they manage.
Subscription-based diagnostic access is displacing perpetual license purchases as the dominant commercial model, with practices preferring per-case interpretation fees that align costs with utilization rather than capital deployment. Independent companion animal hospitals in metropolitan United States markets lead this transition, driven by cash flow constraints and uncertainty regarding technology obsolescence cycles. Equipment financing arrangements now incorporate mandatory software update clauses that lock buyers into multi-year algorithm maintenance commitments, restructuring vendor-customer relationships toward continuous engagement rather than transactional equipment replacement.
Artificial Intelligence (AI) in Animal Health Market Segmentation
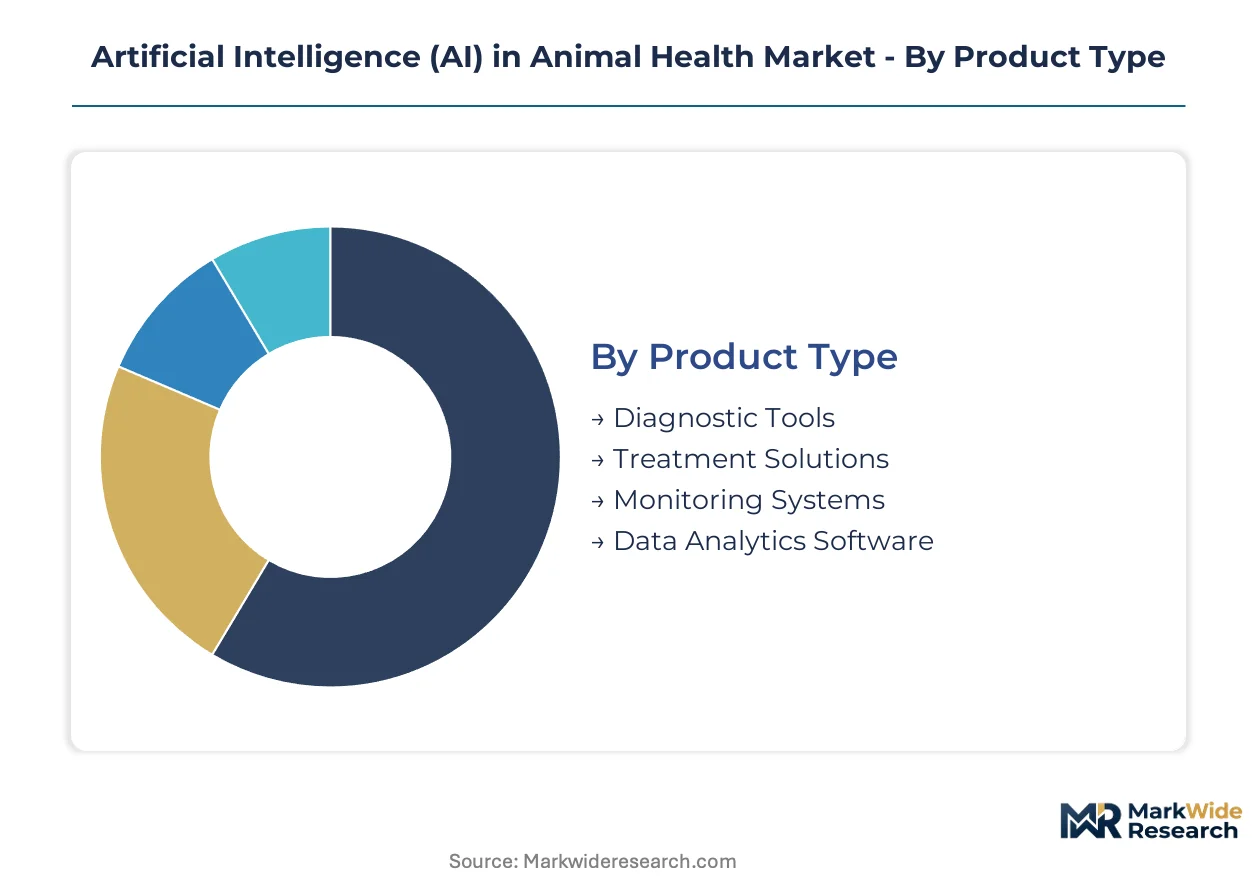
Segmentation in veterinary AI reveals divergent technology maturities and buyer economics across product architectures. Diagnostic tools and predictive analytics command fundamentally different margin structures than hardware-centric monitoring systems. Understanding these divides clarifies where capital deployment concentrates and where algorithmic differentiation creates defensible positions.
Product Type:
Cost tier stratification separates capital-intensive hardware placements from recurring software revenue streams with divergent payback periods.
- Diagnostic Tools:Automated imaging interpretation and pathology detection systems replace conventional microscopy and culture methods. Demand concentrates in companion animal specialty practices across the United States, where labor costs for specialist interpretation exceed algorithmic per-case fees. FDA's software-as-a-medical-device pathway imposes validation documentation burdens that favor established diagnostic instrument manufacturers with regulatory affairs infrastructure.
- Monitoring Systems:Acoustic sensors, computer vision cameras, and wearable biologgers capture continuous physiological data from livestock environments. Dairy cooperatives in Denmark and the Netherlands deploy these systems for automated mastitis detection, compressing screening intervals from daily manual checks to real-time alerts. Hardware component costs decline rapidly, pushing margin pools toward data aggregation and analytics layers.
- Treatment Solutions:AI-optimized dosing protocols and therapeutic recommendation engines.
- Data Analytics Software:Cloud platforms aggregating multisource inputs for herd-level or practice-level decision support.
Diagnostic Tools hold installed capacity. Data Analytics Software is rotating up the share rankings.
Application:
Volume concentration varies dramatically between production agriculture and companion animal settings, with livestock operations driving sensor hardware scale and veterinary clinics anchoring diagnostic software utilization.
- Livestock Management:Precision farming systems deploy computer vision and acoustic monitoring for feed optimization, reproductive timing, and early disease detection. Large dairy operations in the United States and the Netherlands generate the densest sensor deployment, where marginal milk yield improvements justify capital expenditure. USDA's Animal and Plant Health Inspection Service coordinates with state veterinarians on AI-enabled disease surveillance reporting standards.
- Veterinary Diagnostics:Point-of-care and reference laboratory AI interpretation of radiographs, cytology, and histopathology. Metropolitan companion animal hospitals in the United States lead adoption, driven by specialist shortage and client expectation for rapid turnaround. IDEXX Laboratories anchors competitive position through deep workflow integration.
- Pet Care:Consumer-facing applications including symptom checkers and remote monitoring for companion animals.
- Disease Prediction:Predictive models for outbreak detection and epidemiological surveillance across animal populations.
Livestock Management captures the steepest expansion trajectory as dairy cooperatives digitize. Veterinary Diagnostics retains the revenue concentration.
End User:
Customer type determines purchasing authority, with veterinarians controlling diagnostic software decisions and farm operators driving monitoring system procurement.
- Veterinarians:Individual practitioners and specialist consultants selecting point-of-care diagnostic tools. Heska Corporation concentrates product development here, prioritizing portable imaging with embedded interpretation for mobile and rural settings.
- Animal Clinics:Multi-doctor practices and corporate veterinary groups negotiating enterprise software licenses. Subscription-based access models displace perpetual licenses as cash flow constraints reshape procurement preferences.
- Research Institutions:Academic veterinary schools and pharmaceutical research organizations developing training datasets and validation protocols.
- Farms:Dairy, beef, swine, and poultry operations deploying sensor networks and predictive analytics for production optimization.
Veterinarians command diagnostic software selection authority. Farms are gaining procurement influence as livestock AI scales.
Technology:
Maturity gradients separate proven neural network architectures from emerging natural language processing applications in veterinary contexts.
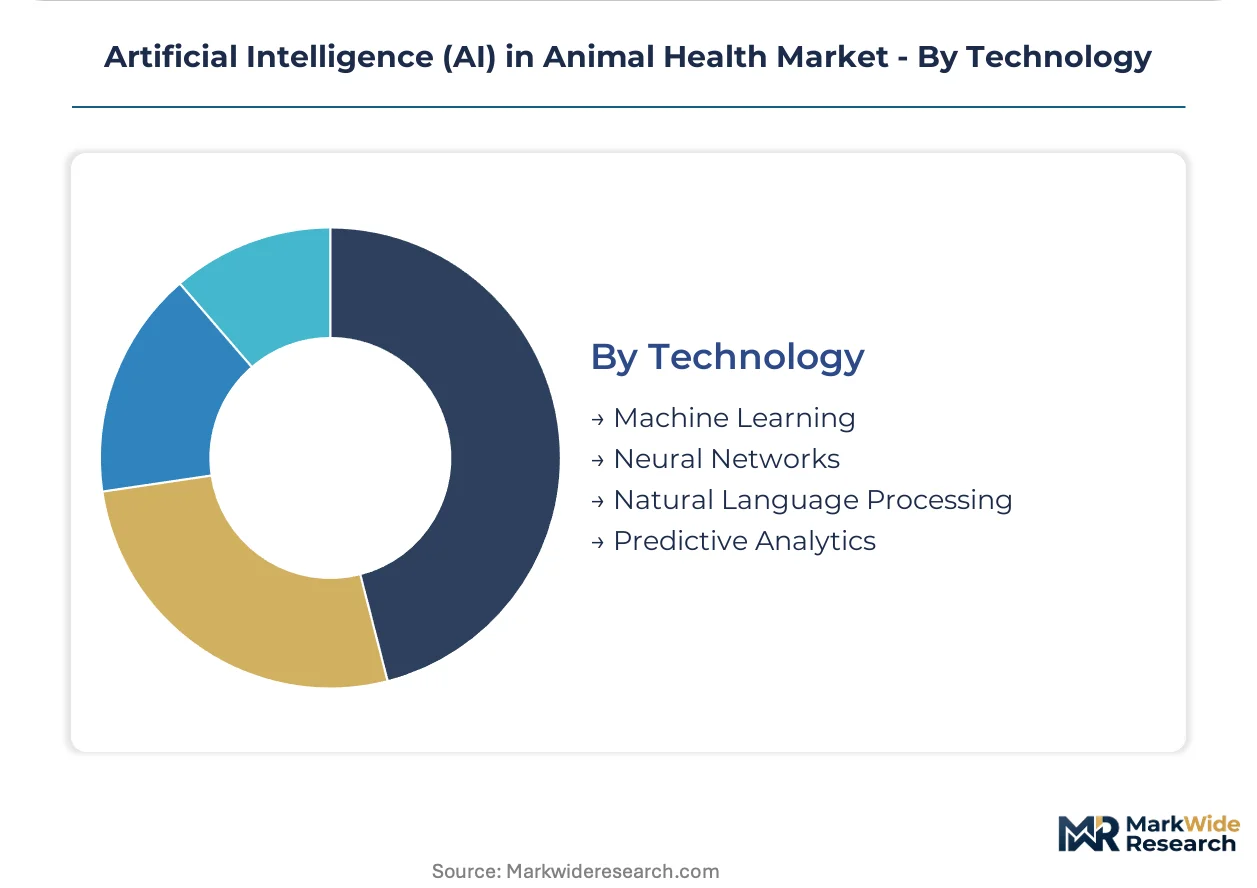
- Machine Learning:Supervised classification and regression models trained on structured veterinary datasets. These architectures underpin most deployed diagnostic applications with established validation protocols.
- Neural Networks:Deep learning models achieving diagnostic parity with board-certified veterinary radiologists for select orthopedic and thoracic conditions. Training data requirements and computational costs limit deployment to well-capitalized developers.
- Natural Language Processing:Text analysis of electronic health records and clinical notes for automated coding and decision support. Interoperability constraints across practice management systems slow implementation.
- Predictive Analytics:Temporal pattern recognition for disease onset forecasting and production parameter optimization. This segment is climbing the fastest as farm-level demand for early mastitis and metabolic disorder detection accelerates.
Neural Networks retain technical leadership. Predictive Analytics is gaining commercial traction fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates AI diagnostic utilization in companion animal specialty practices, while Denmark and the Netherlands deploy sensor networks at farm density levels unmatched elsewhere. China channels investment toward computer vision for livestock facial recognition. Brazil's dairy sector lags in digitization but shows accelerating venture capital interest.
United States
Metropolitan veterinary hospitals drive point-of-care AI adoption as specialist labor costs exceed algorithmic interpretation fees. FDA's Center for Veterinary Medicine applies software-as-a-medical-device criteria, creating compliance barriers that favor established diagnostic instrument manufacturers. Greater Boston hosts dense clusters of veterinary AI startups developing radiographic interpretation models.
Denmark
Large dairy cooperatives deploy acoustic sensors and computer vision for automated mastitis detection at herd scales exceeding ten thousand cattle. The Danish Veterinary and Food Administration coordinates with EU agencies on AI-enabled disease surveillance standards. The Jutland Peninsula anchors Europe's densest precision livestock farming infrastructure.
Netherlands
Farm operators integrate multisource sensor inputs for metabolic disorder prediction, compressing therapeutic intervention intervals from days to hours. The Dutch Medicines Evaluation Board participates in EMA's Committee for Medicinal Products for Veterinary Use guideline development for AI-supported pharmacovigilance. Wageningen University and Research corridors generate specialized veterinary data science talent pipelines.
China
Livestock operations pilot facial recognition and gait analysis for individual animal health tracking across swine and poultry facilities. The National Medical Products Administration develops veterinary AI regulatory frameworks parallel to human medical device pathways. Yangtze River Delta technology parks concentrate computer vision startups targeting agricultural applications.
Brazil
Dairy and beef producers show rising procurement interest in predictive analytics despite limited existing sensor infrastructure. The national agricultural regulator evaluates AI-enabled disease reporting protocols for notifiable conditions. São Paulo state veterinary schools partner with technology developers on training dataset creation for regional pathologies.
Artificial Intelligence (AI) in Animal Health Market Competitive Landscape
Capability concentration sits with specialized veterinary AI developers possessing deep clinical training data; scale advantage sits with diversified animal health conglomerates leveraging installed diagnostic instrument bases. The market structures around three tiers: pharmaceutical-backed diagnostics divisions, pure-play veterinary AI startups, and human medical imaging companies extending into animal applications. Dominant competitive moves include algorithm licensing partnerships and subscription-based commercial model transitions displacing perpetual software licenses.
Within the pharmaceutical-backed tier, Zoetis Services LLC and Merck & Co., Inc. exemplify scale-driven positions anchored by global distribution infrastructure and regulatory affairs capacity. IDEXX Laboratories, Inc. occupies a hybrid position combining reference laboratory networks with embedded machine learning development. Heska Corporation represents the point-of-care specialization archetype, concentrating on portable diagnostic tools for mobile and rural veterinary settings.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Heska Corporation |
| Zoetis Services LLC |
| Vetology LLC |
| ImpriMed, Inc. |
| IDEXX Laboratories, Inc. |
| SignalPET |
| Connecterra |
| Mars Petcare |
| Others |
Value Network & Pricing Analysis
FDA software-as-a-medical-device validation requirements determine both pricing tier spreads and supply chain configuration, concentrating premium algorithm development in established diagnostic instrument manufacturers while pushing hardware commoditization toward cost-sensitive farm operators. Compliance documentation burdens compress margins for early-stage developers lacking regulatory affairs infrastructure, restructuring procurement authority toward vendors with pre-cleared quality management systems.
Pricing Analysis
Long-term subscription contracts dominate companion animal diagnostic software, with per-case interpretation fees displacing perpetual licenses as metropolitan veterinary hospitals prioritize cash flow alignment over capital deployment. Price differentiation rests on FDA validation tier and algorithm update frequency, with SaaS tiers separating enterprise multi-practice licenses from single-clinic deployments. Cost compression in hardware-centric monitoring systems intensifies as sensor component prices decline, making farm operators the most price-sensitive segment while specialty practices absorb premium diagnostic fees.
Supply Chain Analysis
Upstream GPU and specialized AI accelerator chip supply concentrates in Taiwan and South Korea, with cloud compute infrastructure anchored in United States hyperscaler facilities. Neural network training datasets draw from radiographic archives held by IDEXX Laboratories and academic veterinary schools, creating single-source vulnerability for algorithm development pipelines. Tariff exposure runs through semiconductor import dependencies. Distribution runs through direct veterinary instrument sales forces for diagnostic tools and agricultural equipment dealers for livestock monitoring systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intersection of clinical veterinary expertise and machine learning engineering remains critically underpopulated, creating persistent bottlenecks in algorithm development cycles and inflating compensation costs for qualified personnel. This capability scarcity rewards organizations that can bridge the domain gap through structured training pipelines or strategic hiring.
For Market Incumbents: Harden regulatory affairs infrastructure against FDA software-as-a-medical-device documentation burdens that disadvantage emerging competitors lacking validation protocols. Consolidate control over training data archives through exclusive partnerships with academic veterinary schools, neutralizing substitute threats from human medical imaging companies extending into animal applications. For New Entrants and Emerging Players: Pursue point-of-care convergence opportunities in rural and mobile veterinary settings underserved by reference laboratory networks, where portable imaging with embedded interpretation commands premium positioning. Target Brazilian dairy cooperatives showing accelerating procurement interest despite limited existing sensor infrastructure, leveraging project-based implementation services as the primary go-to-market angle. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors vertically integrated diagnostic instrument manufacturers with installed base leverage over pure-play algorithm developers. Long-term viability across the projection horizon hinges on recurring software subscription revenue attaching to hardware placements. Watch FDA-EU regulatory harmonization progress as the critical inflection signal for cross-border scalability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Licensing Partnership | Enables human medical imaging companies to enter veterinary markets without clinical dataset development. |
| Subscription Model Transition | Restructures Zoetis and IDEXX revenue toward recurring software fees from perpetual diagnostic licenses. |
| Regulatory Affairs Capacity Buildout | Accelerates FDA software-as-a-medical-device pathway navigation for AI diagnostic platform developers. |
| Training Data Archive Acquisition | Secures proprietary radiographic datasets that constrain competitor algorithm development cycles. |
| Point-of-Care Hardware Integration | Extends Heska Corporation diagnostic capability into rural veterinary settings lacking specialist access. |
Research Methodology
A spread of perspectives from veterinary diagnostic instrument manufacturers, dairy cooperative operations managers, FDA regulatory affairs specialists, and academic veterinary school researchers converged on the working assumptions underlying this analysis. Primary interview data combined with secondary validation from USDA Animal and Plant Health Inspection Service surveillance protocols, EMA Committee for Medicinal Products for Veterinary Use guideline drafts, FDA Center for Veterinary Medicine premarket submission databases, and venture capital investment tracking in veterinary AI startups. Bottom-up segment sizing triangulated against top-down market aggregation across technology deployment models and end-user procurement patterns.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling adoption curves for diagnostic tools, monitoring systems, predictive analytics software, and treatment optimization platforms. Segmentation dimensions included product architecture, application setting, end-user type, and technology maturity tier. CAGRs derived from fitted growth curves applied to installed base expansion and software attach rate assumptions, with farm-level sensor deployment density and companion animal specialist labor cost inflation as primary forecast inputs.
Sensitivities concentrate around FDA-EU regulatory pathway divergence, veterinary data science talent availability, and dairy commodity price volatility affecting precision livestock farming capital expenditure cycles. Forecasts reflect assumptions regarding algorithm validation protocol standardization and cloud infrastructure cost trajectories. Material shifts in FDA software-as-a-medical-device enforcement posture or EU AI Act veterinary alignment timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Animal Health
African Horse Sickness Treatment Market
Animal Health
US Military Animals Market
Animal Health
Companion Animal Medicine Market
Animal Health
Canine Mammary Tumor Treatment Market
Animal Health
Companion Animal Healthcare Market
Animal Health
Duck Medicine and Vaccines Market
Animal Health
Global Farm Animal Healthcare Market
Animal Health
Animal Healthcare Market
Animal Health
Global Companion Animal Health Market
Animal Health
Swine Healthcare Market
Animal Health
Canine Arthritis Treatment Market
Animal Health
Equine Healthcare Market
Animal Health
Companion Animal Ear Infection Treatment Market
Animal Health
Canada Animal Health Care Market
Animal Health
Laboratory Animal Models Market
Animal Health
Animal Health Software Market