
 Congestive Heart Failure Drugs Market | 2026-2036
Congestive Heart Failure Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Congestive Heart Failure Drugs Market Intelligence
A transition from fully outsourced clinical trial management to hybrid in-house models is pivoting the development landscape for new heart failure therapies. Novartis AG leverages its extensive portfolio in cardiovascular medicine to maintain a dominant market position. AstraZeneca plc differentiates its offerings through a strong focus on SGLT2 inhibitors for expanded heart failure indications. Bristol-Myers Squibb Company competes by advancing novel drug candidates targeting specific cardiac pathways.
Congestive heart failure drugs are pharmacological agents designed to manage the complex syndrome of heart failure. These therapies function by modifying physiological pathways, such as the renin-angiotensin-aldosterone system or sodium-glucose co-transport, to improve cardiac function and reduce symptoms. Established drug classes like ACE Inhibitors and Beta Blockers constitute the foundational treatment volume. The Chronic Heart Failure therapy area is seeing the fastest value growth from newer, premium-priced medicines.
The U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA) set rigorous standards for clinical trial efficacy and safety endpoints. In parallel, market access in China is governed by the National Medical Products Administration (NMPA), which has accelerated its review process for innovative drugs. Future commercial success depends on demonstrating superior clinical outcomes to secure favorable reimbursement from both public and private payers.
Market Dynamics
The central force shaping the market is the value shift from high-volume, established generics to premium-priced, innovative therapies. This transition is underpinned by compelling clinical trial data demonstrating superior outcomes for newer drug classes in specific heart failure populations.
Growth Catalysts
- Accelerated Regulatory Pathways:China's National Medical Products Administration (NMPA) has expedited its review process for innovative drugs, speeding market access for novel heart failure therapies in a large, underserved patient population.
- Clinical Guideline Expansion:The integration of SGLT2 inhibitors into treatment guidelines for heart failure patients, regardless of diabetes status, is a significant driver, expanding the addressable patient base for Cardiology Clinics.
- Disease Prevalence:High and rising prevalence of congestive heart failure in developed nations, particularly the United States, driven by aging populations and risk factors, ensures sustained demand for effective treatments.
Market Restraints
- Payer Resistance:The high cost of novel therapies like SGLT2 inhibitors and ARNI drugs creates significant reimbursement hurdles from both public and private payers, who often require extensive cost-effectiveness data.
- Generic Competition:Established drug classes, including low-cost generic ACE Inhibitors and Beta Blockers, continue to represent the foundational treatment volume, posing a price-based competitive threat to newer, branded agents.
- Rigorous Clinical Endpoints:Stringent efficacy and safety standards set by the FDA and EMA for clinical trials increase the time, cost, and risk associated with bringing new heart failure drugs to market.
Strategic Opportunities
- Novel Target Pathways:Research into new drug candidates targeting specific cardiac pathways beyond the renin-angiotensin-aldosterone system offers significant opportunities for developing first-in-class therapies for distinct patient subgroups.
- Geographic Expansion in China:The combination of a large patient population and the NMPA's faster drug approval process creates a primary opportunity for Western pharmaceutical firms to expand their commercial footprint.
- Digital Health Integration:Combining pharmacological treatments with digital health platforms for remote patient monitoring and medication adherence can improve outcomes, offering a key value-add service for providers and payers.
Industry Challenges
- Hybrid Trial Management:The operational shift from fully outsourced to hybrid in-house clinical trial management models requires new internal expertise, technologies, and processes, creating execution challenges for drug developers.
- Securing Favorable Reimbursement:Demonstrating superior clinical and economic value to a fragmented global landscape of payers is a persistent operational challenge that dictates commercial success for premium-priced medicines.
- Patent Cliff Management:The cyclical nature of patent expiries for blockbuster cardiovascular drugs forces companies to continually manage revenue loss by successfully advancing a pipeline of innovative replacement therapies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Congestive Heart Failure Drugs Market |
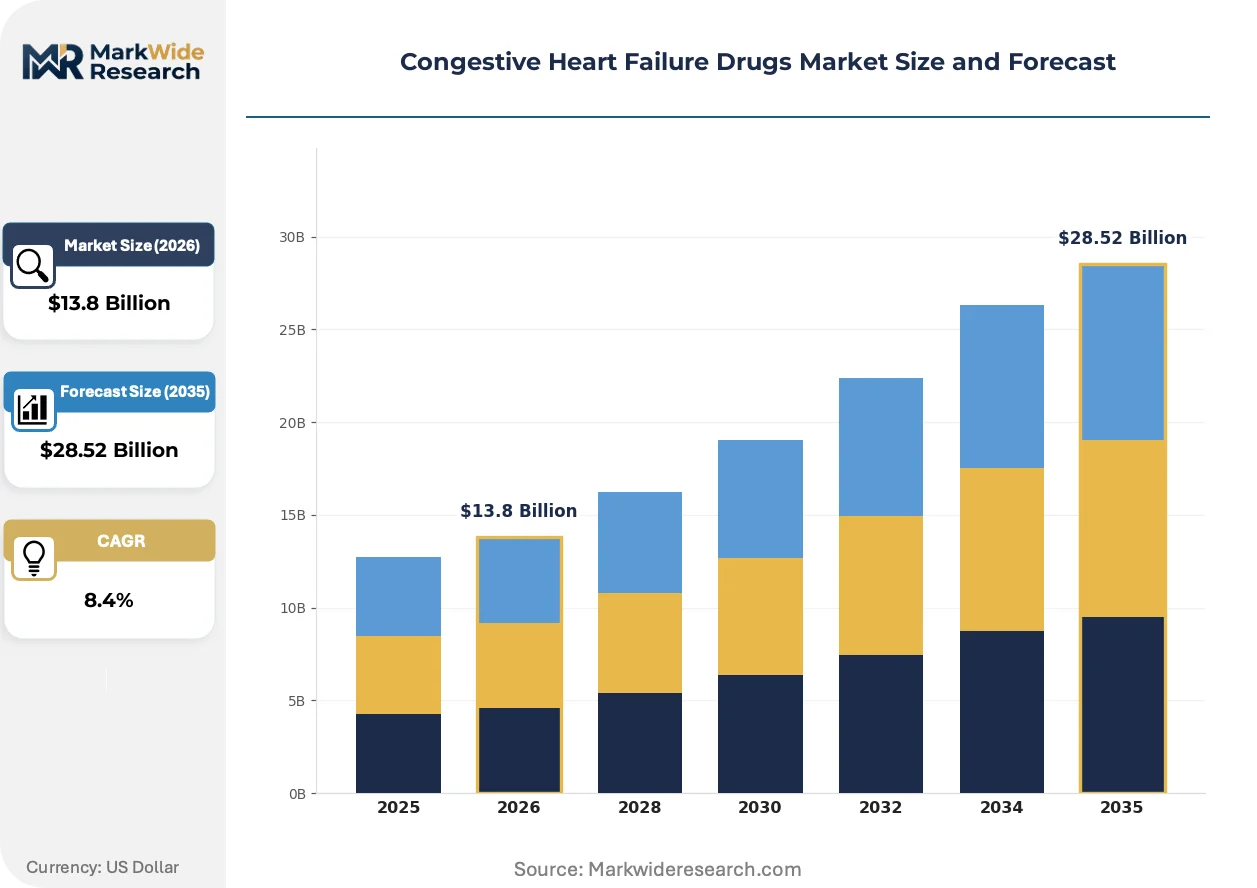
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: ACE Inhibitors, Beta Blockers, Diuretics, Aldosterone Antagonists, Digitalis Glycosides Dosage Form: Tablet, Injectable, Oral Suspension, Extended-Release Capsule, Patch Therapy Area: Chronic Heart Failure, Acute Decompensated Heart Failure, Left Ventricular Dysfunction, Diastolic Dysfunction End User: Cardiology Clinics, Specialty Pharmacies, Geriatric Care Centers, Ambulatory Care Centers |
| Companies Covered | Novartis AG, AstraZeneca plc, Merck & Co., Inc., Sanofi, Pfizer Inc., Bristol-Myers Squibb Company, GSK plc, Cytokinetics Inc., Zensun (Shanghai) Sci & Tech Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Congestive Heart Failure Drugs Market Strategic Shifts & Innovations
Evidence-based stratification is transforming therapeutic approaches to congestive heart failure. Treatment selection is increasingly guided by patient phenotype, comorbidities, and specific biomarkers rather than a uniform standard of care, creating distinct sub-markets for targeted agents.
SGLT2 inhibitors function by modifying sodium-glucose co-transport to deliver cardiovascular benefits beyond glycemic control. Cardiology clinics are rapidly adopting these agents for heart failure patients irrespective of their diabetes status. This therapy class is integrating into foundational treatment guidelines, augmenting established regimens.
The U.S. Food and Drug Administration and European Medicines Agency are emphasizing hard clinical endpoints in trial design. This regulatory focus requires new drugs to demonstrate statistically significant reductions in cardiovascular death and hospitalization rates. Late-stage development programs are most affected, facing higher costs and greater evidence burdens to gain approval.
Guideline-directed medical therapy (GDMT) is standardizing prescribing behavior across health systems. This shift reduces individual physician discretion in favor of evidence-based protocols often tied to quality metrics and reimbursement. The trend is most pronounced within large, integrated delivery networks in the United States and national health services in Europe.
Congestive Heart Failure Drugs Market Segmentation
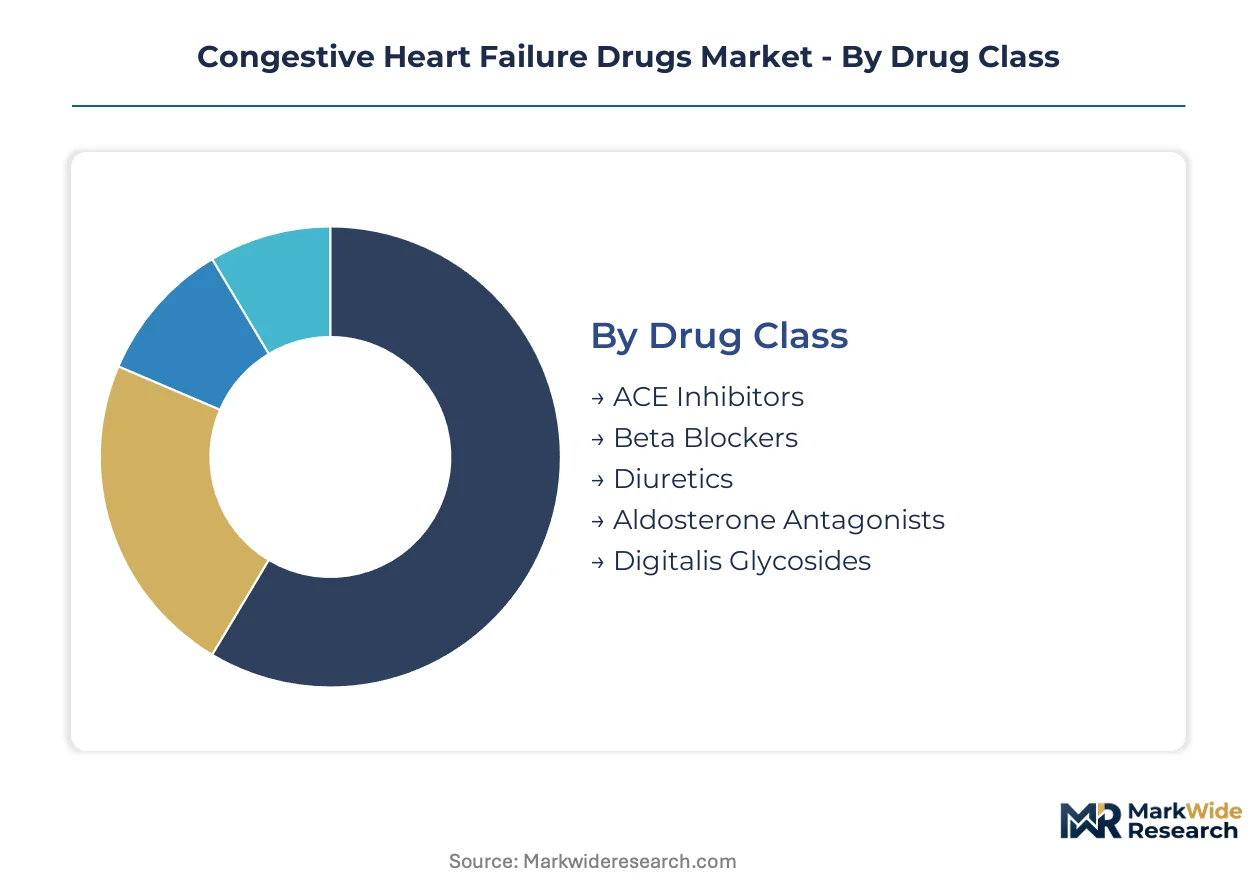
Segmentation provides a granular view of the Congestive Heart Failure Drugs Market, highlighting distinct areas of growth and therapeutic focus. Understanding these divisions helps pharmaceutical companies tailor drug development, optimize market access strategies, and address specific patient needs. Each segment reflects unique clinical requirements and commercial dynamics.
Drug Class:
The supply concentration within drug classes reflects historical development and current treatment guidelines for heart failure management.
- ACE Inhibitors:These agents block the conversion of angiotensin I to angiotensin II, reducing vasoconstriction and fluid retention. Demand for these foundational drugs remains high in primary care settings due to their established efficacy and cost-effectiveness.
- Beta Blockers:These drugs work by blocking the effects of adrenaline on the heart, slowing heart rate and reducing blood pressure. Cardiology clinics widely prescribe beta blockers for long-term management, improving patient survival rates.
- Diuretics:These medications help the body eliminate excess fluid, primarily managing symptoms like edema and congestion.
- Aldosterone Antagonists:These therapies block aldosterone's effects, offering benefits in reducing mortality and hospitalizations.
- Digitalis Glycosides:These older drugs increase myocardial contractility and are used for symptom control in select patients.
ACE Inhibitors absorb the bulk of installed capacity; Beta Blockers are expanding most quickly.
Dosage Form:
Patient convenience and therapeutic urgency heavily influence the market's dosage form segmentation, impacting drug adherence and administration.
- Tablet:Oral tablets represent the most common and convenient method for chronic heart failure drug delivery, facilitating long-term patient compliance. Demand is concentrated in outpatient settings, driven by ease of self-administration.
- Injectable:Injectable formulations provide rapid onset of action, crucial for acute decompensated heart failure management in hospital settings. These forms are vital for patients unable to take oral medications.
- Oral Suspension:Liquid oral suspensions provide an alternative for pediatric or dysphagic patients, ensuring dosage flexibility.
- Extended-Release Capsule:These capsules offer prolonged drug release, reducing dosing frequency and potentially improving patient adherence.
- Patch:Transdermal patches deliver continuous drug absorption, offering a non-invasive option for specific therapeutic agents.
Oral tablets constitute the largest volume segment; injectable forms are gaining share fastest.
Therapy Area:
The premium-priced medicines increasingly target specific therapy areas, reflecting advancements in understanding heart failure pathophysiology.
- Chronic Heart Failure:This segment represents the largest and fastest-growing value market, driven by the introduction of premium-priced SGLT2 inhibitors and ARNIs. Treatment focuses on long-term symptom management and mortality reduction.
- Acute Decompensated Heart Failure:This critical area requires immediate intervention in hospital settings, often involving intravenous medications and intensive monitoring. Demand concentrates on rapid-acting agents for symptom relief.
- Left Ventricular Dysfunction:Therapies for this condition aim to improve the heart's pumping ability, often using established drug classes.
- Diastolic Dysfunction:This area focuses on improving the heart's relaxation and filling capabilities, a challenging therapeutic target.
Chronic Heart Failure therapies command the highest value share; Acute Decompensated Heart Failure treatments are climbing the fastest.
End User:
Customer type significantly influences drug distribution and patient access, with specialized centers driving adoption of novel therapies.
- Cardiology Clinics:These specialized outpatient facilities are primary prescribers and adopters of new heart failure drugs, especially SGLT2 inhibitors. They manage a large volume of chronic heart failure patients.
- Specialty Pharmacies:Specialty pharmacies handle complex, often high-cost heart failure medications requiring specific handling and patient education. They play a vital role in ensuring adherence for advanced therapies.
- Geriatric Care Centers:These centers manage an aging patient population with high heart failure prevalence and complex polypharmacy needs.
- Ambulatory Care Centers:Ambulatory centers provide diagnostic and treatment services, supporting early intervention and follow-up for heart failure patients.
Cardiology Clinics serve the largest patient population; Specialty Pharmacies exhibit the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors a significant portion of global demand for congestive heart failure drugs due to its advanced healthcare infrastructure and high disease prevalence. This market is undergoing transformation as premium-priced innovative therapies gain traction. Regulatory bodies worldwide are adapting to the rapid pace of therapeutic advancements.
United States
High disease prevalence and an aging population drive sustained demand for effective heart failure treatments. The FDA sets rigorous standards for clinical trial efficacy and safety, influencing drug development. Major pharmaceutical research hubs like Boston and San Francisco lead innovation in novel cardiac pathways.
China
Accelerated regulatory pathways by the NMPA are speeding market access for innovative heart failure drugs. A large, underserved patient population creates substantial commercial opportunities for new therapies. Shanghai and Beijing serve as key centers for pharmaceutical R&D and manufacturing expansion.
Germany
Demand for advanced heart failure therapies is strong, supported by robust healthcare spending and an aging demographic. The European Medicines Agency (EMA) standards govern drug approval, ensuring high efficacy and safety. The Rhine-Main region, including Frankfurt, hosts significant pharmaceutical research and development activities.
Japan
An exceptionally aging population ensures consistent demand for chronic heart failure management solutions. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees drug approvals, emphasizing real-world evidence for new treatments. Tokyo's pharmaceutical cluster remains a focal point for cardiovascular drug innovation.
United Kingdom
The National Health Service (NHS) drives procurement for heart failure drugs, with a focus on cost-effectiveness for new agents. EMA guidelines, post-Brexit, still heavily influence regulatory approaches for drug evaluation. London and Cambridge are prominent centers for biotech research and clinical trials.
Congestive Heart Failure Drugs Market Key Industry Players
Operational restructuring dominates the current landscape for congestive heart failure drugs, driven by the shift towards hybrid clinical trial management. The market exhibits a tiered structure, with a few established pharmaceutical giants holding significant portfolio depth alongside numerous specialized biotech innovators. Key strategic archetypes include large-scale integrators focusing on broad cardiovascular portfolios and nimble developers targeting novel cardiac pathways. Portfolio diversification towards premium-priced therapies and strategic partnerships for late-stage development are prominent competitive moves.
On the premium-tier vector, Novartis AG represents an established pharmaceutical leader leveraging an extensive cardiovascular medicine portfolio to maintain market dominance. AstraZeneca plc exemplifies a company differentiating its offerings through a strong focus on SGLT2 inhibitors for expanded heart failure indications. Bristol-Myers Squibb Company occupies a position among firms advancing novel drug candidates that specifically target distinct cardiac pathways, reflecting a strategy of therapeutic innovation. These companies anchor the high-value segment, focusing on superior clinical outcomes to secure favorable reimbursement.
| Leading Market Players |
|---|
| Novartis AG |
| AstraZeneca plc |
| Merck & Co., Inc. |
| Sanofi |
| Pfizer Inc. |
| Bristol-Myers Squibb Company |
| GSK plc |
| Cytokinetics Inc. |
| Zensun (Shanghai) Sci & Tech Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Established pharmaceutical giants with extensive R&D pipelines drive supply behavior, influencing pricing discipline for novel congestive heart failure drugs. Their investment in clinical development directly impacts the market's value proposition and commercial viability.
Pricing Analysis
Warranty and service-bundling for complex heart failure therapies often include patient support programs and reimbursement navigation assistance for premium-priced drugs. Value-based pricing models dominate for innovative treatments, linking cost to demonstrated clinical outcomes. Price differentiation stems from superior efficacy in specific patient populations and the breadth of approved indications, such as SGLT2 inhibitors for non-diabetic heart failure patients. Pricing pressure stems from payer resistance to high-cost novel therapies. Public and private payers exhibit the highest price sensitivity, demanding extensive cost-effectiveness data.
Supply Chain Analysis
Certification and qualification gating by regulatory bodies like the FDA, EMA, and NMPA are critical entry barriers across the supply chain for congestive heart failure drugs. Geographic supply concentration for Active Pharmaceutical Ingredients (APIs) centers on China and India, with finished drug manufacturing prominent in the United States and Germany. The supply chain relies on a steady provision of specialized excipients for complex formulations. Single-source vulnerability for proprietary APIs represents a structural supply chain risk. Distribution runs through a network of specialty pharmacies, hospital systems, and traditional retail pharmacies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The congestive heart failure drug market is supply-constrained by the rigorous and lengthy development process for novel therapies, creating a bottleneck that props up premium pricing for innovative treatments.
For Market Incumbents: Anchor existing market share through continuous investment in late-stage clinical pipelines for next-generation heart failure therapies. Diversify portfolios beyond established drug classes to mitigate generic erosion of foundational treatments like ACE inhibitors and beta blockers. Pursue strategic partnerships for enhanced market access in underserved regions, particularly in China. Integrate digital health platforms to improve patient adherence and demonstrate real-world outcomes, strengthening reimbursement arguments.
For New Entrants and Emerging Players: Patients with specific cardiac pathway abnormalities represent an underserved buyer archetype offering significant white-space opportunities. Target precision medicine approaches for distinct patient subgroups, focusing on novel drug candidates for orphan indications or challenging therapeutic targets like diastolic dysfunction. China's accelerated NMPA review process offers a penetrable geographic segment for demonstrating superior clinical outcomes. A niche specialization go-to-market angle, emphasizing specific biomarker-driven therapies, can facilitate rapid adoption among cardiology specialists.
For Investors and Strategic Acquirers: Early-stage innovation entries favor specialized biotech firms in US research hubs, particularly those with promising Phase 2 or Phase 3 drug candidates. The market exhibits strong long-term viability over the next decade due to rising disease prevalence and continuous demand for advanced treatments. Target acquisition archetypes include nimble developers advancing novel drug candidates targeting specific cardiac pathways. A signal to watch is positive Phase 3 clinical trial readouts for first-in-class mechanisms, combined with favorable early reimbursement discussions with key payers.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market entry for novel SGLT2 inhibitors and ARNI drugs, demonstrating superior patient outcomes. |
| Regulatory Approval Pathway | Secures market access in key regions like the US and China, influencing commercial success and adoption. |
| Licensing Agreement | Expands geographic reach and leverages existing distribution networks for specialized heart failure therapies. |
| Manufacturing Scale-Up | Ensures consistent supply of complex biologicals and premium-priced medicines to meet rising patient demand. |
| Pipeline Diversification | Mitigates revenue loss from patent expirations and strengthens a company's cardiovascular medicine portfolio. |
Research Approach
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone for this analysis, providing foundational data on drug development and regulatory landscapes. This was triangulated with primary interviews conducted with cardiology specialists, pharmaceutical R&D executives, payer representatives, and hospital formulary managers. The study employed both bottom-up and top-down approaches to ensure comprehensive market sizing and validation.
A bottom-up estimation of patient populations, segmented by drug class, dosage form, therapy area, end user, and regional regulatory frameworks, informed the quantitative forecast across the analysis window. Compound Annual Growth Rates (CAGRs) were derived from historical market trends, projected new drug launch timelines, and anticipated adoption rates. Key industry-specific forecast inputs included detailed disease prevalence data and the evolving clinical guideline expansion.
Revisions become necessary when unexpected clinical trial failures or major shifts in reimbursement policy materialize, impacting market dynamics. Forecasts reflect assumptions regarding regulatory approvals and technological advancements. A model refresh is warranted upon material change in clinical guideline updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Immunoglobulin Products Market
Pharmaceuticals
Stomach Cancer Drugs Market
Pharmaceuticals
Metformin HCL Drugs Market
Pharmaceuticals
Retinal Drugs and Biologics Market
Pharmaceuticals
Asia-Pacific GLP 1 Agonist Market
Pharmaceuticals
Famotidine Market
Pharmaceuticals
Aminophylline Market
Pharmaceuticals
Asia-Pacific Biguanide Market
Pharmaceuticals
Intranasal Migraine Drugs Market
Pharmaceuticals
Canine Dilated Cardiomyopathy Drugs Market
Pharmaceuticals
Influenza Antiviral Market
Pharmaceuticals
Benzodiazepine Drugs Market
Pharmaceuticals
Fibroblast Activation Protein Inhibitors Market
Pharmaceuticals
Middle-East and Africa Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Asia-Pacific Pharmaceutical Contract Manufacturing Organization Market
Pharmaceuticals
Meperidine Drugs Market