
 Leukotriene Modifiers Market | 2026-2036
Leukotriene Modifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Leukotriene Modifiers Market Foresight
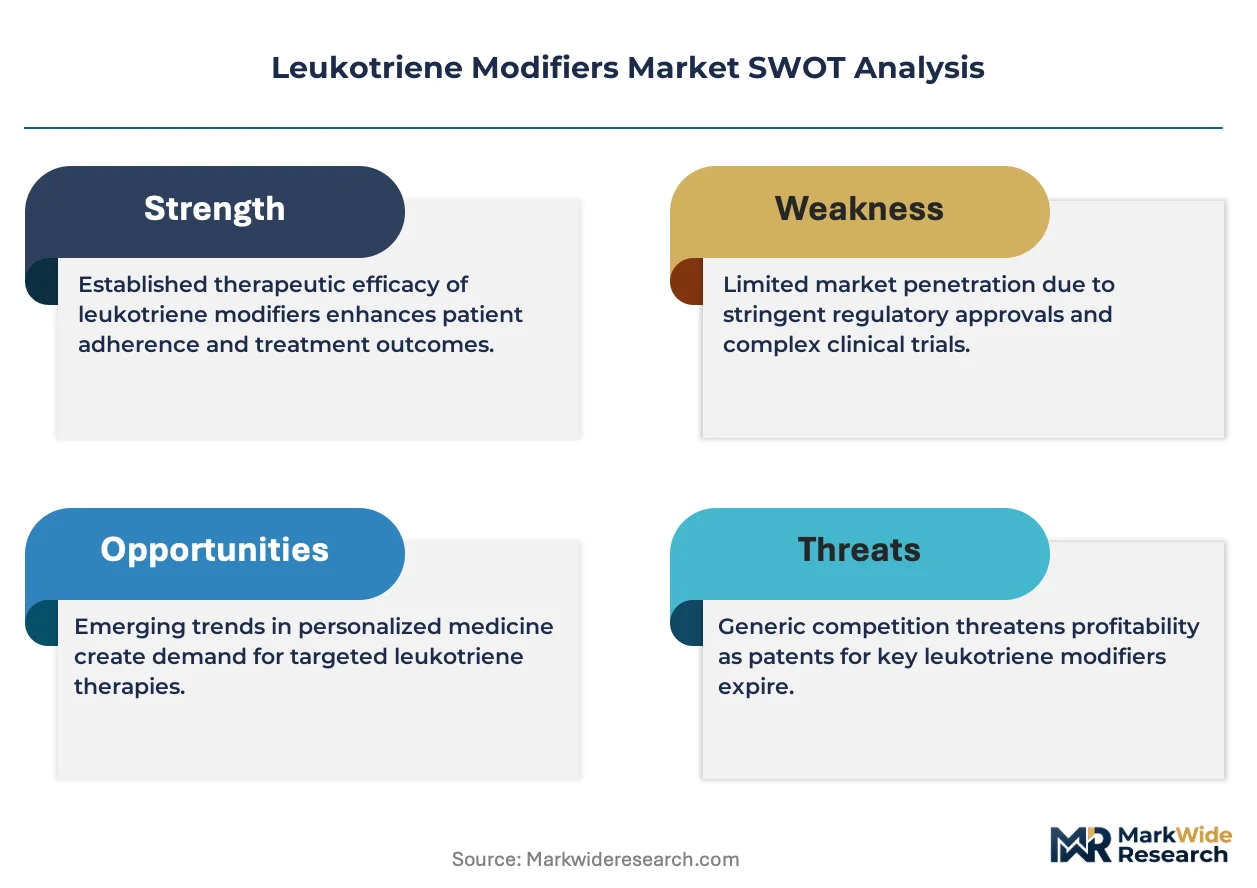
Biologic-targeted therapy development is narrowing the competitive moat for traditional small-molecule leukotriene modifiers in severe asthma. Merck And Co. leverages its entrenched Singulair franchise and pediatric indications to sustain retail pharmacy dominance. AstraZeneca PLC anchors respiratory portfolio breadth through biologic-leukotriene combination strategies across hospital formularies. Teva Pharmaceutical Industries Ltd. competes aggressively in the generics space, extending cost-access advantages through multi-source pranlukast and montelukast supply.
Leukotriene modifiers constitute a class of orally bioavailable small-molecule drugs that antagonize cysteinyl leukotriene receptors or inhibit 5-lipoxygenase, thereby blocking bronchoconstriction and eosinophilic inflammation in asthma and allergic rhinitis. These agents functionally deliver corticosteroid-sparing control with once-daily oral dosing, positioning them between rescue inhalers and injectable biologics in treatment algorithms. Montelukast occupies the dominant revenue position due to its pediatric approval down to six months and broad allergic rhinitis labeling, though neuropsychiatric safety scrutiny has compressed growth in some markets. The asthma application segment retains the deepest clinical evidence base and highest prescriber familiarity, while home care and pharmacy channels are capturing incremental volume as maintenance therapy shifts away from acute-care settings.
The FDA's boxed warning requirements for montelukast directly constrain U.S. prescriber enthusiasm and trigger formulary prior-authorization protocols, while EMA pharmacovigilance reviews across Europe reinforce cautious labeling harmonization. The EPA and OSHA indirectly shape manufacturing economics through environmental compliance burdens on active pharmaceutical ingredient synthesis. Stakeholders must monitor regulatory divergence between FDA risk-minimization strategies and emerging WHO essential medicines list positioning, as this tension will determine whether leukotriene modifiers retain first-line status or cede ground to biologic step-up therapy in international treatment guidelines.
Market Dynamics
The FDA's boxed warning on montelukast neuropsychiatric risk is forcing a structural recalibration of prescribing hierarchies, compressing volume in pediatric segments while hospital formularies elevate biologic alternatives for severe asthma.
Growth Catalysts
- Chronic disease burden:Rising asthma prevalence in urban centers drives maintenance therapy demand, particularly among pediatric populations where oral dosing advantages persist despite safety scrutiny.
- REACH compliance incentives:European manufacturers investing in green chemistry synthesis routes for leukotriene active pharmaceutical ingredients capture preferential formulary positioning under EU Green Deal procurement guidelines.
- Step-down protocols:Hospital systems in the United States embed leukotriene modifiers into corticosteroid tapering pathways, preserving their role in chronic disease management algorithms.
Market Restraints
- Biologic substitution:Anti-IL5 and anti-IgE therapies displace leukotriene modifiers in severe eosinophilic asthma, narrowing the addressable patient pool to mild-to-moderate cases.
- API supply concentration:Bulk manufacturing of montelukast sodium concentrates in India and China, creating single-source vulnerability for European and North American formulators.
- Neuropsychiatric liability:The FDA's risk evaluation and mitigation strategy imposes prior authorization burdens that extend prescription fulfillment timelines and depress initiation rates.
Strategic Opportunities
- Pediatric formulation innovation:Orally disintegrating tablet formats for patients aged 6-23 months address an unmet need in allergy-induced asthma where nebulized alternatives prove adherence-challenging.
- Japan's geriatric asthma wave:METI-supported eldercare initiatives create demand for maintenance therapies with minimal cardiovascular interaction profiles, favoring leukotriene receptor antagonists over beta-agonists.
- Pharmacy benefit integration:United States payers experimenting with value-based adherence incentives for chronic respiratory conditions, opening reimbursement innovation space beyond traditional fee-for-service.
Industry Challenges
- Pharmacovigilance infrastructure:Post-market surveillance systems must capture rare neuropsychiatric events across distributed outpatient settings, straining safety signal detection capabilities.
- Biomarker stratification:Urinary leukotriene E4 testing for responder identification lacks standardized assay availability, complicating precision prescribing efforts in community pulmonology.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leukotriene Modifiers Market |
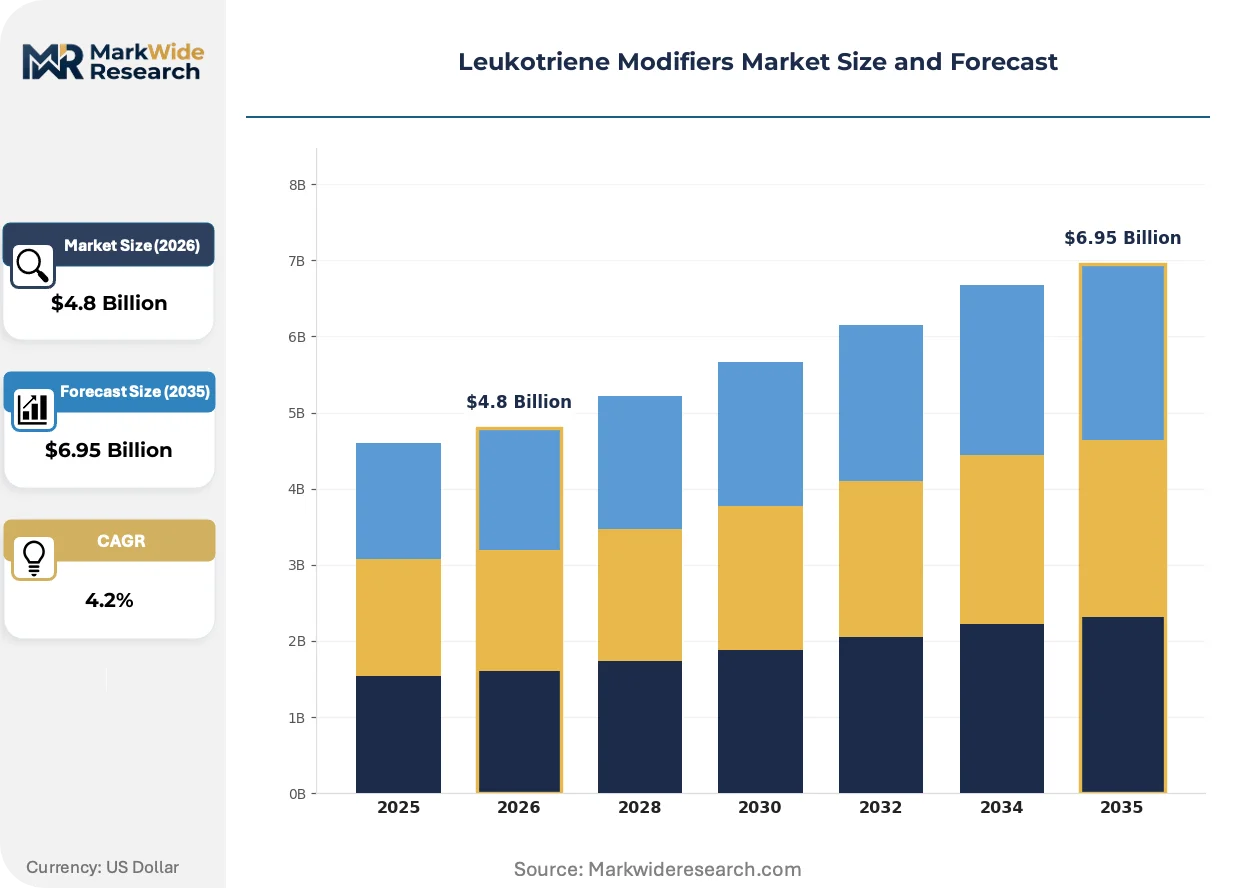
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Montelukast, Zafirlukast, Pranlukast, Others Application: Asthma, Allergic Rhinitis, Exercise-Induced Bronchoconstriction, Others End User: Hospitals, Clinics, Home Care, Pharmacies Distribution Channel: Retail, Hospital Pharmacy, Online, Wholesalers |
| Companies Covered | Merck And Co., AstraZeneca PLC, GlaxoSmithKline plc, Novartis AG, Teva Pharmaceutical Industries Ltd., Viatris Inc., Sun Pharmaceutical Industries, Chiesi Farmaceutici S.p.A., Cipla Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leukotriene Modifiers Market Shifts & Advancements
Competitive pressure from biologics and tightening regulatory safety requirements are accelerating product differentiation strategies across oral small-molecule respiratory portfolios.
Once-daily fixed-dose combinations pairing leukotriene receptor antagonists with long-acting antihistamines are rendering obsolete standalone allergic rhinitis prescribing in United States retail pharmacy channels. Primary care networks in Texas and Florida have adopted these combinations as first-line seasonal therapy, compressing volume for single-agent montelukast by streamlining adherence for comorbid patients.
The EMA's pharmacovigilance risk assessment committee has mandated enhanced cardiovascular monitoring language across all leukotriene modifier labels in the European Union. This regulatory tightening forces manufacturers to sponsor additional real-world evidence studies, raising post-approval compliance costs while creating competitive separation for sponsors with robust safety databases.
Hospital-at-home programs in the United States are redistributing asthma maintenance volume from infusion centers to specialty pharmacy channels. This channel migration demands cold-chain logistics capabilities and patient education infrastructure that legacy acute-care distributors lack, favoring vertically integrated pharmacy benefit managers with respiratory disease management platforms.
Leukotriene Modifiers Market Segmentation
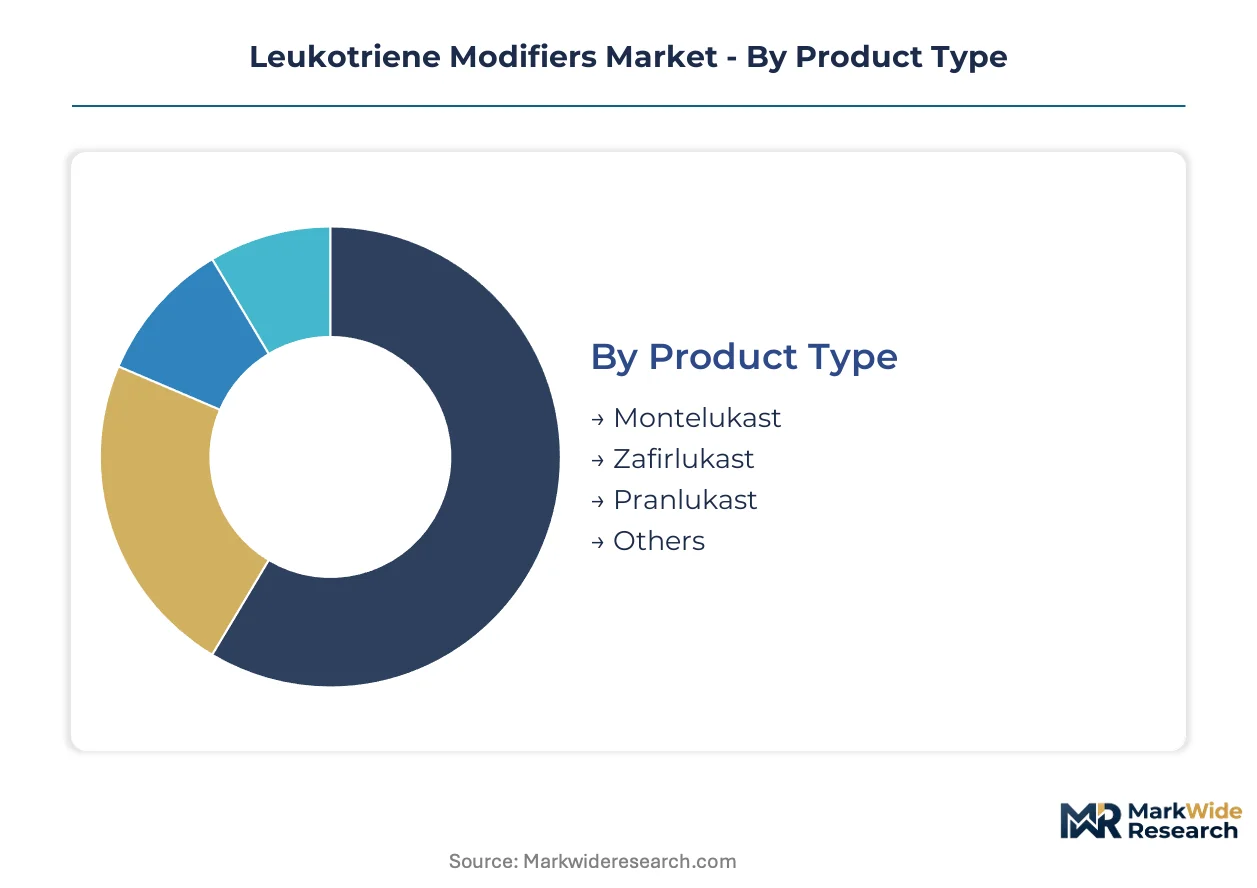
Leukotriene modifiers exhibit distinct demand rhythms across molecular structures and care settings, with product lifecycles ranging from decades-old blockbusters to niche generics and application patterns shifting between acute intervention and chronic maintenance protocols.
Product Type:
Cysteinyl leukotriene receptor antagonists and 5-lipoxygenase inhibitors turn over at vastly different velocities, with pediatric patent cliffs and generic entry waves creating asynchronous competitive cycles across the class.
- Montelukast:Oral leukotriene receptor antagonist approved for patients down to six months of age, delivering once-daily bronchoconstriction blockade. United States retail pharmacy volumes concentrate in suburban pediatric practices where caregiver adherence preferences outweigh FDA neuropsychiatric warning burdens.
- Zafirlukast:Twice-daily leukotukast receptor antagonist with narrower age labeling and hepatic metabolism considerations. Hospital formulary committees in Germany and France retain limited niche positioning for aspirin-sensitive asthma subpopulations where montelukast response proves inadequate.
- Pranlukast:Japanese-developed receptor antagonist with established reimbursement in East Asian markets. Teva Pharmaceutical Industries and domestic Chinese manufacturers dominate API supply through cost-optimized fermentation routes.
- Others:Zileuton and experimental 5-LO inhibitors occupy hepatotoxicity-constrained prescribing territories. Compounding pharmacies in India formulate customized zileuton suspensions for corticosteroid-resistant cases.
Montelukast anchors the volume base while pranlukast gains share at the steepest rate through Asia-Pacific generic substitution dynamics.
Application:
Clinical evidence depth and payer coverage generosity stratify sharply across respiratory and allergic indications, with exercise-triggered segments commanding premium positioning despite smaller addressable populations.
- Asthma:Chronic inflammatory airway disease indication with the deepest randomized trial portfolio and step-down protocol integration. United States pulmonology practices embed leukotriene modifiers into corticosteroid tapering pathways for persistent mild-to-moderate cases.
- Allergic Rhinitis:Seasonal and perennial nasal inflammation application where fixed-dose antihistamine combinations are displacing standalone prescribing. Texas and Florida primary care networks have adopted these combinations as first-line therapy.
- Exercise-Induced Bronchoconstriction:Acute pre-exercise prophylaxis niche with Olympic athlete and military fitness program demand. Sports medicine clinics in Australia and the United Kingdom prescribe prior to competitive endurance events.
- Others:Urticaria and atopic dermatitis off-label utilization persists in South Korean and Brazilian dermatology settings where histamine-resistant inflammation pathways dominate.
Asthma indications retain the deepest prescriber familiarity while exercise-induced bronchoconstriction applications command the highest per-patient revenue intensity.
End User:
Site-of-care migration from institutional to ambulatory settings is redistributing volume capture across channel intermediaries with divergent logistics and reimbursement competencies.
- Hospitals:Acute-care institutions managing severe exacerbations and biologic step-up decisions. Cleveland Clinic and Mayo Clinic embed leukotriene modifiers into discharge protocols for moderate persistent asthma.
- Clinics:Outpatient pulmonology and allergy specialty practices driving initiation and titration decisions. United Kingdom NHS specialist clinics prioritize leukotriene trials before biologic referral.
- Home Care:Long-term maintenance therapy delivery through visiting nurse and remote monitoring platforms. Kaiser Permanente Northern California deploys respiratory therapists for home adherence coaching.
- Pharmacies:Retail and specialty dispensing nodes capturing refill loyalty through 90-day maintenance programs. CVS Caremark and Walgreens Boots Alliance compete on generic montelukast pricing.
Hospital systems anchor prior authorization control while home care channels expand most quickly through Medicare Advantage value-based contracting.
Distribution Channel:
Channel margin structures and cold-chain requirements fragment fulfillment economics, with direct-to-patient digital platforms capturing adherence-sensitive chronic therapy segments.
- Retail:Community pharmacy networks dominating generic montelukast volume through convenience and insurance network density. Rite Aid and independent pharmacies in the United States compete on copay optimization.
- Hospital Pharmacy:Captive dispensaries controlling formulary-adherent prescribing within integrated delivery networks. Kaiser Permanente and Intermountain Healthcare enforce pathway compliance through internal pharmacies.
- Online:Mail-order and digital pharmacy platforms capturing 90-day maintenance prescriptions. Amazon Pharmacy and Capsule target urban millennials with auto-refill subscription models.
- Wholesalers:McKesson, AmerisourceBergen, and Cardinal Health distributing to institutional and independent pharmacies with generic sourcing scale advantages.
Retail pharmacy retains the prescription volume base while online channels gain share at the steepest rate through convenience-oriented demographic capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric pulmonologists in suburban United States practices drive volume concentration for oral maintenance therapies, while hospital formulary committees in Germany and Japan shape step-care protocols that preserve leukotriene positioning against biologic displacement.
United States
High asthma prevalence in Texas and Florida sustains retail pharmacy demand for once-daily oral alternatives to inhaled corticosteroids. FDA boxed warning requirements on montelukast trigger prior-authorization protocols that compress pediatric initiation rates. Cleveland Clinic and Mayo Clinic embed leukotriene modifiers into discharge pathways for moderate persistent asthma.
Germany
Aspirin-sensitive asthma subpopulations in Bavaria and North Rhine-Westphalia retain niche demand for zafirlukast where montelukast response proves inadequate. EMA pharmacovigilance reviews reinforce cautious labeling harmonization across EU member states. Heidelberg University Hospital maintains specialist referral pathways that trial leukotriene receptor antagonists before biologic escalation.
Japan
METI-supported eldercare initiatives in the Kanto region generate demand for maintenance therapies with minimal cardiovascular interaction profiles. Pranlukast maintains established reimbursement positioning through domestic manufacturer relationships. Osaka-based respiratory clinics prioritize leukotriene receptor antagonists for geriatric patients with comorbid cardiac conditions.
India
Generic montelukast manufacturing concentrates in Gujarat and Maharashtra, supplying API to European and North American formulators. CDSCO post-market surveillance requirements strain pharmacovigilance infrastructure for rare neuropsychiatric event detection. Sun Pharmaceutical and Cipla operations in Mumbai and Ahmedabad anchor cost-optimized production for export markets.
United Kingdom
NHS specialist clinics in London and Manchester prioritize leukotriene trials before biologic referral for eosinophilic asthma cases. NICE cost-effectiveness thresholds favor generic montelukast over inhaled corticosteroid combinations for mild persistent disease. Guy's and St Thomas' NHS Foundation Trust maintains step-down protocols that embed leukotriene modifiers into corticosteroid tapering pathways.
Leukotriene Modifiers Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tiers where originator franchises defend pediatric indications against generic erosion. The vendor base separates into three strategic archetypes: entrenched originators with legacy pediatric approvals, aggressive generic manufacturers with API supply advantages, and vertically integrated hospital formulary managers. Consolidation pressure concentrates around M&A activity targeting pediatric formulation capabilities and strategic partnerships securing 90-day retail pharmacy distribution.
Within the originator tier, Merck And Co. and AstraZeneca PLC exemplify franchise defenders leveraging decades of clinical data and hospital formulary relationships. Among generic specialists, Teva Pharmaceutical Industries Ltd. occupies a position anchored by multi-source API supply and cost-access positioning. These three companies represent the competitive spectrum from premium-brand maintenance to commodity substitution dynamics.
| Leading Market Players |
|---|
| Merck And Co. |
| AstraZeneca PLC |
| GlaxoSmithKline plc |
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| Viatris Inc. |
| Sun Pharmaceutical Industries |
| Chiesi Farmaceutici S.p.A. |
| Cipla Limited |
| Others |
Supply & Pricing Matrix
API manufacturing for montelukast sodium concentrates in Gujarat and Maharashtra, India, anchors upstream supply and funnels margin capture toward North American and European formulators with captive distribution networks. This geographic concentration creates asymmetric bargaining power where bulk chemical suppliers compete on fermentation yield while finished dose manufacturers extract value through pediatric formulation patents and hospital formulary control.
Pricing Analysis
Cost-plus contracts with active pharmaceutical ingredient suppliers index to fermentation feedstock and solvent recovery costs, stabilizing input volatility for formulators. Three-tier pricing structure across originator pediatric formulations, authorized generics, and commodity multi-source tablets differentiates on FDA label breadth and caregiver adherence support. Pricing pressure stems from Teva Pharmaceutical Industries and Sun Pharmaceutical aggressive generic entry in United States retail pharmacy channels. Price-sensitive Medicaid and uninsured segments drive volume toward 90-day mail-order generic substitution, while pediatric allergy specialists retain brand loyalty for montelukast chewable formats.
Supply Chain Analysis
Extended payment terms from European and North American formulators to Indian API manufacturers, often 90-120 days, strain working capital and force supplier-financing facilities through trade credit insurers. Raw material dependencies center on quinoline derivatives, methanol for crystallization, and specialized fermentation nutrients sourced from China and Germany. Single-source vulnerability concentrates in montelukast sodium intermediate synthesis, where CDSCO-registered Gujarat facilities feed multiple downstream formulators. Distribution runs through McKesson, AmerisourceBergen, and Cardinal Health wholesale networks to retail and hospital pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Leukotriene modifiers occupy an early-cycle expansion phase as hospital-at-home programs and corticosteroid-sparing protocols extend maintenance therapy penetration beyond acute-care settings. Japan's geriatric asthma wave and United States value-based Medicare Advantage contracting represent named tailwinds accelerating adoption.
For Market Incumbents: Pre-empt biologic substitution by embedding leukotriene modifiers into step-down protocols with measurable corticosteroid reduction outcomes, while securing pediatric formulation exclusivity through FDA-approved orally disintegrating tablet formats. Backward integration into Indian API supply through strategic partnerships with Sun Pharmaceutical or Cipla manufacturing sites mitigates single-source concentration risk. For New Entrants and Emerging Players: Mid-market allergy practices in Texas and Florida represent the most penetrable entry point, where fixed-dose antihistamine-leukotriene combinations displace standalone prescribing and payer value-based adherence incentives create reimbursement innovation space. Pharmacy benefit integration partnerships with CVS Caremark or Walgreens Boots Alliance offer the strongest go-to-market angle for generic montelukast volume capture. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed generic manufacturers possessing Indian API supply relationships and United States ANDA portfolios. The five-to-ten year viability window hinges on whether leukotriene modifiers retain first-line status against biologic step-up therapy in international treatment guidelines. Monitor WHO essential medicines list positioning as the critical inflection signal for emerging market volume sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Formulation Innovation | Orally disintegrating tablets for 6-23 month patients address adherence gaps where nebulized alternatives fail. |
| Green Chemistry Synthesis Investment | REACH compliance incentives under EU Green Deal procurement guidelines capture preferential European formulary positioning. |
| Hospital-at-Home Channel Expansion | Cold-chain logistics and respiratory therapist deployment through Kaiser Permanente models redistribute volume from infusion centers. |
| API Supply Partnership Structuring | Strategic alliances with Gujarat and Maharashtra manufacturers secure fermentation-based cost advantages against synthetic chemistry competitors. |
| Real-World Evidence Generation | Post-market cardiovascular and neuropsychiatric safety databases create competitive separation under EMA pharmacovigilance mandates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pediatric pulmonologists, hospital formulary directors, pharmacy benefit managers, and generic API procurement leads at Indian manufacturing sites. Secondary validation drew from FDA Adverse Event Reporting System filings, EMA pharmacovigilance risk assessment committee outputs, ClinicalTrials.gov intervention records, and United States Medicaid prescription claims databases. Bottom-up patient population modeling and top-down pharmaceutical market sizing were triangulated to reconcile volume estimates.
Calibration against historical generic entry waves and patent cliff erosion patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include molecular structure class, indication severity tier, patient age cohort, site-of-care setting, and regional regulatory cluster. CAGRs were derived from epidemiological trend extrapolation, reimbursement pathway stability assessment, and competitive displacement elasticity estimates. Forecast inputs incorporated asthma prevalence trajectories in urban centers and biologic therapy penetration curves in severe eosinophilic segments.
Macroeconomic conditions sit as an overlay; deviation in Medicare Advantage reimbursement rates, Indian rupee volatility affecting API export economics, or FDA risk evaluation and mitigation strategy expansion would shift the trajectory. Forecasts embody documented assumptions regarding regulatory label stability and biologic substitution velocity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Nasal Antihistamines Market
Pharmaceuticals
Global Vero Cell Rabies Vaccine Market
Pharmaceuticals
Compound Acetaminophen Market
Pharmaceuticals
Dual Migraine Treatment Market
Pharmaceuticals
Global Blood Plasma Derivatives Market
Pharmaceuticals
Cognitive and Memory Enhancer Drugs Market
Pharmaceuticals
Telmisartan Market
Pharmaceuticals
Biguanides Market
Pharmaceuticals
Global Antipsychotic Drugs Market
Pharmaceuticals
Global Finasteride Market
Pharmaceuticals
Global Anticoccidial Drugs Market
Pharmaceuticals
Thin Film Drug Manufacturing Market
Pharmaceuticals
Computer-Aided Drug Discovery Market
Pharmaceuticals
India Plasma Fractionation Market
Pharmaceuticals
Pharmaceutical Pellets Market
Pharmaceuticals
Dipeptide Peptidase 4 Inhibitors Market