
 Zero Waste Packaging Market | 2026-2036
Zero Waste Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Zero Waste Packaging Market Intelligence
Direct-to-retailer supply chains for zero waste packaging is narrowing as major buyers consolidate vendor lists and demand certified circularity documentation. Amcor leverages its global film and fiber network to secure multi-year supply agreements with grocery retailers. Mondi competes through integrated kraft paper and containerboard operations that sustain cost advantages in compostable shipping materials. Tetra Pak dominates aseptic carton recycling infrastructure in European markets, controlling collection and reprocessing partnerships that extend its effective channel reach.
Zero waste packaging comprises systems designed to eliminate landfill or incineration disposal through material recovery, biological decomposition, or repeated use cycles, typically employing mono-material constructions, food-grade barriers below 5% by weight, and standardized sorting labels compatible with existing municipal streams. Its primary commercial purpose is to satisfy retailer and brand sustainability commitments while reducing extended producer responsibility fees. Compostable formats lead in fresh produce and food service applications where contamination rates render mechanical recycling impractical. Reusable packaging concentrates margin pools in B2B logistics loops for beverages and personal care, where deposit-return schemes amortize collection costs across hundreds of use cycles. Bioplastics occupy a specialized tier constrained by industrial composting access and anaerobic digestion capacity gaps in most regions.
The European Commission's Packaging and Packaging Waste Regulation shapes minimum recycled content thresholds and standardized reuse targets across EU member states. The US EPA and state-level extended producer responsibility laws in California and Oregon drive demand for recyclable and compostable certifications in North American markets. ISO 17088 and ASTM D6400 testing protocols govern industrial compostability claims, creating market access barriers for uncertified suppliers. Stakeholders must monitor regulatory divergence between jurisdictions that mandate recyclability versus those prioritizing reuse quotas, as this split determines capital allocation toward material innovation versus reverse logistics infrastructure.
Market Dynamics
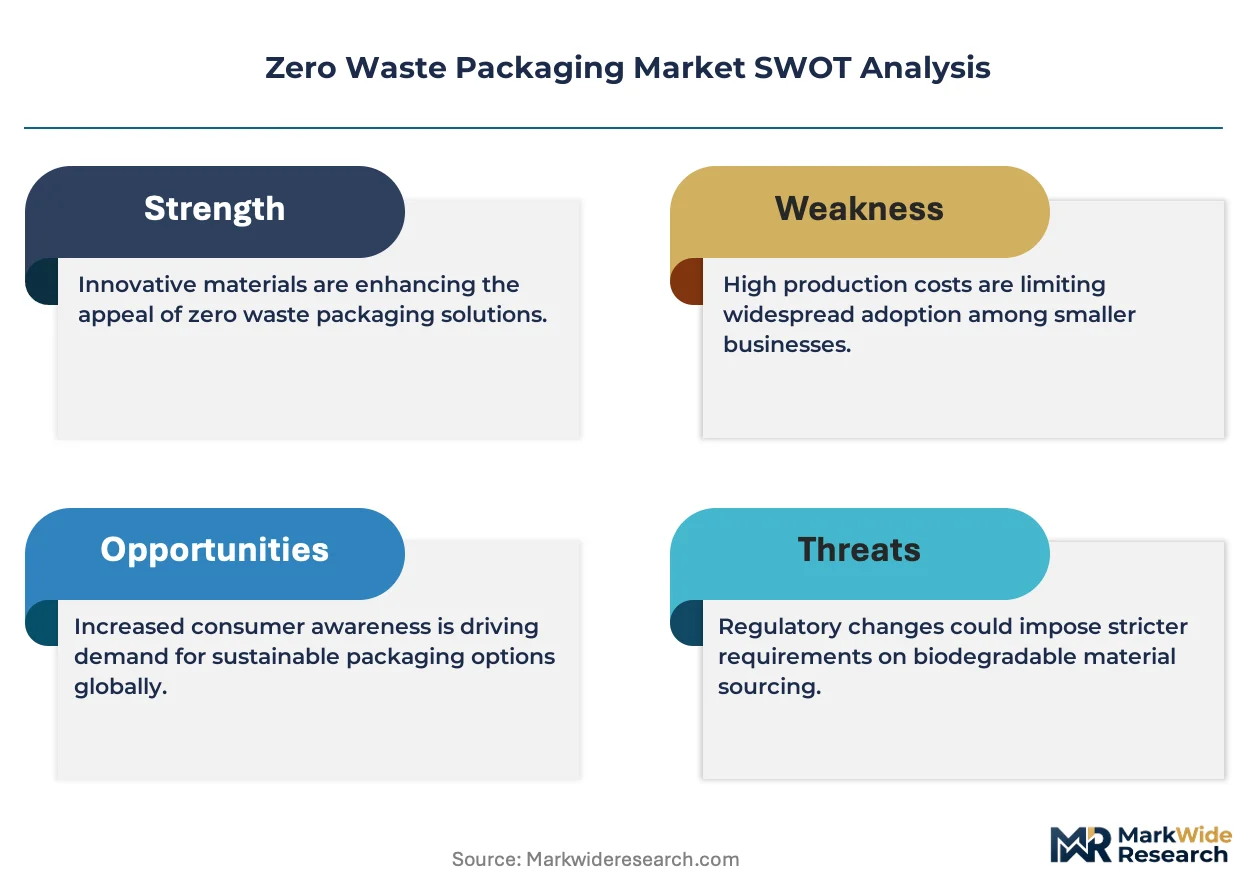
Extended producer responsibility schemes are compressing packaging economics by internalizing end-of-life costs that brands previously externalized to municipal waste systems. The EU Packaging and Packaging Waste Regulation forces rapid redesign of multi-material formats into mono-material or certified compostable alternatives.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandated recyclability thresholds and reuse targets create immediate compliance-driven demand for redesign services and certified material substitutes across food and beverage supply chains.
- Deposit-return schemes:Germany's DRS infrastructure for beverage containers demonstrates operational viability at scale, attracting parallel investments in personal care and household product loop systems.
- Industrial composting capacity expansion:Anaerobic digestion facilities in the Netherlands and France unlock market access for PLA and PHA food service packaging previously constrained by disposal infrastructure gaps.
Market Restraints
- Bioplastic feedstock volatility:Corn and sugarcane price swings directly compress margins for PLA producers lacking long-term agricultural supply contracts.
- Mechanical recycling contamination:Food residue and adhesive labels degrade rPET and rPP quality, limiting closed-loop applications to lower-value products.
- Composting certification fragmentation:Divergence between ISO 17088, ASTM D6400, and emerging national standards forces redundant testing and regional SKU proliferation.
Strategic Opportunities
- Reusable packaging-as-a-service:B2B logistics operators in Germany pilot subscription models for standardized shipping containers, capturing margin pools from single-use corrugated displacement.
- Digital product passports:Integration of blockchain traceability with packaging QR codes enables granular carbon accounting that satisfies CSRD disclosure requirements.
- Fresh produce compostable films:Underpenetrated categories in French retail chains present first-mover advantages for barrier-coated cellulose alternatives to conventional plastic wrap.
Industry Challenges
- Food-grade barrier formulation:Chemists with expertise in sub-5% barrier coatings remain scarce, elongating R&D timelines for mono-material flexible packaging.
- Legacy filling line retrofitting:Aseptic carton converters face capital-intensive equipment modifications to handle novel substrate thicknesses and sealing temperatures.
- Multi-jurisdiction compliance synchronization:Brands operating across EU member states, California, and Oregon must reconcile divergent extended producer responsibility reporting formats and fee structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zero Waste Packaging Market |
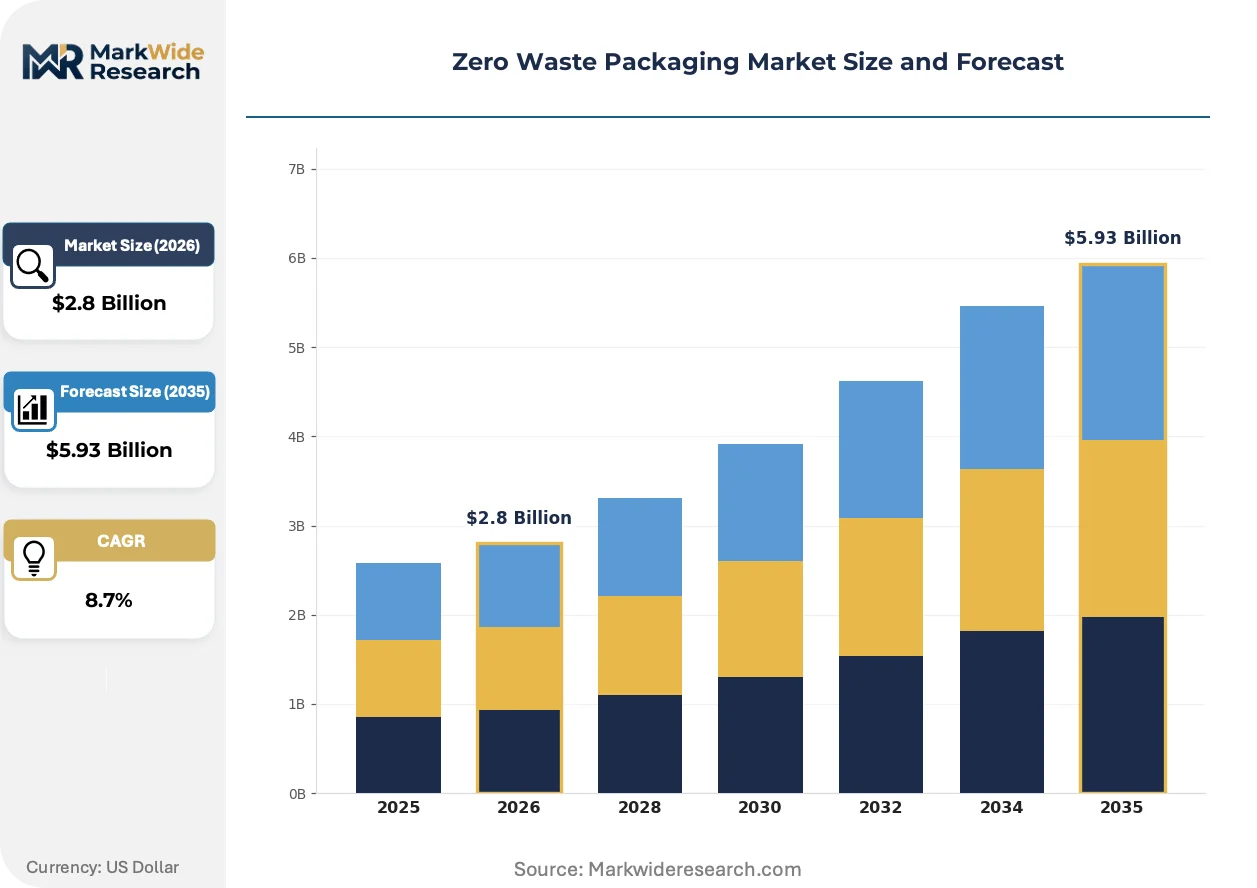
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recyclable, Compostable, Reusable, Edible Material: Glass, Paper, Bioplastics, Plant-based Polymers End User: Food & Beverage, Personal Care, Household Goods, E-commerce Distribution Channel: Online, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Amcor, Mondi, Pakoro, Crown Holdings, Stora Enso, Smurfit Westrock, Ball Corporation, Elopak, Tetra Pak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zero Waste Packaging Market Strategic Shifts & Innovations
Material science advances are collapsing the performance gap between conventional plastics and bio-based alternatives. Three interconnected developments are compressing adoption timelines and reshaping supplier relationships.
Mono-material flexible packaging is collapsing the technical barrier that previously forced brands into multi-layer constructions. Food-grade ethylene vinyl alcohol copolymers formulated for polyethylene compatibility enable high-barrier pouches that sort cleanly in existing mechanical recycling streams. Major grocery retailers in Germany and France are accelerating supplier qualification for these formats ahead of 2030 recyclability mandates.
REACH restrictions on per- and polyfluoroalkyl substances are forcing immediate reformulation of grease-resistant food service packaging. The European Chemicals Agency's 2023 proposal to limit PFAS across all food contact materials compresses transition timelines from years to months. Paperboard converters are pivoting toward silicone- and bio-wax barrier coatings, though heat-seal performance gaps persist in high-temperature applications.
Retailer consolidation of vendor lists is concentrating procurement leverage among fewer packaging suppliers. Certification-driven pre-qualification requirements—spanning ISO 17088 compostability, FSC chain-of-custody, and carbon footprint verification—are raising barriers for mid-tier converters. Dutch supermarket chains now require third-party circularity documentation as a condition of contract renewal, displacing uncertified competitors from shelf-ready packaging categories.
Zero Waste Packaging Market Segmentation
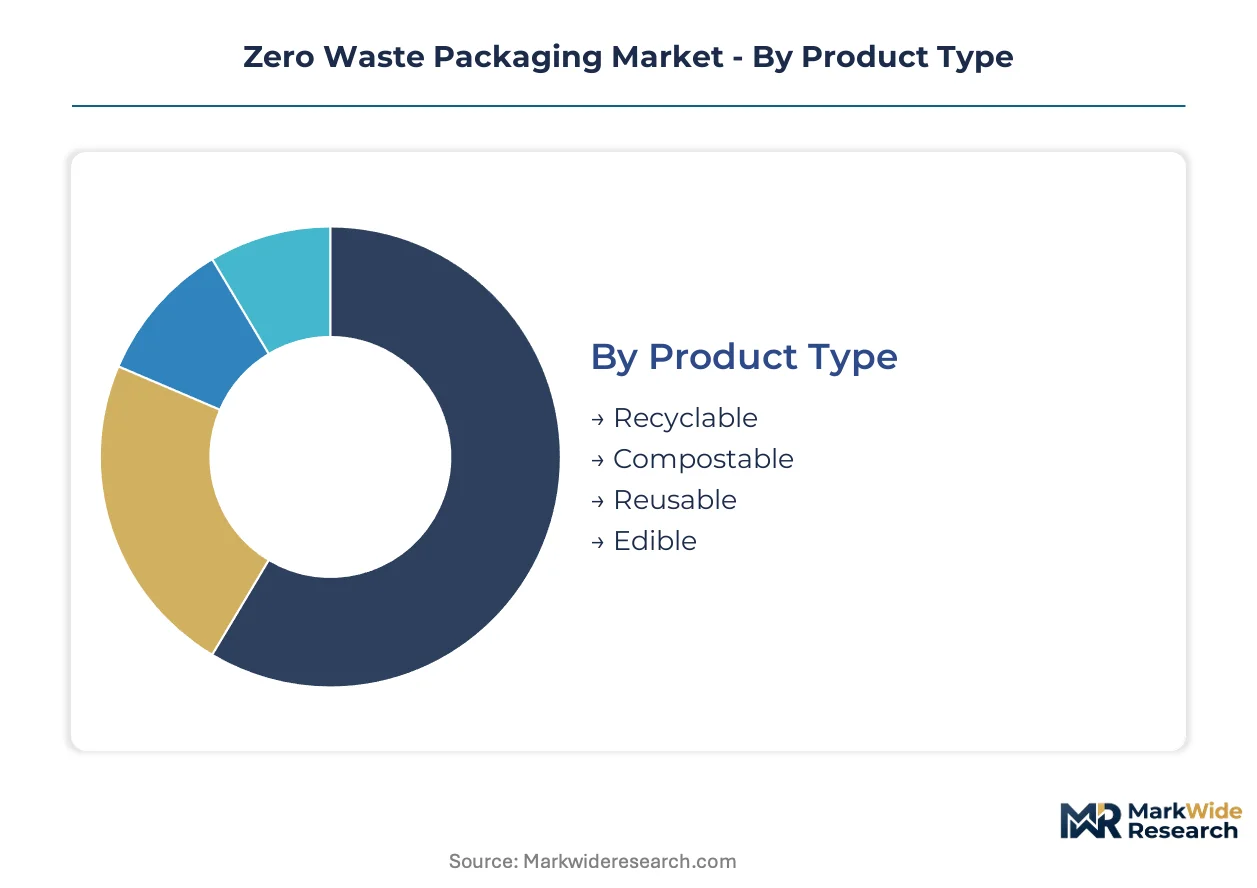
Segmentation in zero waste packaging reveals divergent replacement cycles that dictate capital deployment and inventory strategy. Recyclable formats turn over fastest through municipal collection loops, while reusable systems amortize costs across hundreds of cycles. Understanding these velocity differences separates pricing power from commodity exposure.
Product Type:
Reusable formats lock capital into circulation for years while compostable and edible alternatives exit the value chain within weeks, compressing margin capture windows.
- Recyclable:Mono-material constructions with sub-5% barrier coatings sort cleanly in mechanical recycling streams. German grocery retailers demand ISO-compliant certification as a contract prerequisite, displacing multi-layer alternatives from shelf-ready categories.
- Compostable:PLA and PHA formulations require industrial composting infrastructure access that remains patchy outside the Netherlands and France. Fresh produce applications dominate where contamination renders mechanical recycling impractical.
- Reusable:Standardized shipping containers and deposit-return beverage systems amortize collection costs across 50-200 use cycles. Germany's DRS infrastructure demonstrates operational viability at scale.
- Edible:Seaweed and rice-based films serve niche food service portions where single-bite consumption eliminates disposal entirely. Scale constraints limit applications to premium hospitality segments.
Recyclable formats anchor the volume base while reusable systems gain share at the steepest rate as deposit-return schemes expand beyond beverages.
Material:
Cost tiers separate incumbent substrates with mature recycling infrastructure from biopolymers bearing feedstock volatility and certification premiums.
- Glass:Infinite recyclability and inert barrier properties sustain dominance in beverage and personal care categories. Heavy weight elevates transport costs, constraining e-commerce penetration.
- Paper:Kraft paper and containerboard operations achieve cost advantages in compostable shipping materials through integrated pulp-to-box production. REACH restrictions on PFAS force immediate reformulation of grease-resistant grades.
- Bioplastics:Corn and sugarcane price swings compress margins for PLA producers lacking long-term agricultural supply contracts. Industrial composting capacity gaps in most regions constrain addressable market.
- Plant-based Polymers:Cellulose and chitosan alternatives occupy a specialized tier between paper rigidity and plastic flexibility. Barrier performance gaps persist in high-moisture applications.
Paper commands the widest application footprint while plant-based polymers expand most quickly as barrier coating chemistry advances.
End User:
Customer sophistication varies sharply across sectors, with food and beverage brands facing the most stringent extended producer responsibility compliance deadlines.
- Food & Beverage:Aseptic carton converters retrofit filling lines to handle novel substrate thicknesses and sealing temperatures. EU Packaging and Packaging Waste Regulation mandates force rapid multi-material redesign.
- Personal Care:Refillable formats concentrate margin pools where deposit-return schemes amortize collection infrastructure across high-value products. German retailers pilot subscription models for standardized containers.
- Household Goods:Concentrated and solid formulations reduce packaging mass per use, enabling compostable primary packaging with recyclable secondary shipping materials.
- E-commerce:Corrugated displacement by reusable shipping containers accelerates where B2B logistics operators capture margin pools from single-use formats. Last-mile density determines collection economics.
Food and beverage anchors procurement volume while e-commerce climbs the fastest as reverse logistics infrastructure matures.
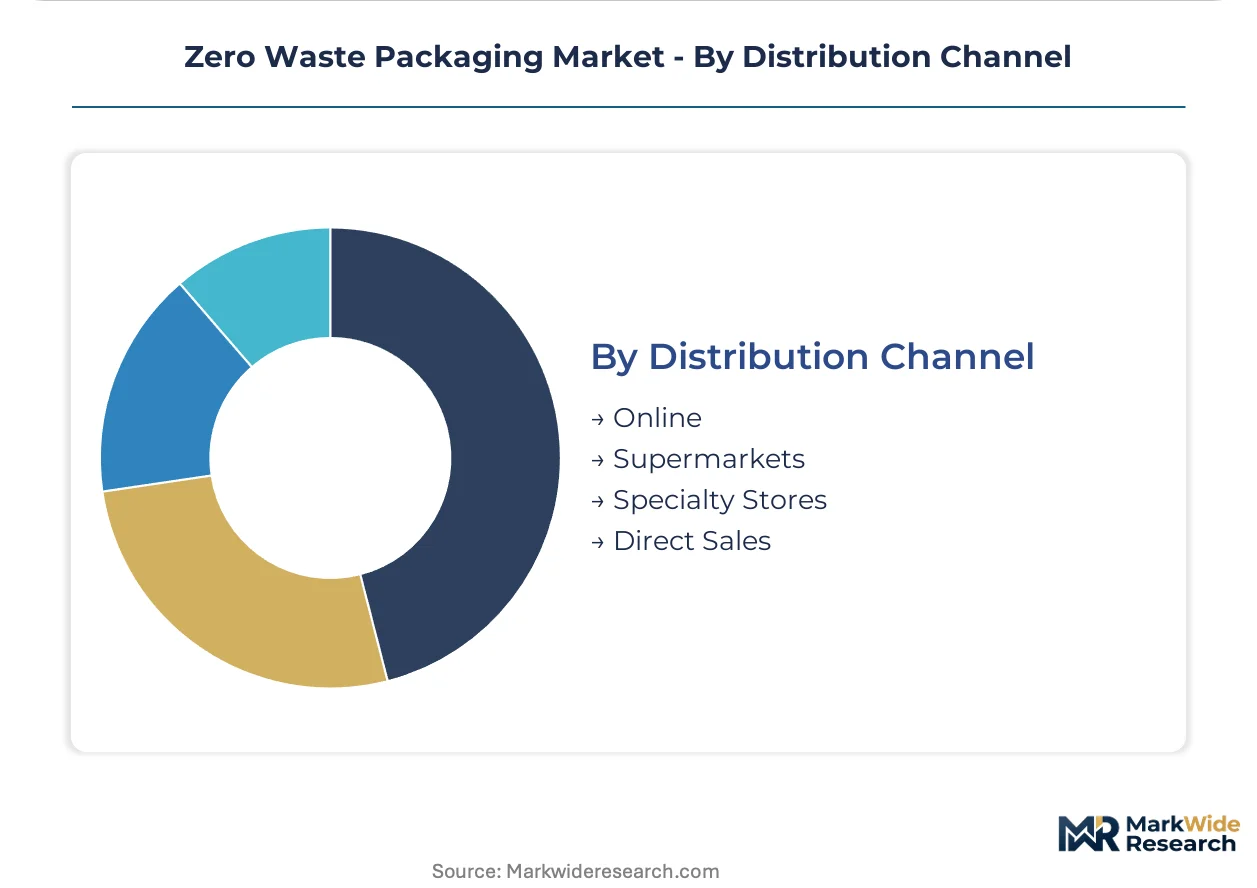
Distribution Channel:
Channel concentration shapes certification requirements, with direct retail procurement demanding the most extensive circularity documentation.
- Online:Direct-to-consumer shipments prioritize lightweight compostable fillers and right-sized corrugated alternatives. Returns complexity constrains reusable format adoption.
- Supermarkets:Dutch chains require third-party circularity documentation as a condition of contract renewal, displacing uncertified competitors from shelf-ready categories.
- Specialty Stores:Premium positioning supports edible and artisanal reusable formats where consumer education justifies price premiums. Limited scale constrains supplier qualification investment.
- Direct Sales:B2B logistics operators in Germany pilot packaging-as-a-service subscriptions for standardized shipping containers, capturing recurring revenue from single-use displacement.
Supermarkets anchor the procurement base while direct sales expands most quickly as subscription models prove unit economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands pricing premiums through integrated deposit-return infrastructure while Italy struggles with fragmented municipal collection systems. This asymmetry concentrates procurement leverage in northwestern European markets where extended producer responsibility schemes internalize end-of-life costs most aggressively.
Germany
Dual systems for lightweight packaging and the Pfand deposit-return scheme for beverage containers create the continent's most mature circular economy infrastructure. The Packaging Act mandates minimum recycled content thresholds that force rapid supplier qualification. The Rhine-Ruhr industrial corridor hosts integrated paper and bioplastic converters retrofitting lines for mono-material flexible formats.
France
Citéo extended producer responsibility fees penalize non-recyclable formats, redirecting brand procurement toward certified compostable alternatives. The AGEC anti-waste law imposes reuse targets for e-commerce shipments that accelerate reusable packaging pilots. The Paris Basin clusters food-grade barrier coating specialists serving major retail chains.
Netherlands
Anaerobic digestion capacity in Groningen and North Brabant unlocks market access for PLA food service packaging previously constrained by disposal infrastructure gaps. The National Plastic Pact sets binding reduction targets that concentrate demand for fiber-based alternatives. The Randstad logistics network enables cost-effective reverse collection for B2B reusable container systems.
United States
California and Oregon extended producer responsibility laws drive demand for recyclable and compostable certifications, though federal fragmentation limits standardization. The EPA signals tightening landfill diversion targets that pressure multi-material redesign. The Pacific Northwest clusters industrial composting facilities serving Seattle and Portland metropolitan areas.
United Kingdom
Extended producer responsibility reforms scheduled for implementation create compliance-driven demand ahead of statutory deadlines. The Environment Agency's packaging recovery note system exposes cost differentials between mechanical recycling and composting pathways. The Midlands packaging manufacturing belt attracts investment in mono-material flexible film capacity.
Zero Waste Packaging Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying certified substrates and barrier coatings. The vendor base concentrates among integrated paper and fiber converters with captive pulp supply, while mid-tier flexible film specialists face margin compression from retailer consolidation. Three archetypes dominate: multinational platform operators with reverse logistics networks, regional integrated fiber converters, and specialty barrier coating formulators. Competitive moves center on multi-year supply agreements with grocery retailers and strategic partnerships with industrial composting operators.
Within the platform integrator tier, Amcor and Tetra Pak occupy positions defined by global collection infrastructure and aseptic processing expertise respectively. Mondi exemplifies the integrated fiber converter archetype through kraft paper and containerboard operations that sustain cost advantages in compostable shipping categories. These three companies represent the competitive poles around which mid-tier specialists must position for contract qualification.
| Leading Market Players |
|---|
| Amcor |
| Mondi |
| Pakoro |
| Crown Holdings |
| Stora Enso |
| Smurfit Westrock |
| Ball Corporation |
| Elopak |
| Tetra Pak |
| Others |
Cost & Logistics Intelligence
EU Packaging and Packaging Waste Regulation compliance deadlines compress both pricing tier spreads and supply chain configuration by forcing rapid supplier qualification for certified mono-material formats. Agricultural feedstock volatility for PLA and PHA bioplastics determines margin capture windows while industrial composting infrastructure gaps in most regions constrain addressable market tiers.
Pricing Analysis
The customization-premium spread separates configured-to-order barrier-coated cellulose films from standard kraft paper grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Pricing pressure stems from retailer consolidation of vendor lists demanding redundant ISO 17088 and FSC documentation. Food and beverage brands exhibit highest price sensitivity due to extended producer responsibility fee exposure, while personal care refillable formats tolerate premiums for deposit-return scheme participation.
Supply Chain Analysis
Export-control regimes on barrier coating chemistries and PFAS alternatives limit technology flows between EU and North American converters. Supply concentrates in Germany, France, and the Netherlands where integrated pulp-to-box operations and anaerobic digestion capacity cluster. Raw material dependencies center on corn and sugarcane feedstocks for PLA, Nordic softwood pulp for kraft paper, and ethylene vinyl alcohol copolymers for mono-material flexible films. Single-source vulnerability runs through agricultural commodity contracts lacking long-term hedging. Distribution runs through direct-to-retailer procurement channels with third-party circularity documentation gates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation mandates a high-growth disruption trajectory by compressing multi-material redesign timelines from years to months.
For Market Incumbents: Insulate market position through backward integration into captive pulp supply and anaerobic digestion partnerships that lock in compostable format disposal capacity. Prioritize certification investment in ISO 17088 and FSC chain-of-custody to defend against retailer vendor list consolidation that displaces uncertified competitors from shelf-ready categories. For New Entrants and Emerging Players: Build out white-space presence in fresh produce compostable films for French retail chains and B2B reusable container subscription models in German logistics corridors. The most penetrable segment sits in underdeveloped industrial composting regions where first-mover barrier-coated cellulose alternatives capture margin pools from conventional plastic wrap displacement. For Investors and Strategic Acquirers: The market sits at a regulatory-enforcement phase that favors integrated fiber converters with captive certification infrastructure and reverse logistics networks. Long-term viability hinges on acquisition targets possessing multi-year grocery retailer supply agreements and industrial composting operator partnerships. The signal to watch is divergence between EU member state implementation timelines that creates arbitrage opportunities for compliant format suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-material Flexible Film Capacity Expansion | Amcor and Mondi retrofit lines to meet German retailer 2030 recyclability mandates ahead of competitors. |
| Industrial Composting Infrastructure Partnership | Tetra Pak secures anaerobic digestion access in Netherlands and France to unlock PLA food service packaging markets. |
| Digital Product Passport Integration | Blockchain traceability with QR codes satisfies CSRD disclosure requirements for granular carbon accounting. |
| Reusable Packaging-as-a-Service Launch | B2B logistics operators in Germany pilot subscription models capturing recurring revenue from single-use corrugated displacement. |
| PFAS-free Barrier Coating R&D Investment | Paperboard converters develop silicone and bio-wax alternatives ahead of ECHA restrictions on food contact materials. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EU regulatory filings, industry association reports, and customs trade data. Primary interviews engaged packaging procurement managers at major grocery retailers, technical R&D directors at integrated fiber converters, regulatory affairs leads at bioplastic producers, and sustainability officers at food and beverage brands. Secondary validation drew from ECHA restriction proposals, EU Packaging and Packaging Waste Regulation impact assessments, and extended producer responsibility fee schedules across member states. Bottom-up demand modeling triangulated against top-down market sizing from production capacity announcements.
Forecast inputs incorporate material substitution rates, regulatory compliance deadlines, and infrastructure deployment timelines across the projection horizon. Segmentation dimensions modeled include product type, material substrate, end-use industry, and distribution channel, with additional weighting for regional regulatory cluster intensity. CAGRs derive from installed base turnover velocity and replacement cycle compression. Industry-specific inputs include industrial composting capacity buildout schedules and deposit-return scheme expansion trajectories.
Stress conditions across agricultural commodity price bands, regulatory enforcement variance, and mechanical recycling contamination rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on EU member state implementation synchronization and bioplastic feedstock contract coverage. Material shifts in REACH restriction scope or ECHA PFAS limitation timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sustainable Packaging
Bagasse Bowls Market
Sustainable Packaging
Eco-Friendly Straw Market
Sustainable Packaging
Sustainable Foodservice Packaging Market
Sustainable Packaging
Europe Sustainable Packaging Market
Sustainable Packaging
Sustainable Packaging Market
Sustainable Packaging
Bio-Based Cutlery Market
Sustainable Packaging
Japan Green Packaging Market
Sustainable Packaging
Europe Eco-Friendly Packaging Market
Sustainable Packaging
Plant Based Packaging Market
Sustainable Packaging
Wheat Straw Cutlery Market
Sustainable Packaging
Asia-Pacific Eco-Friendly Packaging Market
Sustainable Packaging
Global Disappearing Packaging Market
Sustainable Packaging
Eco Friendly Bottles Market
Sustainable Packaging
Sustainable Plastic Packaging Market
Sustainable Packaging
Green Packaging Market
Sustainable Packaging
PVC-Free Packaging Market