
 Sustainable Foodservice Packaging Market | 2026-2036
Sustainable Foodservice Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Sustainable Foodservice Packaging Market Outlook
A capital-intensity divergence between integrated fiberboard producers and specialty bioplastic formulators is reorganizing competitive tiers in sustainable foodservice packaging. Huhtamaki Oyj leverages its molded-fiber manufacturing network across Europe and North America to anchor supply for quick-service chains. Smurfit Kappa Group sustains cost advantages through captive pulp sourcing and recycled-content integration. Sealed Air Corporation differentiates via active and intelligent packaging layers that extend shelf life in foodservice distribution.
Sustainable foodservice packaging comprises containers, utensils, wraps, and serviceware engineered from biodegradable polymers, plant fibers, or recycled substrates to reduce environmental impact across the food consumption cycle. These products must meet performance thresholds for grease resistance, temperature stability, and structural integrity under hot-fill conditions while conforming to compostability certifications such as ASTM D6400 or EN 13432. Plant-based materials dominate volume in the material-type dimension, though compostable polymers command premium pricing in closed-loop catering environments. Containers lead the product-type category, driven by delivery and takeout expansion, while cutlery trails due to durability limitations in high-temperature applications. Restaurants represent the most concentrated end-user segment, with full-service chains negotiating direct supply agreements that bypass wholesale distributors.
The EU Green Deal and F-Gas Regulation shape material innovation pathways for European producers, while FDA food-contact notifications govern substrate approvals in the United States. BIS certification requirements in India and China's GB standards for biodegradable plastics create divergent compliance thresholds that fragment cross-border product standardization. Stakeholders must monitor regulatory harmonization progress between compostability certification schemes, as misaligned definitions of biodegradation across jurisdictions threaten to complicate global sourcing strategies and capital allocation decisions.
Market Dynamics
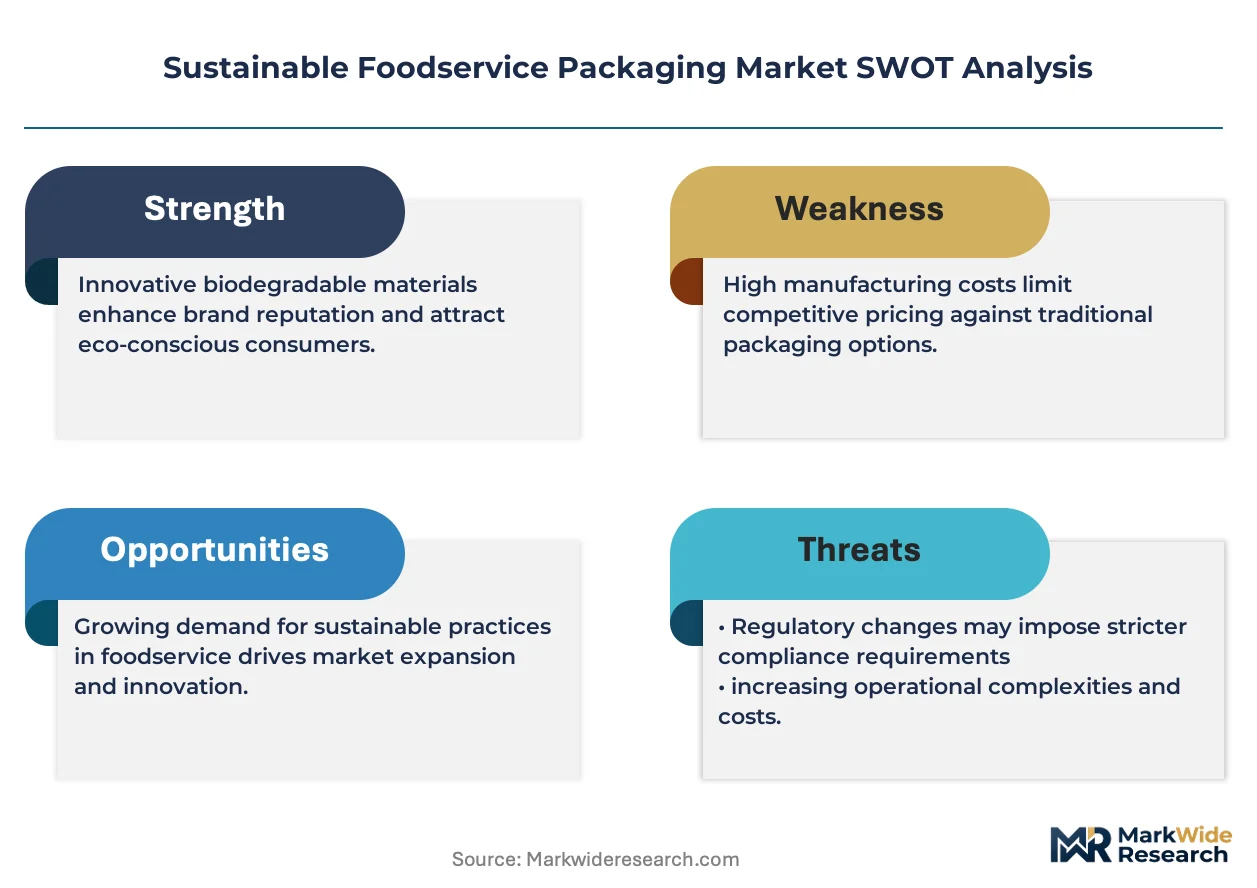
The EU Single-Use Plastics Directive and California's packaging waste laws are forcing material substitution timelines that outpace supply chain readiness, compressing conversion windows for foodservice operators while fiberboard capacity expansion lags demand acceleration.
Growth Catalysts
- Deposit-return systems:Germany's DSD framework and similar schemes across Scandinavia create guaranteed offtake channels for certified compostable packaging, locking in volume commitments from quick-service chains.
- Quick-service restaurant conversion:North American burger and pizza chains are mandating fiber-based clamshells and bowls in procurement specifications, pulling forward capacity investments.
- EU Green Deal implementation:The F-Gas Regulation and Circular Economy Action Plan establish binding recycled-content thresholds that favor molded-fiber solutions over conventional plastics.
Market Restraints
- Pulp price volatility:OCC (old corrugated containers) and virgin softwood pulp input costs swing with Chinese import policy and Nordic forest harvest cycles, compressing margins for non-integrated converters.
- Composting infrastructure gaps:Industrial composting facility concentration in Germany and the Netherlands leaves southern and eastern European markets without end-of-life pathways for certified products.
- Performance limitations:Fiber-based cutlery and hot-fill containers fail durability tests above 85°C, restricting substitution in soup and fried food applications.
Strategic Opportunities
- India regulatory alignment:BIS certification requirements for biodegradable plastics and state-level plastic bans in Maharashtra and Tamil Nadu open premium positioning for ASTM D6400-certified imports.
- Active packaging integration:Oxygen scavengers and moisture regulators from intelligent packaging layers are converging with compostable substrates to extend prepared food shelf life in foodservice distribution.
- Closed-loop catering contracts:Corporate campus and stadium concessionaires are piloting return-wash-reuse systems that bypass composting infrastructure entirely.
Industry Challenges
- Compostability certification timelines:EN 13432 and ASTM D6400 testing protocols require 180-day biodegradation validation that delays product launches by 12-18 months.
- Thermoforming equipment retrofit costs:Converting legacy PET and PP lines to handle PLA and PHA biopolymers demands capital outlays that strain mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sustainable Foodservice Packaging Market |
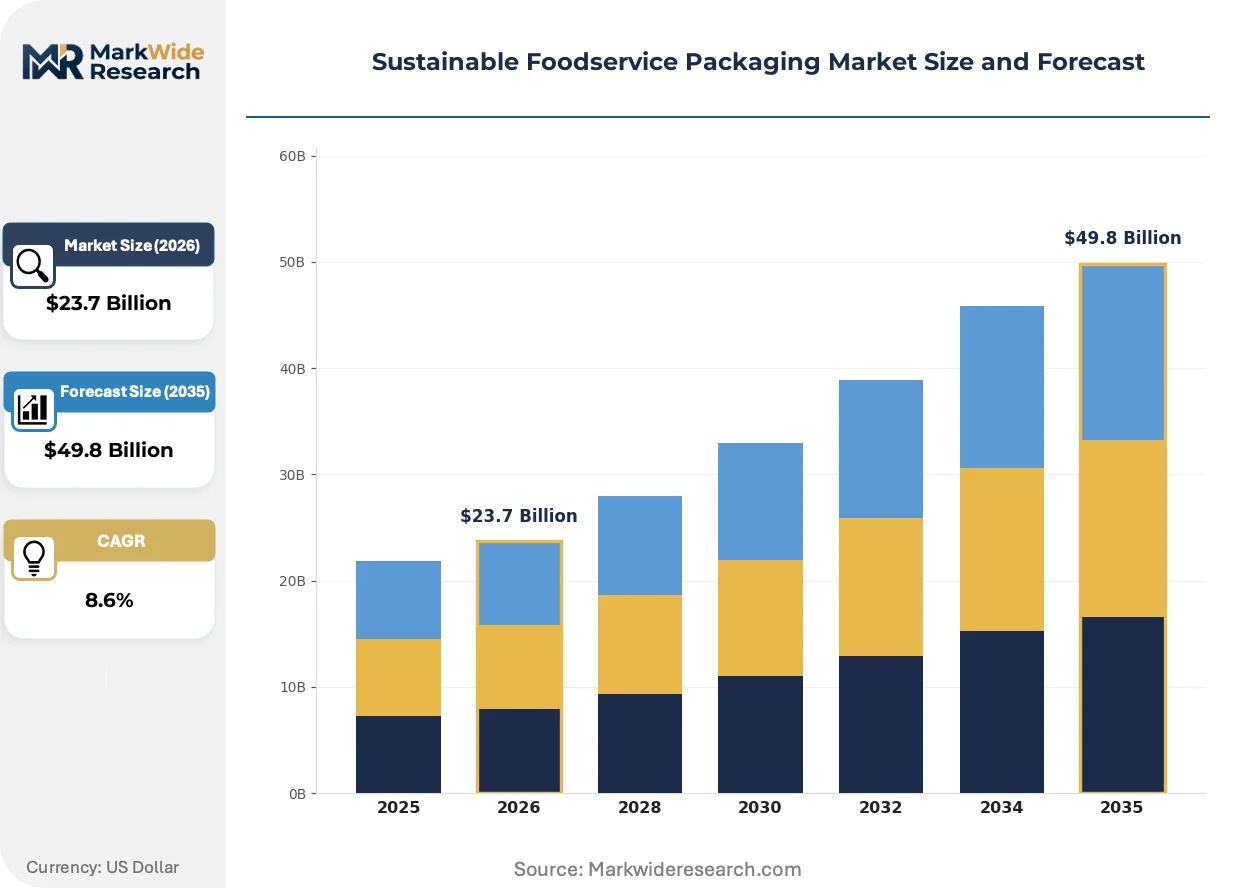
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Biodegradable, Compostable, Recyclable, Plant-Based Product Type: Containers, Cutlery, Straws, Bags End User: Restaurants, Catering Services, Food Trucks, Cafés Distribution Channel: Online Retail, Wholesale, Direct Sales, Grocery Stores |
| Companies Covered | Smurfit Kappa Group, Sabert Corporation, Tetra Pak, Huhtamaki Oyj, Pactiv Evergreen, Amcor Plc, WestRock Company, Sealed Air Corporation, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustainable Foodservice Packaging Market Strategic Shifts
Molded-fiber manufacturing is advancing faster than regulatory harmonization, creating capability gaps between European and North American certification standards while delivery-format packaging absorbs disproportionate R&D investment.
Barrier coating technology is miniaturizing. Nanocellulose and bio-wax layers now provide grease resistance equivalent to polyethylene laminates at sub-micron thickness. Quick-service chains in Germany and the Netherlands are qualifying these coatings for hot-fill applications under accelerated timelines. The technology is miniaturizing material usage per unit, reducing fiber weight by 15-20% without sacrificing performance thresholds.
REACH authorization requirements for per- and polyfluoroalkyl substances are eliminating legacy grease-resistant chemistries from European food contact materials. ECHA's restriction proposals force reformulation of molded-fiber bowls and plates before 2026 deadlines. Nordic producers are accelerating fluorine-free alternatives through joint development programs with pulp suppliers.
Direct procurement by full-service restaurant chains is displacing wholesale distributor intermediaries. Chains with 500+ locations negotiate volume commitments directly with Huhtamaki and Smurfit Kappa, securing price stability and custom specifications. This pattern concentrates most visibly in the United Kingdom and Ireland, where consolidated foodservice groups command leverage over packaging procurement decisions.
Sustainable Foodservice Packaging Market Segmentation
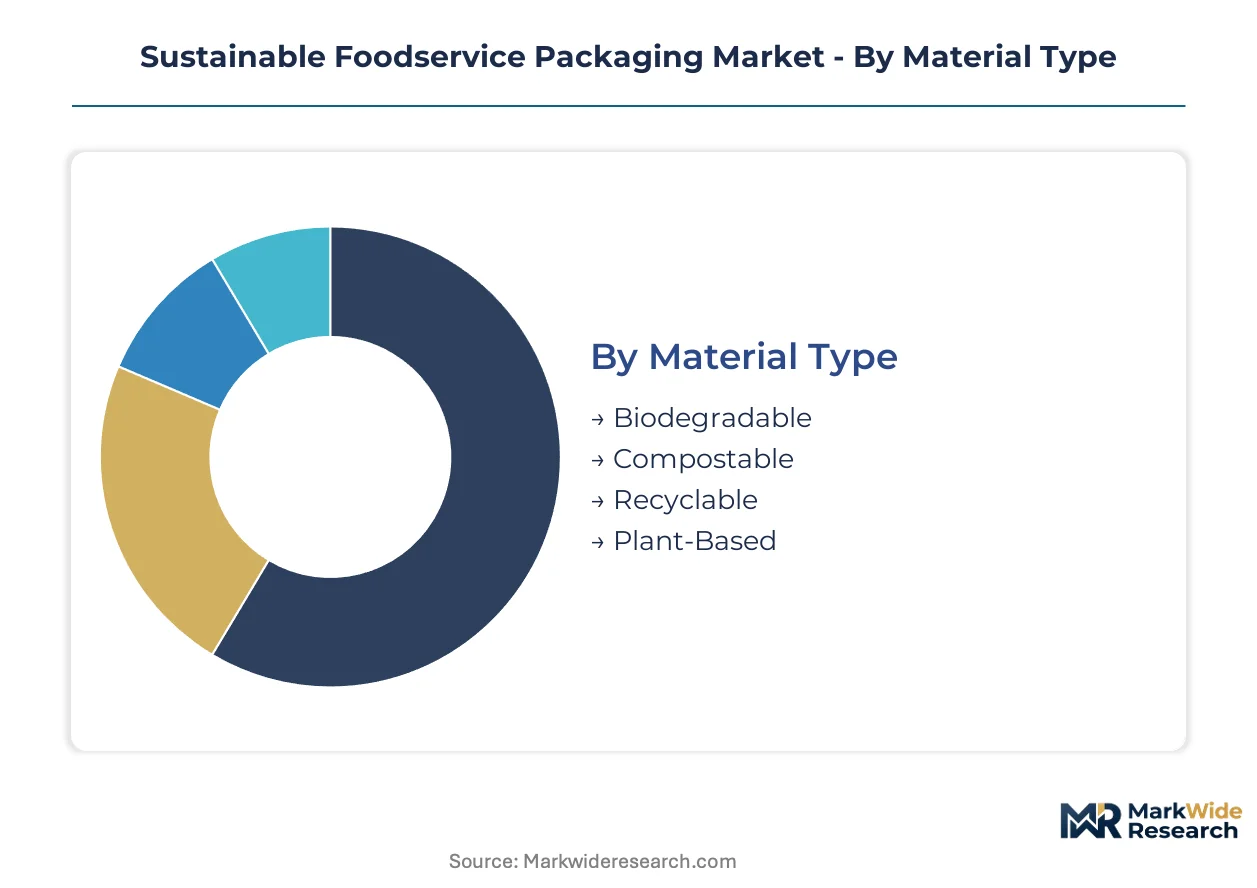
Segmentation in sustainable foodservice packaging reveals how material certifications, product durability requirements, and procurement channel preferences create distinct commercial battlegrounds. Each dimension carries different margin profiles and regulatory exposure, forcing suppliers to prioritize investment across incompatible technical pathways.
Material Type:
Channel mix varies sharply by material: plant-based and recyclable grades dominate grocery retail and wholesale, while certified compostable streams concentrate in direct sales to restaurant chains with controlled waste streams.
- Biodegradable:Polymers engineered for microbial breakdown under anaerobic or aerobic conditions without requiring industrial composting infrastructure. Demand clusters in southern European markets where composting facility coverage remains patchy and operators seek landfill-disposable alternatives. ASTM D6400 certification unlocks California and India procurement specifications.
- Compostable:Materials meeting EN 13432 or ASTM D6400 standards for complete biodegradation within defined timeframes and toxicity thresholds. Germany's DSD deposit-return framework and Netherlands industrial composting network anchor volume concentration, with quick-service chains mandating certification for supplier qualification.
- Recyclable:Fiberboard and selected biopolymers compatible with existing paper and plastic waste streams. Wholesale distributors favor this grade for broad restaurant coverage where post-consumer sorting infrastructure is unreliable.
- Plant-Based:Substrates derived from agricultural residues, bamboo, or sugarcane bagasse without petroleum inputs. Online retail channels promote this category for consumer-facing sustainability claims despite higher unit costs.
By volume, plant-based leads. By growth pace, compostable is climbing the fastest.
Product Type:
Cost tier separation drives procurement patterns: containers command premium pricing for technical performance, while straws and bags compete as commodity substitutes with thinner margin structures.
- Containers:Clamshells, bowls, and boxes engineered for grease resistance and structural integrity under hot-fill conditions. Delivery and takeout expansion across North American burger and pizza chains concentrates demand, with fiber-based specifications displacing foamed polystyrene under California and EU Single-Use Plastics Directive mandates.
- Cutlery:Forks, knives, and spoons requiring flexural strength and temperature stability. Performance failures above 85°C restrict substitution in soup and fried food applications, limiting penetration in full-service Asian cuisine segments.
- Straws:Single-use beverage access devices transitioning from plastic to paper and PLA alternatives. Quick-service beverage chains drive volume through procurement mandates, though consumer acceptance of paper mouthfeel remains variable.
- Bags:Carry-out and food-contact sacks for transport and storage. Grocery store channels and food truck operators represent primary offtake, with compostable certification rarely specified at this price point.
Containers absorb the majority of R&D investment, yet cutlery presents the steepest expansion trajectory as durability improvements unlock new applications.
End User:
Customer type determines contract structure and pricing power: consolidated chains negotiate direct supply agreements, while fragmented operators purchase through wholesale intermediaries at standard list pricing.
- Restaurants:Full-service and quick-service establishments with dine-in, takeout, and delivery operations. Direct procurement by 500+ location chains in the United Kingdom and Ireland concentrates volume with Huhtamaki and Smurfit Kappa, bypassing distributor margins.
- Catering Services:Event and institutional food providers requiring bulk disposable serviceware. Corporate campus and stadium concessionaires pilot closed-loop return-wash-reuse systems that circumvent composting infrastructure requirements entirely.
- Food Trucks:Mobile operators with constrained storage space and high turnover. Wholesale and grocery store channels dominate procurement, with price sensitivity limiting adoption of certified compostable grades.
- Cafés:Coffee-focused establishments with beverage-centric packaging needs. Online retail and direct sales channels serve this segment, with custom branding requirements driving smaller order quantities at premium pricing.
Restaurants generate the highest absolute volume. Catering services are gaining share fastest as closed-loop contracts proliferate.
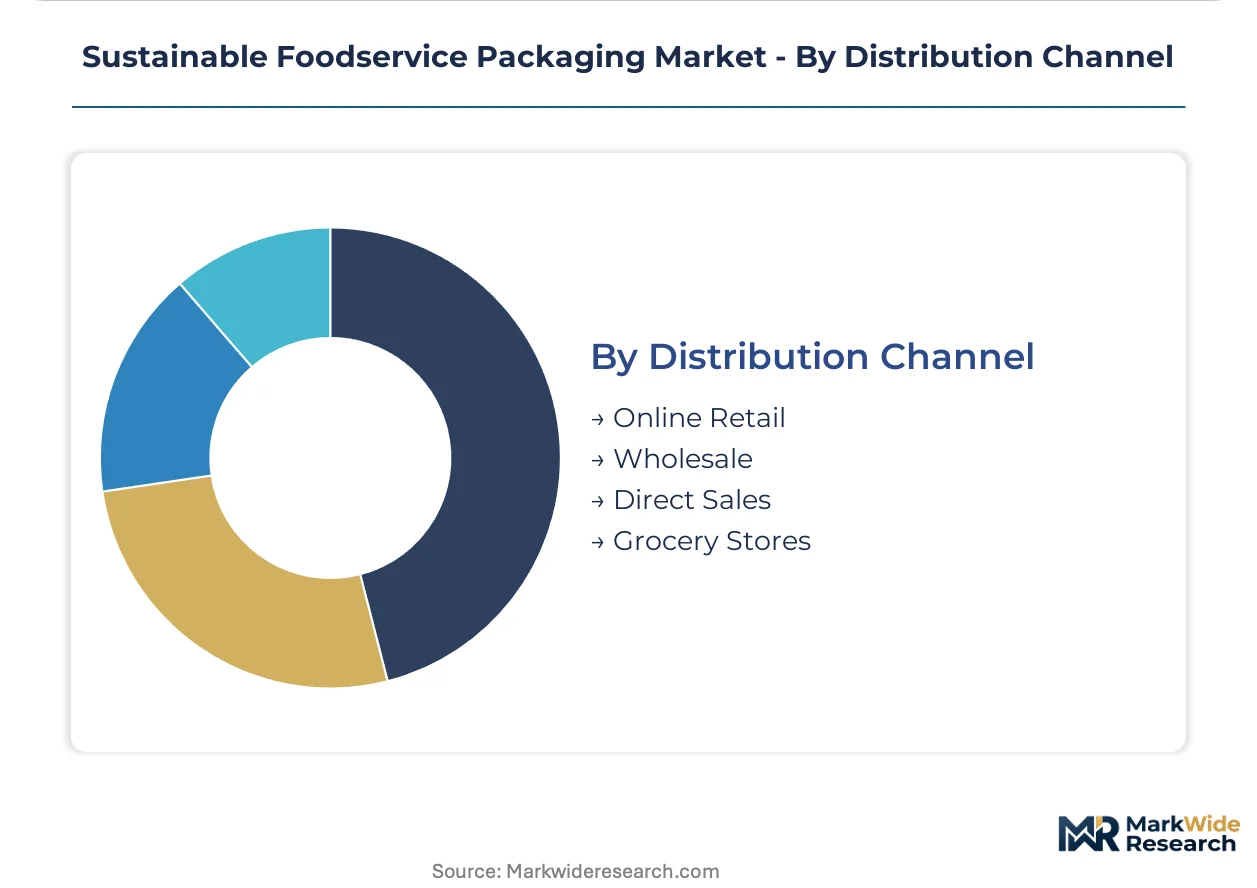
Distribution Channel:
Supply concentration shapes channel economics: direct sales and wholesale anchor commercial volume, while online retail and grocery stores serve fragmented demand with higher fulfillment costs.
- Online Retail:E-commerce platforms serving small operators and individual consumers. Plant-based and premium compostable products concentrate here, with sustainability messaging justifying price premiums over wholesale alternatives.
- Wholesale:Distributors supplying broad restaurant and foodservice coverage. Recyclable and standard biodegradable grades dominate this channel, where price competition and broad SKU availability outweigh certification requirements.
- Direct Sales:Manufacturer-to-chain relationships for large-volume accounts. Huhtamaki and Sealed Air leverage this channel for quick-service restaurant specifications, securing multi-year volume commitments and custom product development.
- Grocery Stores:Retail outlets stocking consumer-packaged disposable serviceware. Food trucks and small cafés represent primary commercial buyers, with limited penetration into certified compostable grades due to shelf-space constraints.
Wholesale moves the most units. Direct sales is expanding most quickly as procurement centralization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany exceeds that in southern European markets by margins that reflect composting infrastructure density and regulatory enforcement stringency. Deposit-return systems in German-speaking Europe lock in volume premiums that fiberboard converters elsewhere cannot replicate. Southern and eastern European markets absorb price compression from infrastructure gaps and fragmented procurement.
Germany
Quick-service chains and institutional caterers drive certified compostable packaging procurement under the DSD deposit-return framework. The EU Single-Use Plastics Directive and F-Gas Regulation enforce material substitution timelines that outpace converter capacity expansion. Industrial clusters in North Rhine-Westphalia and Bavaria host integrated pulp-to-packaging operations that supply molded-fiber containers to pan-European burger and pizza chains.
United States
California's packaging waste laws and similar state-level mandates in New York and Washington force fiber-based substitution faster than national supply chains can adapt. FDA food-contact notifications govern substrate approvals, creating compliance bottlenecks for imported biopolymers. The Pacific Northwest and Northeast Corridor concentrate quick-service restaurant procurement centralization, with direct manufacturer relationships displacing wholesale distributors in 500+ location chains.
India
State-level plastic bans in Maharashtra and Tamil Nadu accelerate demand for ASTM D6400-certified imports among quick-service operators and food truck aggregators. BIS certification requirements for biodegradable plastics fragment product standardization across state boundaries. Industrial corridors in Gujarat and Karnataka host emerging molded-fiber capacity serving domestic quick-service chains and export markets.
Netherlands
Industrial composting network density supports premium compostable packaging adoption across catering services and corporate foodservice contracts. REACH authorization requirements for per- and polyfluoroalkyl substances eliminate legacy grease-resistant chemistries ahead of 2026 deadlines. The Randstad cluster anchors Nordic producer joint development programs for fluorine-free barrier coatings.
United Kingdom
Consolidated foodservice groups in London and the Southeast command procurement leverage that compresses distributor margins and secures custom specifications from integrated manufacturers. Post-Brexit regulatory divergence from EU compostability standards complicates cross-border product certification. Direct supply agreements between full-service chains and fiberboard producers concentrate volume in England's metropolitan corridors.
Sustainable Foodservice Packaging Market Competitive Environment
Concentration sits with integrated fiberboard producers that control captive pulp sourcing and recycled-content integration. Specialty bioplastic formulators occupy a secondary tier dependent on thermoforming equipment retrofits and certification timelines. The market structures around three archetypes: integrated paperboard converters with upstream forest products control, diversified packaging conglomerates with active packaging layers, and regional molded-fiber specialists serving quick-service procurement mandates. Dominant competitive moves include direct supply agreement negotiation with 500+ location chains and barrier coating technology licensing for grease-resistant applications.
Among European-integrated producers, Huhtamaki Oyj and Smurfit Kappa Group exemplify the fiberboard archetype through molded-fiber manufacturing networks spanning multiple continents. Sealed Air Corporation occupies a differentiated position within active and intelligent packaging layers. These three names anchor the competitive landscape without exhausting its structural variety.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| Sabert Corporation |
| Tetra Pak |
| Huhtamaki Oyj |
| Pactiv Evergreen |
| Amcor Plc |
| WestRock Company |
| Sealed Air Corporation |
| Mondi Group |
| Others |
Value Chain & Pricing Dynamics
Ninety-day certification timelines for EN 13432 validation compress procurement cycles for quick-service chains while amplifying pricing power for integrated fiberboard producers with in-house testing capabilities. This lead-time pressure concentrates volume premiums in Germany and the Netherlands where deposit-return systems guarantee offtake, leaving southern European converters exposed to spot-market pulp volatility.
Pricing Analysis
The customization-premium spread separates configured-to-order molded-fiber specifications for 500-plus location chains from standard wholesale catalog pricing. Contract-based long-term offtake dominates, with price differentiation resting on ASTM D6400 certification tier and volume scale commitments. Cost compression in non-integrated converter tiers is intensifying because OCC pulp input swings with Chinese import policy. Food truck operators through wholesale channels exhibit highest price sensitivity; quick-service chains with direct supply agreements demonstrate lowest.
Supply Chain Analysis
Baltic Sea pulp transit underwrites European fiberboard converter margins, with Nordic softwood harvest cycles creating seasonal chokepoint exposure. Geographic supply concentrates in Sweden, Finland, and Germany. Raw material dependencies draw from OCC recovered paper, virgin softwood pulp, and bio-wax barrier coatings. Single-source vulnerability runs through Chinese bamboo pulp for plant-based grades. Distribution runs through direct manufacturer relationships for chain accounts and wholesale distributors for fragmented foodservice operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as reusable container return-wash-reuse systems bypass composting infrastructure entirely and capture corporate catering contracts.
For Market Incumbents: Secure captive pulp sourcing through backward integration into Nordic forest products or long-term supply agreements with OCC recovery networks. Anchor certification investment in ASTM D6400 and EN 13432 dual-validation to defend against specialty bioplastic formulators capturing quick-service procurement mandates. For New Entrants and Emerging Players: Lead with fluorine-free barrier coating technology targeting California and EU Single-Use Plastics Directive compliance deadlines. Southern European markets present most penetrable geography given composting infrastructure gaps that favor biodegradable grades over certified compostable alternatives. Go-to-market angle: landfill-disposable positioning for operators lacking industrial composting access. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because jurisdictional divergence in compostability definitions creates acquisition targets with multi-certification capabilities. Target integrated molded-fiber specialists with existing EN 13432 validation and underutilized thermoforming capacity. Signal to watch: harmonization progress between ASTM D6400 and EN 13432 testing protocols as inflection indicator for cross-border product standardization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive OCC and softwood sourcing insulates margins from Chinese import policy swings. |
| Dual Certification Investment | ASTM D6400 plus EN 13432 validation unlocks California and Germany procurement specifications simultaneously. |
| Fluorine-Free Barrier Development | REACH authorization deadlines eliminate legacy grease-resistant chemistries from European food contact materials. |
| Direct Supply Agreement Expansion | Manufacturer-to-chain relationships with 500-plus location operators displace wholesale distributor intermediaries. |
| Closed-Loop Catering Pilots | Return-wash-reuse systems with stadium concessionaires bypass composting infrastructure requirements entirely. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with quick-service procurement directors, molded-fiber plant managers, composting facility operators, and wholesale distributor category buyers. Secondary validation drew from FDA food-contact notification databases, ECHA REACH restriction proposals, EU Single-Use Plastics Directive implementation reports, and BIS certification registries. Bottom-up volume modeling triangulated against top-down market sizing across material type, product format, and end-use segment dimensions.
Across the analysis window, forecasts applied segmented growth rate derivation by material certification tier, product durability requirement, and procurement channel concentration. Modeled dimensions spanned biodegradable versus compostable versus recyclable versus plant-based grades; container, cutlery, straw, and bag formats; and restaurant, catering, food truck, and café end-use archetypes. CAGRs were computed from year-over-year progression analysis incorporating pulp price index trajectories and regulatory mandate implementation schedules.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or accelerated US state-level plastic ban adoption would require recalibration. Forecasts reflect documented assumptions regarding composting infrastructure buildout rates and barrier coating technology maturation timelines. Practitioners should keep alternative scenarios live as REACH authorization deadlines and BIS certification requirement expansions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sustainable Packaging
Europe Green Packaging Market
Sustainable Packaging
Bagasse Tableware Products Market
Sustainable Packaging
Plant Based Packaging Market
Sustainable Packaging
Eco Friendly Bottles Market
Sustainable Packaging
Global Disappearing Packaging Market
Sustainable Packaging
Europe Sustainable Packaging Market
Sustainable Packaging
Zero Waste Packaging Market
Sustainable Packaging
United States Green Packaging Market
Sustainable Packaging
Wheat Straw Cutlery Market
Sustainable Packaging
GCC Green Packaging Market
Sustainable Packaging
Japan Green Packaging Market
Sustainable Packaging
Areca Plates Market
Sustainable Packaging
Global Paper Straw Market
Sustainable Packaging
Sustainable Packaging Market
Sustainable Packaging
Green Packaging Market
Sustainable Packaging
Middle East and Africa Eco-Friendly Packaging Market