
 Plant Based Packaging Market | 2026-2036
Plant Based Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Plant Based Packaging Market Analytics
Green bond issuance and sustainability-linked project finance is rewriting competitive entry rules in plant based packaging, allowing mid-scale converters to fund fermentation and extrusion assets without full balance-sheet commitment. NatureWorks LLC leverages its integrated polylactic acid supply chain from corn dextrose to resin pellets, sustaining cost discipline across agricultural feedstock volatility. Novamont S.p.A. anchors European biopolymer capacity through its Mater-Bi production platform, while Braskem competes from Brazilian sugarcane ethanol feedstock with geographic dominance in South American flexible film markets.
Plant based packaging comprises containers, films, trays, and protective structures derived from annually renewable biomass such as polylactic acid, polyhydroxyalkanoates, or thermoplastic starch, typically processed through injection molding, thermoforming, or blown-film extrusion to achieve barrier properties against moisture and oxygen for perishable goods. Bioplastic formulations currently lead value generation due to higher unit margins and performance parity with conventional polymers in cold-chain applications, while molded fiber segments expand fastest as quick-service restaurants eliminate expanded polystyrene under operational sustainability mandates. Paperboard applications occupy mature volume positions in dry-goods secondary packaging, though wheat straw and bamboo fiber variants differentiate through lower agricultural land-use intensity than wood pulp alternatives.
The European Commission's Packaging and Packaging Waste Regulation, alongside FDA food-contact substance notifications in the United States and China's GB standards for biodegradable plastics, collectively reshape material approval pathways and cross-border shipment compliance burdens. REACH chemical registration requirements in Europe further constrain additive formulations used in biodegradable films, elevating R&D spend for formulation houses serving multinational brand owners. Stakeholders must monitor regulatory divergence between compostability certification schemes—TÜV Austria's OK Compost versus BPI labeling in North America—as this fragmentation threatens economies of scale in resin production and converter equipment design.
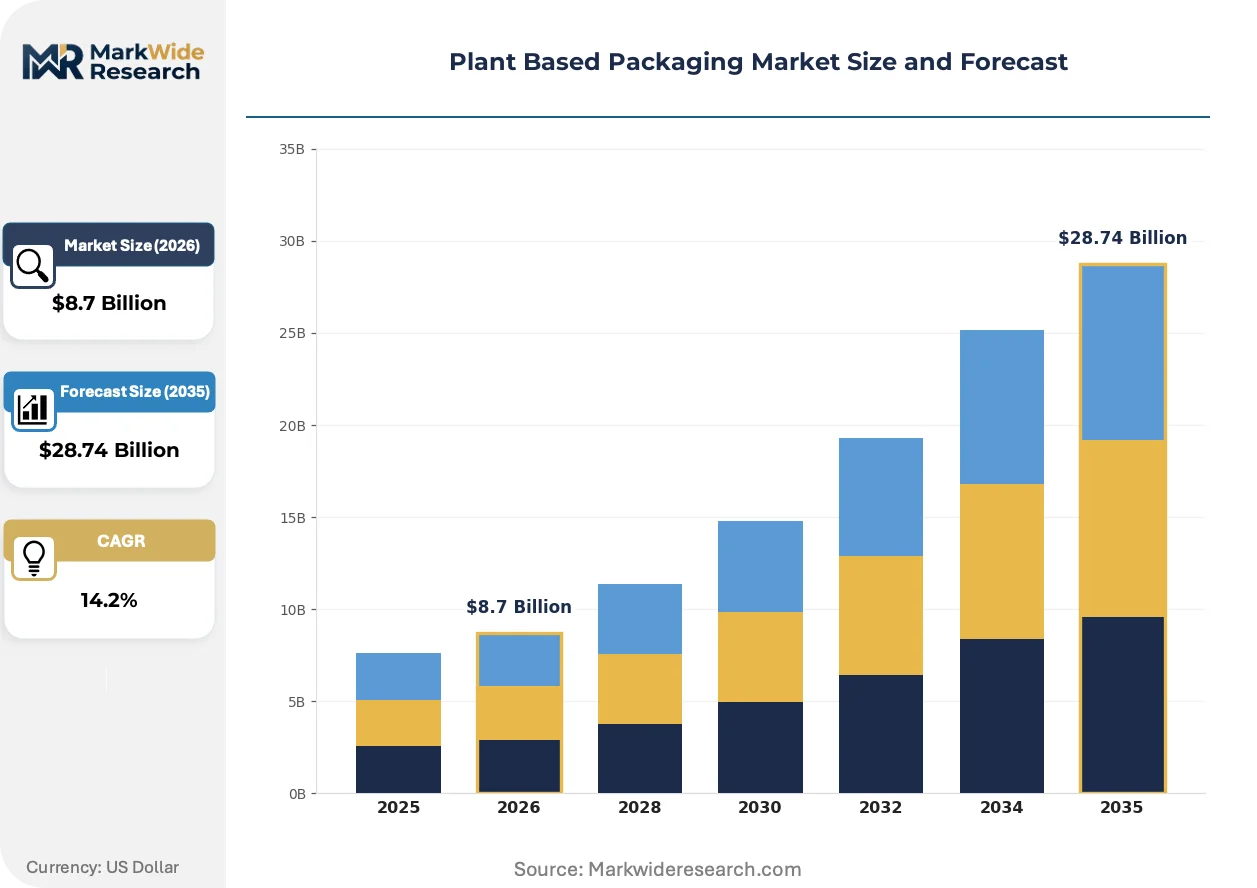
Market Dynamics
The EU Green Deal and single-use plastics directives are forcing rapid material substitution across European packaging value chains, while compostability certification fragmentation between TÜV Austria's OK Compost and BPI labeling in North America creates compliance complexity for multinational converters.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recycled content targets and extended producer responsibility schemes accelerate converter investment in bio-based extrusion lines across Germany, France, and Italy.
- Quick-service restaurant sustainability mandates:Operational elimination of expanded polystyrene by major foodservice chains drives molded fiber tray adoption for hot and cold prepared meals.
- Corn dextrose fermentation infrastructure:Agricultural processing capacity in the US Midwest and Brazilian Center-West enables integrated polylactic acid supply chains with captive feedstock security.
Market Restraints
- Agricultural feedstock price volatility:Corn and sugarcane commodity swings compress resin producer margins during drought cycles in major growing regions.
- European biopolymer supply concentration:Novamont's Mater-Bi platform and limited alternative fermentation capacity create single-source risk for flexible film converters.
- Industrial composting infrastructure gaps:Uneven anaerobic digestion and aerobic composting facility distribution limits end-of-life value realization for certified biodegradable packaging.
Strategic Opportunities
- Indian food-contact bioplastic approvals:FSSAI regulatory pathway development for polylactic acid and polyhydroxyalkanoates in dairy and ready-to-eat packaging opens subcontinent penetration for compliant converters.
- Barrier coating convergence:Integration of bio-based nanocellulose with thermoplastic starch substrates enables oxygen and moisture protection parity with multilayer conventional films.
- Closed-loop retail collection systems:German supermarket chains pilot return-and-compost logistics networks that secure feedstock for converter circularity claims.
Industry Challenges
- REACH additive registration timelines:ECHA chemical safety assessments for novel plasticizers and slip agents extend formulation approval cycles by 18-24 months.
- Extrusion equipment reconfiguration:Legacy blown-film lines require screw design, die gap, and cooling tower modifications to process hygroscopic biopolymers without degradation.
- Cross-certification documentation burdens:Dual OK Compost and BPI labeling requirements force parallel testing protocols that duplicate laboratory spend for global brand owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant Based Packaging Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bioplastic, Molded Fiber, Paperboard, Biodegradable Film Material: Corn Starch, Sugarcane, Wheat Straw, Bamboo Application: Food Packaging, Cosmetic Packaging, Consumer Goods, Industrial Packaging End User: Food & Beverage, Cosmetics, Electronics, Retail |
| Companies Covered | Corbion N.V., Novamont S.p.A., NatureWorks LLC, Biome Bioplastics Limited, Toray Industries, Inc., Braskem, Danimer Scientific, Arkema Group, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant Based Packaging Market Evolving Landscape
Active R&D pipelines are compressing the performance gap between bio-based and petroleum-derived barrier materials, while regulatory pressure on carbon intensity disclosures accelerates capital deployment toward fermentation-based resin platforms.
Barrier coating technology is migrating from petroleum-derived ethylene vinyl alcohol and polyvinylidene chloride toward bio-based nanocellulose and lignin-derived alternatives. Fresh produce and prepared meal packagers in Nordic markets are piloting these substrates for modified atmosphere applications. The shift is compressing reliance on multilayer conventional films that complicate mechanical recycling streams.
REACH chemical registration requirements in Europe are constraining additive portfolios for biodegradable films, forcing formulation houses to retire legacy plasticizers and accelerate bio-based substitute development. The regulation elevates R&D spend for converters serving multinational brand owners with EU distribution. Food-contact notification pathways through EFSA now dominate product development timelines for barrier layer innovations.
Certification-driven procurement preferences are consolidating buyer power around converters holding dual OK Compost and BPI credentials. Quick-service restaurant chains and prepared meal retailers in Germany and California now mandate compostability labeling as a condition of vendor qualification. This behavior compresses contract awards to a narrowing tier of qualified suppliers with established certification documentation.
Plant Based Packaging Market Segmentation
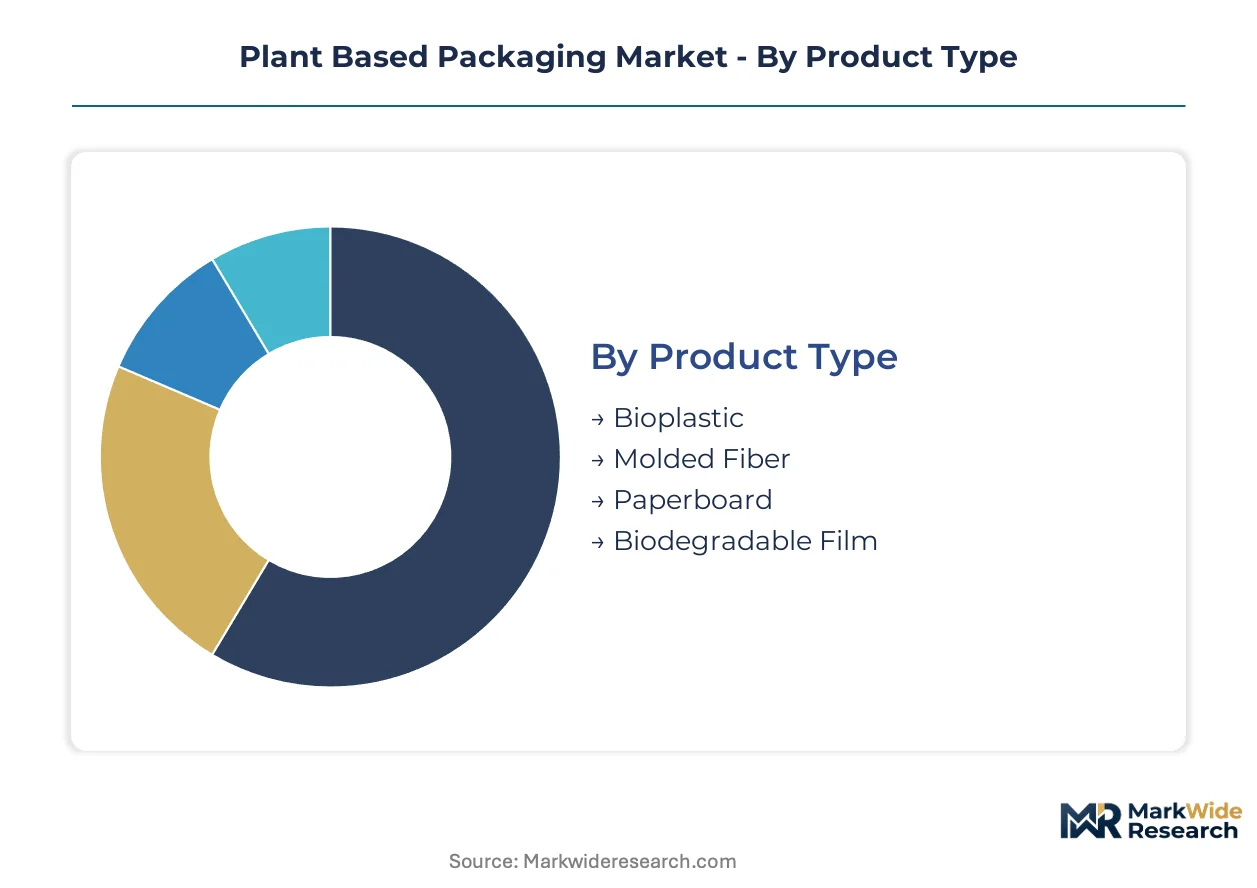
Plant based packaging segmentation reveals how material properties, end-use performance requirements, and regulatory compliance intersect to determine commercial viability across converter portfolios and brand procurement specifications.
Product Type:
The use-case spectrum spans high-barrier food protection, rigid structural support, flexible wrapping, and molded cushioning for diverse perishable and durable goods applications.
- Bioplastic:Polylactic acid and polyhydroxyalkanoate formulations deliver oxygen and moisture barriers comparable to conventional polymers in cold-chain dairy and fresh produce applications. German retailers and quick-service chains specify bioplastic trays for prepared meals under EU Green Deal procurement mandates.
- Molded Fiber:Thermoformed pulp structures from agricultural residues replace expanded polystyrene in hot-food service, with Nordic quick-service restaurants eliminating fossil-based alternatives through operational sustainability targets.
- Paperboard:Dry-goods secondary packaging from wood pulp, wheat straw, or bamboo fiber occupies mature volume positions in e-commerce shipping and retail display applications.
- Biodegradable Film:Blown-film extrusions from starch blends and aliphatic polyesters serve fresh produce overwrap and compostable pouch applications where end-of-life certification drives buyer qualification.
The dominant share belongs to Bioplastic, while Molded Fiber is closing the gap fastest.
Material:
Feedstock selection determines fermentation infrastructure requirements, agricultural land-use intensity, and geographic supply security for integrated resin producers.
- Corn Starch:Dextrose fermentation feeds integrated polylactic acid supply chains across the US Midwest, with NatureWorks LLC sustaining cost discipline through captive agricultural processing capacity.
- Sugarcane:Brazilian Center-West ethanol-to-ethylene routes enable Braskem's bio-based polyethylene production for flexible film markets across South America.
- Wheat Straw:Agricultural residue pulping reduces land-use intensity versus wood fiber for molded fiber tray production serving European quick-service restaurant chains.
- Bamboo:Rapid-growth grass fiber delivers pulp yield advantages for paperboard applications in Chinese and Southeast Asian packaging converter networks.
Corn Starch commands the largest installed fermentation base, though Sugarcane is gaining share fastest in flexible film geographies.
Application:
Barrier requirements, shelf-life specifications, and regulatory food-contact approvals segment demand across perishable, cosmetic, durable, and industrial goods categories.
- Food Packaging:Modified atmosphere trays, films, and pouches for fresh produce, dairy, and prepared meals dominate procurement volumes, with EU Packaging and Packaging Waste Regulation recycled content targets accelerating bioplastic adoption.
- Cosmetic Packaging:Rigid jars, tubes, and secondary cartons for premium personal care brands emphasize renewable content claims and compostable end-of-life pathways.
- Consumer Goods:Durable product cushioning and display packaging for electronics and home goods utilize molded fiber and paperboard structures.
- Industrial Packaging:Pallet wrap, dunnage, and protective films for business-to-business shipment protection represent emerging biodegradable film penetration.
Food Packaging holds the dominant position, while Cosmetic Packaging is expanding most quickly on premium brand sustainability positioning.
End User:
Procurement scale, certification requirements, and supply chain integration depth differentiate demand patterns across sector-specific buyer organizations.
- Food & Beverage:Quick-service restaurant chains and prepared meal retailers mandate compostable packaging as vendor qualification criteria, with German supermarket pilots establishing closed-loop collection logistics.
- Cosmetics:Premium brand owners prioritize bio-based content percentages and dual OK Compost certification for European and North American distribution.
- Electronics:Original equipment manufacturers specify molded fiber cushioning for device protection in e-commerce fulfillment, displacing expanded polystyrene.
- Retail:Private-label and branded goods distributors drive paperboard and flexible film volumes through sustainability-linked supplier scorecards.
Food & Beverage captures the dominant procurement volume, while Cosmetics is climbing the fastest on premium pricing tolerance for certified bio-based materials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and extended producer responsibility frameworks are accelerating capital deployment into bio-based extrusion capacity across Germany, France, and Italy. National composting infrastructure investments and single-use plastic bans are creating differentiated compliance environments that reshape converter location decisions.
Germany
Food retailers and quick-service chains mandate compostable packaging for prepared meals under the Packaging Act amendments. The Federal Environment Agency enforces strict biodegradability certification for food-contact applications. Bavaria's converter cluster around Munich collaborates with supermarket chains on closed-loop collection logistics for bioplastic trays.
United States
Midwest agricultural processors supply corn dextrose fermentation feedstock for integrated polylactic acid production. FDA food-contact substance notifications govern barrier film approvals for dairy and fresh produce applications. NatureWorks LLC anchors production capacity in Blair, Nebraska, with captive agricultural sourcing from surrounding corn belt counties.
Brazil
Sugarcane ethanol-to-ethylene routes enable bio-based polyethylene production for flexible film markets across South America. The National Agency of Petroleum, Natural Gas and Biofuels regulates biofuel content claims in packaging applications. Braskem operates from Triunfo in Rio Grande do Sul, leveraging Center-West sugarcane supply contracts for resin production.
China
GB standards for biodegradable plastics mandate compostability testing protocols for food-contact applications. The Ministry of Ecology and Environment enforces plastic restriction policies in major urban centers. Yangtze River Delta packaging converters scale thermoplastic starch production for e-commerce shipping applications under dual carbon policy targets.
India
FSSAI regulatory pathway development for polylactic acid in dairy packaging opens subcontinent penetration for compliant converters. The Bureau of Indian Standards issues certification requirements for biodegradable carry bags and compostable cutlery. Maharashtra's converter networks around Mumbai and Pune pilot food-grade bioplastic tray production for quick-service restaurant chains.
Plant Based Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across resin production, converter equipment, and brand procurement tiers. The market exhibits moderate concentration at the resin level with integrated fermentation-to-pellet producers holding feedstock security advantages, while downstream converter tiers fragment across regional certification requirements. Three archetypes dominate: agricultural-integrated resin producers, specialty biopolymer formulators, and equipment-integrated converters. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure compostability certifications across multiple geographies.
Among agricultural-integrated resin producers, NatureWorks LLC exemplifies captive corn dextrose supply chain control from Midwest processing capacity. Novamont S.p.A. anchors European biopolymer production through its integrated fermentation platform serving flexible film markets. Braskem occupies a position as the dominant South American producer leveraging Brazilian sugarcane ethanol feedstock security for bio-based polyethylene output.
| Leading Market Players |
|---|
| Corbion N.V. |
| Novamont S.p.A. |
| NatureWorks LLC |
| Biome Bioplastics Limited |
| Toray Industries, Inc. |
| Braskem |
| Danimer Scientific |
| Arkema Group |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Undercapacity in European fermentation assets drives aggressive capacity reservation contracts from flexible film converters seeking supply security amid Novamont's Mater-Bi platform dominance. This utilization squeeze simultaneously elevates spot resin premiums and compels brand owners to accept longer-term offtake commitments that reshape working capital requirements across the value chain.
Pricing Analysis
Certification level creates the primary spread between TÜV Austria's OK Compost INDUSTRIAL grade and home-compostable variants, with dual-certified bioplastic films commanding contract premiums over single-label alternatives. Three-tier pricing structure separates premium certified grades from standard industrial-compostable and economy-tier non-certified bio-based materials. Cost compression in the standard tier is intensifying because Brazilian sugarcane ethanol feedstock volatility transmits directly to bio-polyethylene resin costs. Quick-service restaurant chains exhibit highest price sensitivity due to operational sustainability mandates that force volume procurement without pass-through flexibility, while premium cosmetics brands show least sensitivity given renewable content claims that support brand positioning.
Supply Chain Analysis
REACH chemical registration requirements function as de facto export controls on novel plasticizers and slip agents, limiting formulation flows from non-EU additive houses into European converter networks. Geographic supply concentration centers on the United States for corn dextrose fermentation, Brazil for sugarcane ethanol routes, and Italy for Novamont's integrated Mater-Bi capacity. Raw material dependencies rest on Midwest corn belt harvests, Center-West sugarcane crushing seasons, and agricultural residue pulp from Nordic wheat straw collection. Single-source vulnerability pervades European flexible film markets given limited alternative fermentation capacity to Novamont's platform. Distribution runs through converter-direct contracts with major brand owners, bypassing traditional polymer distributor tiers due to certification documentation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of integrated fermentation-to-pellet capacity with captive feedstock security defines competitive advantage in this market, as agricultural processing infrastructure cannot be replicated without multi-year capital deployment and offtake contracting.
For Market Incumbents: Insulate margin structure through backward integration into corn dextrose or sugarcane ethanol processing to neutralize agricultural commodity swings, while accelerating dual OK Compost and BPI certification coverage to preempt emerging regional converters from qualifying for multinational brand procurement. The threat of REACH additive registration delays for novel plasticizers demands accelerated R&D partnerships with ECHA-pre-notified formulation houses. For New Entrants and Emerging Players: Pursue Indian dairy packaging applications where FSSAI regulatory pathway development for polylactic acid creates first-mover positioning before incumbent certification documentation burdens arrive. The most penetrable segment lies in thermoplastic starch films for e-commerce shipping under China's dual carbon policy targets, where GB standards compliance is achievable without European REACH complexity. A go-to-market angle through Yangtze River Delta converter partnerships enables rapid scaling without proprietary fermentation asset investment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among agricultural-integrated resin producers with captive feedstock offtake contracts spanning multiple harvest cycles, as these structures generate predictable volume commitments that downstream converters cannot replicate. Long-term viability across the analysis window favors targets with established dual-certification documentation and regional composting infrastructure partnerships. The acquisition archetype centers on mid-scale converters with installed extrusion capacity and pending certification approvals that strategic buyers can accelerate. The signal to watch is German supermarket chain expansion of closed-loop collection logistics, which would validate circularity claims and trigger rapid contract consolidation toward qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Processing | Corn dextrose fermentation capacity in the US Midwest secures feedstock cost discipline against commodity volatility. |
| Dual Certification Investment | Parallel OK Compost and BPI documentation opens procurement qualification for EU and North American brand owners simultaneously. |
| Barrier Coating Convergence | Bio-based nanocellulose integration with thermoplastic starch achieves oxygen barrier parity with multilayer conventional films. |
| Closed-Loop Collection Partnership | German supermarket return-and-compost logistics networks secure converter feedstock for circularity claims verification. |
| Regulatory Pathway Navigation | FSSAI food-contact approvals for polylactic acid in Indian dairy packaging enable subcontinent market penetration ahead of competitors. |
Research Methodology
The analysis maps bioplastic resin production, molded fiber thermoforming, and barrier film extrusion segments, each validated through fermentation plant managers, packaging converter procurement leads, quick-service restaurant sustainability officers, and retail category buyers. Primary interviews with these stakeholders combined trade data from USITC and Eurostat customs records, ECHA REACH registration databases, and FSSAI regulatory filings for bottom-up and top-down triangulation.
Forecasts assume fixed EU Packaging and Packaging Waste Regulation recycled content targets and stable agricultural yield patterns across the projection horizon, with segmentation modeled across material type, product format, application barrier requirements, and end-user procurement scale. CAGRs derive from installed capacity utilization rates and certification-constrained supply elasticity, incorporating corn and sugarcane commodity futures curves as feedstock cost inputs alongside converter equipment reconfiguration timelines for hygroscopic biopolymer processing.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, EU composting infrastructure deployment rates, or REACH additive approval timelines would shift the trajectory. Material shifts in certification scheme harmonization between TÜV Austria and BPI protocols would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sustainable Packaging
Asia-Pacific Sustainable Packaging Market
Sustainable Packaging
Global Disappearing Packaging Market
Sustainable Packaging
Compostable Food Trays Market
Sustainable Packaging
Sustainable Packaging Market
Sustainable Packaging
Bagasse Bowls Market
Sustainable Packaging
Wheat Straw Cutlery Market
Sustainable Packaging
Japan Green Packaging Market
Sustainable Packaging
Sustainable Plastic Packaging Market
Sustainable Packaging
Bagasse Tableware Products Market
Sustainable Packaging
Eco Friendly Bottles Market
Sustainable Packaging
Zero Waste Packaging Market
Sustainable Packaging
Middle East and Africa Eco-Friendly Packaging Market
Sustainable Packaging
Europe Green Packaging Market
Sustainable Packaging
United States Green Packaging Market
Sustainable Packaging
Global Paper Straw Market
Sustainable Packaging
Europe Eco-Friendly Packaging Market