
 Von Hippel-Lindau Market | 2026-2036
Von Hippel-Lindau Market Size, Share, and Industry Trends Forecast 2026-2036
Von Hippel-Lindau Market Analysis
North American biologics manufacturing capacity is rewriting competitive dynamics in rare disease therapeutics. Roche leverages its diagnostic-to-therapy integration across VHL-linked renal cell carcinoma pathways. Novartis anchors its position through sustained investment in radioligand therapy infrastructure. Merck competes via checkpoint inhibitor combinations targeting HIF-2α pathways in solid tumors.
Von Hippel-Lindau disease is an autosomal dominant neoplastic disorder driven by VHL tumor suppressor gene mutations on chromosome 3p25-26, producing constitutive hypoxia-inducible factor activation and highly vascularized tumors across cerebellum, retina, kidney, and adrenal glands. Small molecules targeting HIF-2α dimerization currently dominate therapeutic development pipelines, while monoclonal antibodies against VEGF pathways retain mature market presence in retinal hemangioblastoma management. Gene therapy approaches utilizing CRISPR-mediated VHL correction represent the fastest-growing segment, though clinical translation remains concentrated in research institutions with specialized germline editing capabilities.
FDA orphan drug designation and EMA PRIME eligibility frameworks compress development timelines for VHL-targeted therapies, while HIPAA-compliant genomic data sharing protocols shape patient registry participation rates across US academic medical centers. The EU AI Act introduces compliance thresholds for bioinformatics-driven variant classification tools used in genetic screening workflows. Stakeholders must monitor regulatory divergence between FDA accelerated approval pathways and EMA conditional marketing authorization requirements for HIF-2α inhibitors.
Market Dynamics
HIF-2α inhibitor development is compressing clinical timelines while gene therapy manufacturing constraints create supply bottlenecks for CRISPR-mediated VHL correction programs.
Growth Catalysts
- FDA Orphan Drug Exclusivity:Seven-year market protection accelerates sponsor investment in VHL-targeted small molecules. Pediatric rare disease vouchers further incentivize pediatric trial enrollment.
- Radioligand Therapy Infrastructure:Novartis anchors production networks for lutetium-based theragnostics. Academic medical centers in Germany and Japan are expanding cyclotron capacity for isotope generation.
- Retinal Hemangioblastoma Burden:Anti-VEGF intravitreal injections sustain mature demand across ophthalmology networks. Specialist treatment centers in the United States cluster around major vision research institutes.
Market Restraints
- Germline Editing Manufacturing:GMP-compliant viral vector production concentrates at fewer than twelve global facilities. Single-source AAV suppliers create supply vulnerability for gene therapy candidates.
- Diagnostic Access Inequity:VHL germline testing requires specialized genetic counseling infrastructure. Rural and underserved populations face prolonged time-to-diagnosis.
- Reimbursement Complexity:Orphan drug pricing frameworks vary across national health technology assessment bodies. Payer negotiation timelines extend commercial launch windows.
Strategic Opportunities
- Underpenetrated Latin America:Brazil's ANVISA streamlined rare disease pathways in 2023. Argentina and Mexico lack specialized VHL treatment centers.
- Real-World Evidence Integration:HIPAA-compliant genomic registries enable natural history studies. FDA accepts registry data for post-market safety surveillance.
- CRISPR-Base Editing Convergence:Cytosine base editors reduce off-target risk versus nuclease approaches. Prime editing infrastructure investments target germline correction fidelity.
Industry Challenges
- Specialized Genetic Counseling Workforce:VHL syndrome requires pre- and post-test counseling for at-risk family members. Training programs fail to match patient identification rates.
- Multi-System Surveillance Coordination:CNS, renal, adrenal, and retinal monitoring demands cross-specialty integration. Electronic health record fragmentation impedes longitudinal tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Von Hippel-Lindau Market |
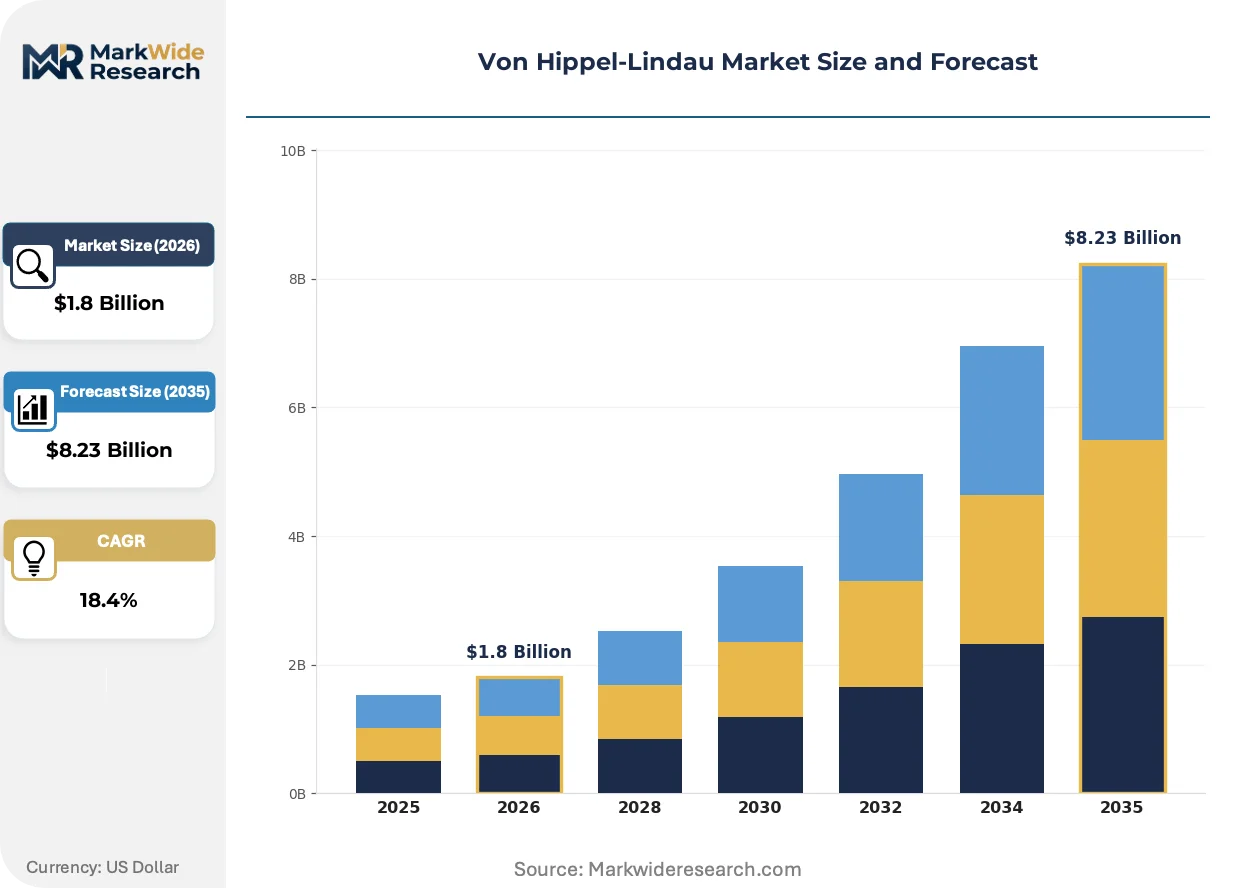
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gene Therapy, Small Molecules, Monoclonal Antibodies, Diagnostics Application: Oncology, Genetic Screening, Clinical Trials, Patient Management End User: Hospitals, Research Institutions, Pharmaceutical Companies, Diagnostic Labs Technology: CRISPR, Next-Generation Sequencing, Proteomics, Bioinformatics |
| Companies Covered | Merck, Novartis, Roche, Exelixis, Bayer, Bedford Laboratories, DNAtrix, Astellas Pharma US, Cellectar Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Von Hippel-Lindau Market Emerging Trajectories
Next-generation sequencing is collapsing diagnostic odysseys while radioligand theragnostics and base editing platforms restructure therapeutic development economics.
Allosteric HIF-2α inhibitors are rendering obsolete traditional VEGF pathway blockade in clear cell renal cell carcinoma. Oncology networks at Massachusetts General Hospital and MD Anderson are prioritizing HIF-2α dimerization disruptors for VHL-linked tumors. The shift is compressing anti-angiogenic antibody revenue trajectories across renal indications.
The EU AI Act imposes conformity assessment requirements for bioinformatics tools classifying VHL variants of uncertain significance. Genetic testing laboratories must document algorithmic training data and performance metrics. German and French reference centers are consolidating variant interpretation workflows to meet documentation burdens.
Academic medical centers are unbundling traditional pharmaceutical distribution for radioligand therapies. Isotope half-life constraints demand on-site compounding or regional hub-and-spoke models. The University of California San Francisco and Heidelberg University Hospital operate dedicated radiopharmacy facilities for patient-specific dosing.
Von Hippel-Lindau Market Segmentation
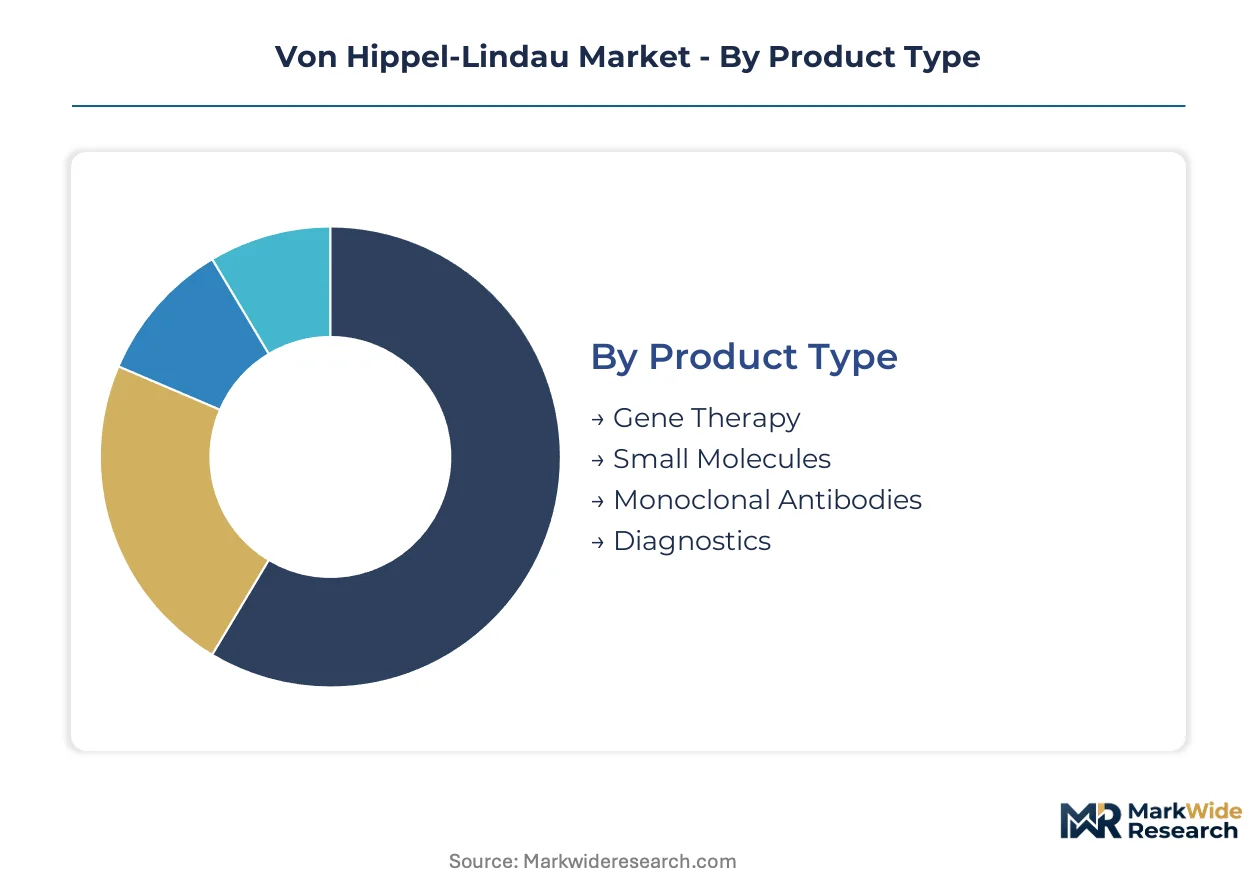
VHL therapeutics fragment across four distinct value chains, each governed by divergent regulatory pathways and manufacturing economics. Gene therapy and small molecules operate on fundamentally different margin structures, while diagnostics and patient management systems compete for the same institutional procurement budgets.
Product Type:
Cost tier stratification separates developmental-stage biologics from established small molecule franchises, with reimbursement complexity escalating at the premium end.
- Gene Therapy:CRISPR-mediated VHL correction programs utilize AAV delivery vectors requiring GMP-compliant manufacturing at fewer than twelve global facilities. Demand concentrates at academic medical centers in the United States, Germany, and Japan where specialized germline editing capabilities cluster, though single-source viral vector suppliers create supply vulnerability.
- Small Molecules:Allosteric HIF-2α inhibitors disrupt hypoxia-inducible factor dimerization with oral bioavailability advantages over biologic alternatives. Roche and Merck anchor development pipelines targeting VHL-linked renal cell carcinoma, with FDA orphan drug exclusivity compressing commercialization timelines.
- Monoclonal Antibodies:Anti-VEGF pathways retain mature market presence in retinal hemangioblastoma management through intravitreal injection protocols.
- Diagnostics:Germline testing platforms require specialized genetic counseling infrastructure, creating access inequities for rural populations.
Small molecules command the established base. The steepest expansion runs through gene therapy.
Application:
Clinical utility divides between curative intent interventions and longitudinal disease surveillance systems with divergent pricing power.
- Oncology:HIF-2α inhibitor development targets clear cell renal cell carcinoma, pancreatic neuroendocrine tumors, and cerebellar hemangioblastoma with disease-modifying intent. Massachusetts General Hospital and MD Anderson prioritize dimerization disruptors, displacing traditional anti-angiogenic revenue trajectories across renal indications.
- Genetic Screening:Next-generation sequencing collapses diagnostic odysseys from years to weeks for VHL germline mutation identification. EU AI Act conformity assessments now govern bioinformatics tools classifying variants of uncertain significance, with German and French reference centers consolidating interpretation workflows.
- Clinical Trials:FDA accelerated approval and EMA conditional marketing authorization frameworks reshape enrollment dynamics for rare disease therapeutics.
- Patient Management:Multi-system surveillance coordination demands cross-specialty integration across CNS, renal, adrenal, and retinal monitoring protocols.
Oncology commands the established base. Genetic screening gains share fastest as diagnostic economics improve.
End User:
Procurement authority concentrates at institutions with integrated research-to-care capabilities, favoring vertically organized health systems.
- Hospitals:Specialized treatment centers cluster around major vision research institutes in the United States and academic medical centers in Germany and Japan. University of California San Francisco and Heidelberg University Hospital operate dedicated radiopharmacy facilities for patient-specific lutetium-based dosing.
- Research Institutions:CRISPR-base editing convergence programs concentrate at facilities with germline editing capabilities, with cytosine base editors reducing off-target risk versus nuclease approaches.
- Pharmaceutical Companies:Novartis anchors radioligand therapy infrastructure investments, while Roche leverages diagnostic-to-therapy integration across VHL-linked pathways.
- Diagnostic Labs:HIPAA-compliant genomic data sharing protocols shape patient registry participation rates across US academic medical centers.
Hospitals command the established base. Research institutions climb the fastest as gene therapy manufacturing matures.
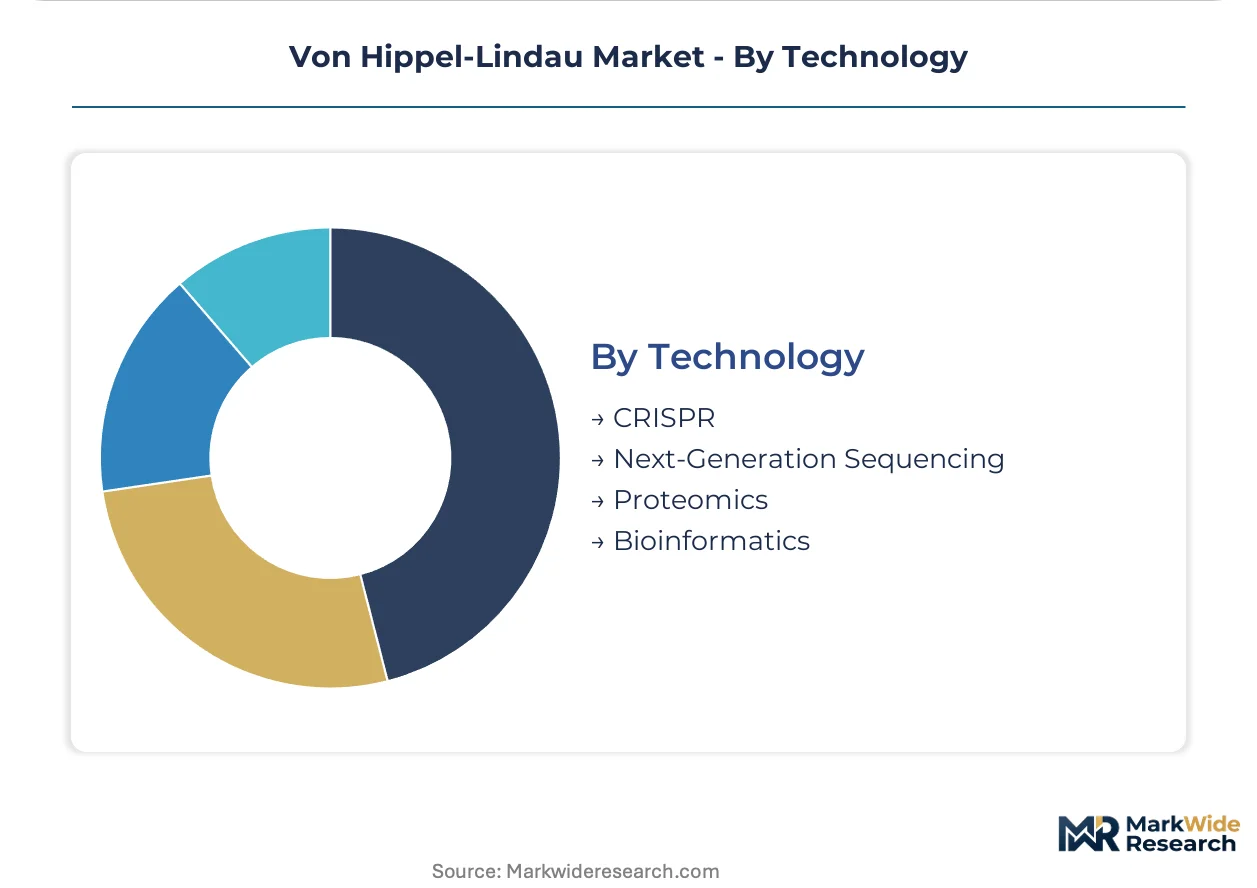
Technology:
Platform maturity determines regulatory pathway efficiency, with established sequencing technologies enjoying streamlined approval compared to editing modalities.
- CRISPR:Prime editing infrastructure investments target germline correction fidelity with reduced double-strand break liability. Manufacturing constraints at viral vector facilities limit clinical translation velocity despite therapeutic promise.
- Next-Generation Sequencing:Collapsed cost curves enable population-scale VHL carrier screening with variant classification algorithms now subject to EU AI Act documentation burdens for training data and performance metrics.
- Proteomics:HIF-2α dimerization assays support patient stratification for small molecule responder identification.
- Bioinformatics:HIPAA-compliant registry architectures enable natural history studies with FDA-accepted post-market safety surveillance applications.
Next-generation sequencing commands the established base. CRISPR shows the steepest expansion trajectory as base editing fidelity improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of HIF-2α inhibitors and radioligand therapies concentrates at specialized facilities in the United States, Germany, and Japan. FDA orphan drug incentives and EMA accelerated pathways compress development timelines in these markets. Academic medical centers in each country anchor clinical trial networks and germline editing research.
United States
Massachusetts General Hospital and MD Anderson Cancer Center prioritize HIF-2α dimerization disruptors for VHL-linked renal cell carcinoma. FDA orphan drug exclusivity provides seven-year market protection for small molecule sponsors. The University of California San Francisco operates dedicated radiopharmacy facilities for patient-specific lutetium-based dosing.
Germany
Heidelberg University Hospital maintains cyclotron capacity for isotope generation supporting radioligand therapy networks. The EU AI Act imposes conformity assessment requirements for bioinformatics tools classifying VHL variants of uncertain significance. German reference centers consolidate variant interpretation workflows to meet documentation burdens.
Japan
Specialized treatment centers cluster around academic medical centers with germline editing capabilities for CRISPR-mediated VHL correction programs. METI oversees radiopharmaceutical production standards for theragnostic applications. Osaka and Tokyo medical school hospitals anchor multi-system surveillance coordination across CNS, renal, adrenal, and retinal monitoring protocols.
Switzerland
Roche leverages diagnostic-to-therapy integration from its Basel headquarters across VHL-linked renal cell carcinoma pathways. Swissmedic regulates accelerated access pathways for rare disease therapeutics. The Lake Geneva biotech corridor hosts concentrated expertise in HIF pathway modulation and hypoxia-inducible factor research.
Brazil
ANVISA streamlined rare disease regulatory pathways in 2023, reducing approval timelines for orphan therapeutics. São Paulo and Rio de Janeiro lack specialized VHL treatment centers relative to patient identification rates. Diagnostic access inequities persist for rural populations requiring germline testing and genetic counseling infrastructure.
Von Hippel-Lindau Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain. Large pharmaceutical conglomerates anchor HIF-2α inhibitor development through integrated diagnostic-to-therapy pipelines. Mid-cap oncology specialists occupy the radioligand and targeted therapy segments. Competitive moves concentrate on diagnostic partnerships and radiopharmacy infrastructure expansion rather than manufacturing scale.
Among Swiss-based platform integrators, Roche exemplifies the diagnostic-therapy convergence archetype. Novartis occupies a position within the radioligand infrastructure tier, anchoring production networks for lutetium-based theragnostics. Merck represents the checkpoint combination strategy, targeting HIF-2α pathways in solid tumors through immuno-oncology integration.
| Leading Market Players |
|---|
| Merck |
| Novartis |
| Roche |
| Exelixis |
| Bayer |
| Bedford Laboratories |
| DNAtrix |
| Astellas Pharma US |
| Cellectar Biosciences |
| Others |
Supply Flow & Price Mechanics
Undercapacity at GMP-compliant viral vector facilities concentrates pricing power among fewer than twelve global suppliers, forcing gene therapy sponsors to absorb premium manufacturing costs while small molecule producers exploit FDA orphan drug exclusivity to sustain elevated price points.
Pricing Analysis
FDA orphan drug exclusivity dictates the pricing tier structure across VHL therapeutics, separating premium HIF-2α inhibitor regimens from standard-of-care anti-VEGF injections and economy-tier surveillance-only protocols. Price differentiation hinges on certification level—EMA conditional marketing authorization versus full approval—and geographic delivery cost for radioligand therapies with isotope half-life constraints. Cost compression in gene therapy manufacturing is intensifying because single-source AAV suppliers face no near-term competition. Hospital procurement committees demonstrate highest price sensitivity for chronic surveillance modalities, while research institutions show lowest sensitivity for curative-intent editing programs.
Supply Chain Analysis
Export controls on CRISPR germline editing technologies limit cross-border flows of base editing reagents and prime editing vectors, constraining capacity expansion beyond existing academic medical center networks. Manufacturing concentrates in the United States, Germany, and Japan where specialized cyclotron facilities and GMP viral vector suites cluster. Raw material dependencies include lutetium-177 isotopes, AAV serotype production cell lines, and synthetic guide RNA chemistries. Single-source vulnerability pervades AAV supplier relationships. Distribution runs through hospital-integrated radiopharmacy hubs and centralized gene therapy compounding centers rather than traditional pharmaceutical wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward vertically integrated health systems as hospital networks consolidate procurement authority for rare disease therapeutics, fragmenting purchasing decisions across fewer institutional decision-makers with specialized pharmacy capabilities.
For Market Incumbents: Pre-empt radioligand therapy infrastructure expansion by securing exclusive cyclotron partnerships at academic medical centers in Germany and Japan before Novartis anchors additional production networks. Lock in backward integration into AAV manufacturing through captive supply agreements with the limited GMP-compliant viral vector facilities, neutralizing single-source vulnerability that threatens gene therapy pipeline timelines.
For New Entrants and Emerging Players: Brazil's diagnostic access gap offers the most penetrable entry point, where ANVISA's streamlined rare disease pathways lack specialized VHL treatment centers to match patient identification rates. Target São Paulo and Rio de Janeiro with mobile genetic counseling units and telemedicine-enabled surveillance coordination. Pursue hospital system partnerships rather than direct-to-patient models to leverage existing oncology network infrastructure.
For Investors and Strategic Acquirers: Capital is best deployed toward platform-integrated mid-cap specialists with diagnostic-to-therapy convergence capabilities and established radiopharmacy footprints. Long-term viability over the next decade rests on CRISPR manufacturing de-bottlenecking and HIF-2α inhibitor regulatory pathway maturation. Watch for FDA acceptance of real-world evidence from HIPAA-compliant genomic registries as the inflection signal accelerating post-market surveillance economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Radiopharmacy Infrastructure Expansion | Heidelberg University Hospital and UCSF anchor patient-specific lutetium dosing capabilities that compress treatment timelines. |
| Diagnostic-Therapy Integration | Roche leverages Basel-based HIF pathway expertise across renal cell carcinoma testing and treatment protocols. |
| CRISPR Manufacturing Scale-Up | GMP viral vector capacity constraints at fewer than twelve global facilities limit gene therapy commercialization velocity. |
| Real-World Evidence Registry Development | HIPAA-compliant genomic data sharing enables FDA-accepted natural history studies for post-market surveillance. |
| Latin America Market Development | ANVISA's 2023 regulatory streamlining creates first-mover advantage for orphan therapeutic sponsors in Brazil. |
Methodological Framework
Desk research of FDA orphan drug filings, EMA accelerated pathway submissions, ClinicalTrials.gov enrollment data, and hospital procurement databases preceded structured interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists. Primary fieldwork with academic medical center pharmacy directors and genetic counseling program heads validated secondary findings on diagnostic access patterns. Bottom-up patient flow modeling and top-down revenue triangulation across the four segmentation dimensions ensured cross-verification.
The analytical framework held regulatory approval timelines and reimbursement negotiation patterns as fixed conditions while varying gene therapy manufacturing capacity assumptions and radioligand therapy infrastructure expansion rates across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and technology platform, with patient population severity and regional regulatory cluster as additional stratifiers. CAGRs were derived from epidemiological prevalence projections, treatment penetration curves, and pricing elasticity estimates for orphan therapeutics.
The forecast holds incumbent behavior within observed patterns; aggressive moves by platform-integrated conglomerates or CRISPR manufacturing specialists would shift outcomes beyond modeled ranges. Material shifts in FDA real-world evidence acceptance standards, EMA AI Act enforcement on bioinformatics tools, or germline editing regulatory frameworks would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Chronic Granulomatous Disease Market
Rare Diseases
Prader-Willi Syndrome (PWS) Market
Rare Diseases
Hutchinson-Gilford Progeria Syndrome Market
Rare Diseases
Niemann Pick Disease Market
Rare Diseases
Byler Disease Market
Rare Diseases
Malignant Infantile Osteopetrosis Market
Rare Diseases
Hemophagocytic Lymphohistiocytosis Market
Rare Diseases
Leigh Syndrome Treatment Market
Rare Diseases
Muckle-Wells Syndrome Market
Rare Diseases
Cowden Syndrome Market
Rare Diseases
Rett Syndrome Market
Rare Diseases
Global Hereditary Angioedema Treatment Market
Rare Diseases
Lennox-Gastaut Syndrome Market
Rare Diseases
Global Rare Hemophilia Factors Market
Rare Diseases
Creutzfeldt-Jakob Disease (CJD) Market
Rare Diseases
Spina Bifida Market