
 Global Cordyceps Militaris Market | 2026-2036
Global Cordyceps Militaris Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cordyceps Militaris Market Foresight
Asset-light contract cultivation models are rewriting competitive entry barriers in Cordyceps militaris supply. Dalong Biotechnology Co., Ltd. leverages captive mycelium laboratories to control substrate quality from inoculation through harvest. Naturalin Bio-Resources Co., Ltd. anchors its position through backward integration into organic grain spawn production. NU SKIN ENTERPRISES, INC competes via direct-to-consumer channel dominance in Asia-Pacific wellness markets.
Cordyceps militaris denotes a parasitic fungus cultivated on sterilized cereal substrates, yielding fruiting bodies standardized for cordycepin and adenosine content used in immunomodulatory and stamina-support formulations. Hot-water extraction followed by spray-drying remains the dominant industrial concentration method for bioactive retention. Capsules currently occupy the largest product-type margin pool due to dosing precision and pharmacy shelf placement, while liquid extracts represent the fastest-growing format as beverage brands seek functional differentiation. Among applications, health supplements lead volume absorption, though functional foods are gaining traction as CPG brands reformulate energy and recovery portfolios.
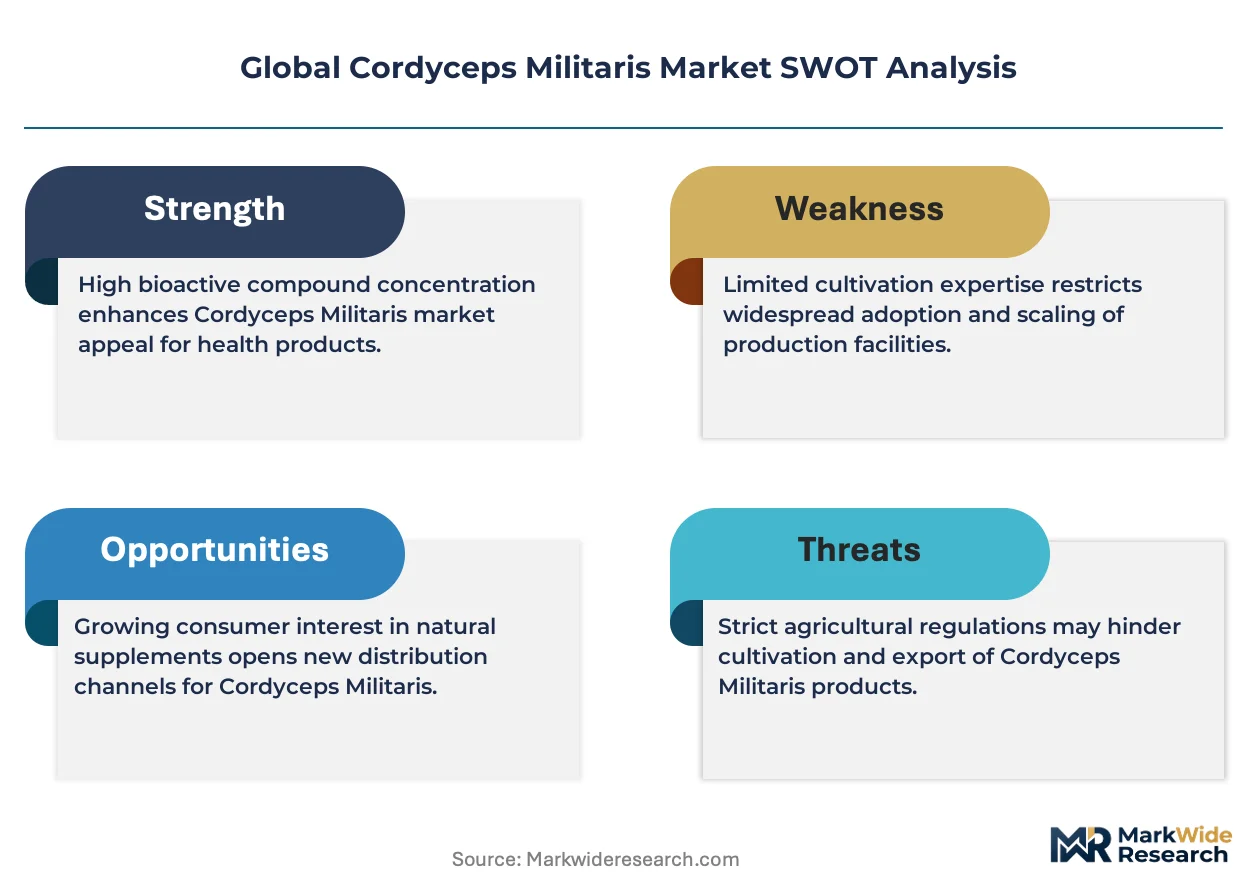
The FDA's New Dietary Ingredient notification requirements constrain novel Cordyceps extract introductions in the United States, while China's NMPA and SAMR jointly enforce fungal product licensing under revised food safety codes. EFSA's ongoing Novel Food assessments for Cordyceps-derived ingredients in Europe are creating pre-market approval bottlenecks that favor established dossier holders. Stakeholders must monitor regulatory divergence between pharmacopeial-grade and food-grade classification pathways to avoid stranded formulation investments.
Market Dynamics
Asset-light contract cultivation models are compressing capital requirements for Cordyceps militaris market entry while simultaneously fragmenting quality control across dispersed substrate suppliers. This structural shift forces incumbents to defend margin pools through captive mycelium laboratories or backward integration into organic grain spawn production.
Growth Catalysts
- China's GB standards tightening:Stricter purity thresholds for fungal-derived supplements are forcing cultivation upgrades that favor scaled, standardized producers over artisanal growers.
- Japan's aging demographic:Elderly consumers seeking traditional medicine alternatives are expanding the addressable base for immunomodulatory formulations.
- Solid-state fermentation advances:Bioreactor-based mycelium production is reducing harvest-cycle variability and enabling year-round supply consistency.
Market Restraints
- Substrate input volatility:Organic brown rice and oat grain prices fluctuate with climate-driven harvest yields in Northeast Asian sourcing regions.
- EFSA Novel Food bottlenecks:Pre-market approval timelines for Cordyceps-derived ingredients in Europe favor established dossier holders and deter new entrants.
- Plant-based adaptogen substitution:Ashwagandha and rhodiola extracts compete for identical shelf space in stamina-support formulations.
Strategic Opportunities
- Underpenetrated Brazil:ANVISA's evolving functional food regulations create first-mover positioning for pharmacy-channel entrants.
- Beverage format expansion:Liquid extract integration into ready-to-drink energy and recovery portfolios opens CPG volume pools beyond capsules.
- Dual carbon policy alignment:China's MEE carbon intensity targets reward low-energy solid-state fermentation over conventional substrate farming.
Industry Challenges
- Cordycepin assay standardization:Inconsistent HPLC methodology across laboratories complicates contract enforcement and premium pricing.
- Cross-border cold chain integrity:Temperature excursions during international shipment degrade adenosine bioactivity and trigger rejection clauses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cordyceps Militaris Market |
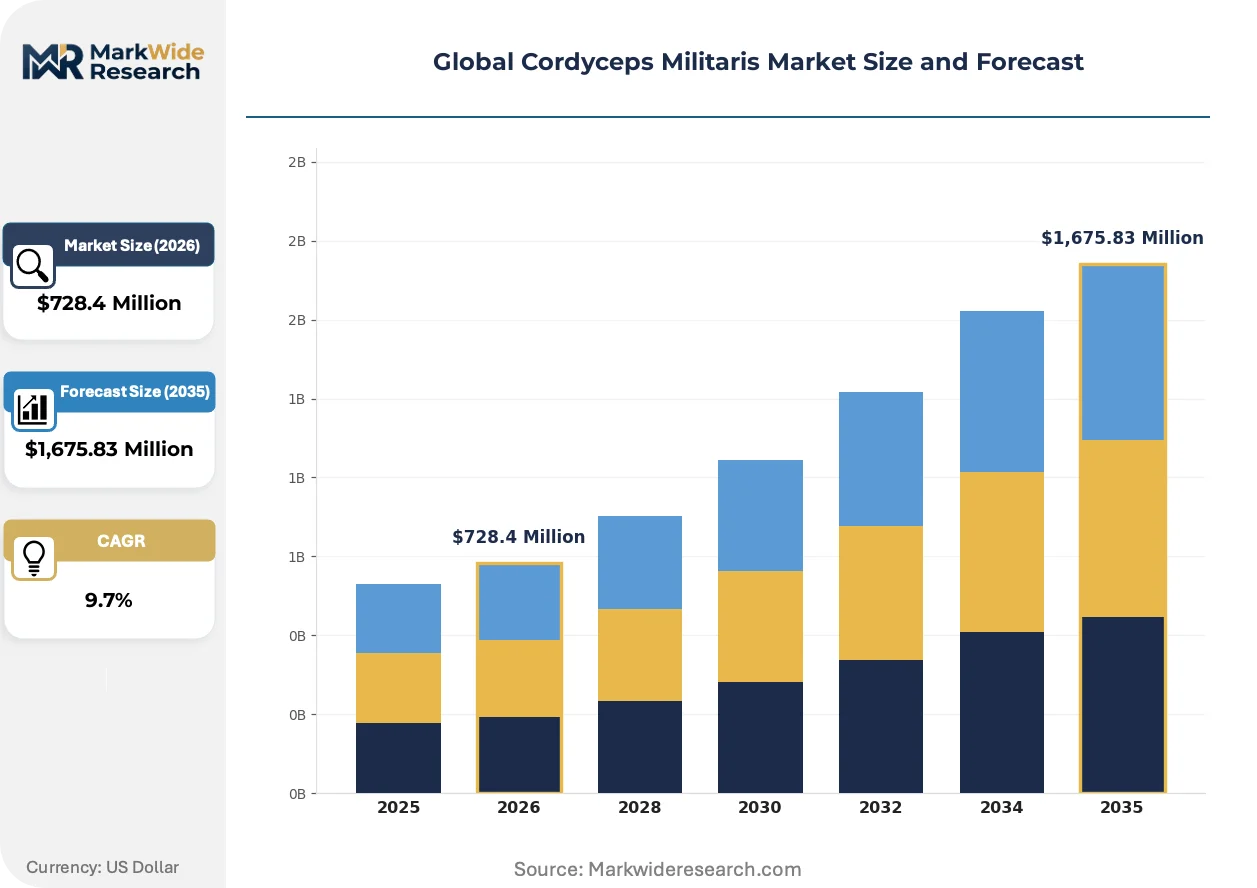
| Market Size in 2026 | $728.4 Million |
| Market Size in 2035 | $1,675.83 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powder, Liquid Extract, Dried Application: Health Supplements, Functional Foods, Pharmaceuticals, Cosmetics Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies End User: Health-Conscious Consumers, Athletes, Elderly, Wellness Enthusiasts |
| Companies Covered | Dalong Biotechnology Co., Ltd., Health Choice Limited, MycoForest, Naturalin Bio-Resources Co., Ltd., NU SKIN ENTERPRISES, INC, Nutra Green Biotechnology Co., Ltd., Xi'an Saina Biological Technology Co., Ltd., Sunrise Nutrachem Group Ltd., Shanghai Kangzhou Fungi Extract Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cordyceps Militaris Market Shifts & Advancements
Bioprocess intensification and regulatory data harmonization are converging to compress product development cycles while elevating bioactive consistency requirements. These forces favor technology-forward cultivators with in-house analytical capabilities.
Spray-drying protocols optimized for cordycepin retention are collapsing the cost gap between artisanal hot-water extracts and industrial-scale concentrates. Functional beverage brands in South Korea and Japan are adopting these standardized inputs at triple-digit annual procurement rates. This technology diffusion is collapsing premium pricing power for small-batch suppliers unable to match batch-to-batch consistency.
EFSA's ongoing Novel Food assessments for fungal-derived ingredients are extending pre-market approval timelines beyond thirty-six months for new dossier submissions. European health supplement distributors are responding by consolidating procurement around grandfathered suppliers with existing authorizations. Capsule-format incumbents with established EFSA compliance records are capturing disproportionate shelf placement in German and French pharmacy channels.
Direct-to-consumer subscription models are displacing traditional pharmacy and health-food-store distribution for Cordyceps militaris supplements in Asia-Pacific urban centers. Wellness platforms in Seoul and Tokyo are bundling personalized dosing protocols with automated replenishment. This channel migration is most visible among thirty-to-forty-five-year-old consumers seeking stamina support for high-intensity work schedules.
Global Cordyceps Militaris Market Segmentation
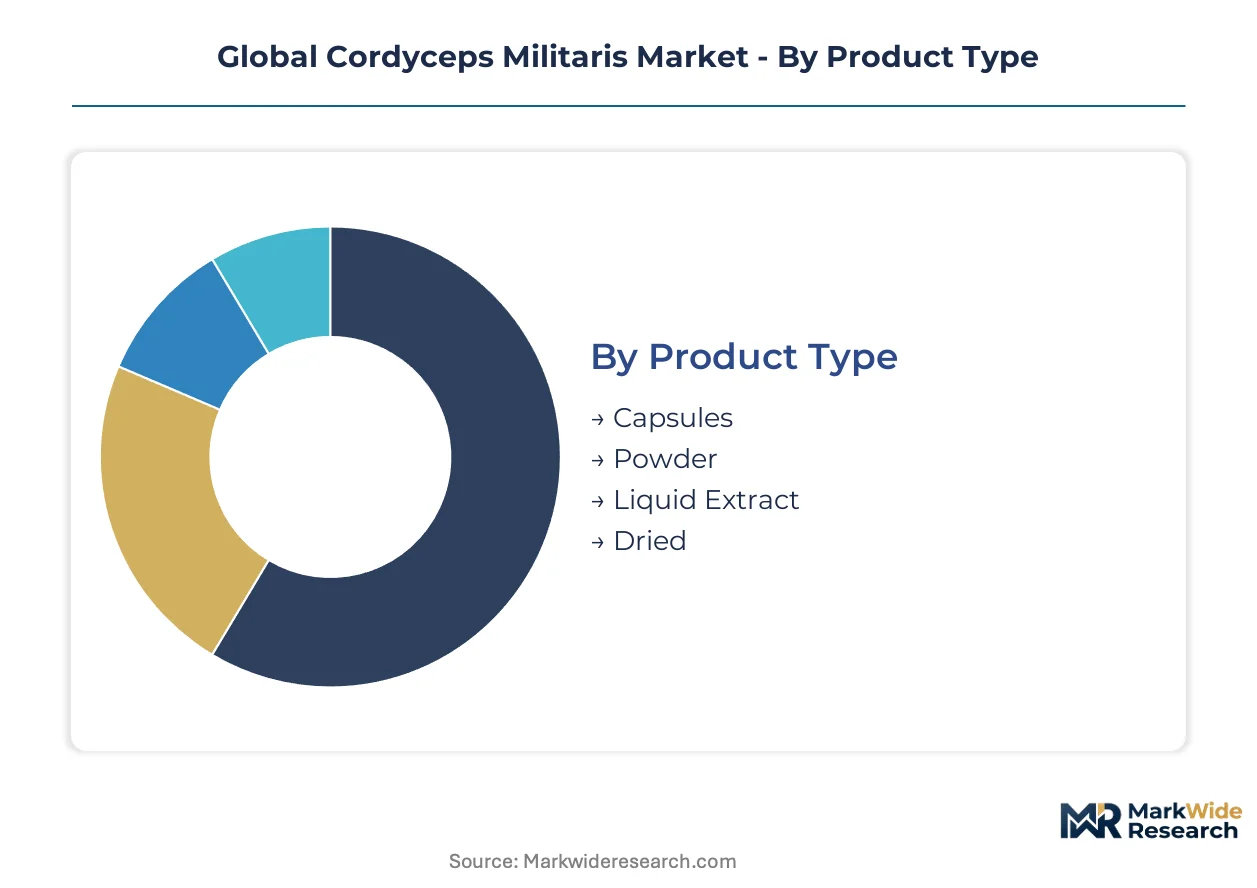
Cordyceps militaris supply chains demand distinct post-sale technical support across each product format, from stability guidance for liquid extracts to dosing calibration for encapsulated concentrates. Segmentation reveals how formulation chemistry and channel economics allocate margin pools unevenly across the value chain.
Product Type:
After-sales service intensity varies sharply by physical form, with liquid extracts requiring cold-chain compliance consulting and powder formats demanding reconstitution protocol support.
- Capsules:Gelatin or vegetable-based shells encase standardized cordycepin doses, enabling precise titration for immunomodulatory regimens. Pharmacy shelf placement in Japan and South Korea concentrates demand among elderly consumers seeking traditional medicine alternatives, with GB standards compliance becoming a non-negotiable procurement filter.
- Liquid Extract:Alcohol or glycerin-based suspensions deliver rapid bioavailability for functional beverage integration. Procurement from Seoul and Tokyo wellness platforms is climbing the fastest as direct-to-consumer subscription models displace conventional retail.
- Powder:Spray-dried concentrates require rehydration guidance and storage humidity controls. Sports nutrition blenders in North America represent the primary volume absorption for bulk ingredient sourcing.
- Dried:Whole fruiting bodies demand decoction instruction and visual quality grading. Traditional medicine practitioners in China sustain artisanal procurement despite industrial format competition.
By volume, capsules lead. By growth pace, liquid extract is ahead.
Application:
Margin architecture diverges across use cases, with pharmaceutical-grade extraction commanding analytical certification investments that food-grade applications avoid.
- Health Supplements:Standardized extracts in capsule or tablet form target daily immunomodulatory and stamina-support regimens. EFSA Novel Food dossier holders in Germany and France capture disproportionate pharmacy channel placement.
- Functional Foods:Cordyceps integration into energy bars, recovery beverages, and fortified cereals demands heat-stability optimization. South Korean CPG brands are expanding reformulated portfolios at triple-digit procurement rates.
- Pharmaceuticals:Pharmacopeial-grade extracts require HPLC-verified cordycepin and adenosine content for investigational drug applications. China's NMPA licensing framework constrains new entrant participation.
- Cosmetics:Topical formulations leverage purported antioxidant properties for anti-aging serums. Niche positioning in Japanese premium skincare channels sustains limited but high-margin volume.
Health supplements dominate current absorption. Functional foods are expanding most quickly.
Distribution Channel:
Channel selection determines regulatory exposure, with pharmacy placement requiring national pharmaceutical regulator compliance that online retail circumvents.
- Online Retail:Direct-to-consumer platforms enable personalized dosing protocols and automated replenishment. Seoul and Tokyo urban centers show the steepest subscription model adoption among thirty-to-forty-five-year-old professionals.
- Specialty Stores:Health food retailers provide education-intensive purchase environments for novel adaptogen consumers. Staff training investments differentiate premium from mass-market positioning.
- Supermarkets:Mass-market placement demands price-competitive powder and capsule formats with simplified labeling. Brazil's ANVISA evolving regulations create first-mover positioning for compliant entrants.
- Pharmacies:Professional recommendation channels require pharmacopeial-grade certification and national pharmaceutical regulator registration. EFSA-authorized suppliers consolidate procurement in European markets.
Pharmacies lead by margin per unit. Online retail is gaining share fastest.
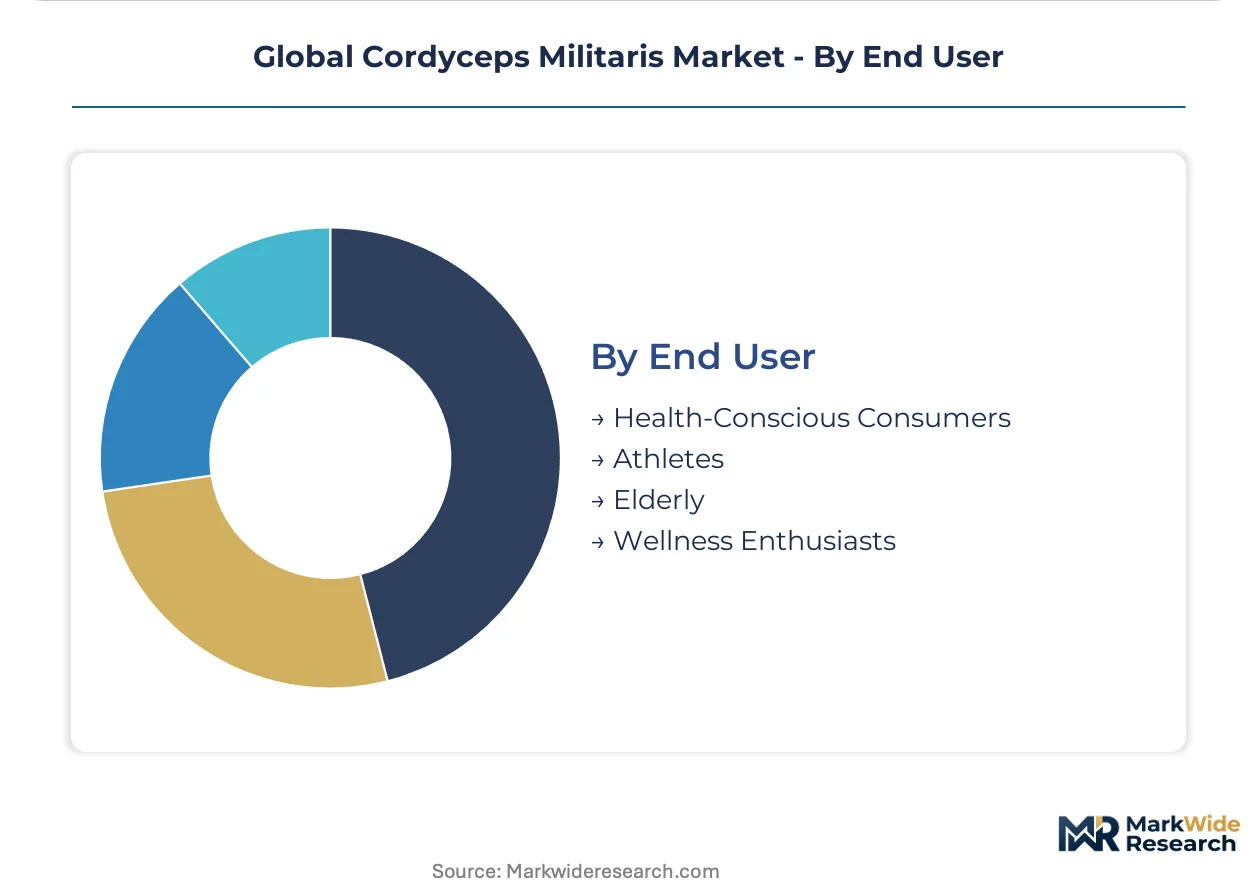
End User:
User sophistication dictates formulation complexity, with athletes requiring batch-tested purity certifications that general wellness consumers rarely demand.
- Health-Conscious Consumers:Preventive regimen adopters prioritize organic certification and substrate transparency. China's tightening GB standards for fungal-derived supplements reshape supplier qualification criteria.
- Athletes:Competition-tested populations demand banned-substance screening and bioactive standardization. Solid-state fermentation advances reduce harvest-cycle variability critical for consistent dosing.
- Elderly:Traditional medicine-oriented demographics in Japan favor capsule convenience and established brand recognition. Aging demographic expansion broadens the addressable base for immunomodulatory formulations.
- Wellness Enthusiasts:Early-adopter segments experiment with novel formats including liquid extracts and functional food integration. Direct-to-consumer channel migration is most visible in this cohort.
Elderly users represent the largest current segment. Wellness enthusiasts are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese pharmacy channels where elderly consumers pay premiums for pharmacopeial-grade extracts, while Brazilian distributors absorb margin compression from ANVISA compliance costs. German and French retailers consolidate procurement around EFSA-authorized suppliers. Chinese cultivators face GB standards upgrades that favor scaled producers.
China
Functional food manufacturers in Jiangsu and Zhejiang provinces expand Cordyceps-enriched product lines as adaptogenic ingredient interest intensifies. NMPA and SAMR jointly enforce fungal product licensing under revised food safety codes. Solid-state fermentation clusters in Dandong and Shenyang reduce harvest-cycle variability through bioreactor-based mycelium production.
Japan
Elderly consumers in Tokyo and Osaka seek traditional medicine alternatives, expanding the addressable base for immunomodulatory formulations. PMDA maintains pharmacopeial-grade certification requirements for pharmacy-channel placement. Kanto region distributors capture disproportionate shelf placement for capsule formats targeting aging demographic expansion.
Germany
Health supplement distributors consolidate procurement around grandfathered suppliers with existing EFSA Novel Food authorizations. EFSA assessments extend pre-market approval timelines beyond thirty-six months for new dossier submissions. Frankfurt and Munich pharmacy channels favor established capsule-format incumbents with compliance records.
South Korea
Wellness platforms in Seoul bundle personalized dosing protocols with automated replenishment for thirty-to-forty-five-year-old professionals. MFDS regulates functional food claims while CPG brands reformulate energy and recovery portfolios. Busan-Ulsan manufacturing bases supply triple-digit procurement growth for spray-dried extract inputs.
Brazil
ANVISA's evolving functional food regulations create first-mover positioning for pharmacy-channel entrants willing to absorb compliance investment. São Paulo distributors experiment with mass-market placement of powder formats. Southeast regional clusters test price-competitive positioning against established North American import suppliers.
Global Cordyceps Militaris Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream capturing substrate and extraction value. The vendor base distributes across captive mycelium laboratories, organic grain spawn producers, and direct-to-consumer wellness platforms. Three archetypes dominate: technology-forward cultivators with in-house analytical capabilities, backward-integrated substrate controllers, and channel-dominant subscription operators. Competitive moves concentrate on strategic partnerships for regulatory dossier sharing and capacity expansion in solid-state fermentation infrastructure.
Within the technology-forward cultivator tier, Dalong Biotechnology Co., Ltd. exemplifies captive laboratory control from inoculation through harvest. Naturalin Bio-Resources Co., Ltd. anchors the backward-integrated archetype through organic grain spawn production. NU SKIN ENTERPRISES, INC occupies a position within channel-dominant subscription models across Asia-Pacific wellness markets.
| Leading Market Players |
|---|
| Dalong Biotechnology Co., Ltd. |
| Health Choice Limited |
| MycoForest |
| Naturalin Bio-Resources Co., Ltd. |
| NU SKIN ENTERPRISES, INC |
| Nutra Green Biotechnology Co., Ltd. |
| Xi'an Saina Biological Technology Co., Ltd. |
| Sunrise Nutrachem Group Ltd. |
| Shanghai Kangzhou Fungi Extract Co., Ltd. |
| Others |
Supply & Pricing Matrix
Overcapacity in Dandong solid-state fermentation clusters is forcing cultivators to absorb substrate cost volatility while discounting standardized extracts to maintain offtake volumes. This utilization squeeze compresses margins for artisanal growers unable to match batch consistency, while scaled producers leverage captive laboratories to defend premium positioning in Japanese pharmacy channels.
Pricing Analysis
Configured-to-order pricing for pharmacopeial-grade extracts commands substantial premiums over standard spray-dried concentrates. Three-tier pricing structure across premium, standard, and economy levels reflects HPLC certification depth and substrate traceability. Pricing pressure stems from South Korean CPG brands demanding volume discounts for triple-digit procurement growth. Functional beverage manufacturers show highest price sensitivity, while Japanese elderly consumers in Tokyo and Osaka pharmacy channels remain least sensitive.
Supply Chain Analysis
Extended payment terms from Seoul wellness platforms are squeezing working capital for mid-tier cultivators dependent on grain spawn procurement. Supply concentrates in China, South Korea, and Japan, with Dandong bioreactor clusters and Busan-Ulsan manufacturing bases anchoring upstream capacity. Organic brown rice and oat grain inputs draw from climate-vulnerable Northeast Asian harvests. Single-source vulnerability concentrates in substrate suppliers lacking diversification. Distribution runs through direct-to-consumer subscription models displacing traditional pharmacy channels in Asia-Pacific urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market, with functional beverage integration representing a penetration tailwind as CPG brands reformulate energy portfolios at triple-digit rates.
For Market Incumbents: Harden analytical certification moats through captive HPLC laboratories to defend against spray-drying technology diffusion eroding premium pricing power. Deepen backward integration into organic grain spawn production to offset substrate input volatility threatening margin stability in Dandong fermentation clusters. For New Entrants and Emerging Players: Establish a beachhead in Brazil's pharmacy channel before ANVISA regulatory frameworks crystallize, absorbing compliance investment to capture first-mover positioning against North American import suppliers. Target São Paulo distributors experimenting with mass-market powder placement as the most penetrable entry vector. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across asset-light contract cultivation models, compressing capital requirements for scaled entry. Long-term viability favors technology-forward cultivators with in-house cordycepin assay capabilities over substrate-dependent artisanal growers. Watch EFSA Novel Food dossier approval velocity as the critical inflection signal for European market access economics.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Fermentation Scale-Up | Bioreactor-based mycelium production in Dandong reduces harvest-cycle variability for year-round supply. |
| EFSA Novel Food Dossier Investment | Pre-market authorization in Germany and France secures pharmacy shelf placement against thirty-six-month approval timelines. |
| Backward Integration into Organic Spawn | Captive grain production in Northeast Asia insulates against climate-driven substrate price fluctuations. |
| Direct-to-Consumer Platform Launch | Seoul and Tokyo subscription models capture thirty-to-forty-five-year-old professionals seeking stamina support. |
| Functional Beverage Partnership | South Korean CPG integration opens triple-digit procurement growth beyond capsule-format pharmacy channels. |
Research Methodology
A spread of perspectives from cultivation operations managers, functional food R&D directors, pharmacy procurement leads, and regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews across stakeholder roles with secondary validation from NMPA filings, MFDS functional food registrations, EFSA Novel Food assessments, and customs trade data. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Demand-supply-balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeling spanning product format, application tier, distribution channel, and end-user sophistication. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology diffusion curves. Forecast inputs incorporated solid-state fermentation capacity buildouts, GB standards enforcement timelines, and channel migration velocity in Asia-Pacific urban centers.
Sensitivities concentrate around EFSA approval velocity, ANVISA regulatory crystallization, and substrate harvest volatility in Northeast Asian sourcing regions. Forecasts reflect documented assumptions on technology adoption curves and regulatory enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Sea Moss Market
Specialty Foods
Asia-Pacific Free from Food Market
Specialty Foods
Mexico Guacamole Market
Specialty Foods
Tunisia Couscous Market
Specialty Foods
High Protein Cat Food Market
Specialty Foods
Fruit Dessert Market
Specialty Foods
Maple Syrup Market
Specialty Foods
Asia Pacific Pet Milk Replacers Market
Specialty Foods
Low Calorie Chocolate Desserts Market
Specialty Foods
Acacia Honey Market
Specialty Foods
Wheatgrass Products Market
Specialty Foods
Liquid Mushroom Market
Specialty Foods
Germany Barbeque Grill Market
Specialty Foods
Sweet Spreads Market
Specialty Foods
Hot and Sour Noodles Market
Specialty Foods
Asia-Pacific Tofu Market