
 High Protein Cat Food Market | 2026-2036
High Protein Cat Food Market Size, Share, and Industry Trends Forecast 2026-2036
High Protein Cat Food Market Foresight
Premium grain-free formulations are redrawing competitive boundaries in high protein cat food. Mars Incorporated leverages its global manufacturing scale to secure supply chain stability across multiple protein sourcing regions. Nestlé Purina PetCare differentiates through veterinary channel partnerships that reinforce clinical credibility. Blue Buffalo Pet Products specializes in limited-ingredient, high-animal-protein recipes that occupy the super-premium shelf space in pet specialty retail.
High protein cat food denotes formulations where crude protein exceeds standard commercial benchmarks, typically delivered through elevated inclusion rates of named animal meals, fresh muscle tissue, or hydrolyzed protein isolates, with manufacturing processes emphasizing lower-temperature extrusion or retort cooking to preserve amino acid bioavailability. Wet food and freeze-dried segments command disproportionate margin pools due to perceived freshness and minimal processing narratives among discerning owners. Animal-based ingredient sourcing dominates volume, though mixed formulations are gaining shelf presence as brands navigate cost volatility in poultry and fish commodities.
The FDA Center for Veterinary Medicine enforces food safety standards under the Federal Food, Drug, and Cosmetic Act, while AAFCO model regulations govern nutritional adequacy claims that manufacturers must meet for interstate commerce. State-level feed control officials in California and Texas conduct additional label audits that create compliance friction for smaller entrants. Stakeholders must monitor evolving definitions of "high protein" as regulatory bodies weigh whether percentage thresholds warrant explicit disclosure requirements.
Market Dynamics
Pet humanization is compressing the premiumization cycle in high protein cat food, as urban millennial owners demand species-appropriate nutrition transparency that forces manufacturers to reformulate around named animal proteins and reject ambiguous by-product labeling.
Growth Catalysts
- AAFCO Nutrient Profile Updates:The association's evolving protein adequacy standards are compelling manufacturers to elevate named animal meal inclusion rates and disclose amino acid profiles, creating formulation differentiation that rewards transparency investments.
- Wet Food Processing Advances:Lower-temperature retort cooking technologies are preserving taurine and lysine bioavailability in canned formulations, enabling premium positioning that captures margin pools from freeze-dried alternatives.
- Urban Millennial Pet Ownership:Concentrated demand in United States metropolitan clusters is sustaining category expansion as disposable income growth supports sustained trading-up from standard commercial kibble.
Market Restraints
- Poultry and Fish Commodity Volatility:Animal-based ingredient sourcing dominates volume, leaving manufacturers exposed to price swings in Atlantic salmon and broiler chicken supply chains that compress margin stability.
- California and Texas Label Audits:State-level feed control officials conduct additional compliance verification that creates friction for smaller entrants lacking dedicated regulatory affairs functions.
- Plant Protein Substitution Pressure:Mixed formulations incorporating pea and lentil isolates are gaining shelf presence as brands navigate cost volatility, threatening pure animal-protein positioning.
Strategic Opportunities
- Veterinary Channel Partnerships:Clinical credibility reinforcement through prescription diet positioning opens access to recommendation-driven purchasing that commands price premiums over mass retail.
- Freeze-Dried Format Expansion:Minimal processing narratives among discerning owners support disproportionate margin capture in raw-adjacent segments that wet food cannot fully satisfy.
- FDA Labeling Requirement Evolution:Anticipated disclosure mandates for percentage-based protein thresholds would advantage early movers with transparent formulation architectures already in place.
Industry Challenges
- Animal Nutritionist Talent Scarcity:Formulation expertise combining feline metabolic science with extrusion engineering is concentrating among established manufacturers, constraining new entrant R&D velocity.
- Multi-State Registration Complexity:Individual state feed control approvals create compliance timeline fragmentation that delays product launches and strains smaller brand regulatory bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Protein Cat Food Market |
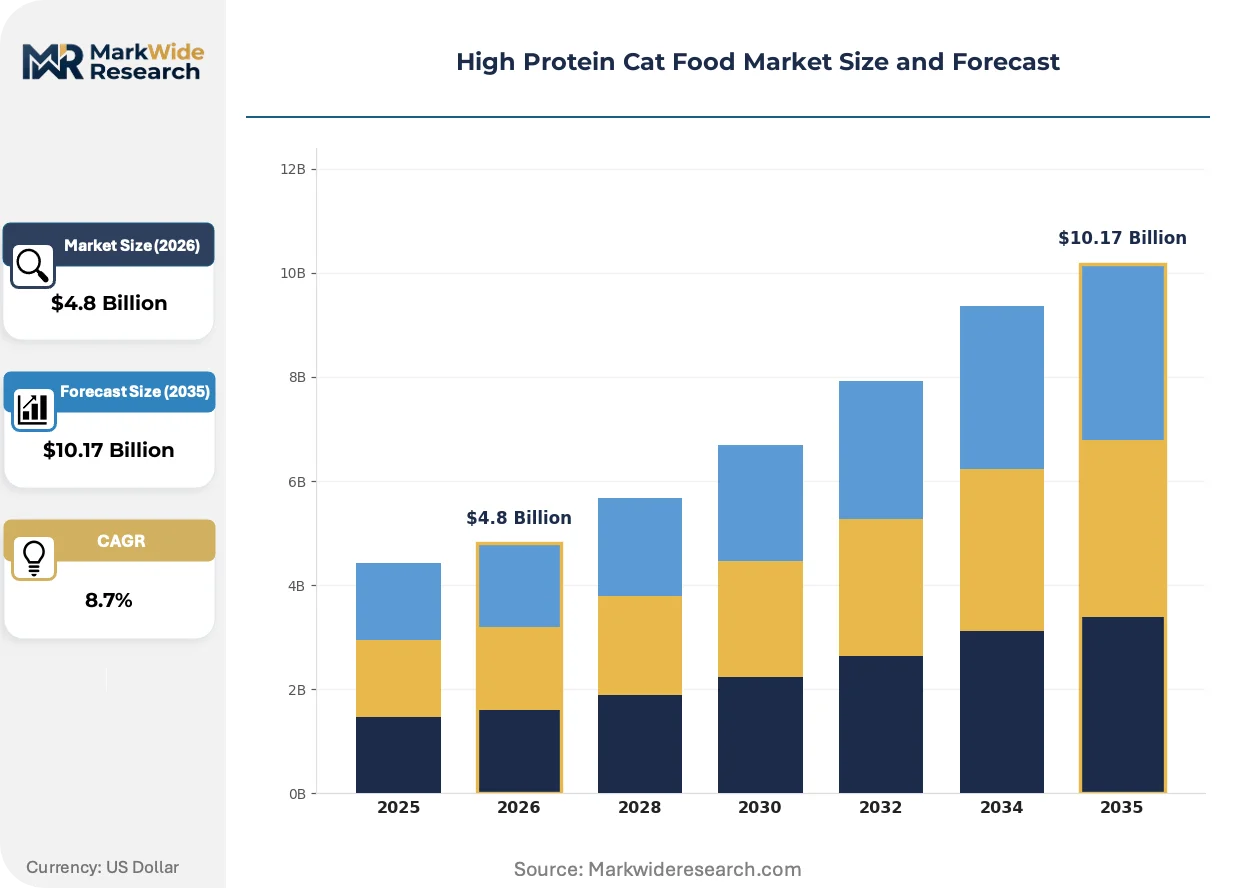
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Freeze-Dried Ingredient Source: Animal-Based, Plant-Based, Mixed, Others Formulation: Grain-Free, High-Fiber, Low-Carb, Organic Distribution Channel: Online Retail, Pet Specialty Stores, Supermarkets, Veterinarians |
| Companies Covered | Mars Incorporated, Nestlé Purina PetCare, Hill’s Pet Nutrition, The J.M. Smucker Company, General Mills, Blue Buffalo Pet Products, WellPet LLC, The Hartz Mountain Corporation, Diamond Pet Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Protein Cat Food Market Shifts & Advancements
Cold-chain preservation technologies and direct-to-consumer subscription models are simultaneously elevating product integrity expectations and disintermediating traditional pet specialty retail, forcing incumbent brands to rebuild distribution economics around freshness guarantees rather than shelf stability.
High-pressure processing (HPP) for raw and lightly cooked formulations is bifurcating the premium segment between pathogen-eliminated safety-assured products and traditional raw diets. Early adopting urban owners in coastal United States markets are trading up to HPP-treated options at accelerating velocity. This safety-technology convergence is compressing conventional raw brand positioning while enabling mass-market retailers to stock previously restricted product categories.
REACH chemical safety standards in Europe are extending scrutiny to packaging migration risks in retort pouches and cans, compelling suppliers to validate epoxy-phenolic coating alternatives. Manufacturers exporting to EU markets must reformulate can linings or absorb certification costs that domestic-only competitors avoid. Wet food brands with European distribution footprints are accelerating migration to polyester-based barrier coatings ahead of anticipated regulatory tightening.
Subscription replenishment models are displacing episodic pet specialty purchasing among high-loyalty urban households, compressing customer acquisition costs while elevating lifetime value metrics. Direct-to-consumer platforms capture detailed consumption data that enables personalized feeding recommendations and automated reorder timing. This channel shift concentrates in United States metropolitan corridors where delivery infrastructure density supports cold-chain reliability for wet food shipments.
High Protein Cat Food Market Segmentation
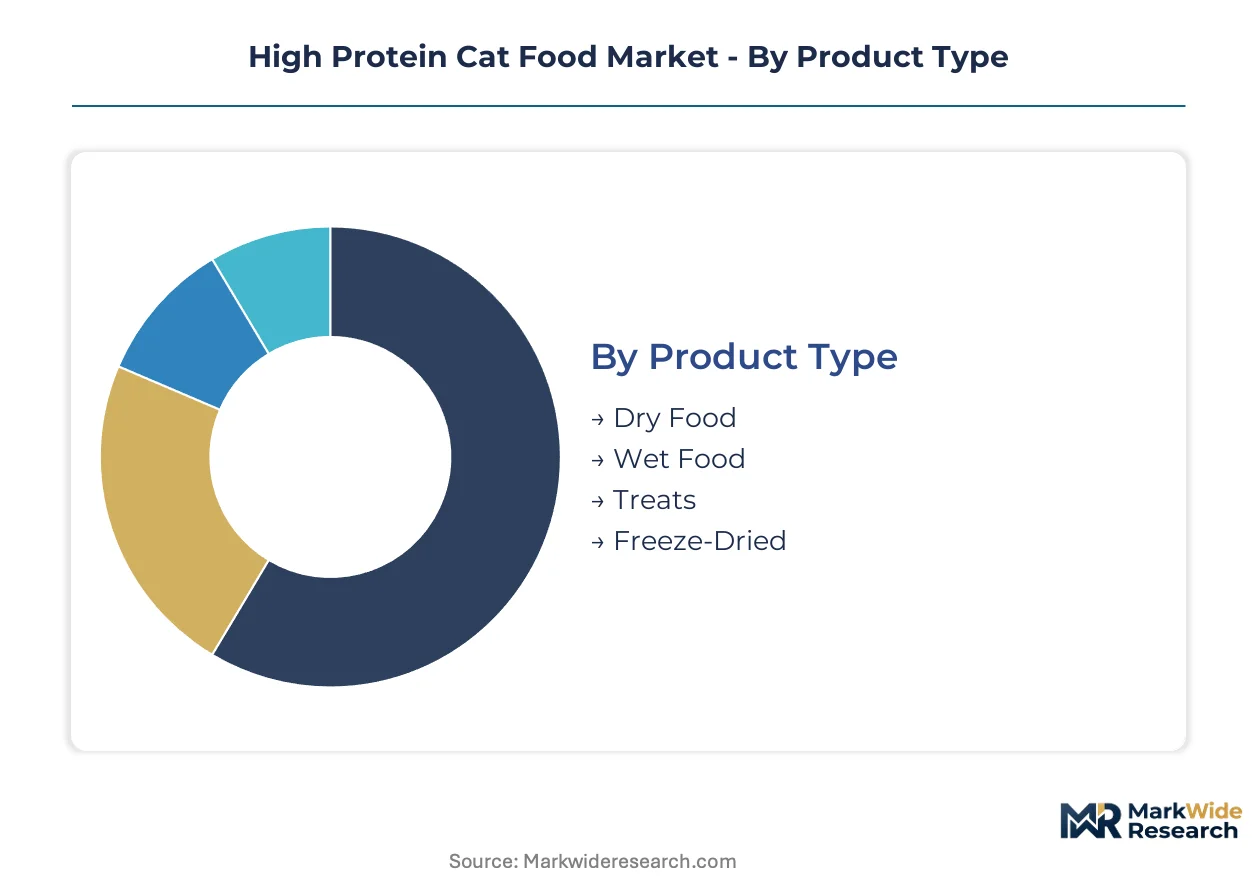
Segmentation in high protein cat food reveals how manufacturing capabilities, sourcing strategies, and channel economics partition the competitive landscape. Manufacturers must align formulation investments with distinct margin pools and regulatory exposure profiles across each dimension.
Product Type:
Dry formulations dominate domestic manufacturing volume in the United States, while wet and freeze-dried segments drive export-led premium positioning into European and Asian markets.
- Dry Food:Extruded kibble with protein content typically delivered through rendered meat meals and concentrated isolates. Demand concentrates in mass retail channels across the United States Midwest and Southeast, constrained by AAFCO labeling audits that elevate compliance costs for smaller producers.
- Wet Food:Retort-canned formulations preserving amino acid bioavailability through lower-temperature processing. Coastal United States metropolitan clusters sustain trading-up momentum as urban millennial owners prioritize moisture content and species-appropriate nutrition narratives.
- Treats:High-protein functional snacks targeting dental health or hairball control. Limited-ingredient positioning in pet specialty retail captures impulse purchasing adjacent to core nutrition categories.
- Freeze-Dried:Raw-adjacent minimal processing formats commanding disproportionate margins through direct-to-consumer subscription channels.
Dry food holds the largest share; momentum sits with freeze-dried formats expanding most quickly through veterinary recommendation networks.
Ingredient Source:
Cost tier stratification separates commodity-exposed animal-based sourcing from emerging plant-protein alternatives navigating taurine supplementation challenges.
- Animal-Based:Named muscle tissue, organ meats, and hydrolyzed protein isolates delivering complete amino acid profiles. Premium positioning in United States pet specialty and veterinary channels depends on transparent supply chain documentation responding to FDA evolving disclosure requirements.
- Plant-Based:Pea and lentil protein concentrates with synthetic amino acid fortification. European markets under EFSA scrutiny drive formulation caution as regulators evaluate long-term feline metabolic adequacy claims.
- Mixed:Hybrid formulations balancing cost volatility hedging against animal-protein authenticity marketing. Supermarket channel placement in Germany and France accelerates as mid-tier brands seek margin protection.
- Others:Novel protein sources including insect meal and cultivated muscle tissue. Experimental positioning in Scandinavian markets tests consumer acceptance ahead of broader commercialization.
Animal-based sourcing holds the largest share; momentum sits with mixed formulations gaining share fastest in cost-sensitive European retail.
Formulation:
Maturity differentiation separates established grain-free positioning from emerging metabolic health claims targeting feline obesity and diabetes management.
- Grain-Free:Elimination of corn, wheat, and soy with carbohydrate replacement through tubers and legumes. United States coastal urban demand sustains premium pricing despite ongoing FDA investigation into dilated cardiomyopathy correlations.
- High-Fiber:Soluble and insoluble fiber inclusion targeting hairball management and satiety. Veterinary channel distribution in Japan and South Korea expands as metabolic disease prevalence rises among indoor cats.
- Low-Carb:Carbohydrate restriction below 10% dry matter aligning with obligate carnivore metabolic physiology. Prescription diet positioning through United States veterinary clinics commands reimbursement-adjacent pricing power.
- Organic:Certified ingredient sourcing with prohibited synthetic inputs. European Union organic regulation compliance creates export qualification barriers for non-certified United States manufacturers.
Grain-free holds the largest share; momentum sits with low-carb formulations climbing the fastest through clinical recommendation networks.
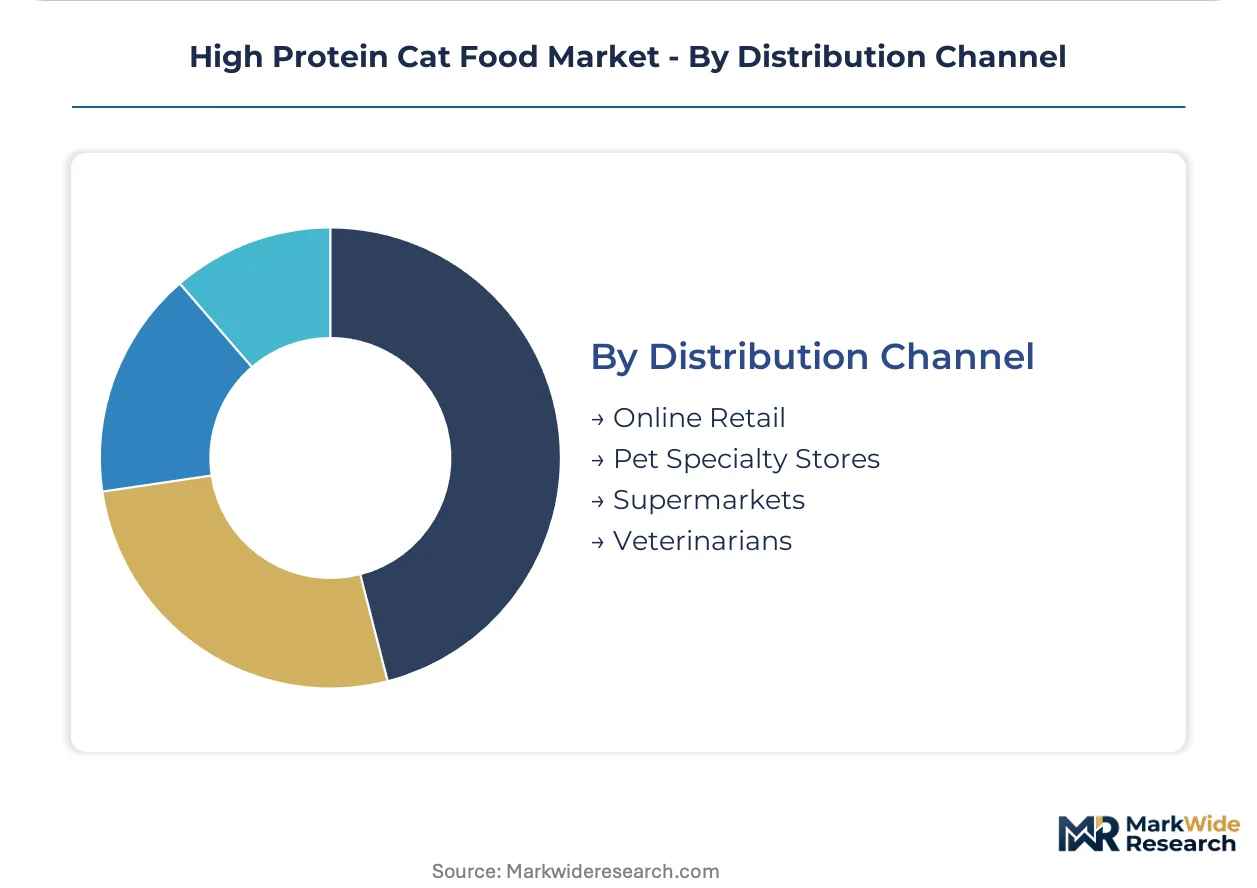
Distribution Channel:
Customer type fragmentation separates episodic retail purchasing from subscription-driven replenishment models capturing lifetime value concentration.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators capturing detailed consumption data. United States metropolitan delivery infrastructure supports cold-chain wet food reliability that enables subscription lock-in.
- Pet Specialty Stores:Independent and chain retailers with educated staff enabling ingredient narrative translation. Shelf space competition in Germany's Fressnapf and United States Petco networks elevates slotting fee burdens.
- Supermarkets:Mass-market placement reaching convenience-oriented purchasers with lower engagement levels. Price-promotion dependency in France's Carrefour and United States Kroger chains compresses brand equity investment returns.
- Veterinarians:Clinic-based dispensing and recommendation-driven purchasing with prescription diet protocols. Clinical credibility reinforcement in United States and Japanese markets supports price premiums unattainable in mass retail.
Pet specialty stores hold the largest share; momentum sits with online retail expanding most quickly through data-enabled personalization engines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of high protein cat food concentrate in formulated wet products shipped from United States and Thai manufacturing hubs toward European and Japanese import markets. Trade balances shift as domestic production capacity expands in Germany and South Korea to reduce import dependency.
United States
Urban millennial pet ownership clusters in coastal metropolitan corridors sustain premium wet food demand growth. FDA Center for Veterinary Medicine labeling enforcement under the Federal Food, Drug, and Cosmetic Act elevates compliance costs for interstate commerce. Manufacturing concentrates in Midwest rendering and extrusion facilities supplying mass retail channels nationwide.
Germany
Discerning pet owners in metropolitan Berlin and Munich drive super-premium grain-free formulation adoption. EFSA scrutiny of pea protein adequacy claims shapes formulation caution across domestic brands. The Fressnapf retail network anchors distribution with educated staff translating ingredient narratives.
Japan
Veterinary channel dispensing of prescription metabolic diets expands as feline obesity prevalence rises among indoor cats. METI oversight of pet food safety standards aligns with international harmonization efforts. Tokyo and Osaka clinic networks concentrate recommendation-driven purchasing with reimbursement-adjacent pricing.
Thailand
Atlantic salmon and tuna raw material access supports wet food export manufacturing for Asian and European markets. National food safety authority audits align with destination market requirements. Bangkok-adjacent processing zones concentrate retort canning capacity serving brand owners in Japan and Australia.
United Kingdom
Subscription replenishment models capture high-loyalty households in London and Southeast England corridors. Post-Brexit veterinary product regulations create parallel compliance tracks with EU standards. Pet specialty chains in Manchester and Birmingham elevate slotting fee competition for shelf space.
High Protein Cat Food Market Competitive Landscape
Listed leaders compete with private specialists across channel access and formulation credibility dimensions. The vendor base concentrates around diversified food conglomerates with captive pet divisions alongside dedicated pet nutrition pure-plays. Three archetypes dominate: multinational CPG houses with veterinary channel leverage, mid-tier private specialists with ingredient transparency positioning, and contract manufacturers serving private label programs. Competitive moves center on M&A absorption of regional brands and backward integration into protein rendering capacity.
Within the multinational CPG tier, Mars Incorporated and Nestlé Purina PetCare exemplify scale-driven supply chain architectures spanning multiple sourcing regions. Blue Buffalo Pet Products occupies a position within the super-premium specialist archetype, anchoring limited-ingredient credibility in pet specialty retail. These three entities represent distinct competitive vectors: manufacturing scale, clinical channel penetration, and ingredient narrative authenticity.
| Leading Market Players |
|---|
| Mars Incorporated |
| Nestlé Purina PetCare |
| Hill’s Pet Nutrition |
| The J.M. Smucker Company |
| General Mills |
| Blue Buffalo Pet Products |
| WellPet LLC |
| The Hartz Mountain Corporation |
| Diamond Pet Foods |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts for Atlantic salmon and broiler chicken lock in supply access and price visibility for United States manufacturers, insulating premium wet food producers from spot market volatility while compressing margin flexibility for smaller brands without procurement scale.
Pricing Analysis
Urban millennial pet owners anchor subscription-based pricing structures that capture lifetime value through automated replenishment models. Three-tier pricing structure across freeze-dried premium, wet food standard, and dry kibble economy levels separates Mars Incorporated and Nestlé Purina PetCare from private-label competitors. Cost compression in the economy tier intensifies as Thai export manufacturers absorb currency fluctuation impacts. Mass retail purchasers in United States supermarket chains exhibit highest price sensitivity, while veterinary channel buyers show lowest sensitivity due to reimbursement-adjacent positioning.
Supply Chain Analysis
Port congestion on the Trans-Pacific trade lane elevates inbound logistics costs for Thai-manufactured retort cans entering United States West Coast distribution hubs. Raw material sourcing concentrates in Thailand for tuna and salmon, the United States Midwest for rendered poultry meals, and Germany for organic certification-compliant ingredients. The supply chain draws from single-source vulnerability in hydrolyzed protein isolate production, where European specialty chemical suppliers dominate capacity. Distribution runs through direct-to-consumer subscription platforms, pet specialty retail networks, and veterinary clinic dispensing systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation expertise combining feline metabolic science with extrusion engineering represents the critical scarcity constraining new entrant velocity, concentrating R&D capability among established manufacturers with captive animal nutritionist teams.
For Market Incumbents: Consolidate backward integration into protein rendering capacity across Midwest United States facilities to secure supply chain stability against poultry commodity volatility. Capture regulatory affairs bandwidth through dedicated multi-state registration teams that neutralize compliance friction from California and Texas feed control audits. Lock in veterinary channel partnerships before prescription diet positioning becomes saturated. For New Entrants and Emerging Players: Differentiate on novel protein transparency through named insect meal or cultivated muscle tissue sourcing that escapes commodity cost exposure. Target Scandinavian markets testing consumer acceptance ahead of broader commercialization, where regulatory scrutiny remains lighter than EFSA-monitored European core markets. Deploy direct-to-consumer subscription models with personalized feeding algorithms to bypass slotting fee barriers in pet specialty retail. For Investors and Strategic Acquirers: Contract manufacturers with private-label wet food capabilities and European organic certification represent the most defensible acquisition archetype, capturing margin pools as brand owners outsource production. Monitor FDA labeling requirement evolution as the inflection signal: percentage-based protein disclosure mandates would advantage targets with transparent formulation architectures already operationalized.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Partnership | Clinical credibility reinforcement through Hill's Pet Nutrition-style prescription positioning opens recommendation-driven purchasing. |
| Freeze-Dried Format Expansion | Minimal processing narratives among discerning owners support disproportionate margin capture in raw-adjacent segments. |
| Backward Integration into Rendering | Captive poultry meal production insulates Mars Incorporated from Atlantic salmon and broiler chicken commodity volatility. |
| Direct-to-Consumer Platform Launch | Subscription replenishment models displace episodic pet specialty purchasing among high-loyalty urban United States households. |
| European Organic Certification | EU organic regulation compliance creates export qualification barriers that certified manufacturers exploit for pricing power. |
Research Methodology
A spread of perspectives from brand formulation directors, veterinary nutritionists, pet specialty retail category managers, and state feed control officials converged on the working assumptions driving supply chain and pricing dynamics. Primary interviews combined with secondary validation from FDA Center for Veterinary Medicine guidance documents, AAFCO model regulation updates, EFSA scientific opinions on pea protein adequacy, and United States customs import records. Bottom-up manufacturer capacity assessments triangulated against top-down retail audit data from Nielsen and Circana.
Segmentation dimensions modeled span product type, ingredient source, formulation claim, and distribution channel across the analysis window. CAGRs derived from volume-weighted average growth trajectories incorporating urban millennial pet ownership clustering, disposable income elasticity coefficients, and regulatory compliance cost pass-through assumptions. Industry-specific forecast inputs include AAFCO nutrient profile update implementation timelines and cold-chain delivery infrastructure density metrics.
Material uncertainties — abrupt shifts in FDA labeling enforcement, EFSA pea protein adequacy rulings, or Trans-Pacific logistics disruption — sit outside the modeled envelope. Forecasts reflect assumptions about sustained pet humanization trends and stable commodity input costs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Spirulina Chocolate Market
Specialty Foods
Low Calorie Desserts Market
Specialty Foods
CBD-Infused Ice Cream Market
Specialty Foods
Global Nata De Coco Market
Specialty Foods
Miso Market
Specialty Foods
Low Calorie Veggie Dip Market
Specialty Foods
Saw Palmetto Market
Specialty Foods
Asia Pacific Cat Food Market
Specialty Foods
Global Hispanic Foods Market
Specialty Foods
Super Foods Market
Specialty Foods
Morocco Couscous Market
Specialty Foods
Mexico Guacamole Market
Specialty Foods
Superfood Bars Market
Specialty Foods
Coconut Butter Market
Specialty Foods
Konjac Noodles Market
Specialty Foods
Asia-Pacific Alcohol-Infused Ice Cream Market