
 Yacht Shell Doors Market | 2026-2036
Yacht Shell Doors Market Size, Share, and Industry Trends Forecast 2026-2036
Yacht Shell Doors Market Analytics
Carbon fiber reinforced polymer is expanding its share in superyacht shell door fabrication, displacing conventional aluminum plate in vessels above 50 meters. Fassmer GmbH & Co. KG leverages its German engineering heritage to dominate complex custom geometries for expedition yachts. Cramm sustains a specialized position in high-cycle hydraulic shell door systems for commercial conversion projects. AdvanTec Marine anchors its competitive stance through backward integration into CNC-machined sealing hardware.
Yacht shell doors are pressure-rated marine access systems, typically fabricated from marine-grade aluminum alloys, carbon fiber composites, or glass-reinforced polymers, engineered to withstand hydrostatic loading, salt corrosion, and cyclic fatigue while maintaining watertight integrity per ISO 12216 standards. Their primary purpose is to provide secure personnel and equipment transfer points on yacht hulls and superstructures without compromising structural or environmental sealing performance. Sliding door configurations lead volume in new-build superyachts due to space-efficiency demands in constrained engine room and tender garage layouts. Composite material segments command premium positioning as shipyards pursue weight reduction for IMO-compliant efficiency gains. Retrofit installation channels are gaining traction as owners extend vessel service life rather than commissioning replacement hulls.
ISO 12216 structural requirements, the EU's F-Gas Regulation on sealed system refrigerants, and CE marking under the EU Marine Equipment Directive collectively shape product certification pathways and market access conditions for shell door manufacturers serving European-flagged vessels. The US Coast Guard's structural fire protection standards for commercial yacht conversions create parallel compliance obligations for suppliers targeting North American refit yards. Stakeholders must monitor evolving classification society rules on composite fire resistance ratings as these materials penetrate larger vessel classes.
Market Dynamics
Superyacht owners are compressing build cycles while demanding lighter, larger shell door systems, forcing shipyards to reconfigure tender garage layouts and recertify structural load paths mid-project.
Growth Catalysts
- EU Green Deal material mandates:Emissions-linked standards are accelerating carbon fiber adoption in Mediterranean new-build yards. Shipbuilders in Italy and Turkey are redesigning hull access points to meet weight targets.
- Composite fabrication advances:Automated fiber placement is reducing shell door production lead times for expedition yacht orders. German engineering clusters are supplying precision-molded geometries that manual layup cannot replicate.
- Retrofit channel expansion:Service life extension programs in French and Spanish refit centers are generating aftermarket shell door replacements. Owners are opting for hull upgrades rather than commissioning replacement vessels.
Market Restraints
- Carbon fiber input cost volatility:Prepreg resin systems and aerospace-grade fiber supply constraints are compressing margins for composite shell door fabricators. Price spikes in epoxy chemistries directly transfer to quoted door assemblies.
- Mediterranean supply concentration:Italian and Turkish yards control over sixty percent of superyacht shell door specification authority. This geographic clustering creates vulnerability to port labor disruptions and regional logistics bottlenecks.
- ISO 12216 fire resistance limitations:Current classification society rules restrict composite shell doors from passenger vessel applications above certain tonnage thresholds. Aluminum plate retains mandatory status in fire-critical zones.
Strategic Opportunities
- Expedition yacht segment expansion:Polar-class vessel orders from Norwegian and Icelandic operators are creating demand for ice-rated shell door systems. These doors require reinforced sealing geometry absent from standard Mediterranean specifications.
- EU F-Gas Regulation retrofit incentives:Refrigerant system overhauls in existing superyachts are triggering concurrent hull access upgrades. Shell door replacements are being bundled with climate system compliance work.
- Digital twin integration:Hull stress modeling software is converging with shell door CAD libraries to enable real-time load monitoring. French classification societies are piloting sensor-embedded door frames for predictive maintenance contracts.
Industry Challenges
- Composite technician scarcity:Vacuum infusion and autoclave curing expertise is concentrated among aging workforces in German and Dutch marine fabrication clusters. Training pipelines are not replenishing skilled labor at replacement rates.
- CE marking timeline compression:EU Marine Equipment Directive certification cycles for novel shell door geometries are extending due to Notified Body backlogs. Shipyards are absorbing schedule risk in fixed-price build contracts.
- Legacy hydraulic system integration:Refit projects requiring shell door upgrades must reconcile modern electronic controls with existing vessel power architectures. Spanish and Italian yards report elevated commissioning delays from control interface mismatches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yacht Shell Doors Market |
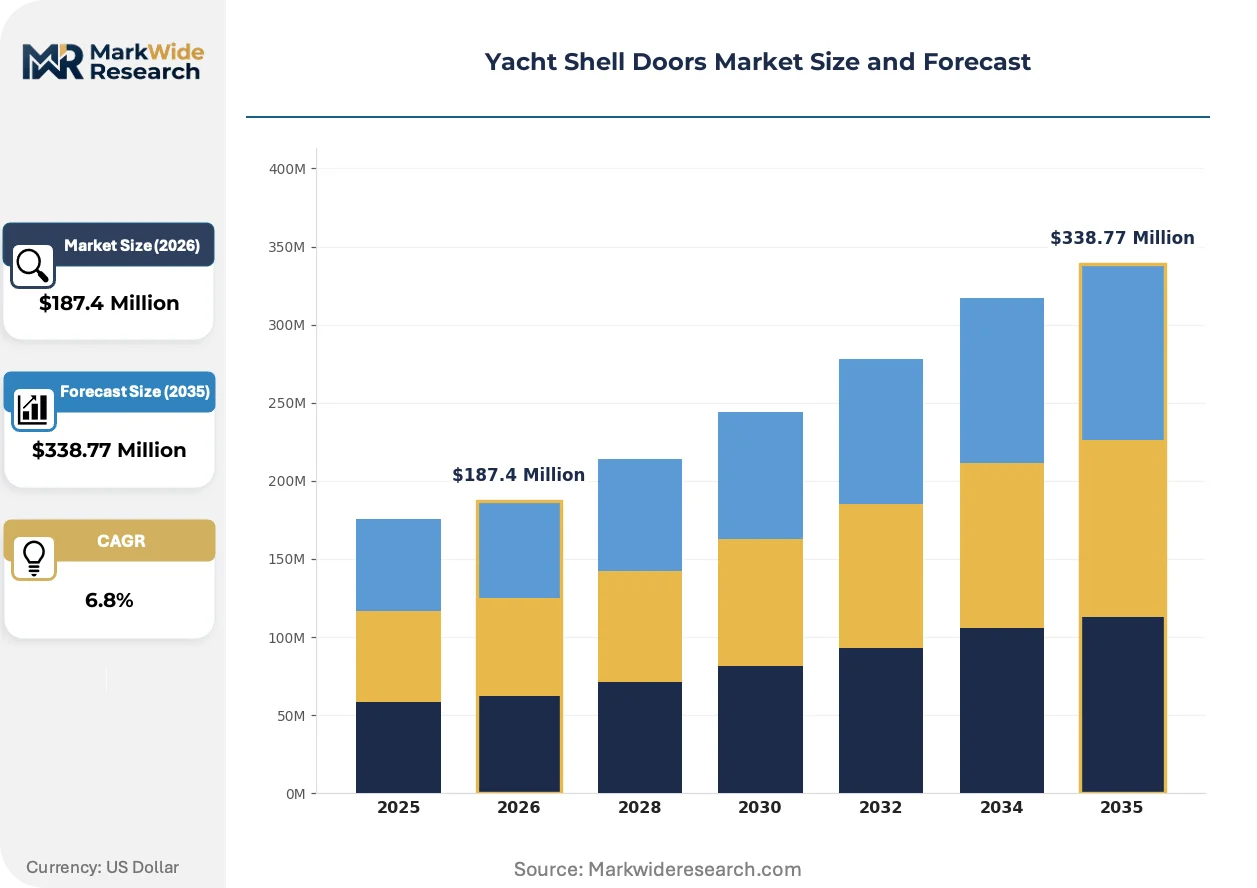
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliding Doors, Hinged Doors, Bi-Fold Doors, French Doors Material: Composite, Fiberglass, Aluminum, Wood Installation Type: New Construction, Retrofit, Custom Fit, Standard Fit End User: Private Yachts, Commercial Vessels, Charters, Shipbuilders |
| Companies Covered | Sea Power, Ocean Group, Fassmer GmbH & Co. KG, Cramm, SeaNet SA, Cen-Tex Marine, AdvanTec Marine, Houdini Marine Windows, Saajos Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yacht Shell Doors Market Evolving Landscape
Shell door engineering is pivoting from static structural components to integrated systems that communicate load state and sealing integrity back to vessel automation platforms.
Carbon fiber reinforced polymer door fabrication is modularizing across superyacht build programs. Italian shipyards are adopting standardized frame subassemblies that slot into variable hull curvatures. This approach compresses custom engineering hours while preserving owner-specific aesthetic specifications.
The EU F-Gas Regulation is tightening refrigerant containment standards for yacht climate systems. Shell door perimeter sealing must now accommodate thermal expansion cycling without compromising gasket integrity. Mediterranean yards are specifying dual-durometer seal profiles that respond to both pressure and temperature differentials.
Owner procurement patterns are fragmenting across direct yard relationships and specialized marine equipment distributors. Turkish build centers are consolidating shell door sourcing through captive supply agreements with German engineering houses. This channel consolidation is marginalizing independent door fabricators lacking classification society pre-approval.
Yacht Shell Doors Market Segmentation
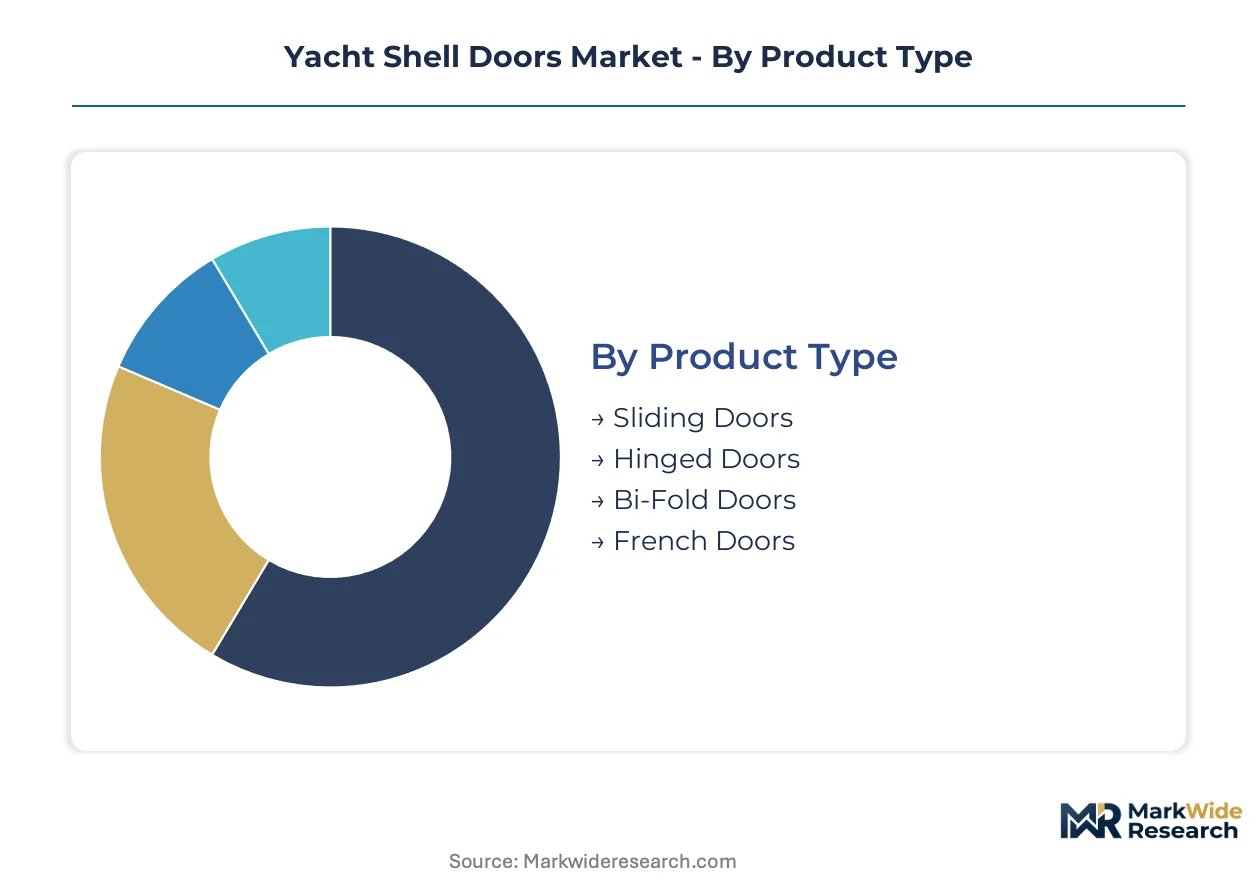
Shell door segmentation reveals how technical specifications cascade through procurement decisions. Shipyards configure product-mix strategies around hull architecture constraints and owner customization requirements.
Product Type:
Integration depth varies sharply—sliding configurations embed directly into tender garage superstructures while hinged systems function as standalone hull penetrations.
- Sliding Doors:Horizontal track-mounted systems maximize spatial efficiency in confined engine room and tender garage layouts. Mediterranean new-build yards in Italy and Turkey specify these for vessels above 50 meters where garage volume is constrained by beam limitations. Lateral translation eliminates swing radius requirements.
- Hinged Doors:Pivot-mounted assemblies attach at reinforced hull frames and open outward against hydrostatic pressure. Expedition yacht operators in Norway and Iceland favor these for ice-rated sealing geometry that withstands polar loading conditions. Simpler actuation reduces hydraulic complexity.
- Bi-Fold Doors:Articulated panel systems fold mid-span to reduce open swing footprint. Compact stowage suits refit projects where existing hull cutouts cannot expand.
- French Doors:Paired hinged panels with center mullion division serve superstructure access points. Aesthetic specifications dominate owner-facing applications.
Sliding doors lead volumes today; hinged doors are gaining share fastest in polar-class expedition segments.
Material:
Cost tiers stratify sharply—composite commands premium positioning while aluminum retains mid-market dominance through regulatory fire-safety mandates.
- Composite:Carbon fiber reinforced polymer laminates achieve weight reductions exceeding aluminum equivalents by substantial margins. German engineering clusters supply precision-molded geometries via automated fiber placement. EU Green Deal emissions standards accelerate specification in Mediterranean new-builds.
- Aluminum:Marine-grade 5083 and 6082 alloys maintain mandatory status in fire-critical zones under ISO 12216 fire resistance limitations. Classification society rules restrict composites from passenger vessel applications above certain tonnages. Turkish and Italian yards default to aluminum for commercial conversion projects.
- Fiberglass:Glass-reinforced polymer offers intermediate weight savings at lower cost than carbon fiber systems. Vacuum infusion production suits mid-size yacht production runs.
- Wood:Teak and mahogany veneers serve interior aesthetic applications where structural loading is minimal. Heritage restoration projects in French and Spanish refit centers sustain niche demand.
Aluminum dominates current installations; composite materials are expanding most quickly in superyacht new-build specifications.
Installation Type:
Volume distribution tracks vessel lifecycle patterns—new construction flows through shipyard procurement while retrofit channels capture service life extension economics.
- New Construction:Shell doors specified during hull design enable integrated structural load path engineering. CE marking under EU Marine Equipment Directive shapes certification timelines for European-flagged vessels.
- Retrofit:Hull access upgrades bundled with climate system compliance work generate aftermarket replacements. French and Spanish refit centers report rising owner preference for vessel extension over replacement commissioning.
- Custom Fit:Bespoke geometry engineered to owner-specific hull curvatures and aesthetic requirements. German and Dutch fabrication clusters concentrate vacuum infusion expertise for complex geometries.
- Standard Fit:Pre-engineered frame subassemblies slot into production hull programs. Italian yards modularize across build programs to compress custom engineering hours.
New construction channels capture majority volume; retrofit installations are climbing the fastest as fleet aging accelerates.
End User:
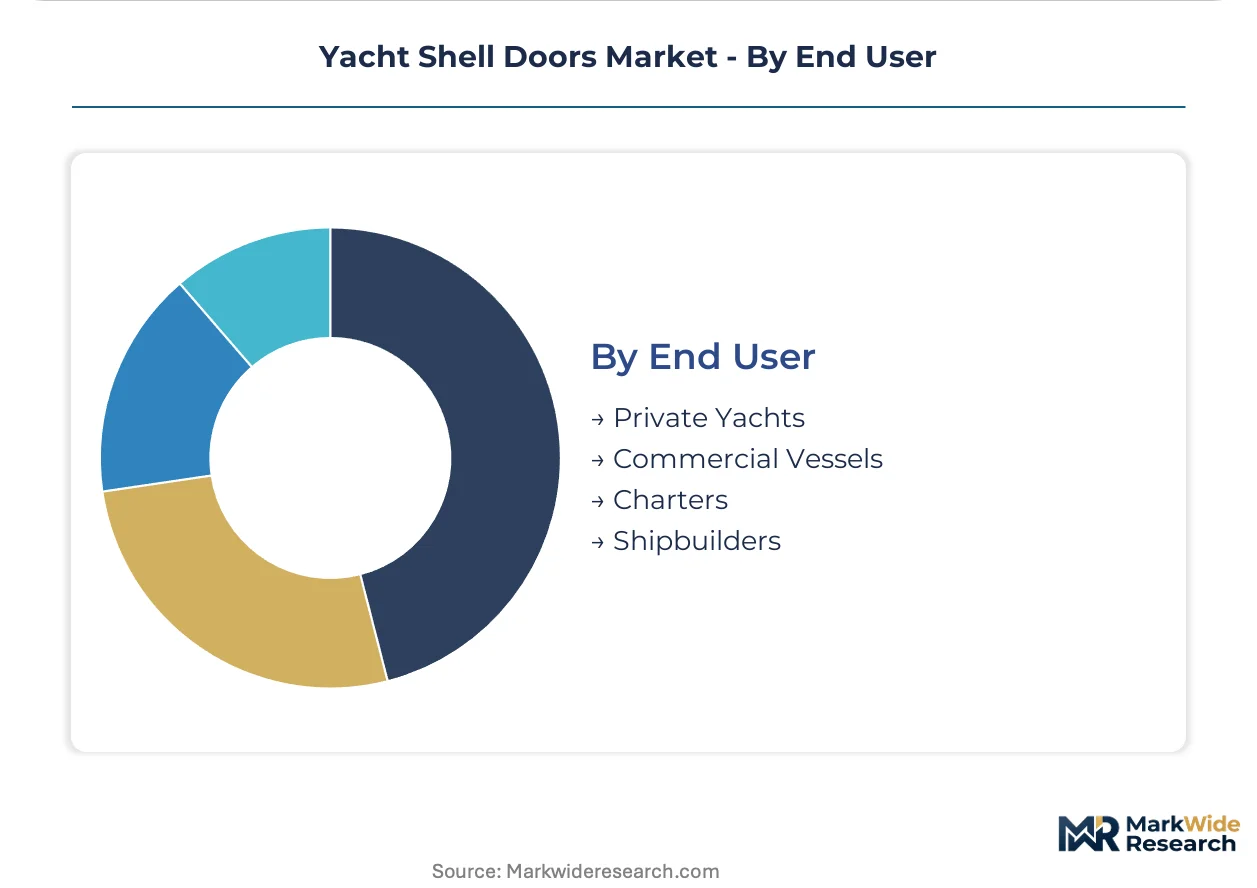
Customer type determines specification authority—shipbuilders control technical selection while private owners drive aesthetic customization.
- Private Yachts:Individual owners prioritize weight reduction for IMO-compliant efficiency gains and tender garage capacity expansion. Mediterranean build centers concentrate demand for composite systems above 50 meters.
- Commercial Vessels:Charter operators and yacht management companies emphasize durability and maintenance interval predictability. US Coast Guard structural fire protection standards shape North American refit yard specifications.
- Charters:High-cycle usage patterns demand reinforced sealing hardware and hydraulic system redundancy. Cramm specializes in high-cycle configurations for this segment.
- Shipbuilders:Turkish build centers consolidate sourcing through captive supply agreements with German engineering houses. Channel consolidation marginalizes independent fabricators lacking classification society pre-approval.
Private yachts lead specification value; commercial vessels are expanding most quickly through conversion project pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mediterranean shipbuilding clusters in Italy, Turkey, and France command specification authority for superyacht shell door systems. German engineering houses supply precision-molded composite geometries to these build centers. Norwegian and Icelandic operators are emerging as distinct demand nodes for polar-rated ice-class configurations.
Italy
Superyacht new-build demand from owners compressing build cycles drives specification for lightweight sliding door systems. CE marking under the EU Marine Equipment Directive shapes certification timelines for European-flagged vessels. Italian yards in Viareggio and Ancona are modularizing carbon fiber frame subassemblies across production programs to compress custom engineering hours.
Turkey
Expanding superyacht construction capacity and owner preference for integrated tender garage layouts accelerates shell door procurement. The country's national maritime regulator enforces ISO 12216 structural compliance for export-bound vessels. Istanbul and Yalova build centers are consolidating sourcing through captive supply agreements with German engineering houses, marginalizing independent fabricators.
Germany
Automated fiber placement capabilities and vacuum infusion expertise supply precision-molded geometries to Mediterranean and Scandinavian yards. REACH chemical regulations govern epoxy resin systems used in prepreg composite fabrication. Engineering clusters in Bremen and Hamburg are concentrating specialized labor for complex custom geometries that manual layup cannot replicate.
Norway
Polar-class expedition yacht orders from operators seeking ice-rated sealing geometry create distinct specification requirements. The country's national maritime authority enforces additional structural load standards for Arctic operating conditions. Bergen and Stavanger fabrication centers are developing reinforced door frames absent from standard Mediterranean specifications.
France
Service life extension programs in refit centers generate aftermarket shell door replacements bundled with climate system compliance work. The EU F-Gas Regulation on sealed system refrigerants triggers concurrent hull access upgrades. French Riviera yards in La Ciotat and Antibes are piloting sensor-embedded door frames for predictive maintenance contracts with classification societies.
Yacht Shell Doors Market Competitive Landscape
Global majors compete with regional champions across engineering specialization and certification depth. The vendor base stratifies between German precision fabricators, Mediterranean system integrators, and Nordic polar-class specialists. Three archetypes dominate: composite engineering houses with automated fiber placement capabilities, hydraulic system specialists serving high-cycle commercial applications, and vertically integrated fabricators controlling sealing hardware production. Capacity expansion and backward integration into CNC-machined components represent the dominant competitive moves.
Among German engineering houses, Fassmer GmbH & Co. KG exemplifies the complex custom geometry tier for expedition yacht applications. Cramm occupies a specialized position within high-cycle hydraulic system configurations. AdvanTec Marine anchors the backward integration archetype through in-house production of sealing hardware. These three represent distinct strategic postures rather than direct substitutes.
| Leading Market Players |
|---|
| Sea Power |
| Ocean Group |
| Fassmer GmbH & Co. KG |
| Cramm |
| SeaNet SA |
| Cen-Tex Marine |
| AdvanTec Marine |
| Houdini Marine Windows |
| Saajos Group |
| Others |
Value Network & Pricing Analysis
Captive supply agreements between Turkish build centers and German engineering houses anchor both procurement stability and pricing power for composite shell door systems serving Mediterranean superyacht yards. This integration pattern insulates specification authority from spot-market volatility while compressing margins for independent fabricators lacking classification society pre-approval.
Pricing Analysis
Epoxy resin and aerospace-grade carbon fiber prepreg pass through directly to quoted door assemblies, with Mediterranean shipyards absorbing input-cost spikes in fixed-price build contracts. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked composite systems from aluminum equivalents and glass-reinforced polymer alternatives. Cost compression in mid-market aluminum tiers is intensifying because Turkish yards consolidate volume through captive supply channels. Charter operators exhibit highest price sensitivity due to maintenance-interval predictability requirements, while private superyacht owners prioritize weight-reduction premiums for IMO-compliant efficiency gains.
Supply Chain Analysis
Composite technician scarcity in German and Dutch marine fabrication clusters constrains vacuum infusion and autoclave curing capacity for complex custom geometries. Supply concentrates in Italy, Turkey, and Germany, with raw material flows drawing from Japanese carbon fiber producers, Belgian epoxy resin suppliers, and Chinese sealing hardware manufacturers. Single-source vulnerability in aerospace-grade fiber supply creates exposure to export licensing disruptions. Distribution runs through shipyard procurement departments and specialized marine equipment distributors, with direct yard relationships fragmenting owner procurement patterns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
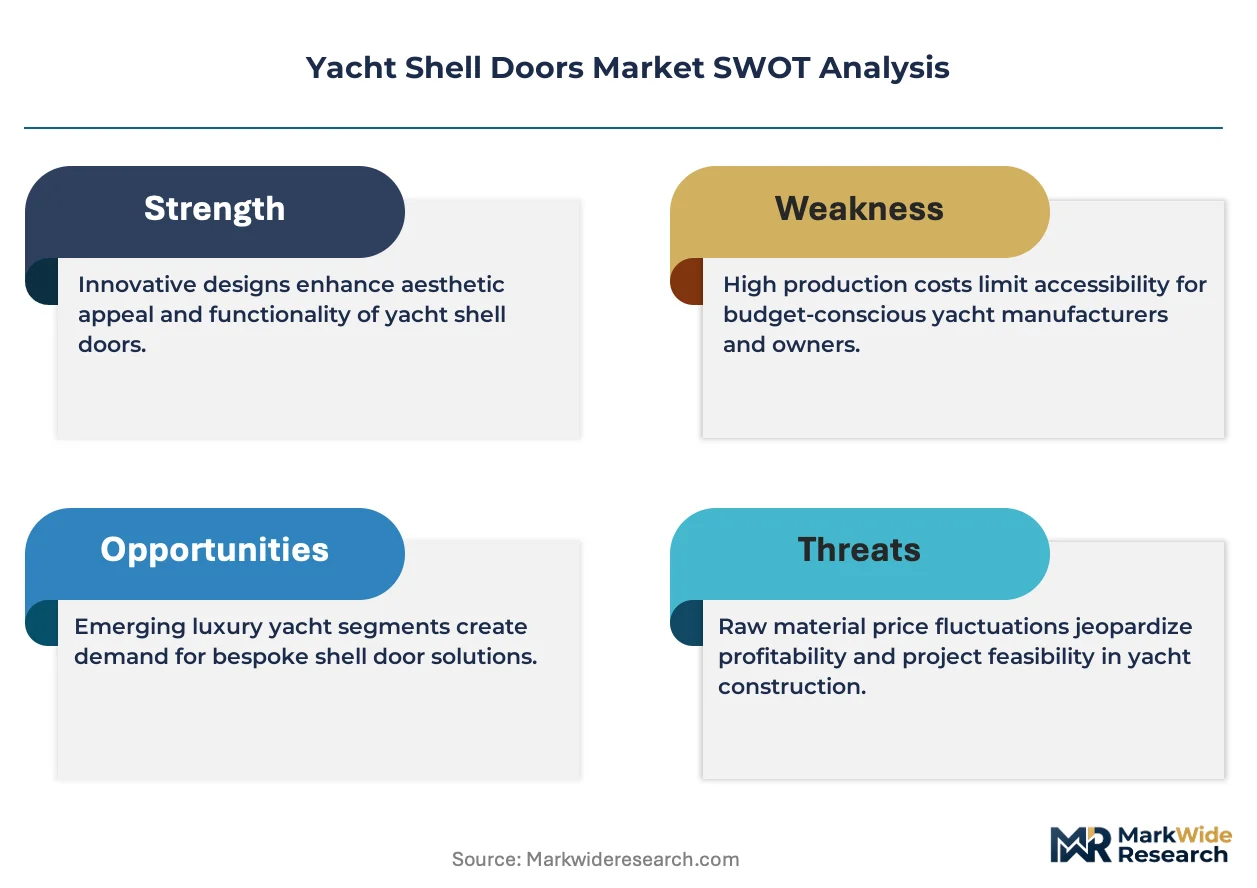
The yacht shell doors market functions as a regulatory compounder where EU Green Deal emissions-linked material standards and F-Gas Regulation retrofit mandates continuously refresh replacement demand across vessel lifecycles.
For Market Incumbents: Anchor competitive position through backward integration into CNC-machined sealing hardware and automated fiber placement capabilities that manual layup cannot replicate. Invest in classification society pre-approval for novel composite geometries before CE marking timeline compression extends further. Defend against emerging German-Turkish captive supply channels by establishing direct technical service presence in Italian and French refit centers. For New Entrants and Emerging Players: Launch via polar-class expedition yacht specialization targeting Norwegian and Icelandic operators seeking ice-rated sealing geometry absent from Mediterranean specifications. Target aftermarket retrofit channels in French and Spanish refit centers where service life extension programs bundle shell door replacements with climate system compliance work. Differentiate through sensor-embedded door frames for predictive maintenance contracts with classification societies. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap composite engineering houses with automated fiber placement capabilities because CE marking backlogs and Notified Body capacity constraints prevent rapid new entrant scaling. Monitor composite fire resistance rating evolution at classification societies as the inflection signal for composite penetration into larger passenger vessel classes above current tonnage thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sealing Hardware | In-house CNC-machined gasket production compresses lead times for CE-marked assemblies serving Italian yards. |
| Automated Fiber Placement Capacity | Precision-molded geometries from German engineering clusters displace manual layup for expedition yacht orders. |
| Polar-Class Certification Investment | Ice-rated sealing geometry unlocks Norwegian and Icelandic expedition vessel specifications outside Mediterranean competition. |
| Sensor-Embedded Door Frame Development | French classification society pilot programs create predictive maintenance contract opportunities in refit channels. |
| Captive Supply Agreement Expansion | Turkish build center consolidation marginalizes independent fabricators lacking ISO 12216 pre-approval status. |
Research Methodology
Coverage spans Mediterranean shipbuilding clusters, German engineering centers, and Nordic polar-class fabrication hubs, with primary inputs from each. The analysis combines structured interviews with superyacht procurement directors, shipyard technical managers, classification society surveyors, and composite fabrication specialists with secondary validation from EU Marine Equipment Directive filings, ISO 12216 certification databases, and customs trade records for carbon fiber prepreg imports. Bottom-up vessel order analysis triangulates against top-down shipyard capacity assessments.
Rate-of-change decomposition separates volume growth from value growth across the projection horizon. The analytical framework models shell door demand by product type, material grade, installation channel, and vessel size class, with CAGRs derived from shipyard orderbook trajectories and fleet aging patterns. Forecast inputs incorporate EU Green Deal implementation timelines and F-Gas Regulation retrofit incentive uptake curves.
Several conditions sit outside the modeled scope, including abrupt changes in CE marking processing timelines at Notified Bodies and unforeseen shifts in composite fire resistance classification rules. Forecasts reflect assumptions about continued Mediterranean shipbuilding concentration and stable aerospace-grade fiber supply availability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Military Marine Engine Market
Marine
Marine Shackle Market
Marine
Hydrofoil Market
Marine
Marine AIS Monitoring System Market
Marine
Pneumatic Marine Fender Market
Marine
Marine Lighting Market
Marine
Passenger Vessel Propeller Market
Marine
Sailboat Propellers Market
Marine
Marine Glass Market
Marine
Offshore AUV and ROV Market
Marine
Ship Rudders Market
Marine
Marine Electronics Market
Marine
Sailboat Market
Marine
Boat Console Market
Marine
Autonomous Ships Market
Marine
Marine Navigation System Market