
 Europe Marine Communication Systems Market | 2026-2036
Europe Marine Communication Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Marine Communication Systems Market Foresight
Software-defined satellite service layers is decoupling hardware ownership from connectivity contracts across European maritime fleets. Inmarsat plc leverages its L-band constellation to anchor long-haul cargo routes through the North Sea and Baltic corridors. KVH Industries, Inc. competes in the mini-VSAT segment with compact antenna systems purpose-built for mid-size commercial vessels. Rohde & Schwarz specializes in military-grade naval communication suites, sustaining dual-use technology pipelines that serve both defense and coast guard end users.
Europe marine communication systems encompass integrated radio, satellite, and digital networking equipment engineered to operate across VHF (156-174 MHz), MF/HF (1.6-30 MHz), and Ku/Ka-band satellite frequencies in salt-spray and vibration-intensive environments. These systems enable vessel-to-vessel, vessel-to-shore, and emergency distress signaling required under international maritime law. Satellite communication commands the dominant value share as fleet operators replace legacy SSB installations with always-on broadband links for route optimization and crew welfare. Cloud-based solutions represent the fastest-expanding technology segment, though analog VHF persists in small-craft and fishing fleets where capital constraints limit digital migration. Integrated systems capture concentrated margin pools by bundling AIS, GMDSS, and fleet management software into single-bridge architectures.
EU MDR and CE marking requirements shape hardware certification pathways for radio equipment sold across member states, while the F-Gas Regulation constrains cooling system choices in shore-based station infrastructure. EASA coordination with national maritime authorities harmonizes spectrum allocation for unmanned surface vessel trials now proliferating in North Sea test zones. ETSI standards for software-defined radio interoperability are tightening compliance burdens on smaller equipment vendors. Stakeholders must weigh the capital cost of integrated digital suites against fragmented upgrade cycles as SOLAS amendments and cybersecurity directives converge through the decade ahead.
Market Dynamics
Software-defined radio architectures are compressing hardware refresh cycles across European commercial fleets, forcing traditional equipment vendors to recalibrate service revenue models around connectivity subscriptions rather than terminal sales.
Growth Catalysts
- IMO SOLAS Chapter IV mandates:European flag states enforce GMDSS modernization deadlines that require satellite backup systems for all cargo vessels over 300 gross tonnage, tightening compliance windows through 2027.
- EU Green Deal maritime decarbonization:Shore power connectivity and voyage optimization software require real-time data links, pulling broadband satellite installations into vessel retrofit programs.
- North Sea offshore wind expansion:Service vessel operators in German and Danish waters demand redundant communication layers for crew transfer operations in congested sea lanes.
Market Restraints
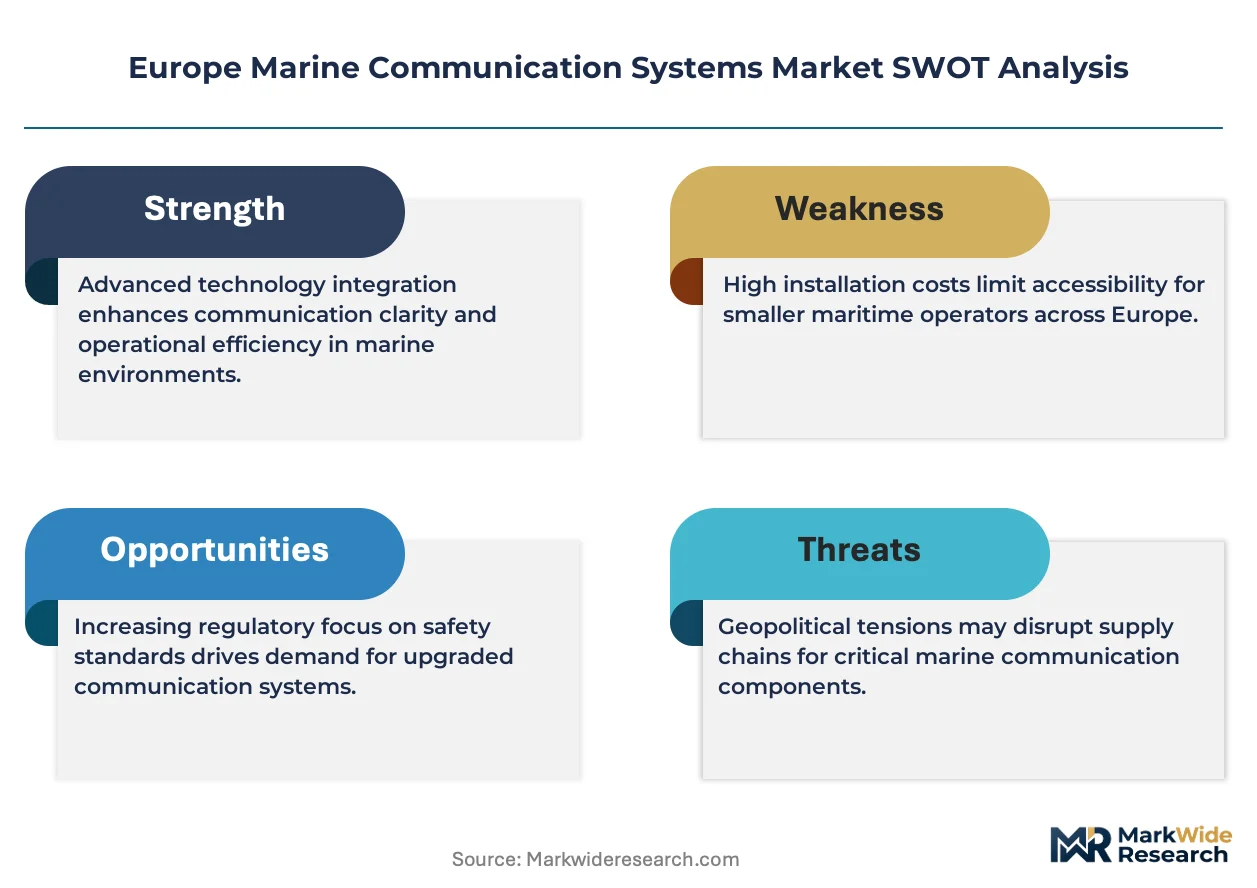
- Semiconductor supply concentration:RF front-end components for marine-grade transceivers depend on Taiwanese foundry capacity, exposing lead times to geopolitical friction.
- F-Gas Regulation cooling constraints:Shore station infrastructure faces refrigerant phase-down requirements that limit thermal management options for high-power transmitters.
- Ku-band spectrum congestion:Geostationary slot scarcity above European maritime corridors degrades link reliability during peak traffic windows.
Strategic Opportunities
- Polish and Romanian inland waterway modernization:Danube cargo operators remain underpenetrated by integrated bridge systems, presenting first-mover openings for bundled AIS-GMDSS suites.
- ETSI software-defined radio standardization:Harmonized interoperability testing reduces certification duplication costs for equipment vendors targeting multi-national fleets.
- Unmanned surface vessel trials:North Sea test zones in Norwegian and UK waters require dedicated C-band telemetry links that bypass congested commercial satellite pools.
Industry Challenges
- Cybersecurity directive compliance:IMO 2024 maritime cyber risk management guidelines impose network segmentation requirements that conflict with legacy analog VHF installations on aging coastal fleets.
- Multiband antenna integration:Bridge space constraints on mid-size commercial vessels complicate simultaneous L-band, Ku-band, and MF/HF hardware deployment without structural modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Marine Communication Systems Market |
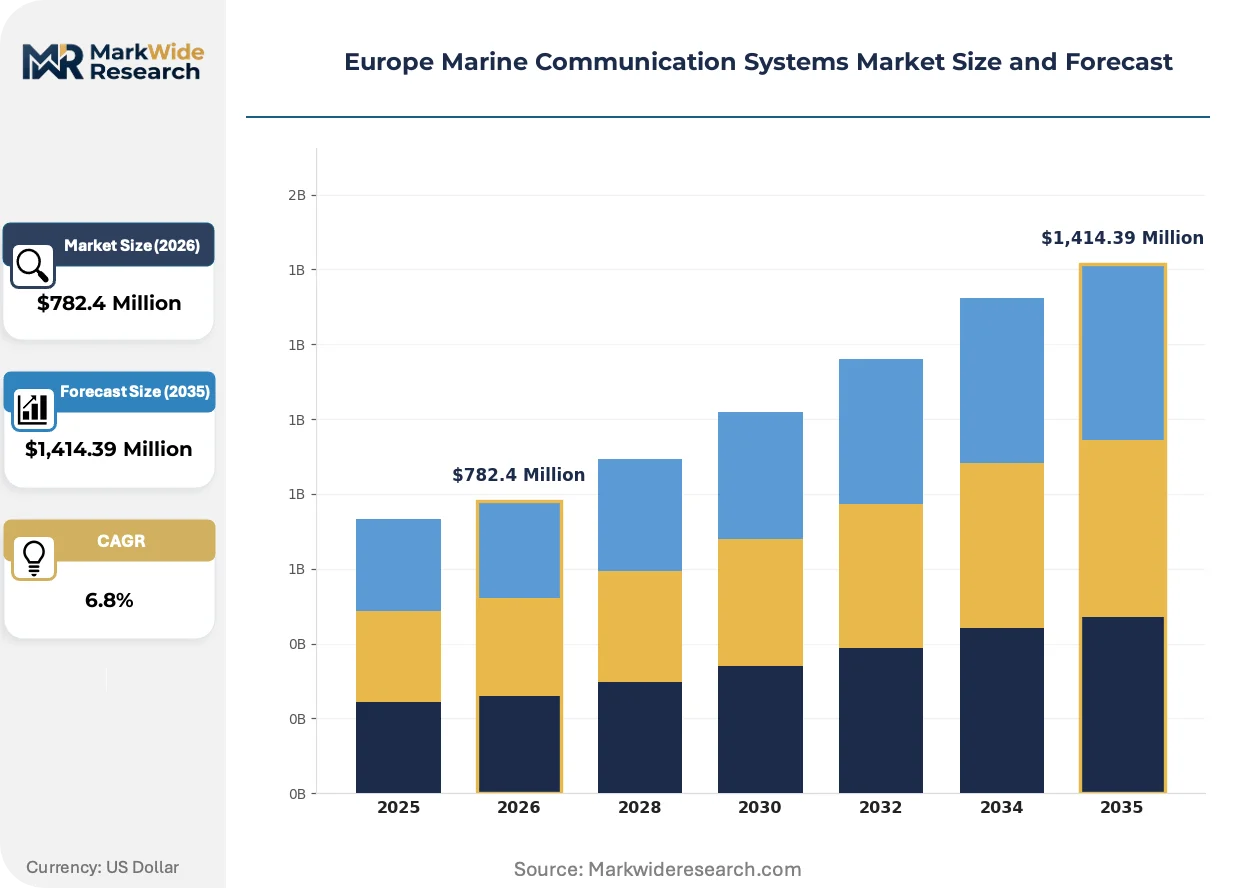
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $1,414.39 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: VHF Radios, SSB Radios, Satellite Communication, AIS Transponders Technology: Analog Communication, Digital Communication, Integrated Systems, Cloud-Based Solutions End User: Commercial Vessels, Recreational Boats, Government Services, Research Vessels Installation: Onboard Systems, Shore-Based Stations, Network Infrastructure, Wireless Devices |
| Companies Covered | Inmarsat plc, Iridium Communications Inc., KVH Industries, Inc., Cobham plc, Orbit Communications Systems Ltd., Leonardo S.p.A., Rohde & Schwarz, SAAB, FURUNO ELECTRIC CO., LTD., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Marine Communication Systems Market Shifts & Advancements
European maritime communication infrastructure is pivoting from hardware ownership to service-layer monetization, compressing traditional equipment margins while expanding recurring revenue pools for connectivity providers.
Flat-panel electronically steered arrays is overtaking parabolic dish architectures in commercial shipping applications. These solid-state terminals eliminate mechanical azimuth-elevation tracking, reducing maintenance burdens for container lines operating North Atlantic routes. The technology is overtaking legacy stabilized antennas in newbuild contracts, collapsing the historical premium commanded by mechanically stabilized systems.
EU MDR and CE marking convergence with ETSI software-defined radio standards is tightening type-approval pathways for radio equipment sold across member states. Manufacturers now face unified electromagnetic compatibility and safety testing protocols that previously fragmented across national notified bodies. German and French maritime authorities coordinate spectrum allocation for autonomous vessel trials, compressing licensing timelines for experimental installations.
Charter operators are unbundling communication hardware from vessel lease agreements, shifting connectivity procurement to voyage-specific service contracts. Mediterranean short-sea shipping lines now rent bandwidth by the nautical mile rather than owning depreciating terminal assets. This pattern concentrates most acutely in Greek and Italian ferry fleets where seasonal demand volatility rewards operational flexibility over capital commitment.
Europe Marine Communication Systems Market Segmentation
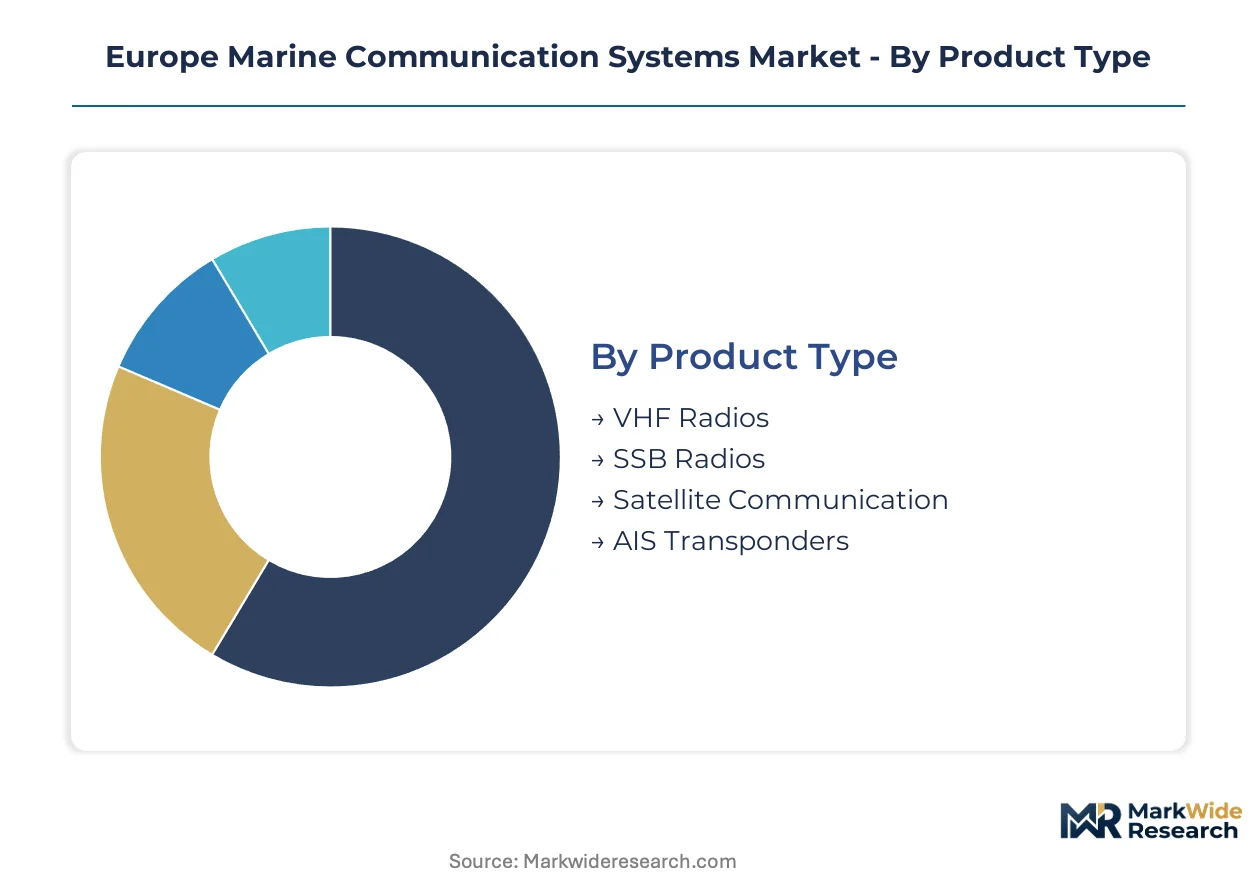
Marine communication systems fragment across four critical dimensions that determine procurement patterns, regulatory compliance burdens, and technology refresh cycles. Fleet operators weigh capital intensity against operational flexibility differently across each category, shaping vendor go-to-market strategies and service bundling approaches.
Product Type:
Satellite communication commands premium pricing while VHF radios dominate unit volumes across European maritime fleets.
- Satellite Communication:Ku/Ka-band and L-band terminals deliver always-on broadband for route optimization, crew welfare, and GMDSS compliance. Mediterranean container lines and North Sea offshore service vessels anchor demand as IMO SOLAS modernization deadlines tighten.
- VHF Radios:Analog 156-174 MHz equipment persists in coastal fishing fleets and small craft where capital constraints limit digital migration. German and French port authorities maintain extensive shore-based VHF networks for harbor traffic control.
- SSB Radios:MF/HF single-sideband installations serve as backup distress systems on legacy cargo vessels awaiting satellite retrofit.
- AIS Transponders:Automatic identification systems are mandated for vessels over 300 gross tonnage, with Class A units dominating commercial shipping and Class B penetrating recreational segments.
Mature deployment sits with VHF Radios. Newer deployment is concentrated in Satellite Communication.
Technology:
Hardware ownership models are collapsing as connectivity subscriptions displace terminal sales across European fleets.
- Cloud-Based Solutions:Software-defined service layers decouple vessel operators from hardware refresh cycles. Greek and Italian ferry operators now rent bandwidth by nautical mile rather than owning depreciating assets.
- Integrated Systems:Single-bridge architectures bundle AIS, GMDSS, and fleet management software. Nordic coastal patrol networks and German port modernization programs drive specification.
- Digital Communication:Software-defined radio architectures compress compliance testing burdens under converging EU MDR and ETSI standards.
- Analog Communication:Legacy installations persist where cybersecurity directive compliance conflicts with network segmentation requirements on aging coastal fleets.
Integrated Systems capture concentrated margin pools. Cloud-Based Solutions are climbing the fastest as charter operators unbundle hardware from lease agreements.
End User:
Procurement authority fragments between fleet managers, defense procurement offices, and research institution grant administrators.
- Commercial Vessels:Container lines, tanker operators, and bulk carriers drive satellite communication adoption. EU Green Deal decarbonization targets pull broadband installations into retrofit programs for shore power connectivity and voyage optimization.
- Government Services:Naval communication suites and coast guard networks sustain dual-use technology pipelines. Rohde & Schwarz and Thales anchor this segment with military-grade encrypted systems.
- Recreational Boats:Leisure craft demand compact VSAT terminals and portable VHF handhelds. Seasonal demand volatility in Mediterranean marinas rewards flexible service contracts over capital commitment.
- Research Vessels:Oceanographic institutes require redundant communication layers for Arctic and North Atlantic operations. C-band telemetry links for unmanned surface vessel trials are proliferating in Norwegian and UK test zones.
Commercial Vessels anchor revenue concentration. Research Vessels represent the steepest expansion trajectory as autonomous maritime experimentation accelerates.
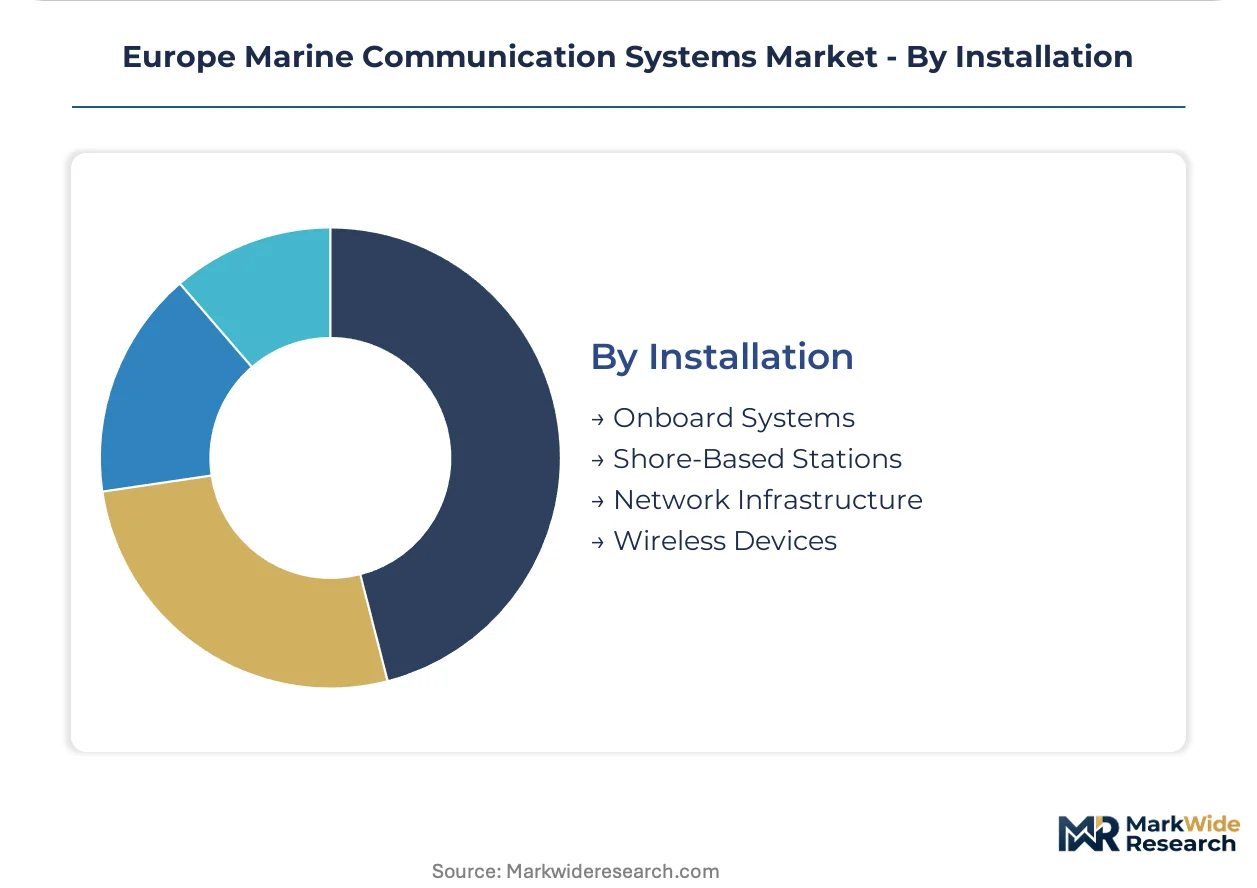
Installation:
Bridge space constraints and shore-side infrastructure aging create divergent upgrade cycles across deployment modes.
- Onboard Systems:Flat-panel electronically steered arrays are overtaking parabolic dish architectures. Solid-state terminals eliminate mechanical tracking, reducing maintenance burdens for North Atlantic container lines.
- Shore-Based Stations:Port traffic control centers and coastal monitoring networks face F-Gas Regulation constraints on cooling systems for high-power transmitters.
- Network Infrastructure:Undersea cable landing stations and satellite ground segments in the UK, Norway, and France handle traffic aggregation for offshore wind service corridors.
- Wireless Devices:Portable VHF handhelds and satellite messengers serve crew transfer operations and emergency backup roles.
Shore-Based Stations carry deferred maintenance backlogs. Onboard Systems are gaining share fastest as newbuild contracts specify integrated digital bridge architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of marine communication terminals concentrates in Northern European industrial corridors, while consumption spreads across Mediterranean shipping lanes and Baltic offshore zones. The EU's regulatory harmonization under ETSI standards compresses cross-border certification costs for equipment vendors. Fleet operators in coastal economies drive differentiated demand patterns based on vessel age profiles and SOLAS compliance deadlines.
Germany
Port modernization programs in Hamburg and Bremerhaven anchor terminal demand for integrated bridge systems. The Federal Maritime and Hydrographic Agency enforces strict electromagnetic compatibility standards under EU MDR frameworks. Bavaria-based equipment fabricators supply military-grade naval communication suites to NATO-aligned coast guard networks.
United Kingdom
North Sea offshore wind service corridors require redundant C-band telemetry links for crew transfer vessels. The Maritime and Coastguard Agency coordinates spectrum allocation for autonomous surface vessel trials in Scottish waters. London satellite ground stations aggregate traffic for trans-Atlantic container routes.
France
Mediterranean short-sea ferry operators in Marseille and Toulon adopt bandwidth-by-nautical-mile service contracts. ANSM and national maritime authorities harmonize software-defined radio licensing for cross-border fleet operations. Brittany fishing cooperatives maintain analog VHF networks where capital constraints limit digital migration.
Netherlands
Rotterdam port traffic control centers face F-Gas Regulation constraints on cooling systems for high-power shore transmitters. Eindhoven-region semiconductor fabricators supply RF front-end components for Ku-band marine terminals. Dutch inland waterway operators on the Rhine corridor trial integrated AIS-GMDSS bundles.
Norway
Arctic research vessels and offshore supply operators demand L-band backup systems for high-latitude satellite connectivity. The Norwegian Maritime Authority licenses experimental frequency blocks for unmanned surface vessel testing in North Sea zones. Stavanger-based fleet managers specify flat-panel electronically steered arrays for newbuild contracts.
Europe Marine Communication Systems Market Competitive Landscape
Top-tier vendors anchor satellite constellation and integrated system provision, while specialized equipment fabricators occupy mid-tier niches in radio hardware and military-grade encryption. The vendor base stratifies across three functional layers: connectivity service providers owning orbital assets, bridge system integrators bundling multi-band terminals, and component specialists supplying RF subsystems. Two dominant competitive moves are reshaping positioning: service-layer monetization displacing terminal sales, and software-defined architectures compressing hardware refresh cycles.
Within the connectivity service tier, Inmarsat plc and Iridium Communications Inc. represent contrasting orbital strategies—geostationary L-band constellations versus low-Earth-orbit mesh networks. KVH Industries, Inc. exemplifies the compact antenna specialist archetype targeting mid-size commercial vessels with mini-VSAT terminals. Rohde & Schwarz anchors the dual-use technology pipeline, supplying encrypted naval communication suites that cascade into coast guard applications.
| Leading Market Players |
|---|
| Inmarsat plc |
| Iridium Communications Inc. |
| KVH Industries, Inc. |
| Cobham plc |
| Orbit Communications Systems Ltd. |
| Leonardo S.p.A. |
| Rohde & Schwarz |
| SAAB |
| FURUNO ELECTRIC CO., LTD. |
| Others |
Supply & Pricing Matrix
RF front-end semiconductor costs from Taiwanese foundries cascade through three distinct pricing tiers for European maritime operators, with military-grade encrypted suites absorbing premium markups while coastal fishing fleets face capital-constrained analog VHF economics.
Pricing Analysis
Price erosion across mid-size commercial vessel segments traces to charter operators unbundling hardware from lease agreements and shifting to bandwidth-by-nautical-mile subscriptions. Pricing stratifies across integrated digital bridge architectures, standalone satellite terminals, and legacy analog equipment tiers. Certification under EU MDR and ETSI software-defined radio standards commands measurable premiums over non-compliant alternatives. Coastal fishing cooperatives in Brittany and Mediterranean small-craft operators exhibit acute price sensitivity, while German port modernization programs and Nordic coastal patrol networks prioritize performance over procurement cost.
Supply Chain Analysis
EU local-content rules under defense procurement directives reshape sourcing for military-grade naval communication suites, pressuring vendors toward European fabrication of sensitive encryption subsystems. RF front-end components draw from Taiwanese foundry capacity, German precision engineering clusters, and Dutch semiconductor fabrication in Eindhoven. Gallium nitride power amplifiers, ceramic substrate materials, and marine-grade aluminum antenna housings constitute critical input dependencies. Single-source vulnerability concentrates in Taiwanese wafer fabrication for Ku-band transceiver chipsets. Distribution runs through specialized maritime electronics distributors serving shipyards in Hamburg, Rotterdam, and Marseille, with direct OEM relationships dominating naval procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where satellite constellation operators pursue downstream antenna manufacturing control, while hardware specialists seek upstream service-layer revenue through connectivity subscriptions.
For Market Incumbents: Cement constellation-based service moats by acquiring flat-panel electronically steered array manufacturers, neutralizing the threat of antenna commoditization. Deepen backward integration into RF semiconductor sourcing to buffer Taiwanese foundry concentration risk. Prioritize certification investments under converging EU MDR and ETSI standards to raise compliance barriers for mid-tier competitors. For New Entrants and Emerging Players: Polish and Romanian inland waterway operators on the Danube corridor represent an underserved buyer archetype with minimal integrated bridge penetration. Target first-mover positioning in C-band telemetry links for North Sea unmanned surface vessel trials, where experimental licensing compresses incumbent response timelines. Pursue bundled AIS-GMDSS suite offerings with localized service partnerships rather than direct terminal sales. For Investors and Strategic Acquirers: Distressed-cycle entries favor dual-use technology specialists with military-grade encryption pipelines and coast guard contract backlogs in German and French maritime authorities. Long-term viability hinges on software-defined radio architectures that compress hardware refresh cycles into recurring service revenue. Monitor EASA coordination with national maritime authorities on autonomous vessel spectrum allocation as the inflection signal for experimental installation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Flat-Panel Antenna Manufacturing Integration | Captures margin pools collapsing from mechanically stabilized parabolic systems across North Atlantic container routes. |
| Software-Defined Radio Certification Investment | Secures type-approval advantages under converging EU MDR and ETSI electromagnetic compatibility protocols. |
| Danube Corridor Distribution Partnership | Establishes channel presence ahead of Polish and Romanian inland waterway modernization programs. |
| C-Band Telemetry Experimental Licensing | Positions for Norwegian and UK unmanned surface vessel trial infrastructure requirements. |
| Connectivity Subscription Service Launch | Replicates Greek and Italian ferry operator bandwidth-by-nautical-mile models across Mediterranean short-sea fleets. |
Research Methodology
Multi-period observation of satellite terminal deployment rates, SOLAS compliance deadline progressions, and port modernization budget allocations anchored the trend analysis, supplemented by interviews with fleet operations directors at Mediterranean container lines, procurement leads at German shipyards, regulatory affairs officers at national maritime authorities, and technical directors at coastal patrol networks. Secondary validation drew from IMO SOLAS amendment documentation, EU MDR and ETSI standard publications, F-Gas Regulation implementation guidance, and customs trade data for marine electronics imports. Bottom-up vessel fleet segmentation triangulated against top-down connectivity service provider revenue disclosures.
Segment-weighting approaches distributed value projections across satellite communication, VHF radio, and integrated system product categories, further disaggregated by commercial vessel, government service, and recreational end-use segments. Technology deployment models differentiated cloud-based solutions, integrated systems, and analog legacy installations. CAGRs were derived from install-base replacement cycles, regulatory compliance windows, and Green Deal decarbonization retrofit timelines. Forecast inputs incorporated North Sea offshore wind service vessel demand curves and autonomous maritime experimentation licensing trajectories.
Revisions become necessary when Taiwanese foundry capacity disruptions, EU cybersecurity directive enforcement escalations, or Ku-band spectrum congestion mitigation measures materialize outside baseline assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Strip Market
Marine
Ballast Water Management Market
Marine
Marine Engine Cooling Systems Market
Marine
Marine Propeller Market
Marine
Marine Chronometers Market
Marine
Marine Exhaust Systems Market
Marine
Marine Gas Oil Market
Marine
Marine Beacon Market
Marine
Marine Fender Systems Market
Marine
Marine Fin Stabilizer Market
Marine
Offshore Autonomous Underwater Vehicle (AUV) Market
Marine
Passenger Vessel Propeller Market
Marine
Submarine Propulsion Systems Market
Marine
Sailboat Market
Marine
Marine Filter Market
Marine
Ship/Boat Keel Market