
 High-End Lighting Market | 2026-2036
High-End Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
High-End Lighting Market Intelligence
Buyer concentration among luxury hotel chains and premium retail flagships is consolidating, with procurement committees now favoring single-source lighting partners for global rollouts. Signify leverages its Interact connected lighting platform to secure multi-property contracts, while Acuity Brands sustains dominance in North American institutional segments through its Holophane and Lithonia specification lines. OSRAM competes on component-level LED engine supply, selling to third-party fixture houses that lack in-house photonics capabilities.
High-end lighting comprises architecturally significant luminaires engineered for superior color rendering, precise beam control, and extended operational lifespan, typically employing premium LED COB arrays, hand-finished metalwork, and proprietary optical systems designed for spaces where visual atmosphere directly affects commercial outcomes. LED technology anchors volume across all application tiers, though OLED panels are gaining traction in ultra-premium residential and gallery environments where surface-area glow and minimal heat emission justify cost premiums. Chandeliers and wall sconces occupy the deepest margin pools, as artisanal metalwork and limited production runs sustain pricing power that commodity fixture categories cannot replicate.
The US DOE maintains escalating minimum efficacy requirements under amended energy conservation standards, while the EU Ecodesign Directive and REACH chemical compliance frameworks restrict hazardous substances in luminaire finishes and electronics. China's GB standards for LED performance and the National Medical Products Administration's oversight of circadian lighting claims in healthcare settings further fragment certification burdens. Stakeholders must monitor regulatory divergence between energy-efficiency mandates and emerging human-centric lighting standards that prioritize biological impact over pure lumen-per-watt metrics.
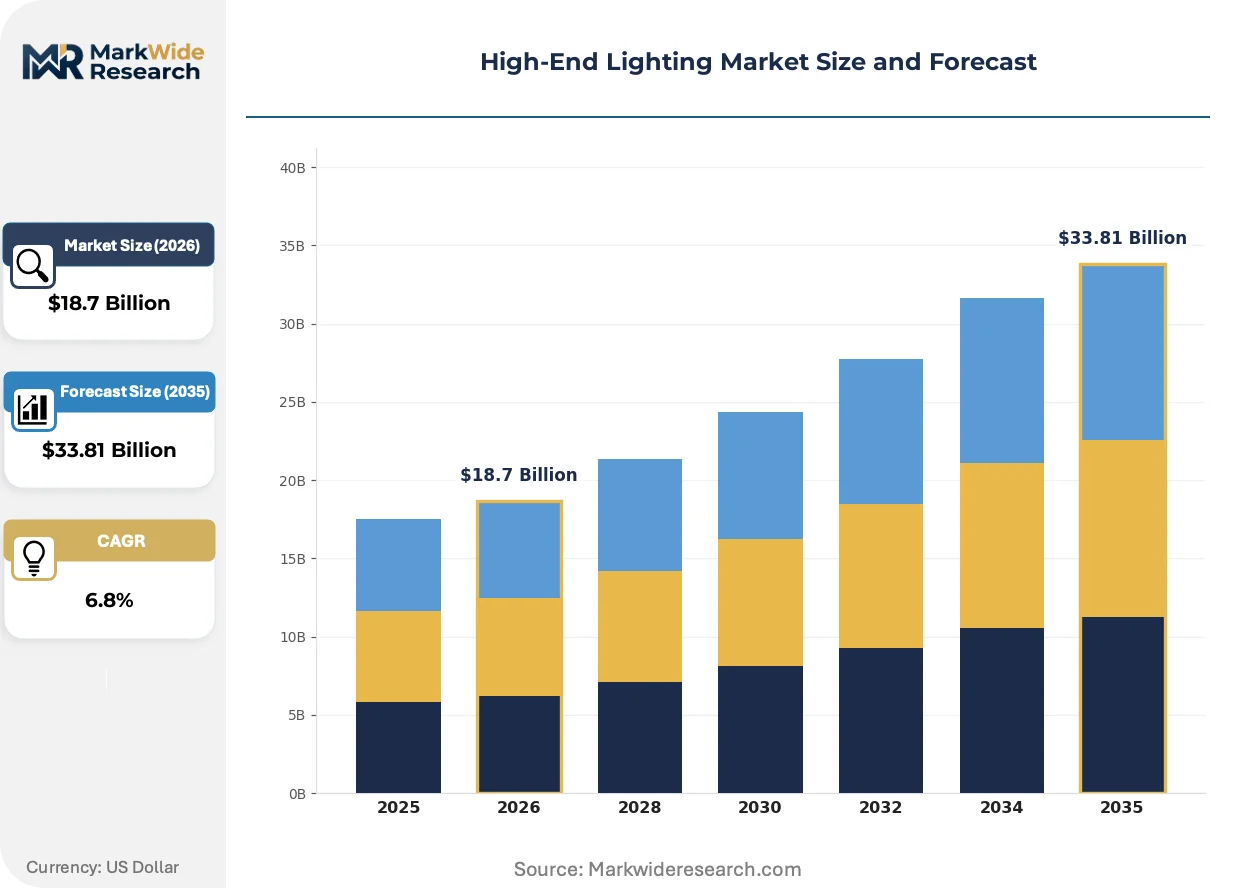
Market Dynamics
Buyer consolidation among luxury hotel chains and premium retail flagships is compressing vendor relationships toward single-source lighting partners, while tightening EU Ecodesign and US DOE efficiency mandates force simultaneous performance upgrades and compliance investments.
Growth Catalysts
- Hospitality Procurement Consolidation:Global hotel operators in Dubai and Milan are expanding custom fixture programs that bundle specification, installation, and maintenance into multi-property contracts.
- EU Ecodesign Tightening:Amended efficiency thresholds under the Ecodesign Directive are accelerating replacement cycles for legacy luminaires in commercial fit-outs across Germany, France, and Italy.
- OLED Surface Glow Technology:Ultra-premium residential and gallery environments are adopting OLED panels for minimal heat emission and uniform surface-area illumination that LED arrays cannot replicate.
Market Restraints
- Premium Input Cost Volatility:Hand-finished brass and copper components face price instability from concentrated Chilean and Peruvian mining supply.
- Photonics Capability Concentration:Third-party fixture houses remain dependent on external LED COB engine suppliers for proprietary optical systems, creating margin capture asymmetry.
- REACH Chemical Compliance:Restrictions on hazardous substances in luminaire finishes and electronics impose reformulation costs and supply qualification delays.
Strategic Opportunities
- India Luxury Retail Pipeline:Five-star hotel and flagship retail fit-outs in Mumbai and Delhi present underpenetrated demand for architecturally significant fixtures.
- Connected Lighting Convergence:Integration of IoT sensors with tunable white LED systems enables circadian and occupancy-responsive installations in healthcare and workplace verticals.
- US IRA Efficiency Incentives:Commercial building tax deductions for high-efficacy retrofits are redirecting capital toward premium LED specification in institutional segments.
Industry Challenges
- Photometric Talent Scarcity:Shortage of lighting designers capable of integrating human-centric and circadian specifications into hospitality and healthcare projects.
- Multi-Jurisdiction Certification Burden:Divergent GB standards in China, BIS requirements in India, and FDA-equivalent circadian claims oversight fragment product qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-End Lighting Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chandeliers, Wall Sconces, Table Lamps, Floor Lamps Technology: LED, OLED, Fluorescent, Incandescent Application: Residential, Commercial, Institutional, Hospitality End User: Homeowners, Designers, Contractors, Architects |
| Companies Covered | Signify, OSRAM, Acuity Brands, Philips, Cree Lighting, Fagerhult, Zumtobel, Louis Poulsen, Flos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-End Lighting Market Strategic Shifts & Innovations
Connected intelligence and biological impact metrics are displacing pure efficacy as the primary specification criteria, while artisanal production methods compete with automated precision manufacturing for margin capture in chandelier and sconce categories.
Tunable white LED systems with embedded sensor networks is integrating circadian rhythm programming into hospitality and healthcare environments. Marriott and Hyatt procurement committees are mandating human-centric specifications for new-build properties. This convergence is integrating lighting controls with building management systems, compressing the addressable market for standalone fixture vendors lacking software capabilities.
REACH and RoHS amendments are restricting cadmium and lead content in decorative metal finishes and driver electronics. Manufacturers serving EU markets must reformulate plating chemistries and resubmit technical documentation. Italian chandelier producers and German industrial fixture houses face the steepest compliance recertification burdens given their reliance on heritage finishing techniques.
Specification authority is migrating from individual architects toward centralized procurement committees at hospitality chains and retail flagships. Boutique lighting studios in Milan and Brooklyn are losing direct client relationships to approved vendor lists managed by corporate sustainability officers. This concentration is most visible in Dubai and Singapore, where sovereign wealth-backed hotel developments require single-source accountability across entire property portfolios.
High-End Lighting Market Segmentation
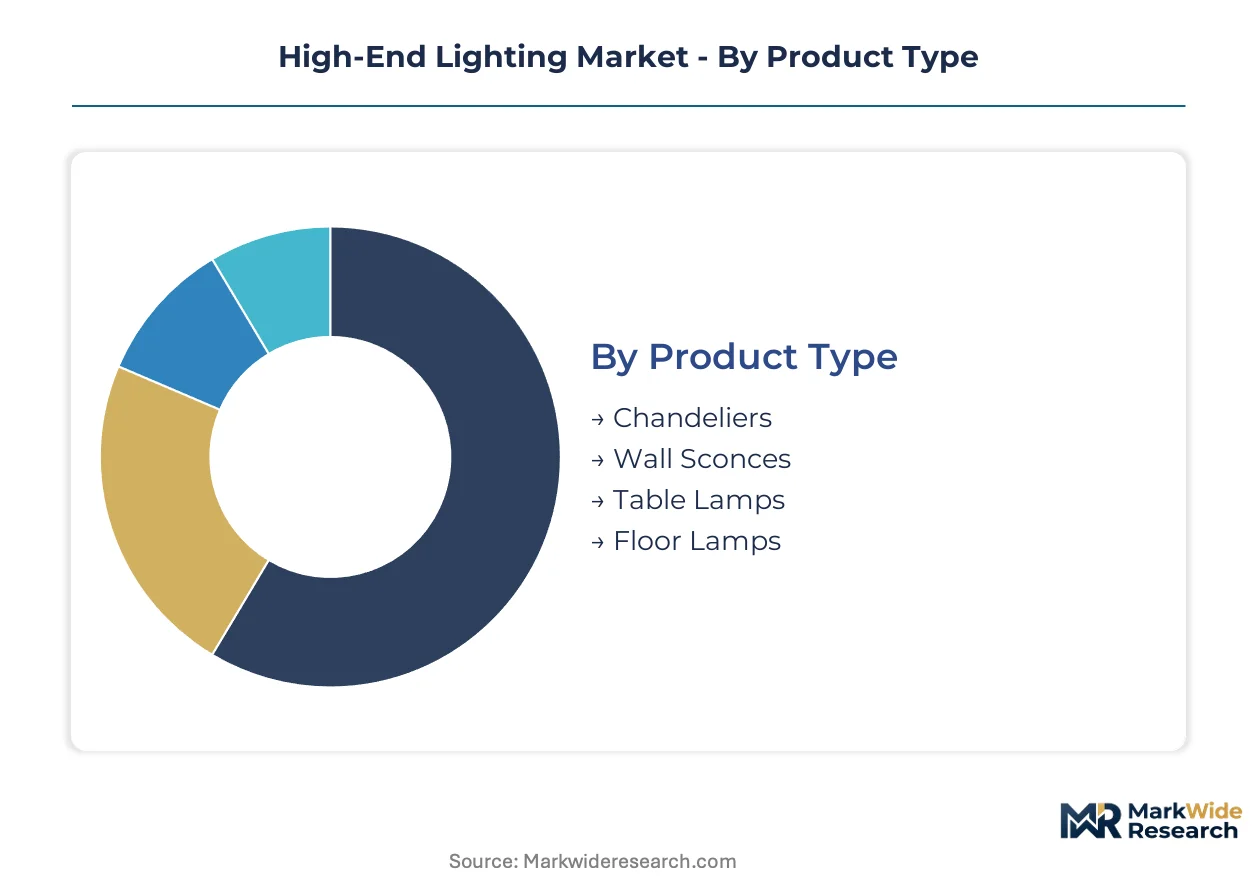
High-end lighting procurement splits sharply between volume-driven LED specification and artisanal categories where hand-finishing sustains margin premiums. Segmentation reveals how technology convergence and buyer consolidation reshape competitive positioning across fixture categories and specification channels.
Product Type:
Volume concentrates in LED-based categories with standardized optical systems, while premium margin pools cluster around metalwork-intensive fixtures requiring artisanal production.
- Chandeliers:Multi-arm suspended fixtures employing hand-finished brass, bronze, or crystal assemblies with proprietary LED COB integration. Demand concentrates in Dubai and Milan hospitality developments where sovereign wealth-backed hotel operators mandate statement pieces for lobbies and ballrooms. REACH chemical compliance on decorative metal finishes drives reformulation costs for heritage European producers.
- Wall Sconces:Surface-mounted luminaires combining precise beam control with architectural metalwork, often specified in matched programs across entire property portfolios. Procurement committees at Marriott and Hyatt are consolidating vendor relationships toward single-source partners capable of global rollout consistency.
- Table Lamps:Portable accent fixtures with premium LED engines and hand-finished bases, serving ultra-premium residential and gallery environments where surface-area glow requirements favor tunable white systems.
- Floor Lamps:Freestanding architectural elements integrating OLED panels in ultra-premium segments for minimal heat emission, though LED arrays dominate commercial specification.
Today's leader: Chandeliers. Tomorrow's challenger: Wall Sconces.
Technology:
LED anchors volume across all tiers, while emerging technologies compete on biological impact metrics rather than pure lumen-per-watt performance.
- LED:Solid-state semiconductor arrays delivering superior color rendering and extended operational lifespan through premium COB configurations. US DOE escalating minimum efficacy requirements and EU Ecodesign tightening force simultaneous performance upgrades and compliance investments across commercial fit-outs.
- OLED:Organic electroluminescent panels providing uniform surface-area illumination with minimal heat emission. Gallery and ultra-premium residential adoption in Germany and France justifies cost premiums where circadian specifications prioritize biological impact.
- Fluorescent:Legacy gas-discharge systems facing accelerated replacement cycles under amended efficiency mandates, now relegated to cost-sensitive institutional retrofits.
- Incandescent:Thermal radiation sources with superior color rendering but poor efficacy, surviving only in heritage restoration and decorative applications exempt from strict efficiency thresholds.
LED commands present volume. OLED gains share fastest in premium niches.
Application:
Buyer consolidation among hospitality chains and retail flagships compresses vendor relationships, while healthcare and workplace verticals drive connected lighting convergence.
- Residential:Ultra-premium single-family and gallery environments where OLED surface glow and artisanal metalwork justify cost premiums. Brooklyn and Milan boutique studios face eroding direct client relationships as specification authority migrates to approved vendor lists.
- Commercial:Workplace and retail fit-outs demanding tunable white LED systems with embedded IoT sensor networks for circadian and occupancy-responsive installations.
- Institutional:Healthcare and educational facilities where China's NMPA oversight of circadian lighting claims and US IRA efficiency incentives redirect capital toward high-efficacy retrofits.
- Hospitality:Five-star hotel developments in Mumbai and Delhi presenting underpenetrated demand, with Dubai operators expanding custom fixture programs bundling specification, installation, and maintenance.
Hospitality drives current procurement consolidation. Healthcare offers the steepest expansion trajectory for connected systems.
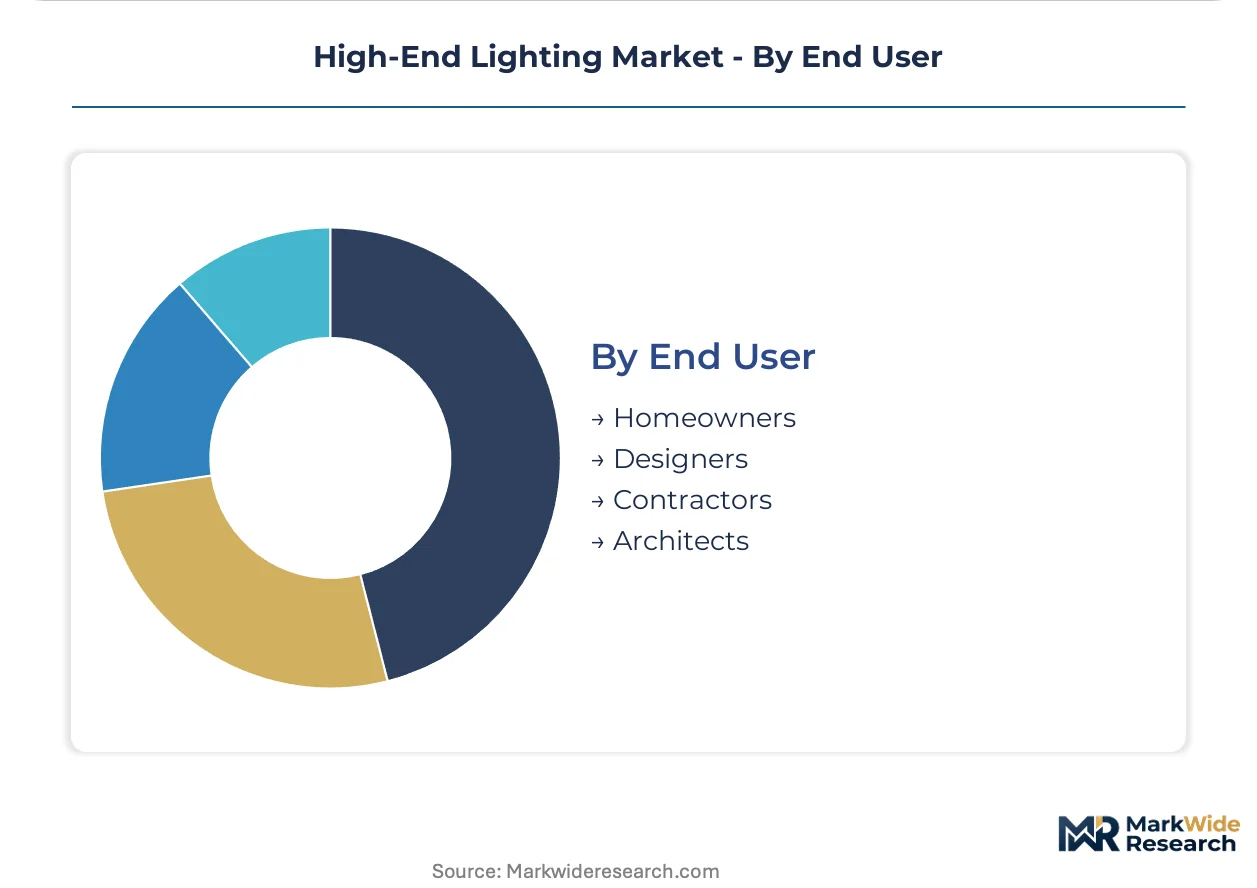
End User:
Specification authority is migrating from individual practitioners toward centralized procurement committees, fragmenting traditional channel relationships.
- Homeowners:Ultra-high-net-worth individuals commissioning bespoke fixtures through designer intermediaries, increasingly influenced by sustainability credentials and circadian performance claims.
- Designers:Lighting design studios facing capability scarcity in human-centric and circadian specifications, with talent concentrated in Milan, Brooklyn, and Singapore clusters.
- Contractors:Installation and maintenance providers bundling services into multi-property contracts, favored by procurement committees seeking single-source accountability.
- Architects:Specification professionals losing direct vendor relationships to corporate sustainability officers managing approved vendor lists for global hotel chains and retail flagships.
Contractors capture growing procurement influence. Designers face compressed margin pressure from committee consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates premium fixture engineering while the UAE commands hospitality procurement scale, each anchoring distinct value pools in the high-end lighting supply chain.
United States
Commercial building retrofits and institutional healthcare projects drive specification volume. The US DOE maintains escalating minimum efficacy requirements under amended energy conservation standards. New York and Los Angeles clusters concentrate specification authority among procurement committees managing approved vendor lists for national rollouts.
Germany
Industrial fixture engineering and gallery-grade OLED integration anchor premium production. ECHA REACH restrictions on hazardous substances in luminaire finishes impose reformulation costs on heritage metalwork producers. The Ruhr and Bavaria industrial corridors host precision optics manufacturers supplying LED COB engines to third-party fixture houses.
China
Luxury retail fit-outs and five-star hotel developments in Shanghai and Shenzhen concentrate the fastest project pipelines. GB standards for LED performance and NMPA oversight of circadian lighting claims fragment certification burdens for healthcare-targeted products. The Yangtze River Delta cluster dominates component-level LED engine manufacturing for export markets.
India
Five-star hotel and flagship retail fit-outs in Mumbai and Delhi present underpenetrated demand for architecturally significant fixtures. BIS requirements for electrical safety and performance create qualification barriers for imported luminaires. The Maharashtra and Karnataka industrial belts are developing domestic assembly capacity for premium hospitality programs.
Italy
Artisanal chandelier production and heritage metalwork sustain margin premiums in the decorative fixture segment. EU Ecodesign Directive amendments accelerate replacement cycles for legacy luminaires in commercial fit-outs. The Milan design district concentrates boutique lighting studios facing eroding direct client relationships as procurement authority migrates to corporate committees.
High-End Lighting Market Key Industry Players
European producers anchor the artisanal tier; North American specialists hold institutional and connected lighting capabilities. The vendor base splits between consolidated multinational platforms with software-integrated portfolios and fragmented boutique fabricators defending margin through limited production runs. Three archetypes dominate: full-stack connected lighting platforms, component-level LED engine suppliers, and artisanal metalwork houses. Competitive moves center on M&A to acquire photonics capabilities and strategic partnerships to bundle installation and maintenance services.
Within the connected platform tier, Signify represents the convergence of hardware specification with software-defined building management integration. Among component suppliers, OSRAM and Cree Lighting exemplify the LED COB engine specialists that third-party fixture houses depend upon for proprietary optical systems. These three names illustrate how capability concentration in photonics and controls is compressing standalone fixture vendors toward partnership or obsolescence.
| Leading Market Players |
|---|
| Signify |
| OSRAM |
| Acuity Brands |
| Philips |
| Cree Lighting |
| Fagerhult |
| Zumtobel |
| Louis Poulsen |
| Flos |
| Others |
Cost & Logistics Intelligence
Photonics engineers concentrated in Germany's Ruhr corridor and Bavaria command wage premiums that compress margins for European fixture houses, while assembly labor arbitrage in China's Yangtze River Delta sustains pricing-tier spreads between artisanal and volume LED categories.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for LED COB engines and compressing margins for mid-tier fixture vendors. Three-tier pricing structure across premium, standard, and economy levels differentiates hand-finished brass chandeliers from volume hospitality specification, with REACH compliance costs and brand heritage anchoring premium tiers. Cost compression in standard-tier LED specification is intensifying because Yangtze Delta manufacturers are scaling automated COB production. Hospitality procurement committees demonstrate least price sensitivity for statement chandeliers, while institutional retrofit buyers prioritize per-lumen economics.
Supply Chain Analysis
Workforce availability constraints in German precision optics manufacturing and Italian metalwork finishing limit scalable artisanal output. Supply concentrates in China for LED COB engines, Germany for optical system design, and Italy for hand-finished decorative metalwork. Raw material dependencies include Chilean copper for conductive components, Peruvian silver for plating chemistries, and rare-earth phosphors for color rendering. Single-source vulnerability runs through concentrated LED die manufacturing in the Yangtze Delta. Distribution runs through specification committees at hospitality chains rather than traditional architectural channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Ecodesign tightening against US IRA efficiency incentives creates a regulatory-arbitrage window for vendors capable of dual-certification production, with German engineering costs offset by Chinese assembly scale.
For Market Incumbents: To counter software-integrated connected lighting platforms, heritage European fixture houses should deepen in-house production of LED COB optical systems and secure captive supply of REACH-compliant plating chemistries. Capacity addition in India's Maharashtra industrial belt offers labor-cost relief for hospitality program manufacturing. For New Entrants and Emerging Players: The mid-tier price-point gap between Milan artisanal studios and volume Chinese specification presents white-space opportunity in Indian five-star hotel fit-outs and Middle Eastern custom fixture programs. Healthcare circadian lighting in Germany and France offers penetrable demand for tunable white systems with NMPA-equivalent claims documentation. Go-to-market through contractor bundling partnerships bypasses entrenched specification committee gatekeeping. For Investors and Strategic Acquirers: Connected building management platforms are the most active acquirer in this space, targeting photonics capabilities and IoT sensor integration. Long-term viability hinges on software-defined lighting control rather than standalone fixture manufacturing. Acquisition target archetype: boutique studios with circadian specification expertise and approved vendor list status at Marriott or Hyatt. Signal to watch: procurement committee mandates for human-centric lighting in new-build hospitality properties.| Strategic Initiative | Industry Significance |
|---|---|
| Photonics Capability Acquisition | OSRAM and Cree Lighting engine supply agreements anchor third-party fixture house competitiveness. |
| REACH Compliance Reformulation | Italian chandelier producers face steepest recertification burdens from cadmium and lead restrictions. |
| Connected Platform Integration | Signify's Interact bundling compresses addressable market for standalone fixture vendors lacking software. |
| India Manufacturing Scale-Up | Maharashtra and Karnataka assembly capacity targets hospitality procurement consolidation in Mumbai and Delhi. |
| Circadian Specification Certification | China's NMPA oversight and Germany's gallery adoption create dual-path validation for biological impact claims. |
Research Approach
Direct dialogue with lighting design studio principals, hospitality procurement committee directors, LED COB engineering leads, and contractor program managers grounded qualitative findings in operational reality. Secondary validation drew from US DOE efficacy standard amendments, EU Ecodesign Directive technical documentation, China's GB LED performance standards, and hospitality chain approved vendor list disclosures. Bottom-up fixture shipment analysis and top-down construction spending triangulation reconciled volume estimates.
Segment-level outputs across the analysis window reflect modeled splits by product type, technology platform, application vertical, and end-user procurement channel. CAGRs derive from regression against hospitality construction pipelines, retail fit-out cycles, and efficiency mandate replacement schedules. Industry-specific inputs include sovereign wealth-backed hotel development announcements in Dubai and Singapore, and circadian lighting specification mandates at Marriott and Hyatt.
Caveats apply where regulatory divergence between EU Ecodesign and US DOE trajectories, or NMPA circadian claim enforcement in China, could materially shift the outlook. Practitioners should monitor procurement committee vendor consolidation announcements and REACH amendment implementation timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lighting
Asia-Pacific Hazardous Lighting Market
Lighting
Industrial Lighting Lifecycle Services Market
Lighting
Flexible Lighting Foils Market
Lighting
Miniature Bulbs Market
Lighting
Circadian Lighting Market
Lighting
Fluorescent Lighting Market
Lighting
US Indoor LED Lighting Market
Lighting
Global Flame Proof Lighting Market
Lighting
Specialty Lighting Market
Lighting
Global Plasma Lamp Market
Lighting
Global Commercial Lighting Market
Lighting
Xenon Headlights Market
Lighting
North America Street Lighting Market
Lighting
North America Outdoor Lighting Market
Lighting
COB Photo Light Market
Lighting
Smart Lamp Market