
 Digital X-Ray Technology Market | 2026-2036
Digital X-Ray Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Digital X-Ray Technology Market Insights
Outpatient diagnostic chains is collapsing the historical hospital-centric procurement pattern for digital x-ray suites. Siemens Healthineers leverages its installed base in fluoroscopy to defend premium positioning across European accounts. GE Healthcare anchors its North American presence through dense field service networks and proprietary image processing architectures. Koninklijke Philips differentiates via integrated workflow software that connects emergency department throughput with radiology throughput.
Digital x-ray technology encompasses direct radiography and computed radiography systems that convert x-ray photons into digital images using flat panel detectors with cesium iodide or gadolinium oxysulfide scintillators, replacing analog film-screen combinations for immediate image acquisition, transmission, and storage. Direct radiography systems lead volume deployment in high-throughput hospital radiology departments where rapid image availability governs emergency department workflow efficiency. Portable systems represent the fastest-expanding product category as point-of-care imaging expands into intensive care units and orthopedic surgery suites where patient transport risks outweigh equipment mobility costs. Image processing software captures concentrated margin pools because algorithmic differentiation in noise reduction and bone suppression creates vendor stickiness beyond hardware replacement cycles.
The FDA's 510(k) premarket notification framework governs digital x-ray device clearance in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for fluoroscopy systems marketed in Europe. Japan's PMDA maintains distinct pharmaceutical and medical device agency standards that shape product registration timelines for flat panel detector imports from Korean and Chinese component suppliers. Stakeholders must monitor convergence between artificial image enhancement algorithms and regulatory definitions of diagnostic device software as a service model to determine capital expenditure versus subscription revenue strategies.
Market Dynamics
Wireless flat-panel detector suites are compressing replacement cycles across hospital radiology departments as outpatient diagnostic chains erode the historical hospital-centric procurement monopoly.
Growth Catalysts
- EU Medical Device Regulation:Stricter clinical evidence requirements for fluoroscopy systems accelerate portfolio rationalization among manufacturers, concentrating procurement toward integrated digital suites.
- Intensive care units:Point-of-care imaging expansion drives portable system deployment where patient transport risks outweigh equipment mobility costs.
- Cesium iodide scintillators:Improved photon conversion efficiency in direct radiography systems shortens image acquisition time for emergency department throughput.
Market Restraints
- Flat panel detector supply:Korean and Chinese component suppliers dominate detector substrate manufacturing, creating geographic concentration risk for original equipment manufacturers.
- FDA 510(k) pathway:Premarket notification timelines extend product development cycles, delaying revenue recognition for algorithmic enhancements.
- Computed radiography legacy:Existing installed base in smaller imaging centers delays full conversion to direct radiography despite superior workflow efficiency.
Strategic Opportunities
- Orthopedic surgery suites:Intraoperative imaging demand creates white space for mobile C-arm configurations with integrated flat panel detectors.
- Artificial image enhancement:Convergence between noise reduction algorithms and diagnostic software-as-a-service models enables subscription revenue streams beyond hardware replacement cycles.
- Germany's radiology modernization:Federal hospital infrastructure programs prioritize digital imaging procurement in university medical centers.
Industry Challenges
- Algorithm validation:Regulatory ambiguity around artificial intelligence-enhanced diagnostics complicates 510(k) submission strategies for software-only updates.
- Legacy PACS integration:Hospital information system interoperability requirements extend deployment timelines and inflate professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital X-Ray Technology Market |
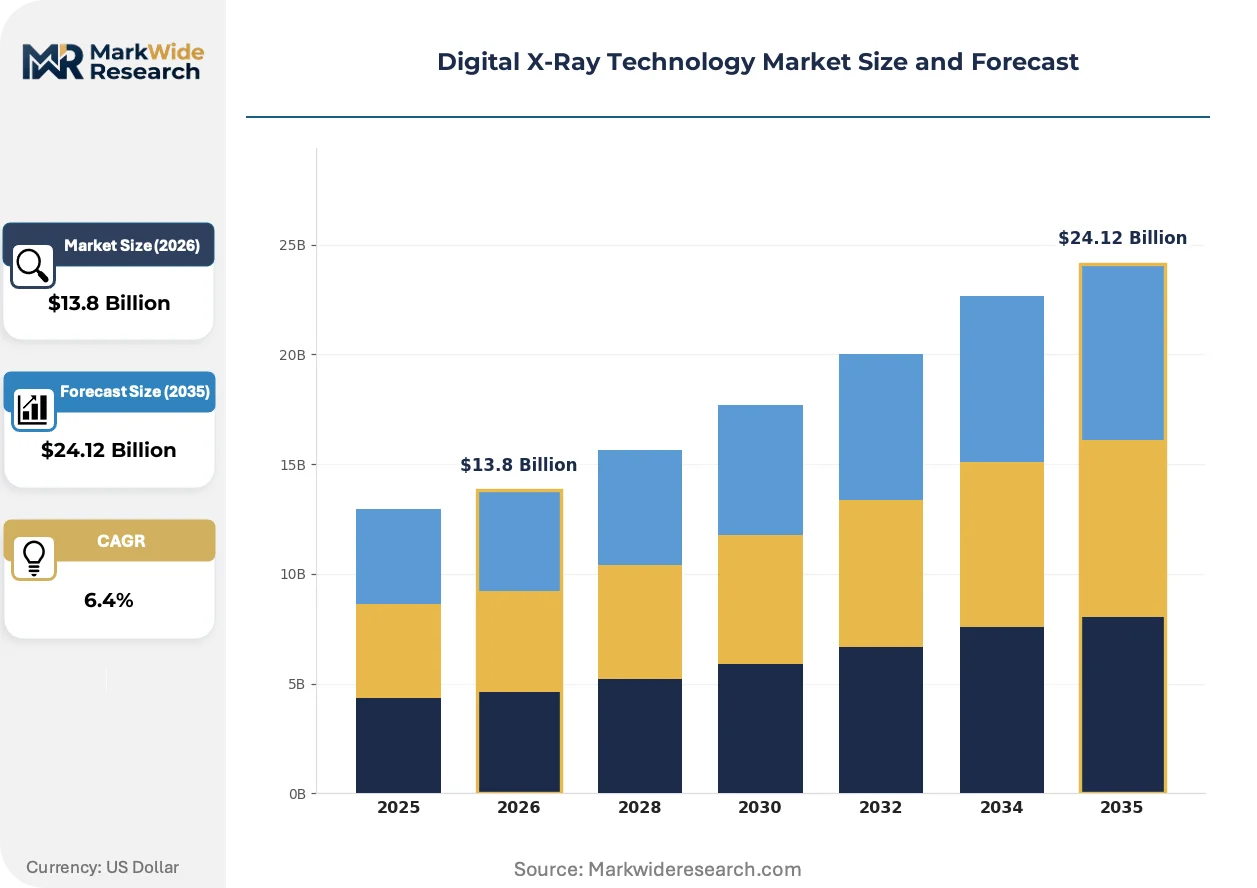
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Computed Radiography, Direct Radiography, Portable Systems, Fluoroscopy End User: Hospitals, Clinics, Diagnostic Centers, Research Institutions Technology: Flat Panel Detectors, Image Processing Software, Wireless Technology, Integration Solutions Application: Orthopedics, Dentistry, Cardiovascular, Oncology |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips, Canon, FUJIFILM Holdings Corporation, Konica Minolta, Agfa-Gevaert Group, Shimadzu Corporation, Carestream Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital X-Ray Technology Market Trends and Innovations
Algorithmic differentiation in image processing is compressing hardware replacement cycles while creating vendor stickiness through software lock-in.
Photon-counting detector technology is displacing energy-integrating flat panel architectures in premium radiology suites. Academic medical centers in Germany and the United States are piloting these systems for spectral imaging applications. The technology is displacing conventional detector procurement patterns by tethering hardware refresh to software upgrade subscriptions.
Japan's PMDA maintains distinct pharmaceutical and medical device agency standards that shape product registration timelines for flat panel detector imports. Korean manufacturers must navigate dual-track conformity assessment procedures that extend market entry by several quarters. Portable system categories face the most pronounced delays as PMDA scrutinizes wireless transmission security protocols.
Diagnostic chains now bundle imaging services with interpretation, collapsing the traditional equipment sale into operational expenditure models. Equipment vendors respond with managed service contracts that unbundle hardware ownership from image throughput guarantees. This restructuring is most visible in North American outpatient networks where capital constraints favor subscription-based procurement.
Digital X-Ray Technology Market Segmentation
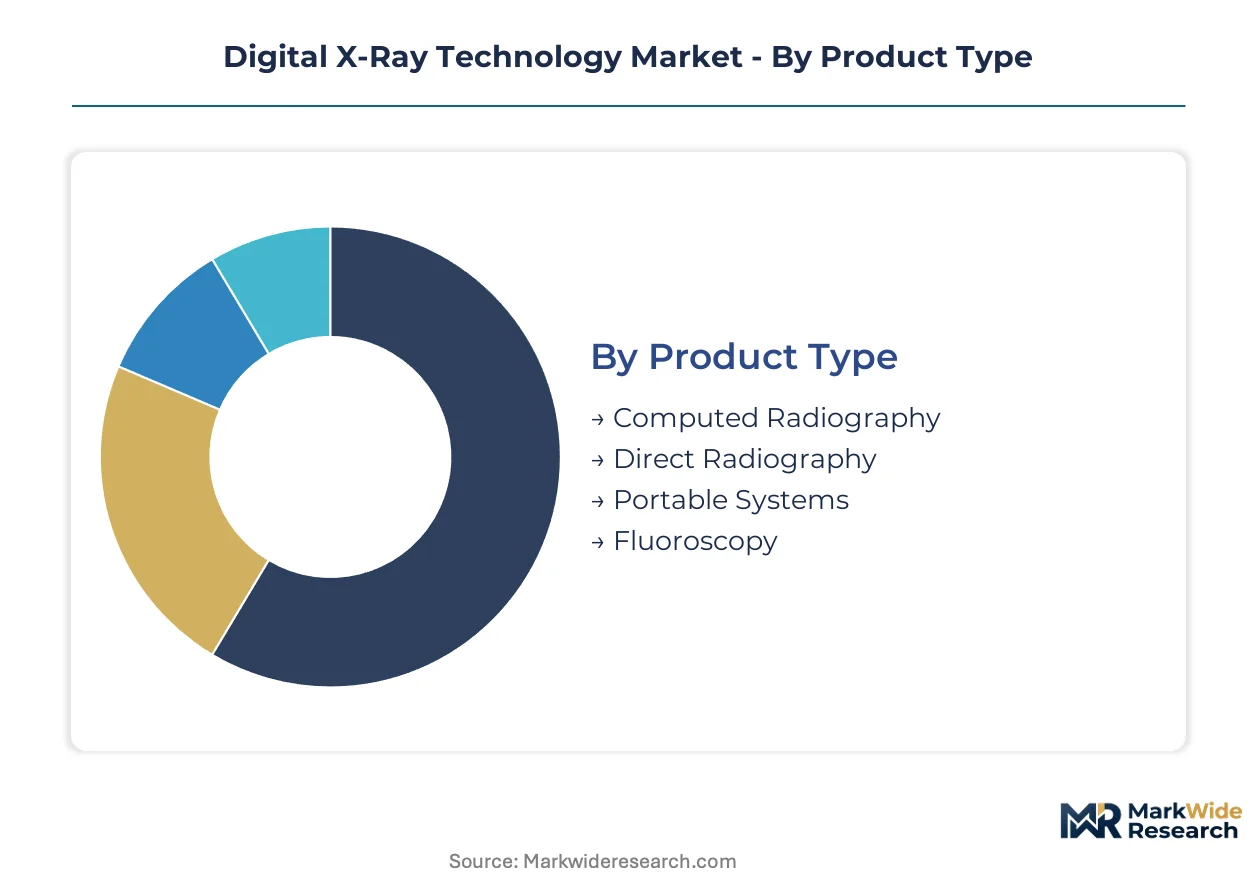
Segmentation in digital x-ray technology reveals how margin pools shift between hardware commoditization and software value capture. Procurement patterns diverge sharply between capital-intensive hospital networks and operational-expenditure-driven outpatient chains.
Product Type:
Margin concentration follows detector architecture sophistication, with premium capture in integrated wireless suites and software-tethered hardware refresh cycles.
- Computed Radiography:Cassette-based systems using photostimulable phosphor plates require laser scanning digitization, creating workflow bottlenecks that limit deployment to budget-constrained imaging centers in secondary cities. Demand persists where capital replacement cycles extend beyond seven years.
- Direct Radiography:Flat panel detectors with cesium iodide scintillators convert x-ray photons directly into electrical signals, eliminating intermediate processing steps. Hospital radiology departments in Germany and the United States prioritize these systems for emergency department throughput optimization.
- Portable Systems:Battery-powered wireless detector configurations enable point-of-care imaging in intensive care units and orthopedic surgery suites where patient transport risks outweigh equipment mobility costs.
- Fluoroscopy:Real-time moving image acquisition systems integrate with surgical navigation platforms, commanding premium positioning through procedure-specific software bundles.
Computed Radiography holds installed capacity. Portable Systems is rotating up the share rankings.
End User:
Procurement authority is fragmenting as diagnostic chains consolidate purchasing power away from traditional hospital-centric decision structures.
- Hospitals:Academic medical centers and tertiary care facilities drive specification standards through bundled enterprise agreements. Siemens Healthineers leverages fluoroscopy installed base to defend premium positioning across European accounts.
- Diagnostic Centers:Outpatient chains now bundle imaging services with interpretation, collapsing equipment sales into operational expenditure models with managed service contracts.
- Clinics:Smaller volume operations prioritize refurbished direct radiography systems and extended service agreements over new capital deployment.
- Research Institutions:Photon-counting detector pilots in Germany and the United States create technology validation pathways for spectral imaging applications.
Hospitals retain specification influence. Diagnostic Centers are climbing the fastest as procurement decision-makers.
Technology:
Value capture concentrates in software layers that create vendor stickiness beyond hardware replacement cycles.
- Flat Panel Detectors:Amorphous silicon and CMOS substrate architectures from Korean and Chinese suppliers dominate component manufacturing, creating geographic concentration risk for original equipment manufacturers.
- Image Processing Software:Algorithmic differentiation in noise reduction and bone suppression creates recurring revenue through subscription models rather than perpetual licenses.
- Wireless Technology:Detector-to-workstation transmission protocols enable mobile deployment but face extended PMDA scrutiny in Japan over security validation timelines.
- Integration Solutions:PACS interoperability requirements extend deployment timelines and inflate professional services costs for legacy hospital information system connectivity.
Flat Panel Detectors hold installed capacity. Image Processing Software is rotating up the share rankings.
Application:
Procedure reimbursement rates and imaging throughput requirements shape technology selection across clinical specialties.
- Orthopedics:Intraoperative imaging demand creates white space for mobile C-arm configurations with integrated flat panel detectors in surgery suites.
- Dentistry:Cone-beam computed tomography systems dominate oral and maxillofacial imaging, with digital panoramic units representing replacement cycle volume.
- Cardiovascular:Interventional suites require fluoroscopy systems with advanced image processing for catheter guidance and stent placement visualization.
- Oncology:Radiation therapy planning demands high-resolution digital radiography for tumor localization and treatment verification protocols.
Orthopedics holds installed capacity. Cardiovascular is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Korean and Chinese component suppliers export flat panel detector substrates to original equipment manufacturers in Germany and the United States, establishing the dominant trade-flow corridor for digital x-ray hardware.
United States
Hospital networks accelerate replacement of analog systems with wireless flat-panel detector suites. The FDA's 510(k) premarket notification pathway governs device clearance timelines. Academic medical centers in Boston and the Research Triangle pilot photon-counting detector systems for spectral imaging validation.
Germany
Federal hospital infrastructure programs prioritize digital imaging procurement in university medical centers. The EU Medical Device Regulation imposes stricter clinical evidence requirements for fluoroscopy systems. Siemens Healthineers anchors regional production in Erlangen while radiology department modernization drives procurement concentration.
Japan
PMDA maintains distinct pharmaceutical and medical device agency standards that shape product registration timelines. Wireless transmission security protocols face extended scrutiny for portable system categories. Tokyo and Osaka metropolitan clusters concentrate demand for integrated digital suites in tertiary care facilities.
China
Domestic flat panel detector manufacturing expands through Korean and Chinese substrate suppliers serving regional original equipment manufacturers. NMPA regulatory frameworks govern medical device registration. Shanghai and Beijing medical device clusters drive component localization strategies.
South Korea
Amorphous silicon and CMOS substrate architectures from domestic suppliers dominate detector manufacturing for export markets. MFDS conformity assessment procedures align with international standards. Seoul Capital Area fabrication facilities supply substrate components to German and US system integrators.
Digital X-Ray Technology Market Competitive Landscape
Listed leaders compete with private specialists across capital deployment cycles and regulatory compliance capabilities. The vendor base concentrates around three tiers: diversified conglomerates with imaging divisions, dedicated medical technology firms, and component-specialist suppliers. Strategic archetypes include installed-base defenders leveraging fluoroscopy relationships, workflow integrators bundling software with hardware, and detector substrate manufacturers controlling upstream supply. Competitive moves center on managed service contract expansion and algorithmic differentiation through subscription revenue models.
Within the installed-base defender tier, Siemens Healthineers and GE Healthcare exemplify archetypes leveraging dense field service networks and proprietary architectures to maintain positioning. Koninklijke Philips occupies a position as workflow integrator connecting emergency department throughput with radiology operations. These three listed entities represent distinct competitive vectors: European production anchoring, North American service density, and software-centric differentiation.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips |
| Canon |
| FUJIFILM Holdings Corporation |
| Konica Minolta |
| Agfa-Gevaert Group |
| Shimadzu Corporation |
| Carestream Health |
| Others |
Pricing and Supply Chain Analysis
Six-to-nine month lead times for flat panel detector substrates concentrate pricing power with Korean and Chinese component suppliers, while original equipment manufacturers absorb inventory carrying costs to hedge against supply disruption. This temporal compression shapes procurement negotiations across hospital networks and outpatient diagnostic chains.
Pricing Analysis
Direct radiography systems command a 40-60% premium over computed radiography cassettes, while portable wireless configurations price at a further 25-35% markup to fixed-room installations. Pricing stratifies across premium, standard, and economy tiers, with differentiation driven by detector resolution specifications and FDA 510(k) clearance tier. Cost compression in the standard tier is intensifying because outpatient diagnostic chains consolidate purchasing volume. Budget-constrained imaging centers in secondary cities exhibit the highest price sensitivity, whereas academic medical centers prioritize throughput optimization over unit economics.
Supply Chain Analysis
Strategic stockpiling of cesium iodide scintillator materials and amorphous silicon substrates prevails over just-in-time approaches, reflecting single-source vulnerability for detector substrate manufacturing. Component supply concentrates in South Korea, China, and Japan, with Korean manufacturers dominating CMOS substrate exports to German and US system integrators. Raw material dependencies include rare-earth phosphors, high-purity silicon wafers, and specialized scintillator crystals. Tariff exposure on Chinese-sourced detector components creates margin pressure for original equipment manufacturers. Distribution runs through direct enterprise contracts with hospital networks and managed service agreements with outpatient diagnostic chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-as-a-service revenue from image processing algorithms and workflow integration layers is expanding faster than hardware replacement cycles, transforming capital equipment markets into recurring-revenue service opportunities.
For Market Incumbents: Consolidate fluoroscopy installed base relationships through bundled managed service contracts that tether hardware refresh to software upgrade subscriptions. Defend against photon-counting detector entrants by accelerating spectral imaging validation partnerships with academic medical centers in Germany and the United States. Backward integration into detector substrate sourcing mitigates Korean and Chinese supply concentration risk. For New Entrants and Emerging Players: Post-contract support gaps in legacy PACS integration create white space for specialized interoperability vendors. Target orthopedic surgery suites and intensive care units where point-of-care imaging demand outpaces incumbent mobile C-arm configuration availability. A hardware-as-a-service go-to-market angle bypasses capital budget constraints at outpatient diagnostic chains. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across portable system categories as wireless detector commoditization reduces manufacturing scale requirements. Five-to-ten year viability favors software-tethered hardware platforms with established hospital information system connectivity. Acquisition target archetypes include algorithm developers with FDA 510(k) clearance pathways and managed service providers with dense field service networks. Watch photon-counting detector pilot outcomes at German university medical centers as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Algorithmic differentiation in noise reduction creates vendor stickiness beyond hardware cycles. |
| Hospital System Partnership | Bundled enterprise agreements with academic medical centers anchor specification influence. |
| FDA Submission | Premarket notification pathways govern clearance timelines for digital radiography enhancements. |
| CE Marking Pathway | EU Medical Device Regulation imposes stricter clinical evidence requirements for fluoroscopy systems. |
| Reimbursement Strategy | Procedure coding alignment with Medicare and commercial payers shapes hospital procurement priority. |
Research Methodology
Operator-level perspectives from hospital purchasing committee members, biomedical engineers, GPO contracts managers, and outpatient diagnostic chain procurement directors anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU Medical Device Regulation submission documents. Bottom-up unit shipment estimates triangulated against top-down market sizing across detector architecture, end-user category, and geographic production cluster.
Sensitivity analysis tested volume and value outputs across the projection horizon against alternative scenarios for regulatory approval timelines and supply chain disruption events. Segmentation dimensions modeled include product type, end-user procurement authority, detector technology architecture, and clinical application specialty. CAGRs derived from fitted growth curves incorporating replacement cycle compression, outpatient chain consolidation, and algorithmic software attach rates. Industry-specific forecast inputs encompass photon-counting detector pilot adoption rates and managed service contract penetration.
Underlying assumptions cover stable FDA 510(k) clearance timelines and continued Korean-Chinese substrate supply availability, with deviation risk concentrated in EU Medical Device Regulation enforcement intensity and wireless transmission security protocol changes. Revision becomes warranted when photon-counting detector cost curves cross energy-integrating thresholds or when diagnostic chain bankruptcy rates exceed historical bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
North America Image Sensors Market
Imaging
North America IP Camera Market
Imaging
India CCTV Camera Market
Imaging
CCD Image Sensors Market
Imaging
Global Waterproof Camera Market
Imaging
Macroscopic Imaging Systems Market
Imaging
Microwave Imaging Market
Imaging
Global 3D Camera Market
Imaging
Photo Kiosk Market
Imaging
Global Optical Preclinical Imaging Market
Imaging
Global Phosphor Plate Scanners Market
Imaging
Event Camera Market
Imaging
Automotive Compact Camera Module Market
Imaging
Side View Camera System Market
Imaging
Global Pathology Imaging Systems Market
Imaging
Machine Vision System and Services Market