
 Ion Beam Etching System Market | 2026-2036
Ion Beam Etching System Market Size, Share, and Industry Trends Forecast 2026-2036
Ion Beam Etching System Market Foresight
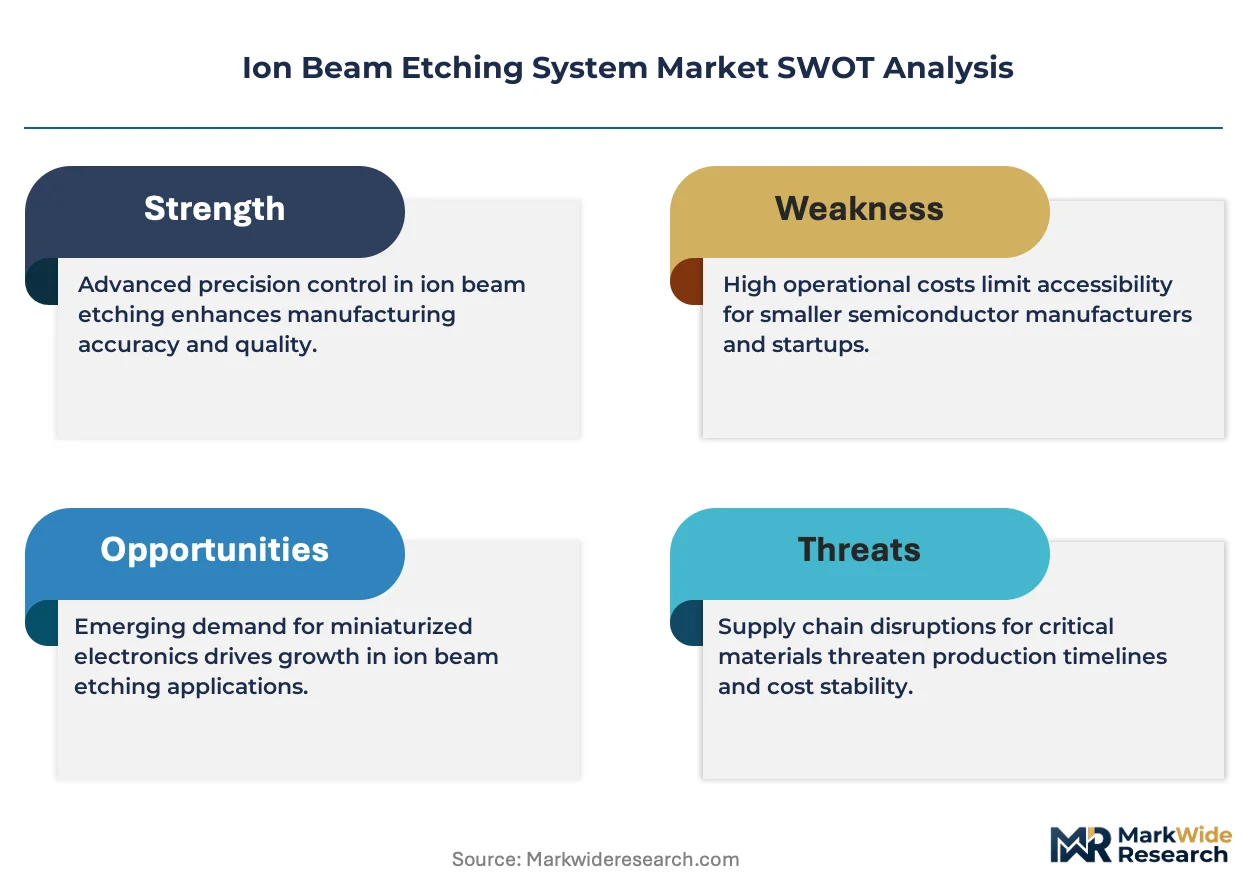
Buyer concentration among leading semiconductor foundries is hardening as capital expenditure tilts toward sub-7nm node development. Applied Materials Inc. leverages its installed base in reactive ion etching to defend service attach rates. Canon Anelva Corporation anchors its position through high-vacuum system integration for memory stack etching. Oxford Instruments differentiates via modular ion source architectures that reduce chamber downtime.
An ion beam etching system directs a focused beam of ions onto a substrate surface to remove material through physical sputtering, typically operating at vacuum levels below 10^-4 Pa with beam energies ranging from 100 eV to 2 keV for precision pattern transfer in microfabrication. The equipment serves critical roles in wafer fabrication where atomic-scale accuracy determines device yield. Inline systems command the largest revenue share due to throughput advantages in high-volume foundry environments, while mask etchers capture premium pricing from photonics applications requiring sub-nanometer edge placement. Deep reactive ion etching technology leads growth in MEMS cavity formation where high aspect ratios exceed 50:1.
EPA hazardous air pollutant standards and OSHA process safety management requirements shape equipment design for US-based fabrication facilities, while EU REACH restrictions on perfluorinated compounds force chemistry transitions in European installations. Japan's METI semiconductor revitalization policy and South Korea's K-Semiconductor Belt initiative direct subsidy flows toward domestic etching tool procurement. Stakeholders must monitor evolving F-Gas Regulation phase-down schedules and corresponding process gas substitutions that could alter ion source configuration requirements.
Market Dynamics
Capital expenditure consolidation among Taiwan Semiconductor Manufacturing Company and Samsung Foundry is compressing vendor negotiation cycles and forcing equipment suppliers to absorb extended warranty terms for sub-5nm node toolsets.
Growth Catalysts
- EU F-Gas Regulation phase-down:Restrictions on perfluorinated process gases are accelerating chemistry transitions that favor ion beam systems with closed-loop gas recovery architectures.
- MEMS sensor proliferation:Automotive lidar and inertial measurement unit demand is expanding deep reactive ion etching capacity for high-aspect-ratio cavity formation.
- South Korea K-Semiconductor Belt:Domestic subsidy flows are directing procurement toward local etching tool vendors for memory stack fabrication expansion.
Market Restraints
- High-purity gas supply concentration:Specialty fluorinated precursor production concentrates in Japanese chemical conglomerates, exposing fabs to input cost volatility and allocation risk.
- Chamber matching complexity:Process drift between matched ion sources limits multi-chamber tool deployment for critical layer etching.
- Plasma dicing substitution:Stealth dicing and laser ablation systems are displacing ion beam approaches in thin-wafer singulation for power devices.
Strategic Opportunities
- Photonics packaging expansion:Silicon photonics transceiver fabrication is opening mask etcher demand for sub-nanometer edge placement in waveguide structures.
- India PLI scheme for semiconductors:Domestic fab incentives are creating first-mover positioning for etching system vendors in emerging foundry clusters.
- Atomic layer etching convergence:Sequential ion bombardment and chemical modification cycles are integrating with existing reactive ion etching platforms for atomic-scale precision.
Industry Challenges
- Vacuum technology specialist scarcity:Ion source design and high-vacuum system engineering expertise concentrates among aging workforce cohorts in Japan and Germany.
- EPA hazardous air pollutant compliance:US-based fabrication facilities face extended certification timelines for abatement system integration with new etching tool installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ion Beam Etching System Market |
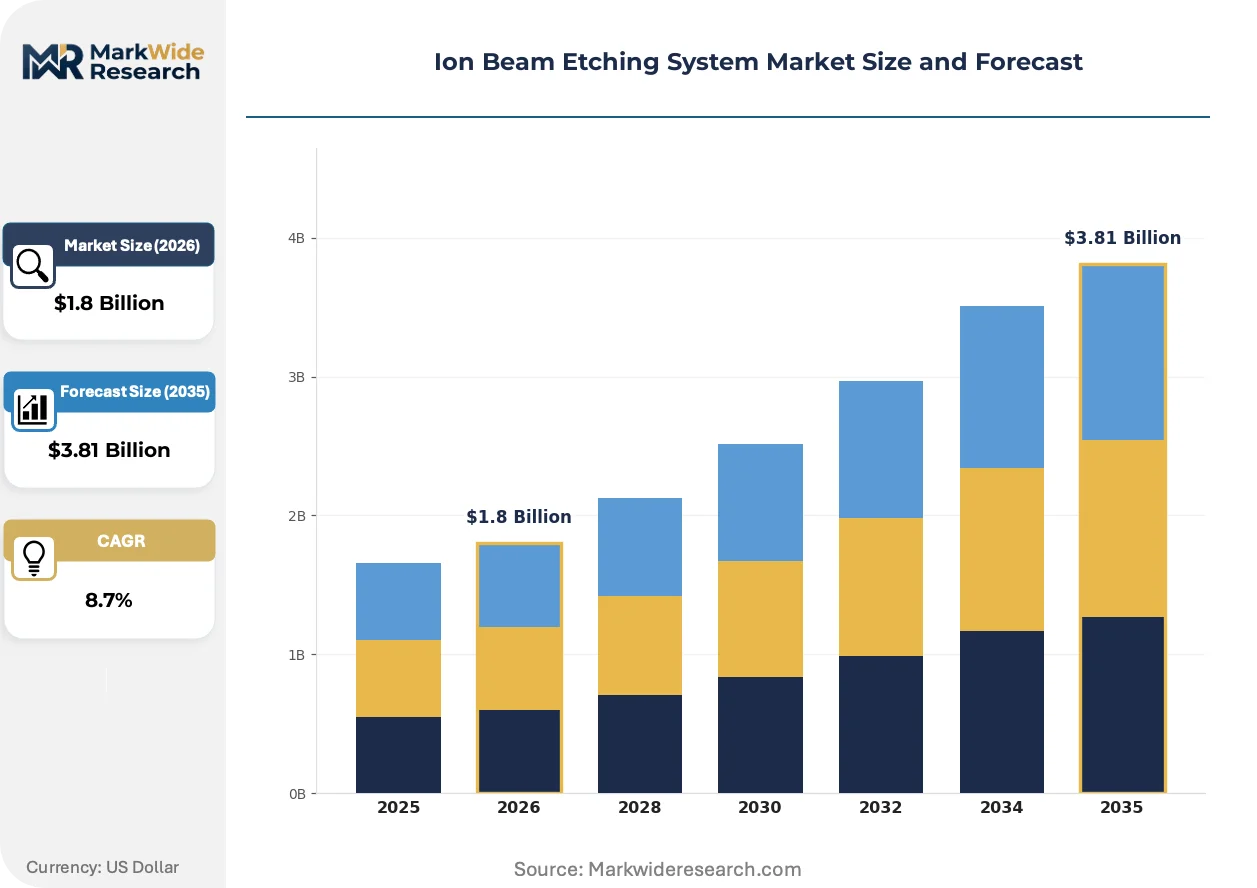
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Systems, Inline Systems, Mask Etchers, Customized Solutions Technology: Reactive Ion Etching, Deep Reactive Ion Etching, Plasma Etching, Conventional Etching End User: Semiconductors, Microelectronics, MEMS, Photonics Application: Wafer Fabrication, Thin Film Deposition, Surface Modification, Component Manufacturing |
| Companies Covered | Veeco Instruments Inc., Canon Anelva Corporation, Hitachi High-Technologies Corporation, Applied Materials Inc., Tokyo Electron Limited, Oxford Instruments, Meyer Burger Technology AG, SCREEN Semiconductor Solutions, Scia Systems GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ion Beam Etching System Market Shifts & Advancements
Process architecture evolution is compressing the boundary between physical sputtering and chemical enhancement, with equipment vendors racing to modularize ion source configurations for rapid chemistry switching.
Neutral beam etching technology is integrating charge-free ion delivery to eliminate pattern-dependent charging damage in delicate gate stack structures. Leading memory manufacturers in South Korea are piloting these systems for 3D NAND string etching. This convergence is compressing the performance gap between ion beam and plasma-based approaches for high-aspect-ratio applications.
Japan's METI semiconductor revitalization policy is mandating domestic content ratios for critical process equipment procurement. Subsidy disbursement now ties to local assembly and service infrastructure commitments. Equipment vendors are responding by establishing regional technical centers in Yokohama and Kyoto to capture policy-directed demand.
Foundry procurement patterns are compressing from multi-year framework agreements to quarterly purchase orders with spot pricing mechanisms. Equipment vendors serving Taiwan and South Korean customers are unbundling service contracts from hardware sales to preserve margin visibility. This disintermediation is most pronounced in trailing-edge node capacity expansions where tool standardization permits vendor switching.
Ion Beam Etching System Market Segmentation
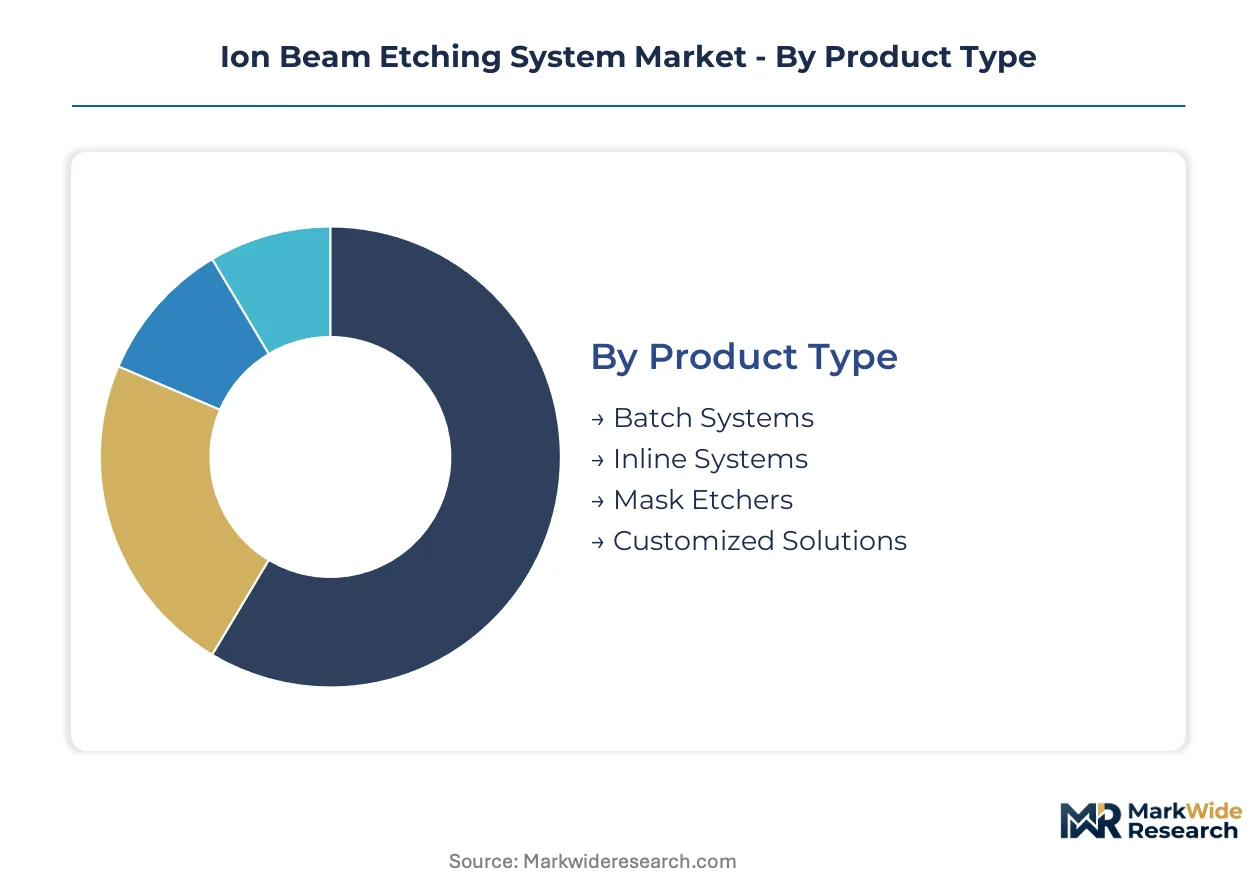
Equipment buyers in the Ion Beam Etching System Market segment procurement by throughput requirements and precision thresholds. Foundry engineers match system architecture to specific layer criticality, creating distinct pricing tiers across product configurations.
Product Type:
Capital allocation intensity varies dramatically across installation footprints, with high-volume fabs prioritizing throughput-per-square-meter over initial acquisition cost.
- Inline Systems:Continuous substrate transport through multiple process chambers enables wafer-per-hour rates exceeding batch alternatives by an order of magnitude. Taiwan Semiconductor Manufacturing Company and Samsung Foundry specify these configurations for logic node production where tool utilization rates directly compress cost-per-wafer metrics.
- Mask Etchers:Sub-nanometer edge placement accuracy serves photonics waveguide fabrication and advanced lithography reticle production. Demand concentrates in Yokohama and Kyoto clusters where Japan's METI semiconductor revitalization policy directs subsidy flows toward domestic equipment procurement.
- Batch Systems:Lower capital outlay suits research institutions and pilot lines where throughput requirements remain modest.
- Customized Solutions:Modified chamber geometries address non-standard substrate sizes in compound semiconductor foundries.
Volume sits with Inline Systems; growth tilts toward Mask Etchers.
Technology:
Process chemistry compatibility determines retrofit potential and extends equipment depreciation schedules across technology node transitions.
- Deep Reactive Ion Etching:Bosch process alternation between etch and passivation cycles achieves aspect ratios exceeding 50:1 in MEMS cavity formation. Automotive lidar manufacturers in South Korea's K-Semiconductor Belt are expanding capacity for inertial measurement unit production.
- Reactive Ion Etching:Combined physical sputtering and chemical reactivity serves multi-material stack patterning in 3D NAND string etching. EU F-Gas Regulation phase-down schedules are forcing chemistry transitions toward closed-loop gas recovery architectures that this technology accommodates.
- Plasma Etching:High-density plasma sources suit dielectric material removal in back-end-of-line processing.
- Conventional Etching:Physical sputtering without chemical enhancement retains niche applications in magnetic thin film patterning.
Installation base concentrates in Reactive Ion Etching; steepest expansion trajectory belongs to Deep Reactive Ion Etching.
End User:
Device complexity escalation across end-use categories is fragmenting specification requirements beyond universal platform coverage.
- Semiconductors:Sub-7nm node production demands atomic-scale etch depth control and chamber-to-chamber matching precision. EPA hazardous air pollutant standards extend certification timelines for US-based fabrication facilities integrating abatement systems with new tool installations.
- MEMS:Cavity release etching and proof mass definition require high aspect ratio capabilities with minimal sidewall roughness. India PLI scheme for semiconductors is creating first-mover positioning for equipment vendors in emerging domestic foundry clusters.
- Microelectronics:Power device and discrete component fabrication prioritizes etch rate uniformity over absolute resolution.
- Photonics:Silicon photonics transceiver waveguide formation demands sub-nanometer sidewall verticality for optical loss minimization.
Revenue concentration favors Semiconductors; share gains are climbing the fastest in Photonics.
Application:
Process step criticality within fabrication sequences determines spare parts inventory depth and service contract pricing structures.
- Wafer Fabrication:Front-end pattern transfer operations account for the majority of chamber hours and consumables expenditure. Foundry procurement patterns are compressing toward quarterly purchase orders with spot pricing mechanisms that disintermediate traditional multi-year framework agreements.
- Surface Modification:Ion beam texturing and cleaning prepares substrates for subsequent deposition steps in compound semiconductor manufacturing. Neutral beam etching pilots in South Korean memory fabs are eliminating pattern-dependent charging damage for delicate gate stack structures.
- Thin Film Deposition:Ion beam-assisted deposition modifies film properties during growth rather than removing material.
- Component Manufacturing:Hard disk drive read head fabrication and sensor element definition operate outside mainstream foundry supply chains.
Chamber hours accumulate in Wafer Fabrication; emerging applications are expanding most quickly in Surface Modification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capital expenditure concentrates in East Asian manufacturing corridors where sub-7nm node production drives etching tool procurement. Taiwan and South Korea dominate wafer starts for advanced logic and memory devices. Equipment vendors align regional service infrastructure to match subsidy-directed procurement flows.
Taiwan
Taiwan Semiconductor Manufacturing Company expands 3nm and 2nm fab capacity in Tainan Science Park and Taichung. The National Development Council's semiconductor initiative directs subsidy flows toward domestic equipment procurement. Kaohsiung's emerging advanced packaging cluster is absorbing mask etcher installations for silicon photonics waveguide fabrication.
South Korea
Samsung Foundry and SK Hynix drive etching system demand for 3D NAND string and DRAM cell formation. The K-Semiconductor Belt policy mandates domestic content ratios for critical process equipment. Yongin and Pyeongtaek host concentrated memory fab complexes where closed-loop gas recovery architectures are becoming standard configuration.
United States
Intel's Ohio and Arizona fab investments are reshoring advanced node manufacturing capacity. EPA hazardous air pollutant standards extend certification timelines for abatement system integration with new tool installations. Phoenix and Columbus metropolitan areas are emerging as etching equipment deployment zones for domestic logic production.
Japan
Tokyo Electron and Canon Anelva anchor domestic equipment supply chains for memory stack etching applications. METI's semiconductor revitalization policy ties subsidy disbursement to local assembly and service infrastructure commitments. Yokohama and Kyoto technical centers are capturing policy-directed demand for high-vacuum system integration.
Germany
Infineon and Bosch expand automotive sensor and power semiconductor capacity in Dresden and Reutlingen. EU REACH restrictions on perfluorinated compounds are forcing chemistry transitions in etching process flows. Saxony's Silicon Saxony cluster is piloting closed-loop gas recovery systems for MEMS cavity formation applications.
Ion Beam Etching System Market Competitive Landscape
Japanese producers anchor one tier; American and European specialists hold differentiated positions in modular architectures and vacuum integration. The vendor structure concentrates around three to five dominant equipment platforms with substantial installed bases. Strategic archetypes include integrated process equipment conglomerates, high-vacuum system specialists, and modular ion source innovators. Competitive moves center on unbundling service contracts from hardware sales and establishing regional technical centers for subsidy capture.
Among Japanese fabricators, Canon Anelva Corporation and Tokyo Electron Limited occupy positions in high-vacuum system integration for memory stack etching. Applied Materials Inc. represents the integrated conglomerate archetype with reactive ion etching installed base leverage. Oxford Instruments exemplifies modular ion source differentiation that reduces chamber downtime in foundry environments.
| Leading Market Players |
|---|
| Veeco Instruments Inc. |
| Canon Anelva Corporation |
| Hitachi High-Technologies Corporation |
| Applied Materials Inc. |
| Tokyo Electron Limited |
| Oxford Instruments |
| Meyer Burger Technology AG |
| SCREEN Semiconductor Solutions |
| Scia Systems GmbH |
| Others |
Supply & Pricing Matrix
Specialty fluorinated precursor costs cascade from Japanese chemical conglomerates through etching system pricing tiers, with high-purity gas supply concentration compressing margins for batch system vendors while inline configurations absorb volatility through foundry volume commitments.
Pricing Analysis
Volume-margin splits separate inline system vendors serving Taiwan Semiconductor Manufacturing Company and Samsung Foundry from mask etcher specialists capturing premium positioning in photonics applications. Pricing stratifies across premium, standard, and economy tiers driven by chamber matching precision and after-sales service bundling. Cost compression in trailing-edge node toolsets intensifies as quarterly purchase orders with spot pricing mechanisms disintermediate traditional multi-year frameworks. Research institutions and pilot lines exhibit highest price sensitivity; sub-5nm node foundries prioritize chamber-to-chamber matching precision over acquisition cost.
Supply Chain Analysis
CE marking and EPA hazardous air pollutant certification gating restricts vendor participation in European and US installations, compressing qualified supplier pools. High-purity ion source components and vacuum pump assemblies draw from Japan, Germany, and the United States; specialty fluorinated precursors rest on Japanese chemical conglomerate production. Single-source vulnerability in gas supply exposes fabs to allocation risk during capacity crunches. Distribution runs through direct sales teams for high-volume foundry accounts and regional technical centers for subsidy-capture in South Korea and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ion beam etching market sits in a technology-transition phase as neutral beam etching pilots in South Korean memory fabs displace legacy reactive ion approaches for 3D NAND string formation.
For Market Incumbents: Deepen backward integration into high-purity gas recovery architectures to defend service attach rates against closed-loop chemistry transitions mandated by EU F-Gas Regulation phase-down schedules. Expand regional technical center footprints in Yokohama and Kyoto to capture METI semiconductor revitalization policy-directed procurement. Prioritize chamber matching algorithm R&D to offset multi-chamber tool deployment limitations in critical layer etching. For New Entrants and Emerging Players: The premium-to-economy tier price gap in mask etchers for silicon photonics waveguide fabrication offers white-space entry. Target India's PLI scheme for semiconductors to establish first-mover positioning in emerging domestic foundry clusters before incumbent service infrastructure solidifies. Pursue atomic layer etching convergence partnerships with existing reactive ion etching platform vendors to bypass standalone system development costs. For Investors and Strategic Acquirers: Canon Anelva Corporation's regional technical center commitments in Japan are the leading indicator that subsidy-tied procurement flows will concentrate vendor selection power in policy-compliant equipment suppliers. The five-to-ten year viability window favors acquisition of modular ion source architecture specialists with demonstrated chamber downtime reduction capabilities. Watch for neutral beam etching pilot-to-production conversion announcements from South Korean memory manufacturers as the inflection signal for technology substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Technical Center Establishment | Captures METI and K-Semiconductor Belt subsidy flows tied to local assembly mandates. |
| Closed-Loop Gas Recovery Architecture Development | Accommodates EU F-Gas Regulation chemistry transitions without chamber reconfiguration. |
| Modular Ion Source Platform Launch | Reduces chamber downtime for foundry customers compressing cost-per-wafer metrics. |
| Atomic Layer Etching Convergence Partnership | Integrates sequential bombardment cycles with existing reactive ion etching installed bases. |
| India PLI Scheme Market Entry | Positions equipment vendors before domestic fab infrastructure locks in incumbent relationships. |
Research Methodology
Document review covered SEC 10-K filings from semiconductor equipment vendors, METI subsidy disbursement records, and EU REACH regulatory filings, complemented by interviews with foundry procurement directors, vacuum technology engineering leads, and ion source design specialists. Secondary validation drew from customs trade data for etching system imports, EPA hazardous air pollutant compliance databases, and South Korea's K-Semiconductor Belt policy implementation reports. Bottom-up equipment shipment tallies and top-down foundry capital expenditure analysis were triangulated to constrain estimate variance.
Cross-referencing historical shipment patterns against panel input from equipment vendor sales executives and foundry engineering directors anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology node criticality, end-use application, and regional subsidy regime. CAGRs were derived from equipment deployment trajectories tied to announced fab construction timelines and process technology roadmaps. Forecast inputs incorporated chamber matching precision requirements for sub-7nm node production and closed-loop gas recovery architecture adoption curves.
Inputs from foundry procurement directors and METI policy implementation records were available through the study window; gaps in neutral beam etching pilot production data introduce uncertainty bands around technology substitution velocity assumptions. Forecasts reflect documented assumptions regarding EU F-Gas Regulation phase-down adherence and South Korea domestic content ratio enforcement. A model refresh is warranted upon material change in subsidy disbursement schedules or neutral beam etching commercialization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Global Cleanroom Technologies Market
Semiconductor Equipment
Acid Filling and Leveling Machine Market
Semiconductor Equipment
Semiconductor Process and Control Equipment Market
Semiconductor Equipment
Global Semiconductor Stepper Systems Market
Semiconductor Equipment
Vapor Blasting Machine Market
Semiconductor Equipment
Focused Ion Beam Market
Semiconductor Equipment
Partition Inserter Machines Market
Semiconductor Equipment
Global Semiconductor Photolithography Market
Semiconductor Equipment
Semiconductor Wafer Fab Equipment (WFE) Market
Semiconductor Equipment
Automatic Flip Chip Bonders Market
Semiconductor Equipment
Laser Micro Perforation Equipment Market
Semiconductor Equipment
Laser Annealing System Market
Semiconductor Equipment
Vacuum Soldering System Market
Semiconductor Equipment
Global Tamping Machine Market
Semiconductor Equipment
Automatic Mounter Wafer Equipment Market
Semiconductor Equipment
Plasma Etch System Market