
 United States Automotive Glass Market | 2026-2036
United States Automotive Glass Market Size, Share, and Industry Trends Forecast 2026-2036
United States Automotive Glass Market Intelligence
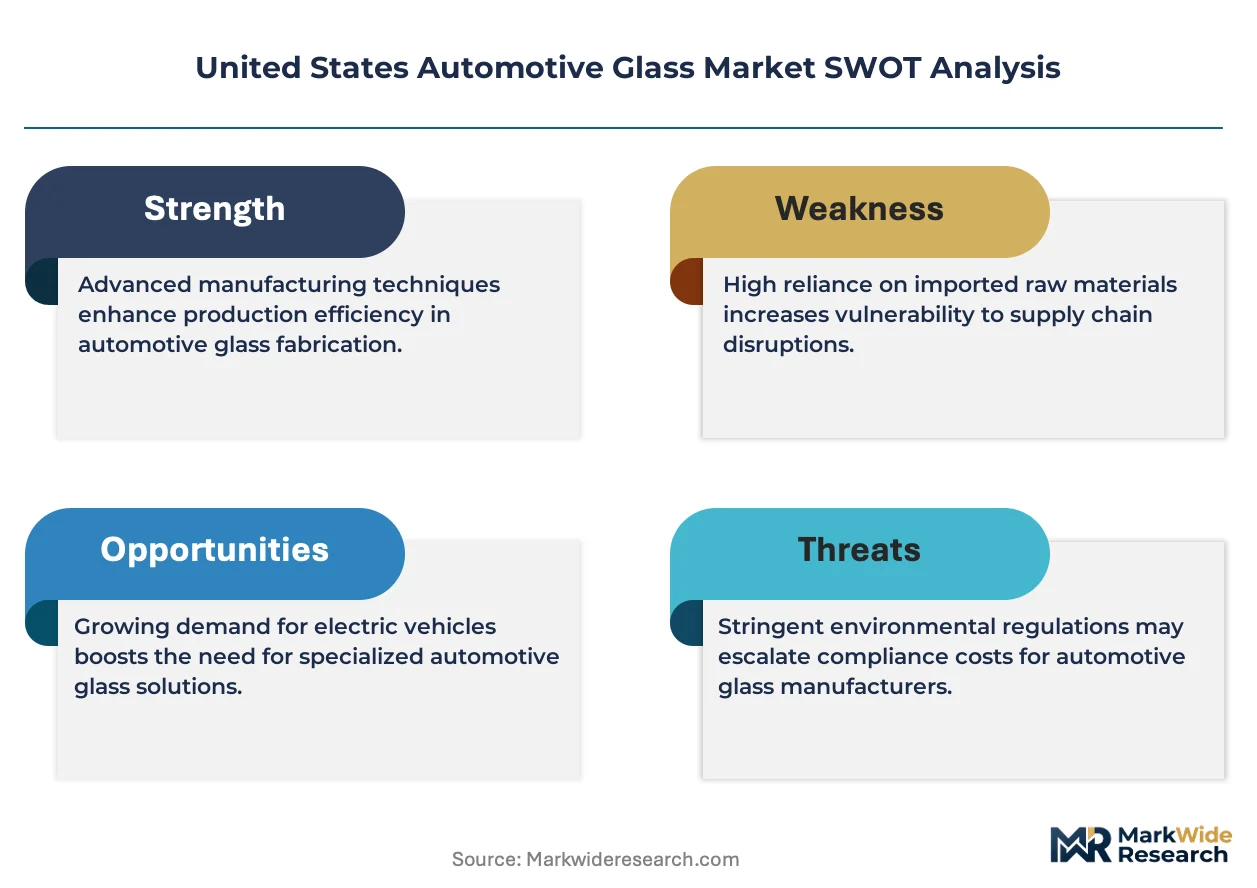
Multi-source procurement toward regional suppliers is shifting how domestic automakers secure windshields and tempered side panels. AGC Inc. sustains significant float glass capacity across Ohio and Kentucky, positioning it close to Detroit Three assembly plants. Fuyao Glass Industry Group Co., Ltd. operates substantial manufacturing in Ohio and Illinois, leveraging its cost structure to compete aggressively on OEM laminated windshields. Saint-Gobain Sekurit differentiates through advanced acoustic and solar-control interlayer technology for premium vehicle programs.
United States automotive glass encompasses laminated and tempered safety glazing engineered to meet optical clarity, impact resistance, and structural integrity specifications for passenger and commercial vehicles, with laminated windshields typically combining two glass plies bonded by polyvinyl butyral interlayers to prevent occupant ejection during collisions. Windshield applications dominate value contribution due to larger surface areas and integrated sensor mounting requirements for advanced driver assistance systems. Laminated glass leads material selection for front glazing given its shatter-retention properties, while tempered glass occupies the side and rear positions where fragmentation patterns reduce laceration risk. OEMs anchor volume demand through long-term supply agreements tied to vehicle platform lifecycles, though aftermarket providers capture higher per-unit margins on replacement installations.
NHTSA Federal Motor Vehicle Safety Standard 205 governs glazing materials and installation integrity, while EPA fuel economy targets indirectly shape demand by pushing thinner, lighter glass formulations. OSHA workplace safety standards affect fabrication facility capital requirements, particularly for silica exposure controls in tempering operations. State-level zero-emission vehicle mandates in California and New York are accelerating laminated sunroof penetration as electric vehicle architectures prioritize cabin openness and weight distribution. Stakeholders must weigh capital allocation between capacity expansion in the Southeast manufacturing corridor and investment in chemically strengthened glass for next-generation head-up display compatibility.
Market Dynamics
Electric vehicle platform architectures are compressing windshield specification cycles as panoramic roof systems displace traditional metal roof panels across Detroit Three and Tesla assembly programs. NHTSA glazing material updates and EPA fuel economy targets are forcing simultaneous investments in lighter interlayer chemistries and sensor-integrated mounting systems.
Growth Catalysts
- Zero-emission vehicle mandates:California and New York ZEV requirements are accelerating laminated sunroof penetration as EV cabins prioritize openness and battery placement flexibility.
- Southeast manufacturing corridor concentration:Alabama, South Carolina, and Tennessee assembly plant expansions are pulling regional float glass capacity investments from Ohio and Kentucky suppliers.
- Head-up display compatibility:Chemically strengthened glass formulations are enabling larger projection areas without optical distortion for premium and mass-market vehicle programs.
Market Restraints
- Silica input cost volatility:High-purity silica sand pricing fluctuations and energy-intensive tempering furnace operations are compressing margins for domestic fabricators.
- Float glass supply concentration:AGC and Fuyao control substantial Ohio and Illinois capacity, creating bottleneck risk for OEMs seeking multi-source procurement.
- Interlayer technical limitations:Polyvinyl butyral acoustic performance gaps at highway speeds restrict premium positioning against acoustic PVB alternatives.
Strategic Opportunities
- Aftermarket channel digitization:Mobile glass replacement platforms and direct-to-consumer scheduling are capturing higher-margin installations outside dealer networks.
- ADAS sensor integration:Windshield-embedded LiDAR and camera mounting requirements are creating specification premiums for optical-grade laminated assemblies.
- IRA clean vehicle credits:Domestic content incentives are favoring U.S.-based float and fabrication investments over imported finished glass.
Industry Challenges
- Optical calibration technician shortage:ADAS-equipped windshield replacement requires precise camera recalibration capabilities that most independent installers lack.
- Tempering line capex intensity:New thermal or chemical strengthening capacity requires substantial furnace investments with payback periods stretching across multiple vehicle platform cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Automotive Glass Market |
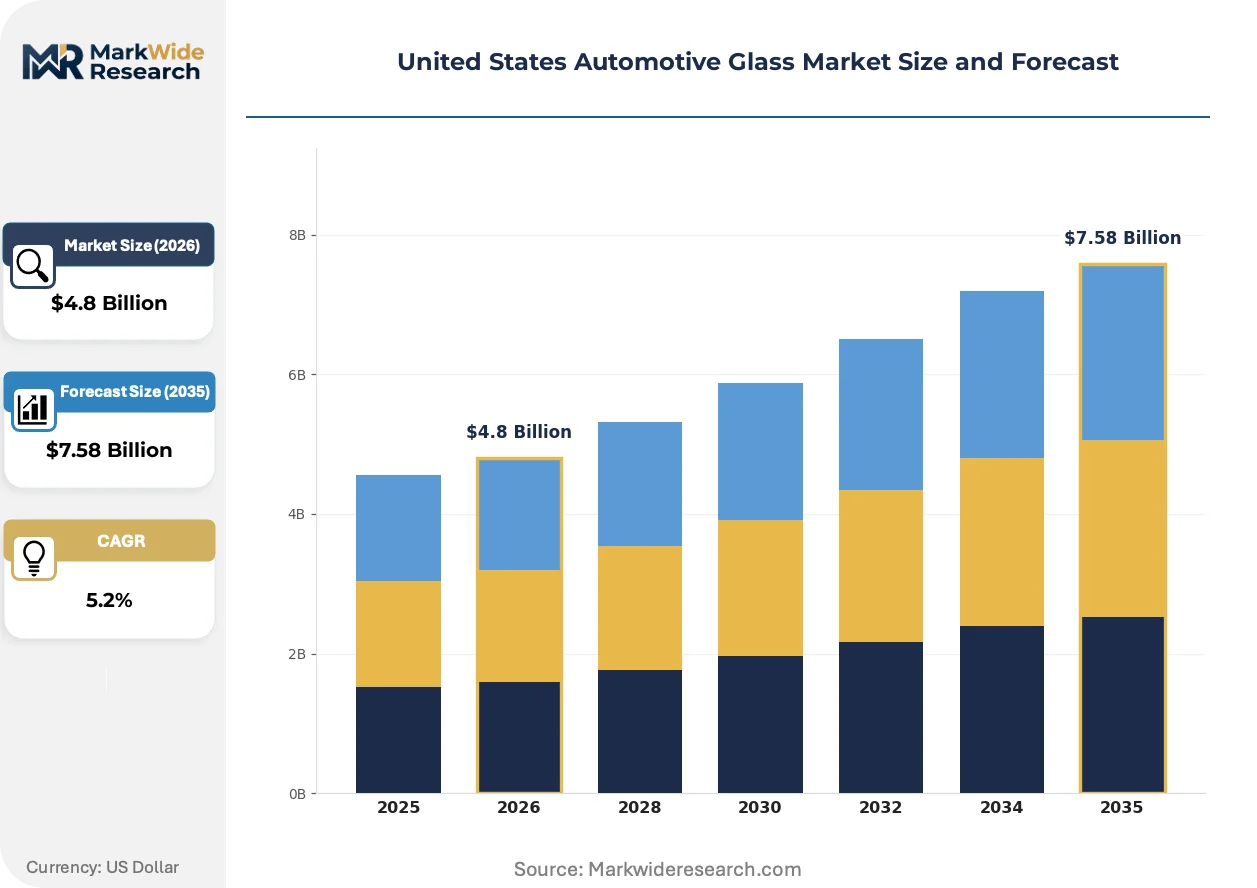
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Windshield, Side Windows, Back Glass, Sunroof Material: Tempered Glass, Laminated Glass, Polycarbonate, Others End User: OEMs, Aftermarket Providers, Repair Shops, Vehicle Assemblers Installation Type: Adhesive Bonding, Mechanical Fastening, Tape Application, Others |
| Companies Covered | AGC Inc., Saint-Gobain Sekurit, Fuyao Glass Industry Group Co., Ltd., Vitro S.A.B. de C.V., Gentex Corporation, Nippon Sheet Glass Co., Ltd., Corning Incorporated, Guardian Industries, Pilkington, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Automotive Glass Market Strategic Shifts & Innovations
Automotive glazing is transitioning from passive structural components to active sensor substrates and cabin experience enablers. Three converging developments are compressing traditional specification boundaries.
Acoustic polyvinyl butyral interlayers with embedded damping films is overtaking standard PVB in premium vehicle programs. BMW and Mercedes-Benz assembly specifications now require 4-6 decibel interior noise reduction for flagship sedans and electric crossovers. This material shift is compressing commodity interlayer margins while rewarding suppliers with acoustic R&D capabilities.
NHTSA Federal Motor Vehicle Safety Standard 205 updates are mandating improved glazing retention under rollover conditions. The revised testing protocols are forcing suppliers to validate new edge-bonding chemistries and frame integration designs. Laminated side glass applications are expanding beyond front windshields as OEMs seek unified safety architectures.
Fleet operators and insurance carriers are consolidating replacement purchasing through national account structures. Independent repair networks and mobile service platforms are displacing traditional dealer-dominated distribution in the aftermarket channel. This concentration is most visible in Florida and Texas where hail damage and comprehensive claim volumes drive bulk procurement negotiations.
United States Automotive Glass Market Segmentation
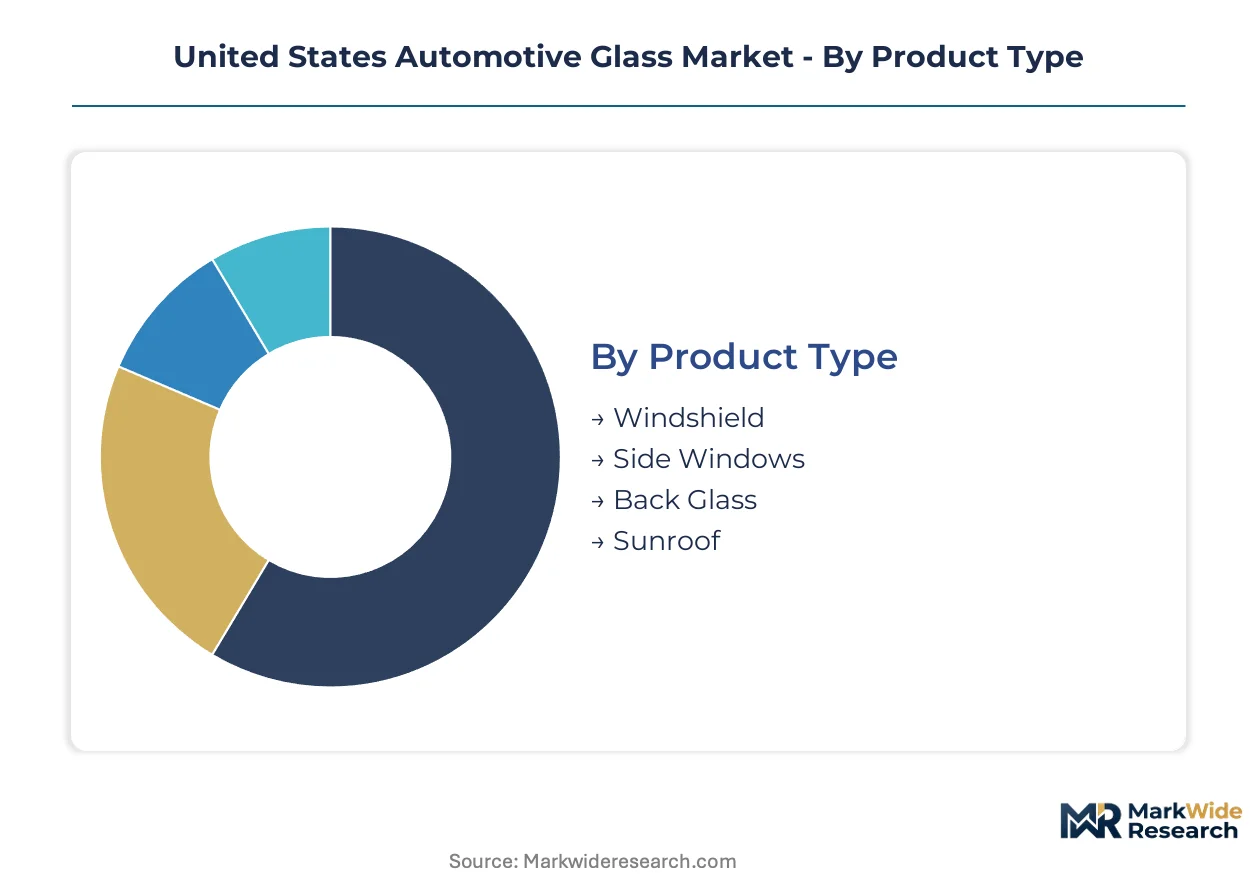
Automotive glass segmentation reveals how specification cycles and procurement economics diverge across vehicle programs. Understanding these divisions exposes where capital allocation priorities clash between volume scale and margin capture.
Product Type:
Standalone glazing dominates front applications where optical clarity and structural retention operate independently; embedded sensor integration is compressing specification cycles for windshields and panoramic roof systems.
- Windshield:Laminated construction pairs two glass plies with polyvinyl butyral interlayers to prevent occupant ejection during collisions. NHTSA rollover retention standards and ADAS sensor mounting requirements are driving thicker interlayer specifications in Southeast assembly corridors.
- Sunroof:Laminated panels with solar-control interlayers enable panoramic roof penetration across electric vehicle platforms prioritizing cabin openness and battery placement flexibility. Zero-emission vehicle mandates in California and New York accelerate demand for larger glass surface areas.
- Side Windows:Tempered glass fragmentation patterns reduce laceration risk in passenger and commercial vehicle doors.
- Back Glass:Tempered construction with integrated defogging elements serves rear visibility and cargo access functions.
Volume placements concentrate in Windshield; the faster expansion belongs to Sunroof.
Material:
Cost tier stratification separates commodity formulations from premium interlayer chemistries as acoustic and solar-control specifications proliferate.
- Laminated Glass:Polyvinyl butyral and acoustic PVB interlayers bond multiple glass plies for shatter-retention performance. OEM long-term supply agreements anchor demand for front glazing and panoramic roof applications.
- Tempered Glass:Thermal strengthening creates controlled fragmentation patterns for side and rear positions. Silica input cost volatility and energy-intensive furnace operations compress fabricator margins in Ohio and Illinois production basins.
- Polycarbonate:Lightweight polymer formulations address weight reduction targets for non-structural glazing positions.
- Others:Chemically strengthened glass enables head-up display compatibility without optical distortion.
Shipments concentrate in Tempered Glass; the steepest expansion trajectory sits with Laminated Glass.
End User:
Customer type determines margin structure and procurement leverage, with long-term platform contracts diverging sharply from episodic replacement demand.
- OEMs:Detroit Three and Tesla assembly programs negotiate multi-year supply agreements tied to vehicle platform lifecycles. Southeast manufacturing corridor expansions in Alabama, South Carolina, and Tennessee pull regional float glass capacity from traditional Ohio and Kentucky supply bases.
- Aftermarket Providers:Mobile glass replacement platforms and direct-to-consumer scheduling capture higher per-unit margins outside dealer networks. Fleet operators and insurance carriers consolidate purchasing through national account structures in Florida and Texas hail damage corridors.
- Repair Shops:Independent installers face optical calibration technician shortages for ADAS-equipped windshield replacement requirements.
- Vehicle Assemblers:Contract manufacturing arrangements for emerging electric vehicle brands drive spot procurement volumes.
Volume concentrates in OEMs; aftermarket channels are gaining share fastest.
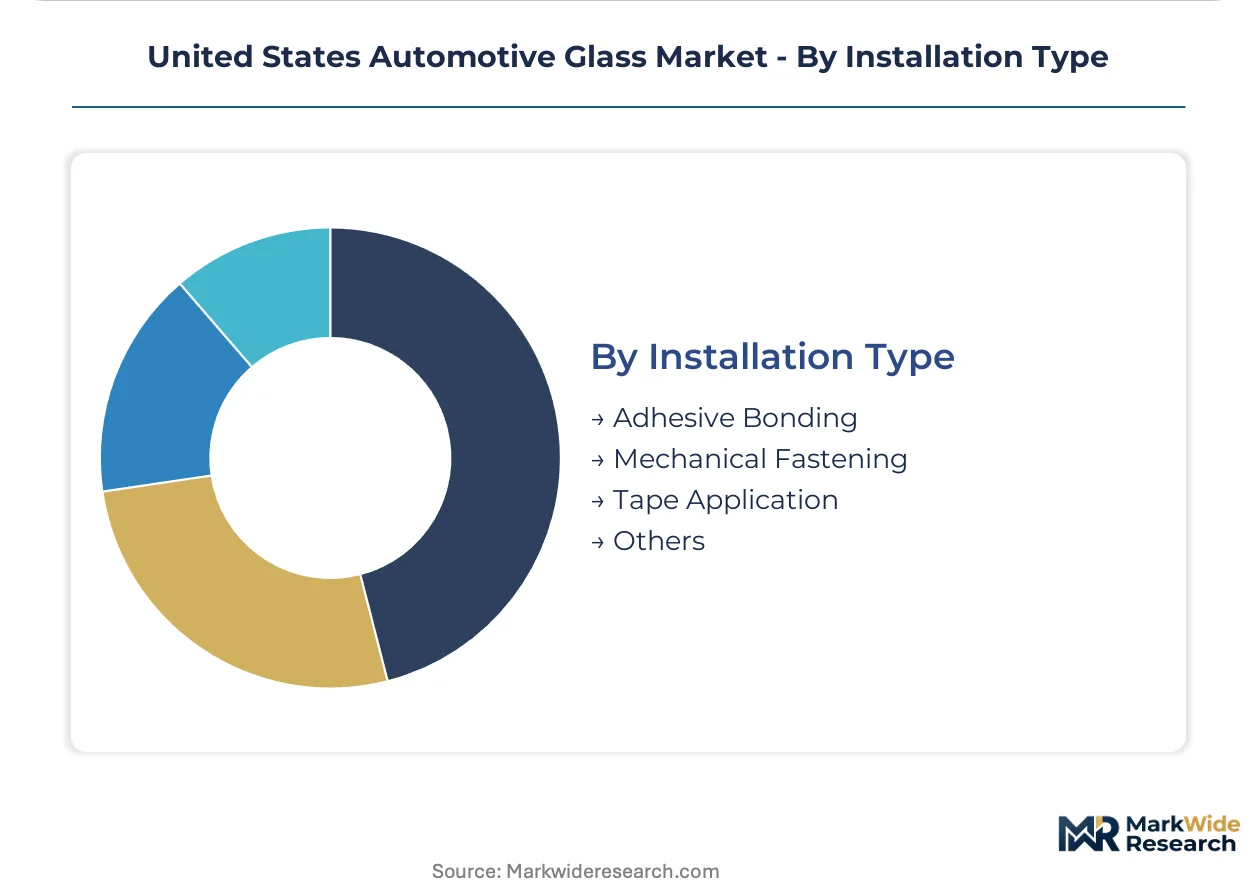
Installation Type:
Application method selection tracks vehicle architecture evolution and repair network capability constraints.
- Adhesive Bonding:Polyurethane structural adhesives enable frameless designs and improved rollover retention per updated NHTSA testing protocols. Edge-bonding chemistry validation requirements extend supplier development cycles.
- Mechanical Fastening:Clip and gasket systems persist in commercial vehicle and heavy-duty applications requiring field serviceability.
- Tape Application:Pressure-sensitive adhesive systems serve temporary positioning and aftermarket repair workflows.
- Others:Hybrid mechanical-adhesive approaches address specific commercial vehicle specifications.
Adhesive Bonding dominates new vehicle assembly; tape-based methods climb fastest in mobile repair segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity silica sand deposits across the upper Midwest anchor domestic float glass production, while automotive assembly concentration in the Southeast reshapes regional supply flows.
Southeast Manufacturing Corridor
Alabama, South Carolina, and Tennessee assembly expansions from Mercedes-Benz, BMW, and Volkswagen pull laminated glass demand southward from traditional Ohio supply bases. NHTSA rollover retention standards for electric vehicle platforms accelerate thicker interlayer specifications in this corridor. Spartanburg and Chattanooga anchor regional logistics networks for just-in-time windshield delivery.
Ohio River Valley
Float glass capacity concentrates along the Ohio River where AGC and Fuyao operate adjacent manufacturing complexes serving Detroit Three assembly plants. EPA fuel economy targets push thinner glass formulations through these legacy production basins. Toledo and Dayton maintain fabrication expertise for ADAS-integrated windshield assemblies.
Illinois Industrial Belt
Chicago-area distribution hubs coordinate tempered glass shipments for commercial vehicle side and rear window replacement networks. OSHA silica exposure controls raise capital requirements for thermal strengthening operations in this corridor. Aurora and Rockford host specialized tempering lines for heavy-duty truck glazing programs.
California ZEV Corridor
Zero-emission vehicle mandates in California accelerate laminated sunroof penetration across Tesla and Rivian assembly programs. CARB regulations exceed federal fuel economy targets, favoring lightweight panoramic roof systems. Fremont and Los Angeles metro areas concentrate EV glass specification engineering and prototype validation.
Texas Aftermarket Hub
Hail damage claim volumes in Dallas-Fort Worth and Houston drive consolidated national account purchasing for replacement windshields. Fleet operators and insurance carriers negotiate bulk procurement through regional distribution centers. San Antonio anchors independent repair network training for ADAS calibration capabilities.
United States Automotive Glass Market Key Industry Players
Global majors compete with regional champions across float glass supply and fabrication specialization, producing a tiered structure where scale-driven interlayer producers coexist with proximity-focused tempering specialists. Three archetypes dominate: integrated float-to-fabrication operators, interlayer technology licensors, and aftermarket-focused mobile service platforms. Capacity expansion in the Southeast corridor and strategic partnerships for ADAS sensor integration represent the dominant competitive moves.
Among integrated glass producers, AGC Inc., Saint-Gobain Sekurit, and Fuyao Glass Industry Group Co., Ltd. occupy positions spanning float capacity and OEM supply relationships. These entities exemplify the scale-driven archetype, with geographic naming conventions indicating Japanese, French, and Chinese origins respectively. Their presence in Ohio and Illinois production basins anchors regional supply security for Detroit Three and transplant assembly programs.
| Leading Market Players |
|---|
| AGC Inc. |
| Saint-Gobain Sekurit |
| Fuyao Glass Industry Group Co., Ltd. |
| Vitro S.A.B. de C.V. |
| Gentex Corporation |
| Nippon Sheet Glass Co., Ltd. |
| Corning Incorporated |
| Guardian Industries |
| Pilkington |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap tempering specialists across the Ohio River Valley anchor regional supply security while exercising disciplined pricing power over aftermarket channels. Their concentrated ownership structures enable long-term contract negotiations with Detroit Three procurement teams without quarterly earnings pressure distorting margin targets.
Pricing Analysis
Warranty-bundled installation services separate national account pricing from unbundled commodity transactions in dealer and independent channels. Three-tier pricing structure across premium acoustic PVB, standard laminated, and economy tempered tiers tracks interlayer chemistry and optical certification grades. Pricing pressure stems from silica input cost volatility compressing fabricator margins in thermal strengthening operations. Fleet operators and insurance carriers exhibit lowest price sensitivity due to consolidated national account structures, while independent repair shops face acute margin constraints.
Supply Chain Analysis
Single-source vulnerability sits with high-purity silica sand extraction from upper Midwest deposits feeding Ohio and Illinois float glass basins. Raw material flows draw from domestic silica deposits, Saudi petrochemical feedstocks for PVB resin, and Canadian soda ash for glass batch formulations. Tariff exposure on Chinese finished glass imports creates strategic risk for OEMs seeking cost-competitive laminated windshields. Distribution runs through regional float-to-fabrication complexes co-located with Southeast and Midwest assembly corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as NHTSA rollover retention standards and ADAS calibration complexity force sub-scale fabricators toward exit or acquisition. Capital intensity for tempering line upgrades and optical-grade laminated capacity favors players with multi-platform contract visibility.
For Market Incumbents: Acquire distressed tempering assets in the Illinois Industrial Belt to secure thermal strengthening capacity ahead of commercial vehicle glazing demand recovery. Prioritize backward integration into acoustic PVB interlayer production to capture premium specification premiums from BMW and Mercedes-Benz programs. Defend against mobile glass replacement platform encroachment by embedding calibration capabilities within dealer network service contracts. For New Entrants and Emerging Players: Independent repair shops lacking ADAS calibration technicians represent the most penetrable buyer archetype for specialized service partnerships. Target mobile replacement platforms in Texas hail damage corridors through white-label calibration-as-a-service offerings. Pursue direct procurement relationships with emerging electric vehicle assemblers bypassing established Tier 1 supply hierarchies. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap laminated specialists with Southeast corridor proximity and existing OEM platform qualifications. Long-term viability hinges on chemical strengthening process capabilities for head-up display compatibility across premium and mass-market vehicle programs. Watch NHTSA glazing material standard revision timing as inflection indicator for interlayer specification upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Acoustic Interlayer Capacity Expansion | Captures premium positioning as BMW and Mercedes-Benz mandate 4-6 decibel interior noise reduction specifications. |
| ADAS Calibration Service Integration | Secures aftermarket margin capture against mobile replacement platforms through embedded recalibration capabilities. |
| Southeast Manufacturing Footprint Addition | Reduces logistics costs for just-in-time windshield delivery to Alabama, South Carolina, and Tennessee assembly plants. |
| Chemical Strengthening Process Investment | Enables head-up display compatibility without optical distortion for next-generation premium vehicle programs. |
| Domestic Float Glass Supply Agreement | Qualifies for IRA clean vehicle credits favoring U.S.-based fabrication over imported finished glass. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and dealership service operations. NHTSA Federal Motor Vehicle Safety Standard 205 documentation, EPA fuel economy compliance reports, and vehicle production databases from IHS Markit provided segmentation foundations. Bottom-up volume modeling triangulated against top-down market sizing across laminated and tempered glass categories.
Data-stream reconciliation merged installation type splits with regional production cluster concentrations over the projection horizon. Segmentation dimensions spanned product type, material chemistry, end-user category, and propulsion architecture. CAGRs derived from platform lifecycle timing and replacement rate assumptions specific to electric vehicle panoramic roof penetration trends. Silica input cost trajectories and interlayer technology substitution curves informed scenario boundaries.
Revisions become necessary when NHTSA testing protocol updates, IRA domestic content rule changes, or ADAS sensor integration specification shifts materialize outside modeled assumptions. Forecasts reflect documented judgments about platform adoption curves and regional assembly expansion timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Russia Automotive Parts Magnesium Die Casting Market
Automotive Parts
Engine Oil Pan Market
Automotive Parts
Global Truck Refrigeration Unit Market
Automotive Parts
Automotive Roller Bearing Market
Automotive Parts
Vietnam Commercial Vehicles Lubricants Market
Automotive Parts
Constant Velocity Joint Market
Automotive Parts
Automotive Coolant Pump Market
Automotive Parts
Automotive Axle and Propeller Shaft Market
Automotive Parts
Automotive Brake Friction Materials Market
Automotive Parts
Leaf Spring Shackle Side Bar Market
Automotive Parts
South America Automotive Engine Oils Market
Automotive Parts
Brazil Automotive Parts Zinc Die Casting Market
Automotive Parts
Japan Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Suspension Control Arms Market
Automotive Parts
Global Automotive Gasoline Particulate Filter (GPF) Market
Automotive Parts
Rear Spoiler Market