
 Brain Tissue Oxygen Monitoring Systems Market | 2026-2036
Brain Tissue Oxygen Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Brain Tissue Oxygen Monitoring Systems Market Analytics
Neurocritical care specialist training pipelines is collapsing across multiple OECD health systems, constraining bedside deployment of advanced neuromonitoring even where capital budgets exist. Integra LifeSciences anchors its position through deep specialization in invasive probe design and direct hospital contracting. Oxford Optronix competes via optical sensor R&D intensity and sustained publication partnerships with European neurotrauma centers. Medtronic leverages its broader critical care ecosystem to bundle brain tissue oxygen monitors with intracranial pressure systems, extending account control within integrated delivery networks.
Brain tissue oxygen monitoring systems measure partial pressure of oxygen in cerebral parenchyma using electrochemical or optical transduction, typically targeting tissue oxygen tension thresholds below 20 mmHg to flag ischemic risk during neurosurgery or traumatic brain injury management. Invasive monitors with catheter-integrated microelectrodes dominate current hospital procurement, reflecting established reimbursement codes and clinician familiarity, while wireless systems represent the fastest-expanding segment as manufacturers miniaturize telemetry hardware for step-down unit transfers. Optical sensors command premium pricing in research institute segments where non-invasive longitudinal monitoring supports stroke recovery protocols.
FDA 510(k) pathways and EU MDR conformity assessments shape sensor validation requirements and prolong commercialization timelines for novel transduction chemistries. Health Canada and TGA alignment with ISO 10993 biocompatibility standards further fragments regulatory submission strategies for multi-territory launches. Stakeholders must monitor evolving CMS National Coverage Determination language around neuromonitoring in traumatic brain injury, as reimbursement ambiguity poses the primary barrier to volume expansion outside academic referral centers.
Market Dynamics
The brain tissue oxygen monitoring systems market pivots on a structural shortage of neurocritical care specialists, constraining bedside deployment of invasive probes even where hospital capital budgets permit equipment acquisition. This talent bottleneck shapes competitive strategy more than sensor innovation cycles.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited clearance for predicate-device-based submissions accelerates commercialization timelines for electrochemical microelectrode upgrades in US tertiary hospitals.
- Traumatic brain injury protocol standardization:Military medical centers and civilian trauma networks embed tissue oxygen tension monitoring into tiered neuroprotection algorithms, creating procedural pull-through demand.
- Optical sensor miniaturization:Photonic integration reduces probe diameter below 0.5mm, enabling parenchymal placement in pediatric neurosurgical populations previously excluded from invasive monitoring.
Market Restraints
- Platinum-iridium electrode supply concentration:Three Japanese and German specialty metal refiners control microelectrode conductor feedstock, exposing manufacturers to spot price volatility and allocation risk.
- EU MDR conformity assessment backlog:Notified body capacity constraints extend optical sensor validation timelines by 14-22 months, freezing European launch schedules for novel transduction chemistries.
- Non-invasive near-infrared spectroscopy substitution:Cerebral oximetry systems from critical care monitoring incumbents capture step-down unit cases where tissue oxygen tension precision is clinically negotiable.
Strategic Opportunities
- Brazil ANVISA pathway alignment:Harmonized ISO 10993 biocompatibility documentation permits synchronized FDA-ANVISA submissions, opening Latin American trauma center procurement previously accessed only through distributor gray channels.
- Stroke rehabilitation extension:Longitudinal optical monitoring during subacute recovery phases creates ambulatory revenue streams outside acute hospital reimbursement frameworks.
- Wireless telemetry bundling:Integration with step-down unit transfer protocols differentiates vendor offerings in integrated delivery network competitive tenders.
Industry Challenges
- Neurocritical care fellowship pipeline collapse:US and UK training program enrollment declines restrict bedside expertise required for invasive probe placement and data interpretation.
- Legacy intracranial pressure system integration:Proprietary digital interfaces from established monitoring vendors force middleware development costs on tissue oxygen sensor manufacturers seeking ecosystem compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brain Tissue Oxygen Monitoring Systems Market |
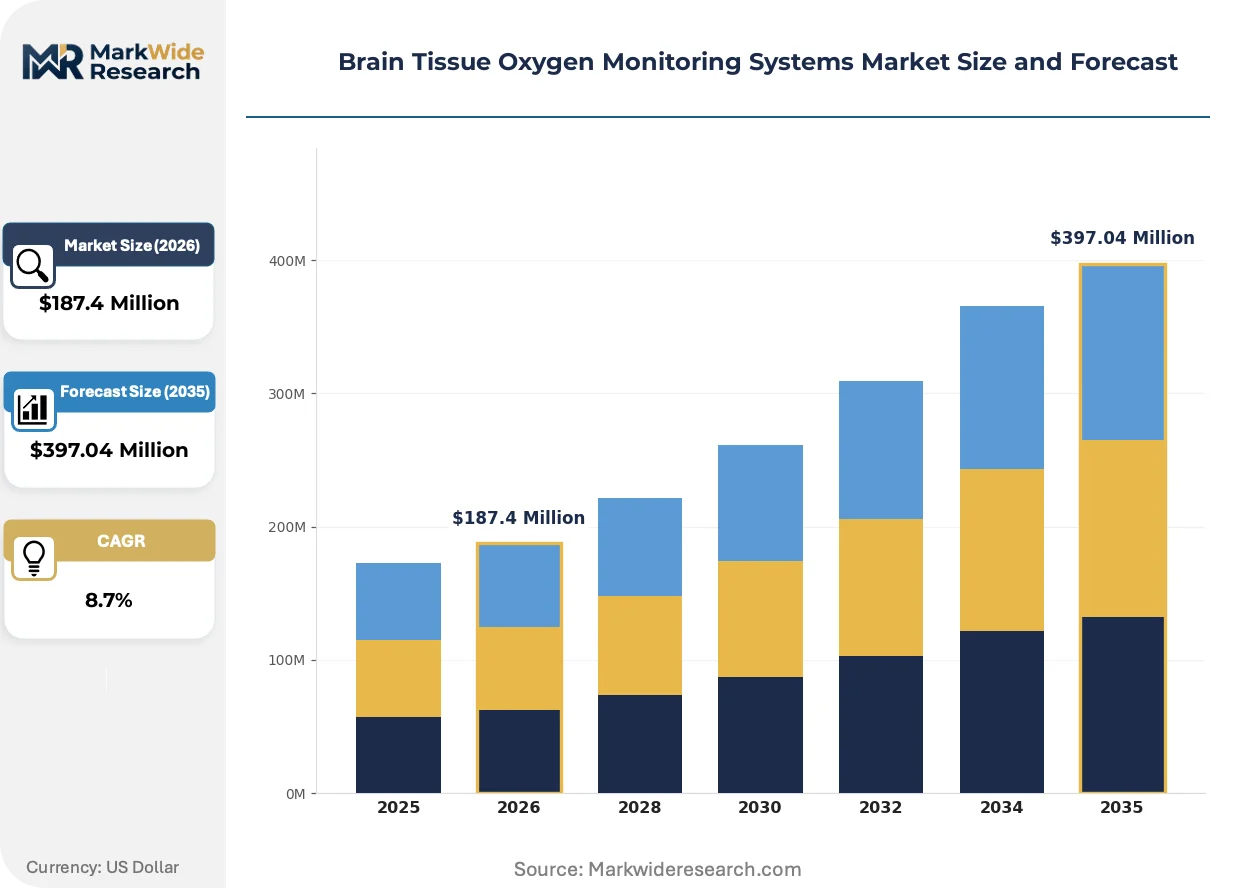
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Invasive Monitors, Non-invasive Monitors, Wireless Systems, Portable Systems End User: Hospitals, Research Institutes, Rehabilitation Centers, Emergency Departments Technology: Electrochemical Sensors, Optical Sensors, Laser-Based Systems, Microelectrode Techniques Application: Cerebral Ischemia, Traumatic Brain Injury, Stroke, Neurosurgery |
| Companies Covered | Oxford Optronix, GE Healthcare, Integra LifeSciences, Mespere LifeSciences, Artinis Medical Systems, Hamamatsu Photonics, Masimo Corporation, Ornim Medical, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brain Tissue Oxygen Monitoring Systems Market Evolving Landscape
Sensor architecture is splitting into divergent technical paths optimized for acute surgical precision versus longitudinal ambulatory monitoring, reshaping R&D resource allocation and partnership strategies across the competitive landscape.
Miniaturized optical phosphorescence quenching sensors is bifurcating the product landscape. Research institutes at Johns Hopkins University and Charité Berlin deploy these systems for continuous parenchymal monitoring during stroke recovery protocols. The technology compresses addressable market overlap with electrochemical incumbents by serving use cases where probe longevity exceeds oxygen tension accuracy.
EU MDR Article 117 device-drug combination requirements now capture antimicrobial-impregnated catheter coatings. Manufacturers reformulating silver-ion elution profiles must resubmit technical documentation through notified bodies in Germany and the Netherlands. Neurosurgical probe suppliers with legacy FDA 510(k) predicates face parallel European validation burdens that delay synchronized launch schedules.
Hospital procurement committees now unbundle neuromonitoring hardware from disposable sensor contracts. Academic medical centers in the United States negotiate separate vendor relationships for capital equipment and recurring probe supply, compressing multi-year sole-source agreements into annual competitive tenders. This pattern concentrates purchasing leverage within supply chain departments and away from individual neurosurgeon preference.
Brain Tissue Oxygen Monitoring Systems Market Segmentation
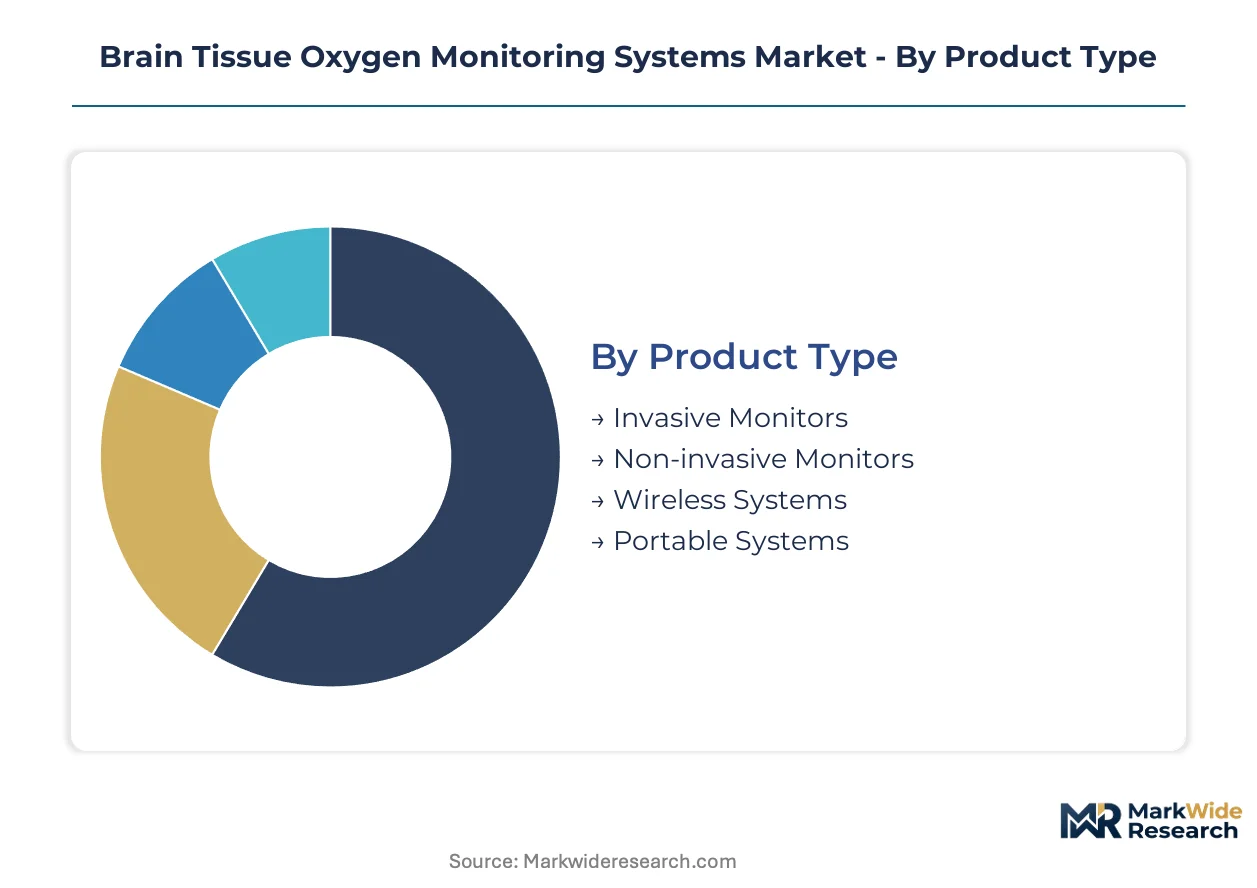
Segmentation in brain tissue oxygen monitoring systems reveals how substitution pressures reshape procurement decisions across acute and longitudinal care settings. Product architecture, end-user economics, and technology validation requirements create divergent competitive arenas that vendors must navigate simultaneously.
Product Type:
Non-invasive monitors face the strongest substitution threat from cerebral oximetry systems, compressing their addressable market to research applications where tissue oxygen tension precision remains non-negotiable.
- Invasive Monitors:Catheter-integrated microelectrodes deliver real-time parenchymal oxygen tension readings with platinum-iridium conductors. Tertiary hospital neurosurgical units in the United States anchor procurement volume, constrained by FDA 510(k) predicate requirements and established reimbursement codes.
- Wireless Systems:Miniaturized telemetry hardware enables step-down unit transfers without monitor disconnection. Integrated delivery networks in Germany and Australia prioritize these systems for competitive tender differentiation, though neurocritical care specialist shortages limit bedside deployment.
- Non-invasive Monitors:Near-infrared and optical phosphorescence quenching approaches serve pediatric populations and stroke recovery protocols. Johns Hopkins University and Charité Berlin deploy these for longitudinal monitoring where probe longevity outweighs absolute accuracy.
- Portable Systems:Battery-powered units support emergency department triage and field military medicine. Health Canada and TGA alignment with ISO 10993 standards shapes multi-territory launch strategies for these mobile configurations.
Invasive monitors anchor the volume base while wireless systems gain share at the steepest rate.
End User:
Cost tier stratification separates capital-intensive hospital installations from research grant-funded procurement, with reimbursement ambiguity creating the widest pricing spreads.
- Hospitals:Academic medical centers and tertiary neurosurgical units drive electrochemical probe adoption through established clinical protocols. CMS National Coverage Determination language around traumatic brain injury neuromonitoring directly shapes US volume.
- Research Institutes:Optical sensor validation partnerships with European neurotrauma centers sustain publication-driven demand. EU MDR Article 117 device-drug combination requirements now capture antimicrobial-impregnated catheter coatings, extending validation timelines.
- Rehabilitation Centers:Subacute stroke recovery monitoring creates ambulatory revenue streams outside acute hospital reimbursement frameworks. Brazil ANVISA pathway alignment permits synchronized FDA submissions for Latin American expansion.
- Emergency Departments:Trauma protocol standardization at military medical centers and civilian networks embeds tissue oxygen tension monitoring into tiered neuroprotection algorithms.
Hospitals dominate capital expenditure while rehabilitation centers expand the addressable market beyond traditional acute care boundaries.
Technology:
Supply concentration in Japanese and German specialty metal refiners exposes electrochemical approaches to feedstock volatility, tilting R&D toward optical alternatives.
- Electrochemical Sensors:Microelectrode arrays with platinum-iridium conductors measure partial pressure of oxygen through redox reactions. Three Asian and European refiners control conductor feedstock, creating allocation risk for manufacturers.
- Optical Sensors:Phosphorescence quenching and fiber-optic approaches enable sub-0.5mm probe diameters for pediatric neurosurgical populations. Photonic integration reduces diameter constraints previously excluding younger patients.
- Laser-Based Systems:Spectroscopic tissue interrogation supports non-invasive cerebral oxygenation mapping. Research applications at academic medical centers validate clinical utility before hospital procurement.
- Microelectrode Techniques:Multi-site array configurations enable spatial oxygen tension mapping across injured brain regions. Proprietary digital interfaces from established monitoring vendors force middleware development costs on integration.
Electrochemical sensors retain the installed base while optical approaches climb the fastest toward new patient populations.
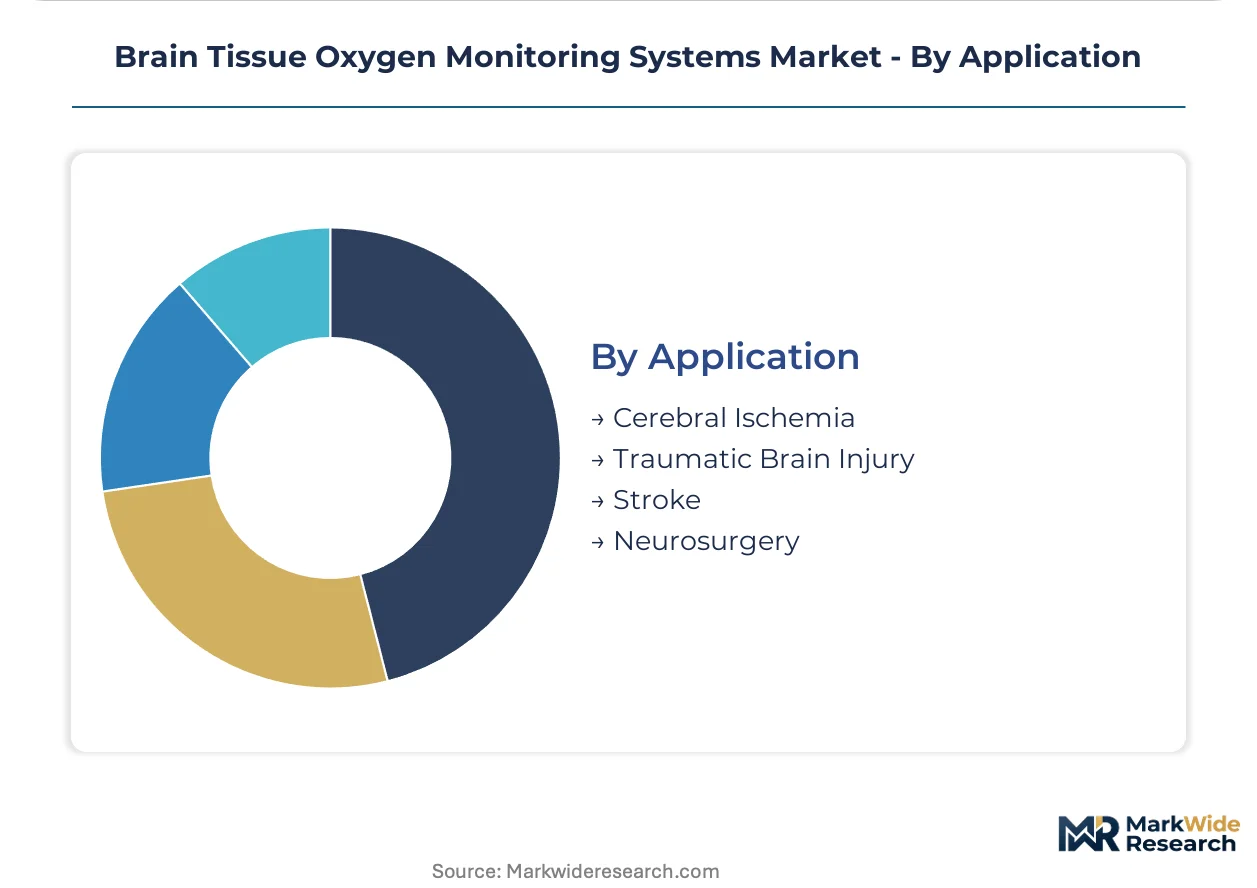
Application:
Protocol maturity varies sharply across indications, with traumatic brain injury standardization furthest advanced and stroke recovery monitoring still building clinical evidence.
- Traumatic Brain Injury:Tiered neuroprotection algorithms at military and civilian trauma networks create procedural pull-through demand. FDA clearance pathways for sensor upgrades accelerate commercialization timelines.
- Neurosurgery:Real-time cerebral oxygenation data during critical procedures drives invasive probe placement in operating theaters. Neurocritical care fellowship pipeline collapses in the US and UK constrain bedside expertise.
- Cerebral Ischemia:Tissue oxygen tension thresholds below 20 mmHg flag ischemic risk during cardiac surgery and carotid endarterectomy. Optical sensors command premium pricing where longitudinal monitoring supports protocol development.
- Stroke:Subacute recovery phase monitoring creates ambulatory revenue opportunities outside traditional hospital reimbursement. Wireless telemetry bundling with step-down unit transfers differentiates vendor offerings.
Traumatic brain injury anchors clinical validation while stroke applications expand fastest into longitudinal care settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds German benchmarks by substantial margins, while Japanese procurement committees extract steeper discounts from platinum-iridium suppliers than their European counterparts.
United States
Academic medical centers in Boston and Baltimore drive electrochemical probe procurement through established CMS reimbursement codes. FDA 510(k) pathway streamlining accelerates commercialization timelines for predicate-device submissions. The Johns Hopkins neurotrauma cluster validates optical sensor protocols for stroke recovery monitoring.
Germany
Integrated delivery networks in Bavaria and North Rhine-Westphalia prioritize wireless telemetry systems for step-down unit transfers. EU MDR conformity assessment backlogs extend optical sensor validation timelines by 14-22 months. The Charité Berlin research partnership sustains publication-driven demand for phosphorescence quenching approaches.
Japan
Tertiary neurosurgical units in Tokyo and Osaka anchor platinum-iridium microelectrode consumption despite spot price volatility. METI industrial standards shape biocompatibility documentation requirements for antimicrobial-impregnated catheter coatings. Hamamatsu Photonics anchors photonic sensor R&D intensity in the Chubu region.
Australia
Trauma networks in New South Wales and Victoria embed tissue oxygen tension monitoring into tiered neuroprotection algorithms. TGA alignment with ISO 10993 standards fragments multi-territory launch strategies for portable system configurations. The Royal Melbourne Hospital cluster validates wireless telemetry bundling for integrated delivery network tenders.
Brazil
Emergency departments in São Paulo and Rio de Janeiro create procurement demand through trauma protocol standardization. ANVISA pathway alignment with FDA submissions opens Latin American markets previously accessed through distributor gray channels. The Albert Einstein Hospital network anchors clinical validation for subacute stroke recovery monitoring.
Brain Tissue Oxygen Monitoring Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with electrochemical specialists commanding premium pricing in tertiary hospitals while optical innovators capture research grant funding. The vendor base consolidates around three strategic tiers: diversified critical care conglomerates bundling brain tissue oxygen monitors with intracranial pressure systems; mid-cap neuromonitoring specialists with deep probe design expertise; and photonics-focused R&D shops leveraging academic partnerships. Dominant competitive moves include strategic partnerships with neurotrauma centers for clinical validation and geographic expansion through synchronized FDA-ANVISA regulatory submissions.
Among diversified critical care conglomerates, Medtronic and GE Healthcare occupy positions spanning hospital capital equipment through disposable sensor supply chains. Integra LifeSciences exemplifies the neuromonitoring specialist archetype with concentrated expertise in invasive probe design. Oxford Optronix sits within the photonics R&D tier, sustaining publication partnerships with European neurotrauma centers. These three company groupings represent the primary competitive vectors reshaping procurement committee negotiations.
| Leading Market Players |
|---|
| Oxford Optronix |
| GE Healthcare |
| Integra LifeSciences |
| Mespere LifeSciences |
| Artinis Medical Systems |
| Hamamatsu Photonics |
| Masimo Corporation |
| Ornim Medical |
| Medtronic |
| Others |
Value Network & Pricing Analysis
Optical phosphorescence quenching sensors displacing electrochemical microelectrodes in pediatric and stroke recovery applications simultaneously shifts supply geography toward Japanese photonics clusters and compresses pricing premiums previously sustained by platinum-iridium conductor scarcity.
Pricing Analysis
Configured-to-order pricing for catheter-integrated microelectrodes commands substantial premiums over standard electrochemical probe configurations. Pricing stratifies across FDA 510(k) predicate tiers, with novel optical transduction chemistries carrying certification-level premiums. Cost compression in wireless telemetry hardware intensifies as integrated delivery networks unbundle capital equipment from disposable contracts. Academic medical centers exhibit lowest price sensitivity due to grant-funded procurement, while community hospitals face acute budget constraints.
Supply Chain Analysis
Strategic stockpiling of platinum-iridium feedstock dominates inventory strategy among electrochemical sensor manufacturers facing Japanese and German refiner allocation risk. Supply concentrates in Japan, Germany, and the United States for specialty metal conductors and photonic components. Raw material dependencies span platinum-iridium alloys, optical fibers, and antimicrobial silver-ion coatings. Single-source vulnerability in microelectrode conductor feedstock exposes manufacturers to spot price volatility. Distribution runs through hospital procurement committees and GPO contracts in integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bedside expertise scarcity in neurocritical care constrains volume expansion regardless of capital equipment availability, making specialist training pipeline investments the decisive capability gap for market participants.
For Market Incumbents: Compound ecosystem control through backward integration into proprietary digital interfaces that force middleware costs on optical sensor challengers seeking intracranial pressure system compatibility. Lock in multi-year disposable probe supply agreements with academic medical centers before procurement committee unbundling accelerates. The threat of wireless telemetry commoditization demands preemptive bundling with step-down unit transfer protocols. For New Entrants and Emerging Players: Anchor in Brazil ANVISA pathway alignment to bypass distributor gray channels and access Latin American trauma center procurement directly. Target subacute stroke rehabilitation monitoring where reimbursement ambiguity has kept incumbents focused on acute care. A software companion development strategy for longitudinal optical monitoring data platforms offers the cleanest go-to-market angle. For Investors and Strategic Acquirers: The market sits at a protocol standardization phase that favors photonics-focused R&D shops with publication partnerships at European neurotrauma centers. Long-term viability hinges on ambulatory revenue streams outside hospital reimbursement frameworks. Watch FDA 510(k) pathway streamlining announcements as the inflection indicator for electrochemical incumbent valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Expedited clearance for predicate-device electrochemical upgrades accelerates US commercialization timelines. |
| CE Marking Pathway | EU MDR conformity assessment navigation determines European launch synchronization for optical sensors. |
| Hospital System Partnership | Direct contracting with academic medical centers secures clinical validation and procurement committee access. |
| Software Companion Development | Longitudinal data platforms for stroke recovery monitoring create ambulatory revenue outside acute reimbursement. |
| Reimbursement Strategy | CMS National Coverage Determination alignment shapes volume expansion beyond grant-funded academic centers. |
Research Methodology
The analysis maps invasive monitors, wireless systems, non-invasive optical sensors, and portable configurations, each validated through neurocritical care specialists, hospital procurement managers, biomedical engineers, and GPO contracts managers. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up probe shipment estimates and top-down tertiary hospital capital expenditure triangulation anchored volume projections.
Consistency checks against external benchmarks validated analytical framework outputs across the projection horizon. Segmentation dimensions modeled include product architecture, end-user economics, technology validation requirements, and application protocol maturity. CAGRs derived from weighted average growth contributions across electrochemical and optical technology paths. Forecast inputs incorporated neurocritical care fellowship enrollment trajectories and regulatory pathway timeline assumptions.
Material uncertainties — reimbursement policy reversals, EU MDR notified body capacity constraints, platinum-iridium supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about protocol standardization velocity and specialist pipeline recovery. Revision becomes warranted when CMS National Coverage Determination language crosses thresholds that fundamentally alter hospital procurement economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Monitoring Wristband Market
Patient Monitoring
Global Epilepsy Monitoring Devices Market
Patient Monitoring
Middle East and Africa Patient Monitoring Market
Patient Monitoring
Online Patient Observation Market
Patient Monitoring
Middle East and Africa Body Temperature Monitoring Market
Patient Monitoring
Global Anaesthesia Monitoring Devices Market
Patient Monitoring
South Korea Patient Monitoring Market
Patient Monitoring
Real-Time Location System (RTLS) in Healthcare Market
Patient Monitoring
Mobile Continuous Patient Monitors Market
Patient Monitoring
Wireless Patient Monitoring Market
Patient Monitoring
Wearable Heart Monitoring Devices Market
Patient Monitoring
North America Self-Monitoring Blood Glucose Market
Patient Monitoring
Australia Patient Monitoring Market
Patient Monitoring
Europe Biomedical Sensors Market
Patient Monitoring
Patient Monitoring and Ultrasound Devices Display Market
Patient Monitoring
Germany Patient Care Monitoring Equipment Market