
 Global Delivery Management Software Market | 2026-2036
Global Delivery Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Delivery Management Software Market Foresight
Direct software sales through vendor-owned channels is fragmenting as cloud marketplaces and systems integrators capture larger shares of delivery management procurement. Bringg leverages its API-first architecture to sustain enterprise relationships across multiple continents. FarEye anchors its position through deep specialization in last-mile orchestration for pharmaceutical logistics. Onfleet competes aggressively on ease of deployment for mid-market courier services.
Delivery management software comprises cloud-native, on-premise, and edge-deployed platforms that ingest GPS telemetry, order data, and traffic feeds to compute dynamic routing, fleet dispatch, and proof-of-capture workflows in real time. The primary commercial purpose centers on minimizing cost-per-delivery while maximizing on-time performance and customer visibility. Cloud-based deployment leads current adoption among third-party logistics operators seeking elastic infrastructure, while edge computing represents the fastest-growing architecture for real-time fleet tracking in bandwidth-constrained corridors. Route optimization commands the deepest margin pools due to its direct fuel and labor savings, though customer notifications is gaining traction as a retention tool for parcel service providers.
FDA traceability rules for pharmaceutical distribution and the EU AI Act's risk classification for automated dispatch algorithms are tightening compliance requirements across vendor development roadmaps. India's BIS cloud security standards and CDSCO cold-chain documentation mandates are creating additional certification barriers for platforms serving pharmaceutical logistics. Stakeholders must monitor how divergent data sovereignty frameworks across the United States, European Union, and India reshape hosting architectures and cross-border feature parity.
Market Dynamics
API-first architectures are fragmenting procurement channels as cloud marketplaces and systems integrators displace direct vendor sales, forcing incumbents to restructure partner programs and pricing tiers to retain enterprise accounts.
Growth Catalysts
- EU AI Act algorithmic risk classification:Automated dispatch systems face mandatory conformity assessments, creating certified vendor demand among pharmaceutical logistics operators seeking compliant platforms.
- India domestic e-commerce infrastructure buildout:Third-party logistics providers and courier networks are scaling digital fleet management to serve platform-driven parcel volume expansion.
- Edge computing deployment:Real-time GPS telemetry processing in bandwidth-constrained corridors enables sub-second routing recalculation for cold-chain and high-value cargo segments.
Market Restraints
- GDPR data residency mandates:Cross-border feature parity requirements force redundant hosting architectures, elevating operational overhead for multi-continental deployments.
- Cloud infrastructure cost volatility:Elastic compute pricing uncertainty compresses margins for usage-based SaaS delivery platforms serving seasonal demand swings.
- Telematics hardware supply concentration:GPS sensor and IoT gateway sourcing clusters in East Asian manufacturing regions expose fleet operators to single-source vulnerability.
Strategic Opportunities
- Brazil pharmaceutical cold-chain digitization:ANVISA temperature documentation mandates create whitespace for route-optimization platforms with integrated sensor telemetry and audit-trail capabilities.
- Subscription-based outcome pricing:Fuel-savings guarantees and on-time-performance SLAs displace seat-based licensing among cost-conscious mid-market courier services.
- 5G-V2X convergence:Vehicle-to-infrastructure communication integration with dynamic routing engines enables predictive traffic avoidance for urban last-mile density.
Industry Challenges
- Legacy TMS integration complexity:Enterprise shippers maintain decades-old transportation management systems requiring custom API middleware and extended deployment timelines.
- Multi-jurisdiction certification cadence:Simultaneous FDA traceability, EU AI Act, and BIS cloud security audits strain vendor product development bandwidth and release cycles.
- Edge-to-cloud synchronization latency:Real-time fleet tracking demands sub-100-millisecond data consistency across distributed architectures, challenging engineering resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Delivery Management Software Market |
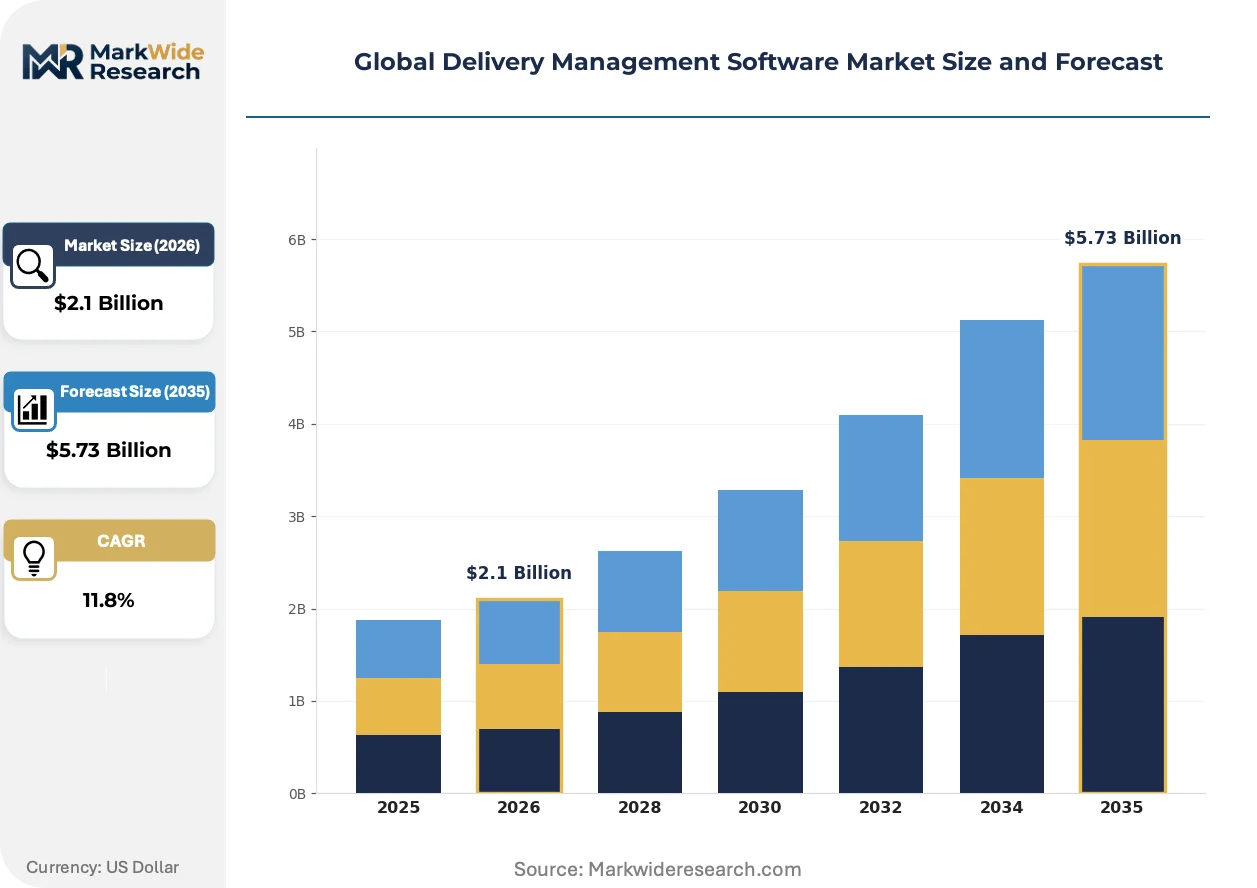
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.73 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing Solution Offering: Route Optimization, Fleet Tracking, Proof of Delivery, Inventory Management, Customer Notifications Use Case: Last Mile Delivery, Courier Services, Food & Beverage Distribution, Pharmaceutical Logistics, E-commerce Fulfillment End User Industry: Transportation Providers, Logistics Operators, Warehousing Companies, Third-Party Logistics, Parcel Service Providers |
| Companies Covered | Bringg, FarEye, Onfleet, Loginext Solutions, GetSwift, WorkWave, DispatchTrack, Project44, Zebra Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Delivery Management Software Market Shifts & Advancements
Automated dispatch intelligence is compressing decision cycles from hours to seconds, while compliance architecture and procurement models undergo parallel restructuring to match regulatory velocity and buyer risk preferences.
Dynamic routing engines are migrating from batch overnight optimization to continuous recalculation architectures. Pharmaceutical distributors and grocery networks with temperature-sensitive cargo are adopting these systems fastest. The technology shift is collapsing planning windows and enabling same-day service promises previously structurally uneconomical.
The EU AI Act's risk-tiered conformity framework is mandating algorithmic audit trails for automated dispatch systems. Vendors must now document training data provenance and decision logic for high-risk logistics applications. European pharmaceutical carriers are prioritizing platforms with pre-certified compliance modules to accelerate deployment timelines.
Buyer preference for consumption-based pricing is displacing perpetual licenses across third-party logistics procurement. Large freight forwarders and regional courier cooperatives now demand fuel-savings guarantees and on-time-performance penalties embedded in contracts. This shift is most pronounced in Germany and the Netherlands, where logistics outsourcing maturity supports outcome-based commercial terms.
Global Delivery Management Software Market Segmentation
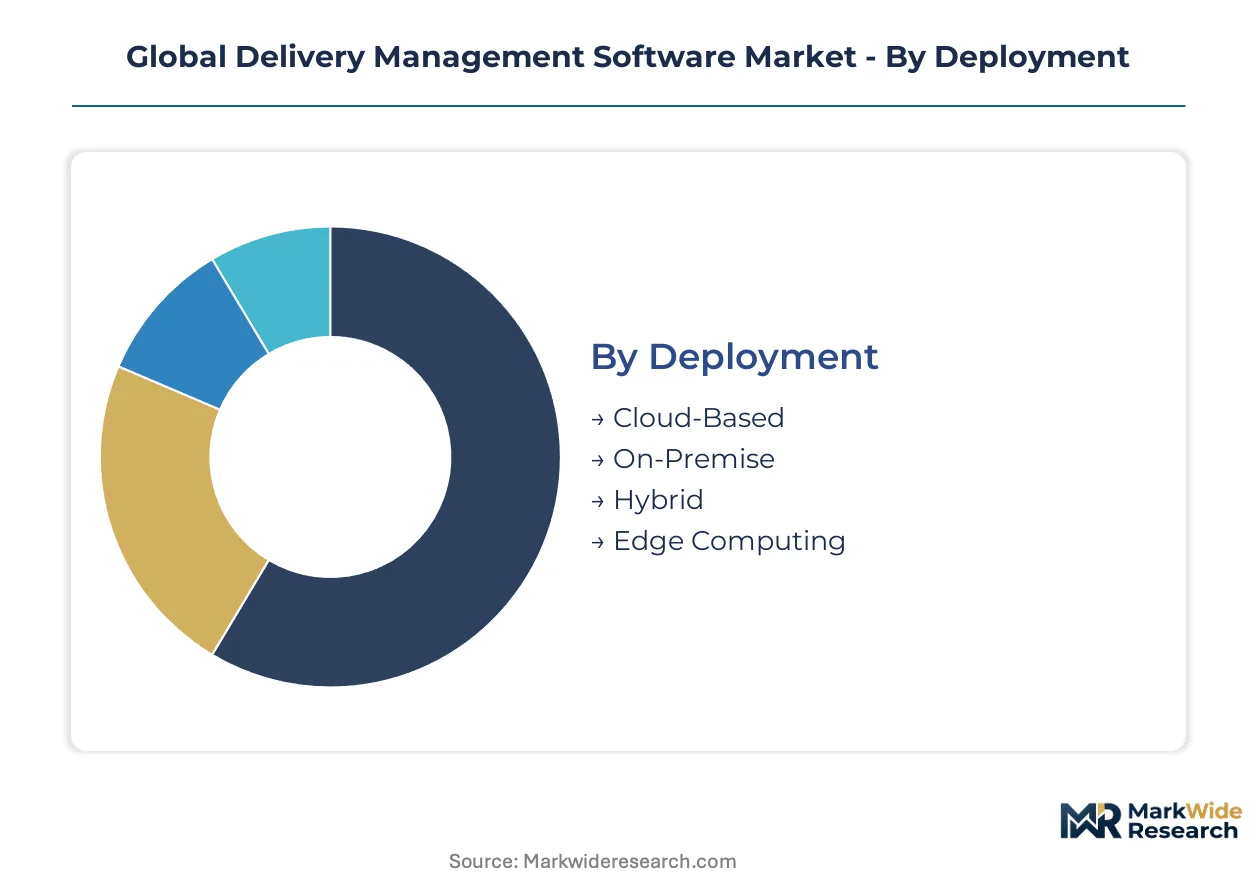
Segmentation in delivery management software reveals how procurement priorities diverge across infrastructure constraints, operational workflows, and regulatory exposure. Deployment architecture and solution bundling decisions cascade through compliance costs, integration complexity, and scalability thresholds.
Deployment:
Use-case spectrum spans hyperscale e-commerce platforms requiring elastic compute to cold-chain operators demanding sub-second telemetry processing in connectivity-deprived corridors.
- Cloud-Based:Multi-tenant SaaS architectures dominate third-party logistics procurement in Germany and the Netherlands, where freight forwarders prioritize rapid deployment over customization depth. GDPR data residency mandates force EU-specific hosting partitions, elevating operational overhead for vendors serving multi-continental accounts.
- Edge Computing:Distributed processing nodes enable real-time GPS telemetry ingestion and dynamic routing recalculation without cloud round-trips. Pharmaceutical distributors in India deploy edge clusters to satisfy CDSCO cold-chain documentation requirements in bandwidth-constrained last-mile corridors.
- On-Premise:Air-gapped installations persist among defense contractors and government postal services with classified cargo protocols.
- Hybrid:Split architectures synchronize sensitive dispatch logic locally while pushing analytics workloads to public cloud infrastructure.
The dominant share belongs to Cloud-Based deployment, while Edge Computing is closing the gap fastest.
Solution Offering:
Margin pools concentrate where fuel and labor savings materialize fastest, with notification modules gaining traction as retention instruments for parcel operators facing churn pressure.
- Route Optimization:Algorithmic engines ingest traffic feeds, order density patterns, and vehicle capacity constraints to minimize cost-per-delivery. Courier cooperatives in Brazil demand fuel-savings guarantees embedded in outcome-based contracts, displacing seat-based licensing.
- Customer Notifications:Real-time ETA propagation and proof-of-capture alerts reduce missed-delivery rates. E-commerce fulfillment platforms in India deploy these modules to defend Net Promoter Scores against platform-driven volume surges.
- Fleet Tracking:GPS telemetry aggregation with geofencing and driver behavior scoring serves high-value cargo segments.
- Proof of Delivery:Digital signature, photo capture, and barcode verification workflows accelerate accounts receivable cycles.
- Inventory Management:Warehouse-to-vehicle synchronization reduces stockout incidents for grocery networks with perishable SKU complexity.
Route Optimization commands the deepest margin pools, though Customer Notifications is expanding most quickly as a churn-prevention investment.
Use Case:
Application maturity varies sharply: pharmaceutical cold-chain demands audit-trail rigor, while food delivery prioritizes speed over documentation depth.
- Last Mile Delivery:Dense urban routing with dynamic recalculation addresses same-day service promises. Platform economies in India drive third-party logistics scaling, with Bringg and FarEye anchoring enterprise relationships through API-first architectures.
- Pharmaceutical Logistics:Temperature excursion alerts, chain-of-custody documentation, and FDA traceability compliance define platform selection. EU AI Act algorithmic risk classification mandates conformity assessments for automated dispatch systems serving European carriers.
- E-commerce Fulfillment:Peak-season elasticity requirements favor cloud-native procurement with consumption-based pricing.
- Courier Services:Mid-market operators compete aggressively on deployment velocity and ease of use.
- Food & Beverage Distribution:Perishability windows compress planning horizons, favoring continuous optimization over batch routing.
Last Mile Delivery retains volume leadership, while Pharmaceutical Logistics is gaining share fastest on regulatory tailwinds.
End User Industry:
Customer type determines procurement channel: direct vendor sales fragment as cloud marketplaces and systems integrators capture larger shares of enterprise accounts.
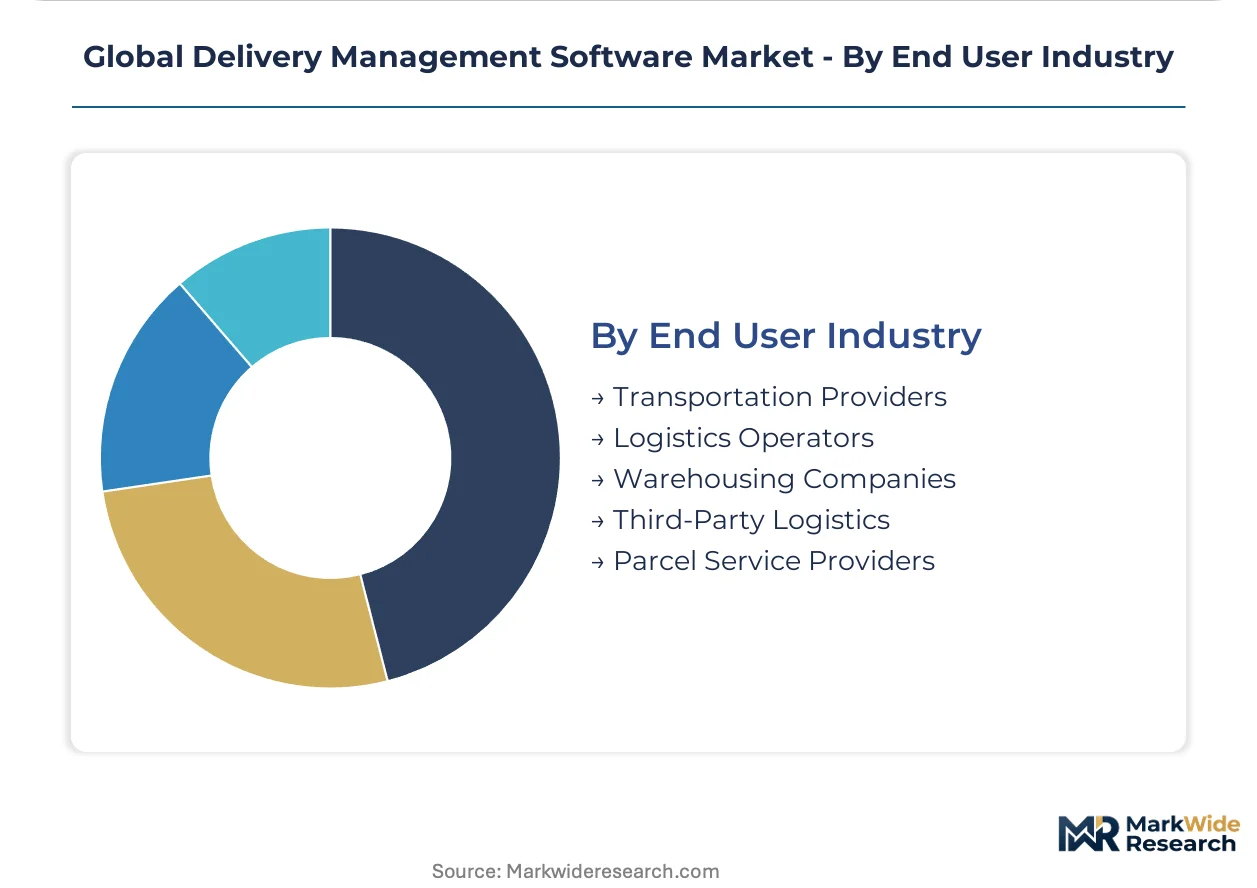
- Third-Party Logistics:Asset-light operators aggregate demand across multiple shippers, requiring multi-tenant platforms with white-label customer portals. India's domestic e-commerce buildout drives fleet management digitization among regional 3PLs serving platform-driven parcel growth.
- Transportation Providers:Fleet-owning carriers with captive driver workforces prioritize telematics integration and hours-of-service compliance.
- Logistics Operators:Full-service providers with warehousing and line-haul assets demand TMS interoperability.
- Parcel Service Providers:Last-mile density specialists invest in customer notification modules to defend retention metrics.
- Warehousing Companies:Distribution center operators focus on yard management and outbound load optimization.
Third-Party Logistics holds the dominant procurement volume, while Parcel Service Providers is climbing the fastest on e-commerce penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act anchors European demand for certified automated dispatch platforms, while India's BIS cloud security standards and CDSCO cold-chain mandates reshape procurement across Asia-Pacific logistics networks.
United States
FDA traceability rules for pharmaceutical distribution drive platform upgrades among cold-chain operators. HIPAA-compliant data architectures dominate healthcare logistics procurement in the Northeast corridor. Chicago and Dallas-Fort Worth anchor third-party logistics scaling for e-commerce fulfillment networks.
Germany
German freight forwarders prioritize GDPR-compliant cloud partitions for multi-tenant delivery management. The KBA enforces hours-of-service integration for fleet tracking systems serving cross-border road haulage. The Rhine-Ruhr industrial cluster concentrates pharmaceutical logistics digitization investments.
India
Domestic e-commerce platform growth accelerates third-party logistics fleet management adoption. BIS cloud security standards and CDSCO documentation mandates create certification barriers for foreign vendors. Mumbai and Bangalore anchor regional courier network digitization for parcel volume expansion.
Brazil
ANVISA temperature documentation requirements open whitespace for sensor-integrated route optimization. Pharmaceutical cold-chain digitization lags regulatory deadlines, compressing deployment timelines for compliant platforms. São Paulo anchors last-mile density investments for urban courier services.
United Kingdom
Post-Brexit customs complexity drives demand for cross-border shipment visibility modules. The Medicines and Healthcare products Regulatory Agency enforces traceability standards for pharmaceutical distribution. London and the Midlands concentrate third-party logistics procurement for European freight forwarding.
Global Delivery Management Software Market Competitive Landscape
API-first specialists and route-optimization purists split the market between enterprise accounts seeking integration flexibility and mid-market operators prioritizing deployment velocity. The vendor base concentrates around three strategic archetypes: platform orchestrators with multi-tenant architectures, last-mile specialists with pharmaceutical compliance depth, and deployment-focused vendors competing on implementation speed. M&A activity targets telemetry data assets, while partnership restructuring with cloud marketplaces displaces direct sales channels.
Within the platform orchestrator tier, Bringg exemplifies API-first architecture serving multi-continental enterprise relationships. FarEye occupies a position among last-mile specialists with pharmaceutical logistics depth. Onfleet anchors the deployment-focused segment competing aggressively on ease of use for mid-market courier services. These three represent the strategic positioning vectors reshaping procurement channel dynamics.
| Leading Market Players |
|---|
| Bringg |
| FarEye |
| Onfleet |
| Loginext Solutions |
| GetSwift |
| WorkWave |
| DispatchTrack |
| Project44 |
| Zebra Technologies |
| Others |
Supply & Pricing Matrix
Shenzhen's IoT sensor manufacturing cluster concentrates GPS module and telematics gateway production, translating upstream capacity tightness into pricing leverage for edge-deployed delivery management platforms serving pharmaceutical cold-chain operators.
Pricing Analysis
German freight forwarders pay 15-25% premiums over Indian courier networks for GDPR-compliant cloud partitions with EU data residency guarantees. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth—EU AI Act pre-certified automated dispatch modules command top-tier rates, while uncertified basic routing engines compete on seat-based SaaS fees. Cost compression in the mid-market tier intensifies as Brazilian pharmaceutical distributors demand fuel-savings guarantees embedded in outcome-based contracts. Third-party logistics operators in the Netherlands show lowest price sensitivity, prioritizing multi-tenant elasticity over per-seat economics.
Supply Chain Analysis
US export controls on advanced GPU and edge-computing semiconductors restrict flows to Chinese logistics platform vendors, forcing architecture pivots toward domestically sourced processing hardware. Component sourcing centers on Taiwan for GPS chipsets, South Korea for memory modules, and Vietnam for IoT gateway assembly. Raw material dependencies span rare earth elements for sensor magnetics, lithium for vehicle-tracking battery backups, and high-purity silicon for edge-node processors. Single-source vulnerability concentrates in East Asian telematics hardware manufacturing, with distribution running through regional systems integrators who bundle software licensing with sensor deployment services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Delivery management software demand follows e-commerce fulfillment cycles, with India's domestic platform growth and Brazil's pharmaceutical cold-chain digitization driving the current upswing after a 2022-2023 correction in freight volumes.
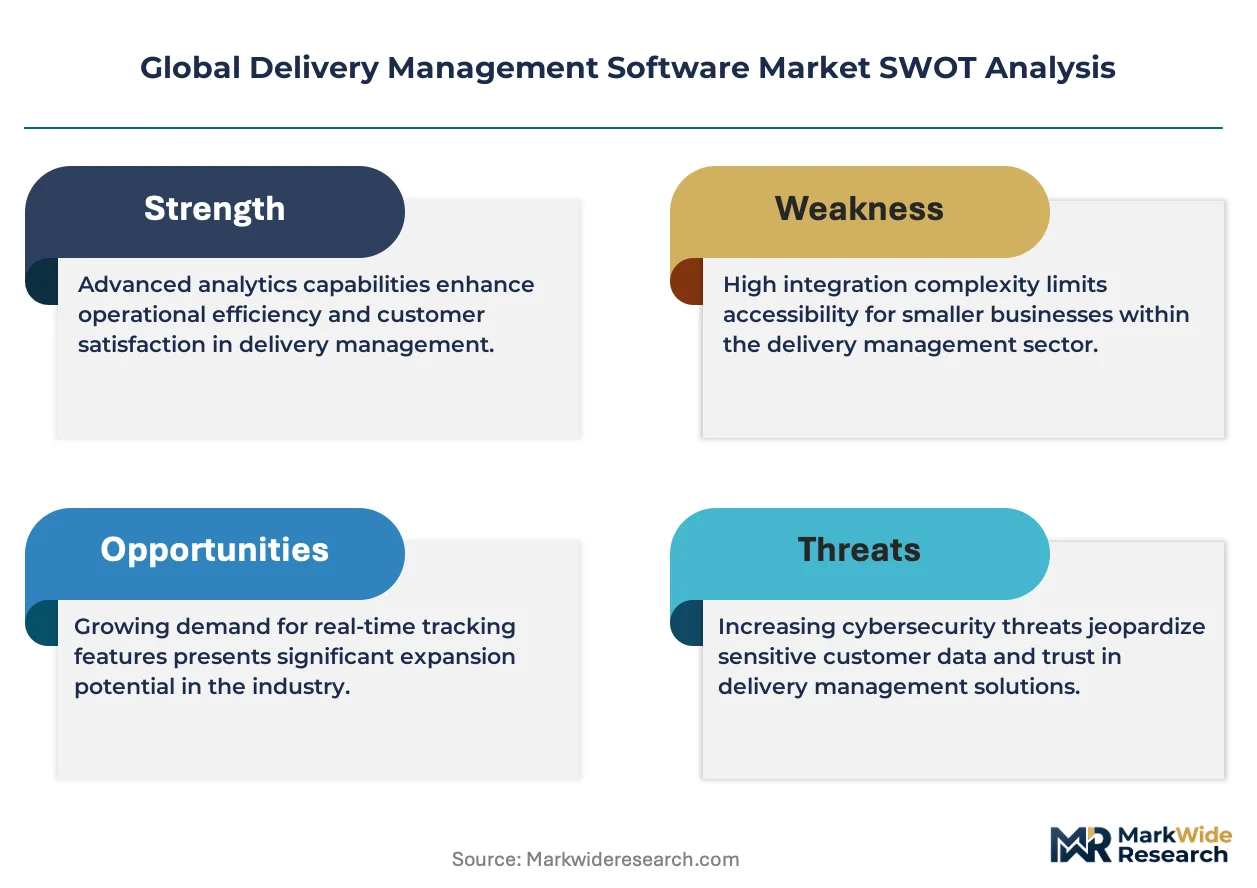
For Market Incumbents: Entrench enterprise relationships through API-first architecture investments that lock in multi-continental accounts against cloud marketplace displacement. Prioritize EU AI Act conformity assessment pre-certification to capture pharmaceutical logistics procurement in Germany and the Netherlands. Defend margin position by acquiring telemetry data assets that deepen algorithmic routing accuracy and create switching costs.
For New Entrants and Emerging Players: Mid-market courier services in Southeast Asia represent the most penetrable entry point, where deployment velocity trumps feature depth and outcome-based pricing remains underdeveloped. Brazil's ANVISA-compliant cold-chain whitespace offers a second beachhead for sensor-integrated route optimization platforms. Go-to-market execution should anchor on systems integrator partnerships rather than direct enterprise sales.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors edge-computing infrastructure specialists with pharmaceutical compliance depth over pure-play SaaS routing vendors. Long-term viability hinges on 5G-V2X convergence readiness and cross-jurisdiction certification bandwidth. Watch FDA traceability rule enforcement intensity as the inflection signal for North American pharmaceutical logistics platform upgrade cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures lock in enterprise accounts across multi-continental deployments against marketplace displacement. |
| Acquisition of Specialist Firm | Telemetry data assets deepen algorithmic routing accuracy and create defensive switching costs for incumbent vendors. |
| Geographic Expansion | Edge-computing clusters in bandwidth-constrained Indian corridors satisfy CDSCO cold-chain documentation mandates. |
| Strategic Partnership | Systems integrator alliances capture procurement channel share as cloud marketplaces fragment direct vendor sales. |
| Product Launch | EU AI Act pre-certified dispatch modules accelerate deployment timelines for European pharmaceutical carriers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC SaaS vendor filings, EU regulatory compliance databases, and Indian logistics operator procurement disclosures. Primary interviews engaged fleet management directors at third-party logistics providers, CTOs at e-commerce fulfillment platforms, and integration specialists at systems integrators. Secondary validation drew from customs trade data on telematics hardware imports, BIS cloud security certification registries, and ANVISA pharmaceutical distribution audit records. Bottom-up deployment volume estimates triangulate against top-down addressable market sizing across cloud, edge, and on-premise architectures.
Forecast inputs span deployment model adoption curves, vertical penetration rates by pharmaceutical versus e-commerce end-use, and regional regulatory compliance cost burdens. Segmentation dimensions modeled include deployment architecture, solution bundling configuration, organization size tier, integration complexity level, and regional data sovereignty framework. CAGRs derive from logistic function diffusion modeling applied to SaaS subscription growth patterns, cross-referenced against fleet telematics hardware shipment trajectories and cloud infrastructure capex disclosures from hyperscale providers.
Macroeconomic conditions sit as an overlay; deviation in e-commerce gross merchandise value growth or cross-border freight volume indices would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement timelines and edge-computing cost decline curves. Material shifts in EU AI Act audit stringency or BIS certification reciprocity agreements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Online Home Service Market
Digital Solutions
Enterprise Content Management (ECM) Market
Digital Solutions
Global Surface Computing Market
Digital Solutions
Life Science Multichannel Campaign Management Market
Digital Solutions
Europe Content Moderation Services Market
Digital Solutions
Community Engagement Platform Market
Digital Solutions
Global Computer Aided Dispatch Market
Digital Solutions
Messaging Platform Market
Digital Solutions
Global Sharing Economy Market
Digital Solutions
Control Room Solutions Market
Digital Solutions
Healthcare Computerized Maintenance Management System Market
Digital Solutions
AI Powered Home Solution Market
Digital Solutions
Enterprise Mobility Market
Digital Solutions
Service Virtualization Market
Digital Solutions
Mobile Dating Apps Market
Digital Solutions
Global User Experience (UX) Market