
 Smart Set-Top Box and Dongle Market | 2026-2036
Smart Set-Top Box and Dongle Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Set-Top Box and Dongle Market Analytics
Market Context
Buyer concentration among telecommunications providers is rebalancing as streaming platforms and direct-to-consumer brands fragment the customer base. Amazon.com Inc. leverages its Prime ecosystem to bundle Fire TV devices with retail and content subscriptions. Samsung Electronics Co. Ltd anchors its position through vertical control over display panels and proprietary Tizen operating system. Roku Inc. competes by specializing in advertising-supported streaming aggregation across third-party channels.
Technical Definition and Segments
Smart set-top boxes and dongles are network-connected television peripherals that decode digital video streams, typically featuring ARM-based processors, HDMI 2.1 output, and onboard storage between 8 GB and 32 GB for application caching and operating system functions. These devices bridge broadband infrastructure to display hardware, enabling over-the-top content delivery, interactive applications, and voice-controlled search. Streaming media players command the fastest expansion trajectory within product type segmentation as consumers bypass traditional broadcast infrastructure entirely. Wi-Fi technology dominates connectivity architecture, though Ethernet retains priority in hospitality and commercial establishment deployments where wired reliability supports concurrent high-bandwidth streams.
Regulatory Framework
The FCC mandates accessibility and interoperability standards for navigation devices in the US, while the EU Green Deal and RoHS directives impose energy efficiency and hazardous substance restrictions on electronics sold across member states. India's BIS certification requirements and PLI scheme for telecom and networking products shape local manufacturing incentives and import compliance costs. Stakeholders must monitor evolving data privacy frameworks and content licensing territorial restrictions that determine firmware regionalization strategies and service availability boundaries.
Market Dynamics
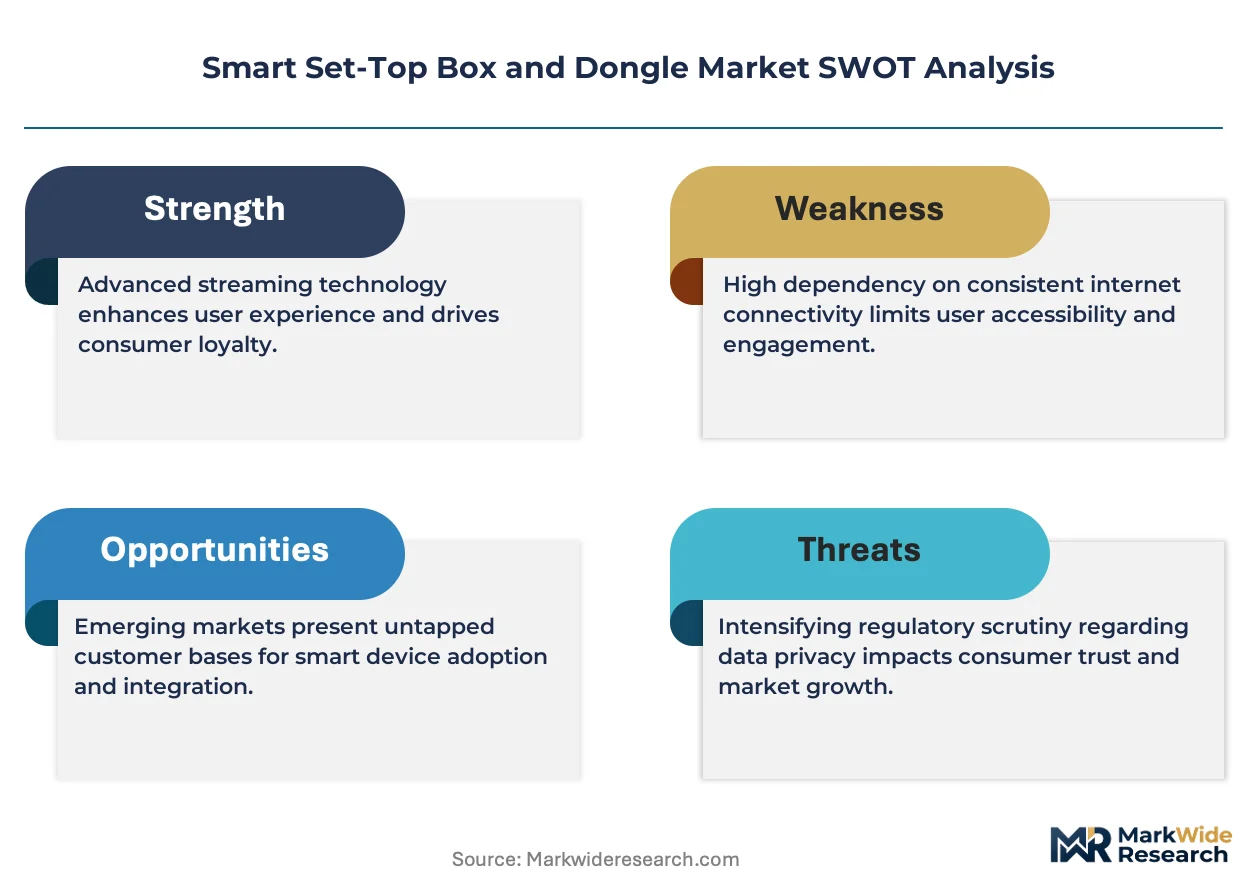
Telecom operators and streaming platforms are fragmenting the buyer base as hardware commoditization accelerates, forcing device manufacturers to compete through software ecosystems and advertising revenue rather than unit margins alone.
Growth Catalysts
- India's PLI scheme for telecom equipment:Domestic manufacturing incentives reduce import dependency and lower landed costs for 4K-capable devices targeting price-sensitive households.
- Wi-Fi 6E chipset integration:Enhanced wireless throughput enables concurrent 4K streams without Ethernet infrastructure, accelerating adoption in multi-dwelling units and hospitality deployments.
- Brazil's broadband infrastructure rollout:Government-backed fiber expansion programs in São Paulo and Rio de Janeiro states create first-time pay-TV subscribers seeking affordable streaming alternatives.
Market Restraints
- ARM-based processor supply concentration:Foundry capacity constraints in Taiwan and South Korea create 16-20 week lead times for advanced SoCs powering 4K decoding functions.
- EU RoHS hazardous substance restrictions:Compliance testing for lead-free solder and restricted flame retardants adds 8-12 weeks to product certification cycles.
- Smart TV native app substitution:Samsung's Tizen and LG's webOS platforms displace external dongle demand in premium television segments.
Strategic Opportunities
- Indonesia's underpenetrated secondary cities:Bandung, Surabaya, and Medan exhibit sub-35% streaming device penetration despite accelerating mobile broadband adoption.
- Voice-controlled search convergence:Natural language processing integration with Dolby Atmos audio output creates differentiated positioning in home theater segments.
- FCC accessibility mandate expansion:Navigation device interoperability requirements open wholesale supply contracts with regional cable operators seeking compliant hardware alternatives.
Industry Challenges
- HDMI 2.1 compliance testing backlog:Certification queue delays at authorized test laboratories extend time-to-market by 6-10 weeks for 8K-ready product lines.
- Firmware regionalization complexity:Content licensing territorial restrictions require 12-18 distinct software builds per hardware SKU, fragmenting engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Set-Top Box and Dongle Market |
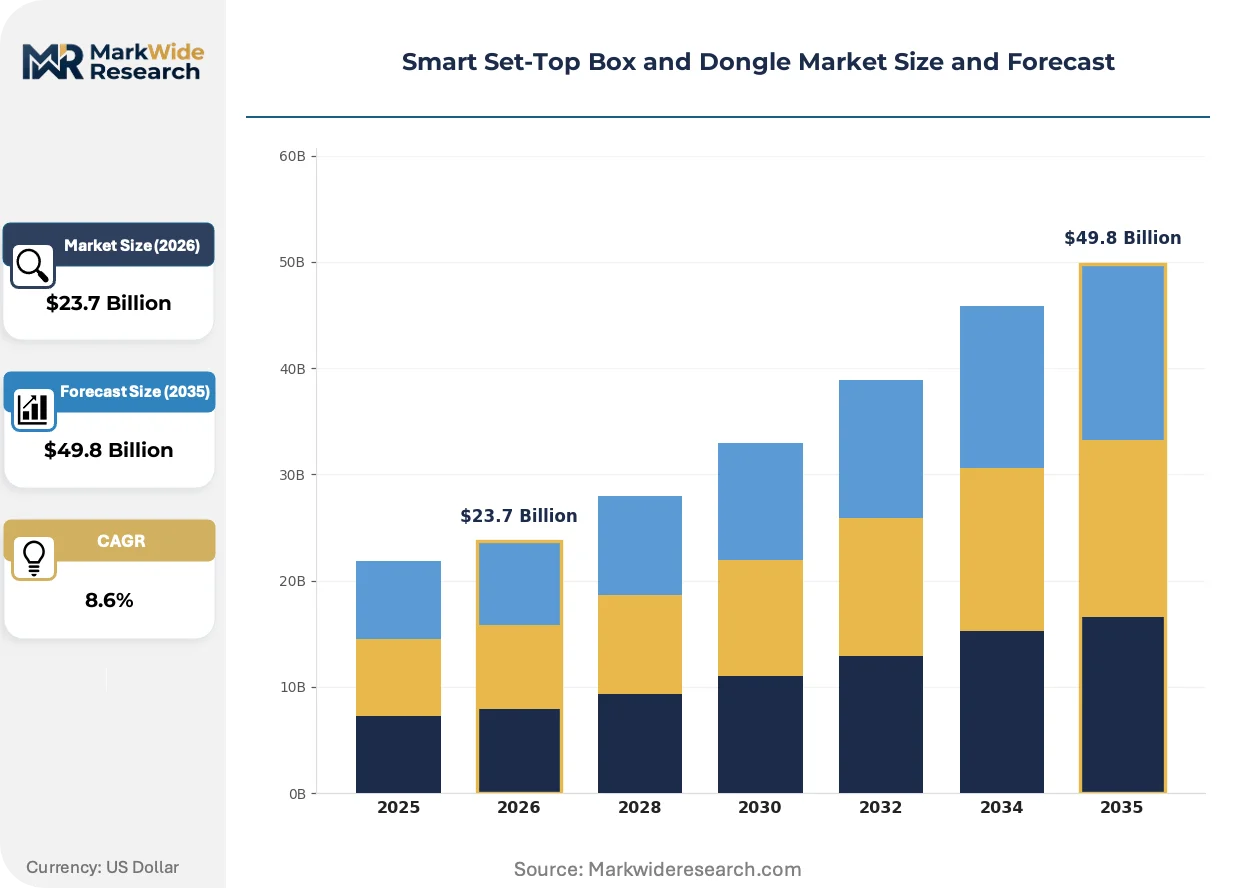
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Set-Top Boxes, Dongles, Hybrid Set-Top Boxes, Streaming Media Players Technology: Wi-Fi, Bluetooth, HDMI, Ethernet End User: Residential, Educational Institutions, Hospitality, Commercial Establishments Distribution Channel: Online Retail, Specialty Stores, Telecommunications Providers, Electronics Retailers |
| Companies Covered | Google LLC, LG Electronics Inc., Roku Inc., TCL Electronics Holdings Limited, Huawei Technologies Co. Ltd., Amazon.com Inc., Samsung Electronics Co. Ltd, Humax Co. Ltd., Apple Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Set-Top Box and Dongle Market Evolving Landscape
Codec efficiency improvements and cloud gaming integration are redefining hardware specifications, while regulatory pressure on interoperability is opening proprietary ecosystems to third-party access.
AV1 video decoding hardware is absorbing the burden of bandwidth-constrained emerging markets where H.265 royalty structures inflate content delivery costs. Streaming platforms in India and Southeast Asia are mandating AV1 support in new device procurement specifications. This compression technology is absorbing market share from legacy H.264 implementations by enabling 4K delivery at 8-10 Mbps versus 25 Mbps requirements.
EU Green Deal energy efficiency directives are imposing standby power limits below 0.5 watts for networked equipment sold across member states. Manufacturers must redesign power management subsystems and source lower-leakage DRAM components. Germany's KBA and France's energy labeling authority are enforcing these standards through retail channel inspections, with non-compliant products facing market withdrawal orders.
Subscription bundling is compressing hardware procurement decisions into content purchasing workflows. Retailers in the United States and United Kingdom are positioning streaming devices as loss-leader attachments to streaming service sign-ups. This channel shift concentrates volume through Amazon, Walmart, and Curry's PC World, marginalizing independent electronics distributors and reducing price transparency for enterprise hospitality buyers.
Smart Set-Top Box and Dongle Market Segmentation
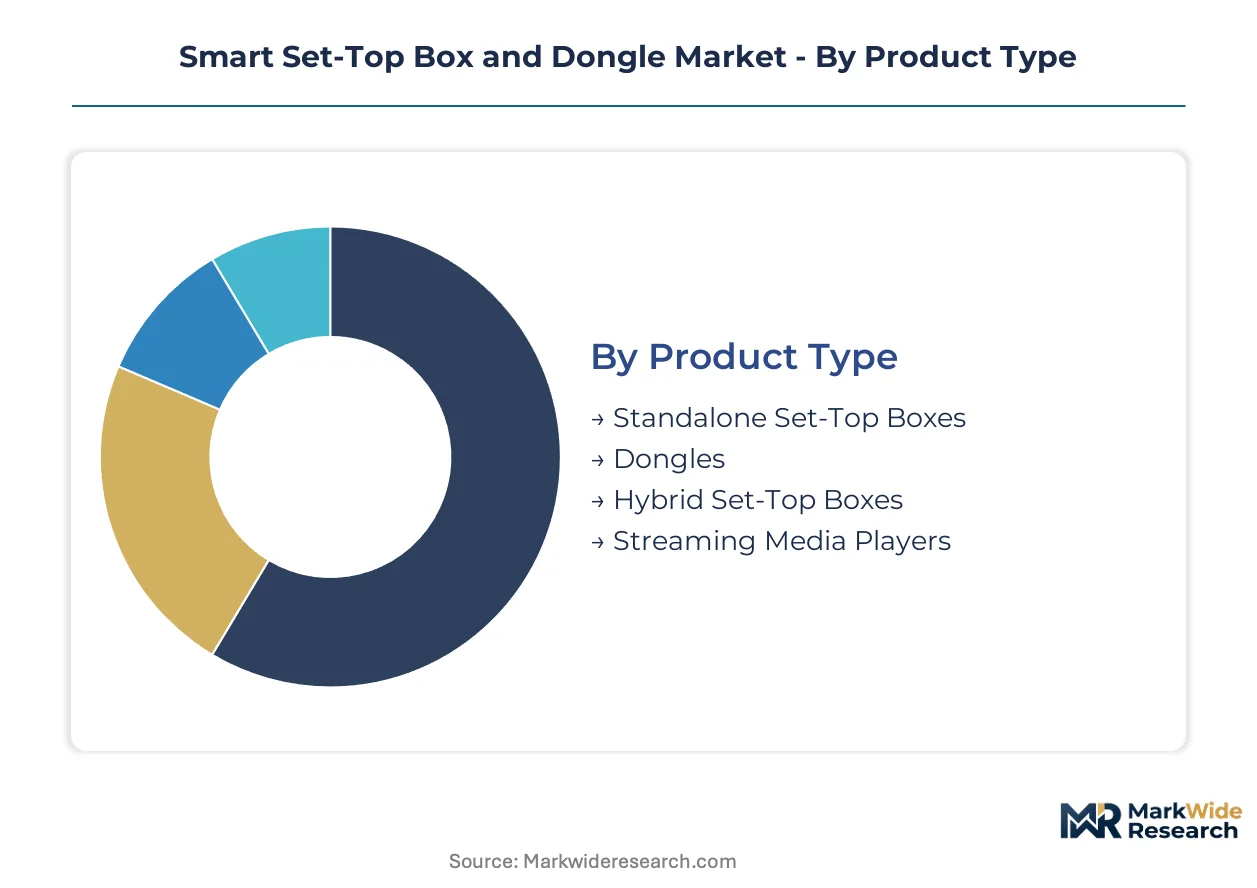
Device segmentation in this market tracks how households upgrade from broadcast-dependent hardware to IP-native streaming peripherals. Replacement cycles compress as software obsolescence outpaces physical wear, shifting purchasing decisions toward ecosystem compatibility and content bundling rather than durability metrics.
Product Type:
Upgrade cycles vary dramatically across form factors, with external dongles refreshing every 2-3 years versus 5-7 year lifespans for operator-issued set-top boxes.
- Streaming Media Players:Compact HDMI peripherals running Android TV, tvOS, or proprietary operating systems with quad-core ARM processors and 8-16 GB storage. Cord-cutting households in the United States and United Kingdom drive volume through retail bundling with Netflix, Disney+, and Amazon Prime subscriptions.
- Dongles:Ultra-portable streaming sticks measuring under 100mm in length, powered via USB or HDMI port draw. India's price-sensitive consumers favor sub-$25 Wi-Fi-enabled dongles as first streaming devices, with Flipkart and Amazon India moving significant volume during festival sales periods.
- Standalone Set-Top Boxes:Self-contained decoders with integrated tuners for terrestrial, cable, or satellite reception, typically deployed by pay-TV operators.
- Hybrid Set-Top Boxes:Dual-mode devices combining broadcast tuning with IP streaming capabilities, bridging legacy infrastructure transitions.
Streaming Media Players sits at the top of the volume ranking, with Dongles climbing the fastest.
Technology:
Connectivity specifications determine deployment feasibility across infrastructure-constrained versus bandwidth-abundant environments.
- Wi-Fi:Wireless standards from 802.11n through Wi-Fi 6E enable cord-free installation, with 5 GHz and 6 GHz bands reducing interference in dense urban apartments. Multi-dwelling units in São Paulo and Mexico City rely exclusively on Wi-Fi connectivity where Ethernet infrastructure is absent.
- Ethernet:Wired Gigabit connectivity guarantees throughput stability for 4K and 8K streams, mandatory in hospitality deployments serving 50+ concurrent rooms.
- HDMI:Physical interface standard with 2.1 specification enabling 8K60 and 4K120 output, dynamic HDR, and eARC audio return.
- Bluetooth:Peripheral pairing protocol for voice remotes, headphones, and game controllers, typically co-implemented rather than primary connectivity.
Wi-Fi captures the highest shipment volumes, though Ethernet retains premium positioning in commercial verticals.
End User:
Application context shapes hardware specifications, with commercial deployments demanding centralized management and consumer segments prioritizing ease of installation.
- Residential:Individual households purchasing through retail or receiving subsidized devices from streaming platforms and telecom operators. Brazilian fiber expansion programs in Rio de Janeiro state are converting first-time broadband subscribers to streaming households.
- Hospitality:Hotels, serviced apartments, and cruise ships requiring bulk deployment with remote provisioning, content filtering, and integrated billing systems.
- Commercial Establishments:Bars, restaurants, and waiting rooms using streaming devices for ambient entertainment, often with advertising-supported tiers.
- Educational Institutions:Schools and universities deploying devices for classroom streaming and campus-wide content distribution.
Residential dominates absolute volume, while Hospitality shows the steepest expansion trajectory among commercial verticals.
Distribution Channel:
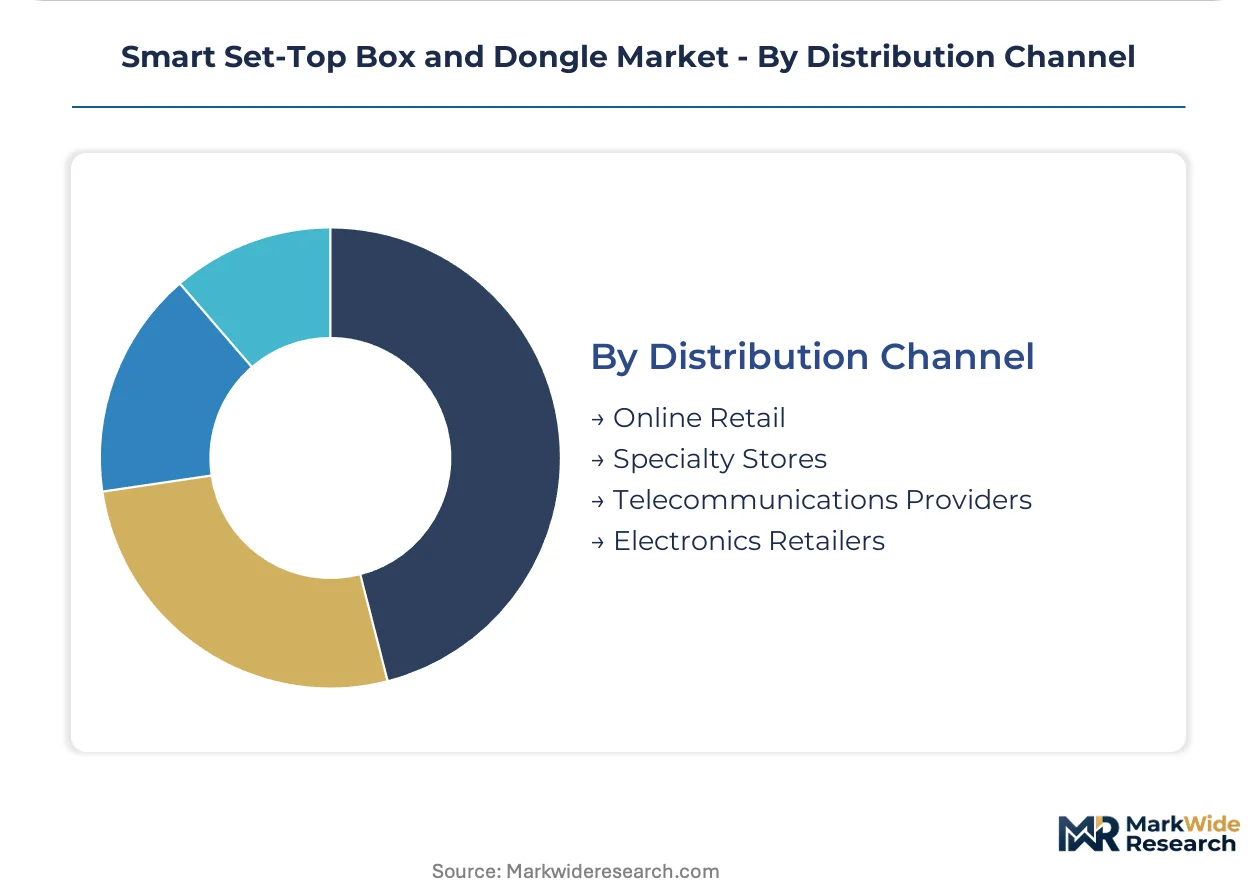
Channel structure concentrates as streaming platforms and retail giants absorb procurement decisions through subscription bundling.
- Online Retail:Amazon, Flipkart, and regional e-commerce platforms offering device-plus-subscription bundles with same-day or next-day fulfillment. India's festive season sales events move substantial inventory through aggressive discounting tied to content service trials.
- Telecommunications Providers:Jio, Airtel, and regional ISPs subsidizing hardware against 12-24 month broadband contracts, controlling activation and firmware updates.
- Electronics Retailers:Brick-and-mortar chains including Best Buy, Currys PC World, and Croma providing hands-on comparison and immediate pickup.
- Specialty Stores:AV installers and home theater specialists serving premium segments with calibration and integration services.
Online Retail leads volume rankings, with Telecommunications Providers gaining share fastest through contract bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's fiber expansion programs generate first-time streaming subscribers faster than Germany's efficiency mandates reshape hardware specifications. India subsidizes domestic manufacturing while the United States enforces open-platform navigation rules.
United States
Cord-cutting households and hospitality sector upgrades sustain demand for 4K-capable streaming peripherals. The FCC mandates accessibility and interoperability standards for navigation devices, reshaping procurement contracts for regional cable operators. Silicon Valley clusters concentrate engineering talent for voice-controlled search integration.
India
Price-sensitive consumers in secondary cities adopt sub-$25 Wi-Fi dongles as first streaming devices. The BIS certification requirements and PLI scheme for telecom equipment incentivize local assembly and reduce import dependency. Bangalore and Hyderabad host firmware development centers serving Asia-Pacific regionalization needs.
Germany
EU Green Deal standby power limits below 0.5 watts force power management subsystem redesigns. The KBA enforces energy efficiency standards through retail channel inspections, with non-compliant products facing market withdrawal. Munich industrial clusters specialize in low-leakage DRAM component sourcing.
Brazil
Government-backed fiber expansion in São Paulo and Rio de Janeiro states converts first-time broadband subscribers to streaming households. ANVISA regulates electronics safety while local content quotas shape firmware regionalization. São Paulo metropolitan area concentrates device distribution logistics for Latin American markets.
China
Domestic streaming platforms mandate AV1 decoding support in procurement specifications for bandwidth-constrained deployments. MIIT oversees network equipment certification while GB standards govern electromagnetic compatibility. Shenzhen manufacturing ecosystems produce ARM-based SoCs and HDMI 2.1 interface components.
Smart Set-Top Box and Dongle Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware commoditization pressures. The vendor base spans three tiers: integrated technology giants controlling display panels and operating systems, streaming-first platforms monetizing advertising aggregation, and contract manufacturers serving operator-branded deployments. Strategic moves concentrate on software ecosystem lock-in and advertising revenue sharing rather than unit margin defense. Partnership structures with telecommunications providers and content platforms determine volume allocation.
Among technology conglomerates, Samsung Electronics Co. Ltd and LG Electronics Inc. exemplify vertical control strategies through captive display panel supply and proprietary operating system deployment. Google LLC and Amazon.com Inc. occupy positions defined by retail ecosystem bundling and voice assistant integration. Roku Inc. represents the advertising-supported aggregation archetype, specializing in third-party channel distribution without hardware manufacturing dependency.
| Leading Market Players |
|---|
| Google LLC |
| LG Electronics Inc. |
| Roku Inc. |
| TCL Electronics Holdings Limited |
| Huawei Technologies Co. Ltd. |
| Amazon.com Inc. |
| Samsung Electronics Co. Ltd |
| Humax Co. Ltd. |
| Apple Inc. |
| Others |
Value Network & Pricing Analysis
Family-owned contract manufacturers in Shenzhen and Dongguan anchor production capacity for ARM-based SoCs and HDMI interface components, translating concentrated semiconductor sourcing into disciplined margin management across tiered hardware categories.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for assembly-intensive dongle production, compressing margins on sub-$25 economy tiers. Three-tier pricing structure across premium, standard, and economy levels separates voice-integrated 4K players from basic Wi-Fi sticks and operator-subsidized entry devices. Cost compression in economy tiers is intensifying because India's PLI scheme incentivizes local assembly against Chinese import competition. Hospitality buyers demonstrate lowest price sensitivity due to centralized procurement and reliability requirements, while India's festival-season retail consumers drive maximum price elasticity.
Supply Chain Analysis
Dual-sourcing mandates from Amazon and Walmart require SoC qualification across MediaTek and Amlogic portfolios, fragmenting volume commitments. Taiwan, South Korea, and China concentrate foundry capacity for advanced decoding chipsets. Raw material dependencies span silicon wafers, lead-free solder alloys, and low-leakage DRAM components. Single-source vulnerability in Taiwan's 7nm and 5nm foundry nodes creates exposure to geopolitical disruption. Distribution runs through Shenzhen component markets feeding contract manufacturers, then direct to telecom operators and retail fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing cost arbitrage between India's PLI-subsidized assembly zones and China's established component ecosystems creates geographic-repositioning incentives for volume producers seeking margin recovery.
For Market Incumbents: Deploy voice-controlled search integration as a differentiation lever against smart TV native platform substitution. Consolidate firmware development centers in Bangalore and Hyderabad to reduce regionalization overhead. Secure captive supply of Wi-Fi 6E chipsets through upstream partnerships with Qualcomm and MediaTek to defend against supply concentration risks in Taiwan. For New Entrants and Emerging Players: Begin with Indonesia's secondary cities—Bandung, Surabaya, and Medan—where sub-35% streaming penetration meets accelerating mobile broadband adoption. Target hospitality verticals in Brazil's Rio de Janeiro fiber expansion corridors with white-label provisioning solutions. Partner with regional telecom operators for subsidized device distribution against 12-24 month broadband contracts. For Investors and Strategic Acquirers: Telecommunications providers are the most active acquirer in this space, seeking captive hardware supply to lock in subscriber retention. Five-to-ten year viability hinges on advertising revenue aggregation capabilities rather than unit margin defense. Monitor AV1 decoding hardware adoption rates across Indian and Southeast Asian procurement specifications as the inflection signal for codec transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| AV1 Hardware Decoding Integration | Enables 4K delivery at 8-10 Mbps for bandwidth-constrained Indian and Southeast Asian markets. |
| Wi-Fi 6E Chipset Migration | Supports concurrent 4K streams in São Paulo and Mexico City multi-dwelling units without Ethernet infrastructure. |
| PLI Scheme Manufacturing Localization | Reduces import dependency and landed costs for price-sensitive Indian household penetration. |
| Voice Assistant Platform Partnership | Locks in ecosystem integration with Amazon Alexa and Google Assistant for retail bundling dominance. |
| Hospitality Vertical Software Suite | Captures remote provisioning and content filtering contracts from hotel chains in Brazil and United States. |
Research Methodology
Bottom-up residential and hospitality deployment modeling reconciled against top-down semiconductor shipment tracking forms the analytical core of this study. Primary interviews with streaming platform hardware procurement directors, telecom operator device strategy leads, contract manufacturing executives, and hospitality technology integrators were validated against secondary sources including FCC equipment authorization databases, BIS certification registries, EU energy labeling authority filings, and customs trade data for set-top box and dongle HS codes.
Historical trendline analysis of replacement cycle compression and codec transition timing informed projection frameworks across the analysis window. Segmentation modeling incorporated product type, connectivity technology, end-user vertical, and distribution channel dimensions. CAGRs were derived from installed base growth rates adjusted for software obsolescence acceleration and broadband infrastructure rollout schedules in priority markets.
Several conditions sit outside the modeled scope, including unforeseen regulatory delays in FCC accessibility mandate implementation and geopolitical disruption to Taiwan foundry operations. Forecasts reflect assumptions about AV1 hardware adoption curves and PLI scheme subsidy continuity. Deviation in ARM-based SoC supply availability or EU Green Deal standby power enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Advocacy Software Market
Digital Solutions
Global Cloud-Based Solutions for Drug Discovery, Development and Manufacturing Market
Digital Solutions
Reverse Logistics Visibility and Disposition Optimization Platforms Market
Digital Solutions
Digital Clothing Market
Digital Solutions
Enterprise Data Management Market
Digital Solutions
North America Online Dating Services Market
Digital Solutions
Service Virtualization Market
Digital Solutions
Poland ICT Market
Digital Solutions
Digital Twin in Construction Market
Digital Solutions
Legaltech Market
Digital Solutions
Employee Recognition and Reward System Market
Digital Solutions
Electronic Discovery Market
Digital Solutions
Restaurant POS Terminals Market
Digital Solutions
Middle East and Africa Digital Scent Technology Market
Digital Solutions
Cloud-Based Product Lifecycle Management (PLM) Market
Digital Solutions
Ediscovery Solution Market