
 Software Defined Application and Infrastructure Market | 2026-2036
Software Defined Application and Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Software Defined Application and Infrastructure Market Analytics
Modular service bundling is realigning how procurement teams evaluate vendor relationships. Cisco Systems leverages its networking hardware heritage to anchor software-defined networking subscriptions within enterprise accounts. Microsoft Corporation extends its Azure control plane to compete across hybrid and multi-cloud deployments. Nutanix specializes in hyperconverged infrastructure software that occupies mid-market data center refresh cycles.
Software defined application and infrastructure encompasses programmable compute, storage, and networking resources abstracted from physical hardware through virtualization layers, API-driven orchestration, and policy-based automation. The architecture enables dynamic resource provisioning with sub-minute deployment times for containerized workloads. Hybrid cloud deployment models carry the deepest margin pools as enterprises retain on-premises sovereignty while bursting to public infrastructure. Container technology is displacing traditional virtualization as the default abstraction layer for cloud-native application development. Management services represent the fastest-growing service type as operational complexity across distributed environments intensifies.
The EU AI Act and GDPR impose algorithmic transparency and data residency requirements that shape European procurement specifications for software-defined stacks. In the United States, NIST cybersecurity frameworks and FedRAMP authorization gates restrict market access for infrastructure software serving federal agencies. China's MIIT cloud service security assessment and data localization rules create parallel compliance architectures for multinational deployments. Stakeholders must monitor divergent sovereign cloud certification regimes to avoid architectural lock-in that fragments global operations.
Market Dynamics
Container orchestration is compressing infrastructure procurement cycles from quarters to weeks, forcing vendors to rebuild pricing models around consumption rather than perpetual licenses.
Growth Catalysts
- EU AI Act compliance mandates:European enterprises must deploy auditable, policy-driven infrastructure stacks. This accelerates replacement of opaque legacy virtualization layers with API-transparent software-defined architectures.
- Kubernetes-native workload density:Platform engineering teams standardize on container orchestration as the default abstraction. Resource utilization rates climb as bare-metal efficiency replaces hypervisor overhead.
- FedRAMP authorization pipelines:United States federal agencies now require cloud-native infrastructure certification. This creates dedicated demand streams for sovereign-compliant software-defined stacks in government data centers.
Market Restraints
- Specialized engineering talent scarcity:Site reliability engineering and infrastructure-as-code expertise concentrates in technology hubs. Enterprise IT departments face 6-12 month hiring timelines for qualified platform engineers.
- Silicon supply concentration:Advanced networking ASICs and SmartNICs depend on Taiwan-based foundry capacity. Geopolitical friction threatens hardware refresh cycles that underpin software-defined networking rollouts.
- IPv4 address exhaustion:Legacy network addressing limits container cluster scale in on-premises environments. Organizations must rearchitect underlay networks before expanding Kubernetes deployments.
Strategic Opportunities
- India's data localization enforcement:The country's central bank and telecom regulator mandate in-country data processing. Domestic cloud providers require software-defined infrastructure partners to meet sovereign storage requirements.
- FinOps tooling convergence:Cloud cost optimization platforms integrate directly with infrastructure orchestration APIs. Vendors can embed spend governance into control plane subscriptions.
- Edge computing micro-clusters:Manufacturing and retail deploy containerized compute at branch locations. Distributed software-defined stacks replace centralized data center dependencies for latency-sensitive workloads.
Industry Challenges
- Multi-cloud credential sprawl:Platform teams manage identity federation across AWS IAM, Azure AD, and Google Cloud Identity. Security posture gaps emerge from inconsistent policy enforcement APIs.
- Stateful workload migration friction:Databases and message queues resist containerization due to persistent storage dependencies. Engineering teams must redesign data tier architectures to achieve cloud-native portability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Software Defined Application and Infrastructure Market |
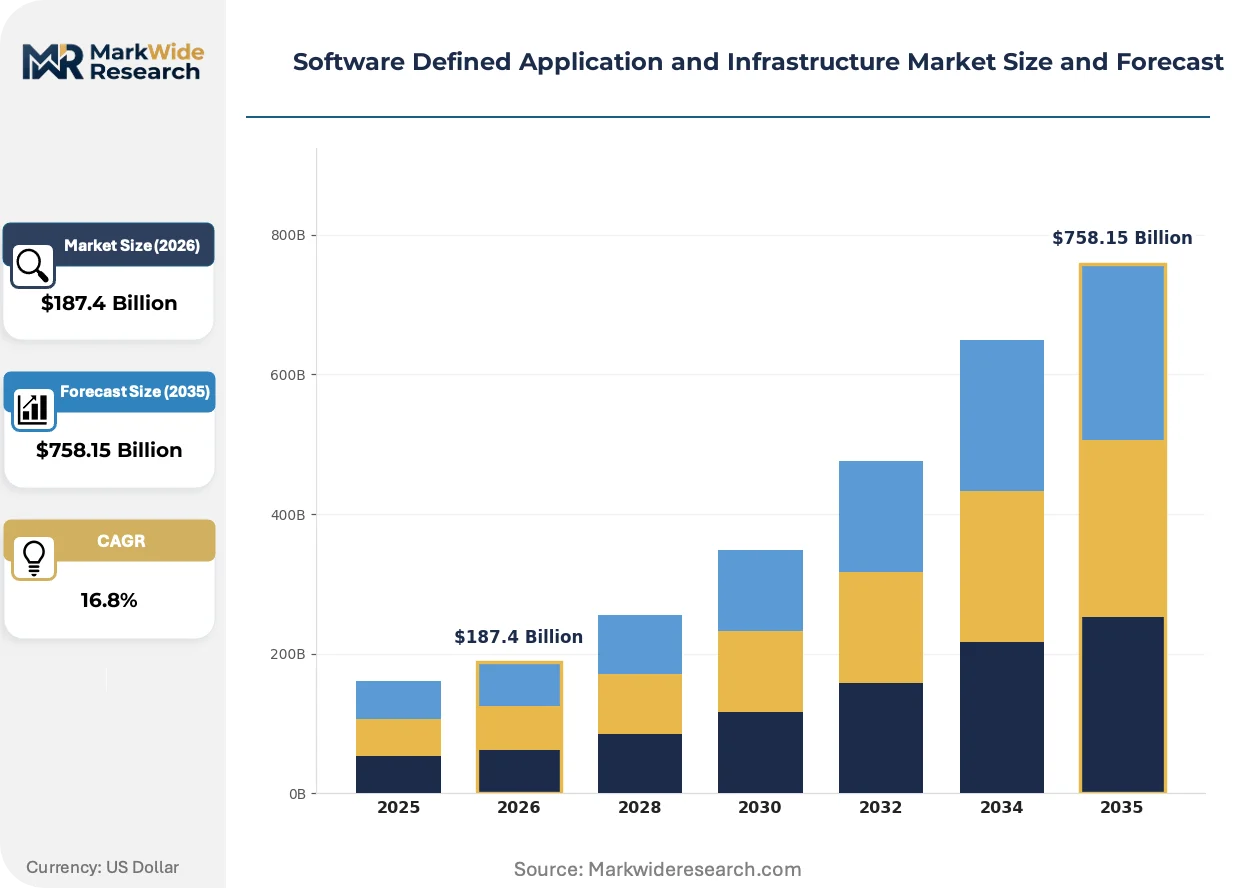
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $758.15 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Infrastructure as a Service, Platform as a Service, Software as a Service, Management Services End User: Small Businesses, Enterprises, Educational Institutions, Government Agencies Technology: Containers, Microservices, Virtualization, Automation |
| Companies Covered | VMware, Cisco Systems, IBM, Hewlett Packard Enterprise, Oracle Corporation, Dell Technologies, Microsoft Corporation, Nutanix, Juniper Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Software Defined Application and Infrastructure Market Evolving Landscape
Workload abstraction layers are fragmenting as platform engineering matures, creating specialized tooling for security, cost, and performance governance that sits adjacent to core orchestration.
eBPF is overtaking kernel-level network filtering and observability functions in Linux environments. Cloud-native security vendors embed extended Berkeley Packet Filter programs directly into host operating systems. This compression of the networking stack eliminates sidecar proxy overhead that previously consumed 30-40% of container resource budgets.
REACH chemical restrictions and the EU Green Deal carbon disclosure rules now extend to data center infrastructure procurement. European enterprise buyers require embodied carbon documentation for servers and networking equipment. Vendors must reconfigure supply chain reporting to capture Scope 3 emissions from semiconductor fabrication through final assembly.
Enterprise buyers now unbundle infrastructure management from hardware acquisition. Mid-market IT departments contract specialized platform operations firms rather than building internal SRE teams. Germany and Japan exhibit the strongest concentration of this managed control plane consumption, where aging IT demographics limit in-house hiring feasibility.
Software Defined Application and Infrastructure Market Segmentation
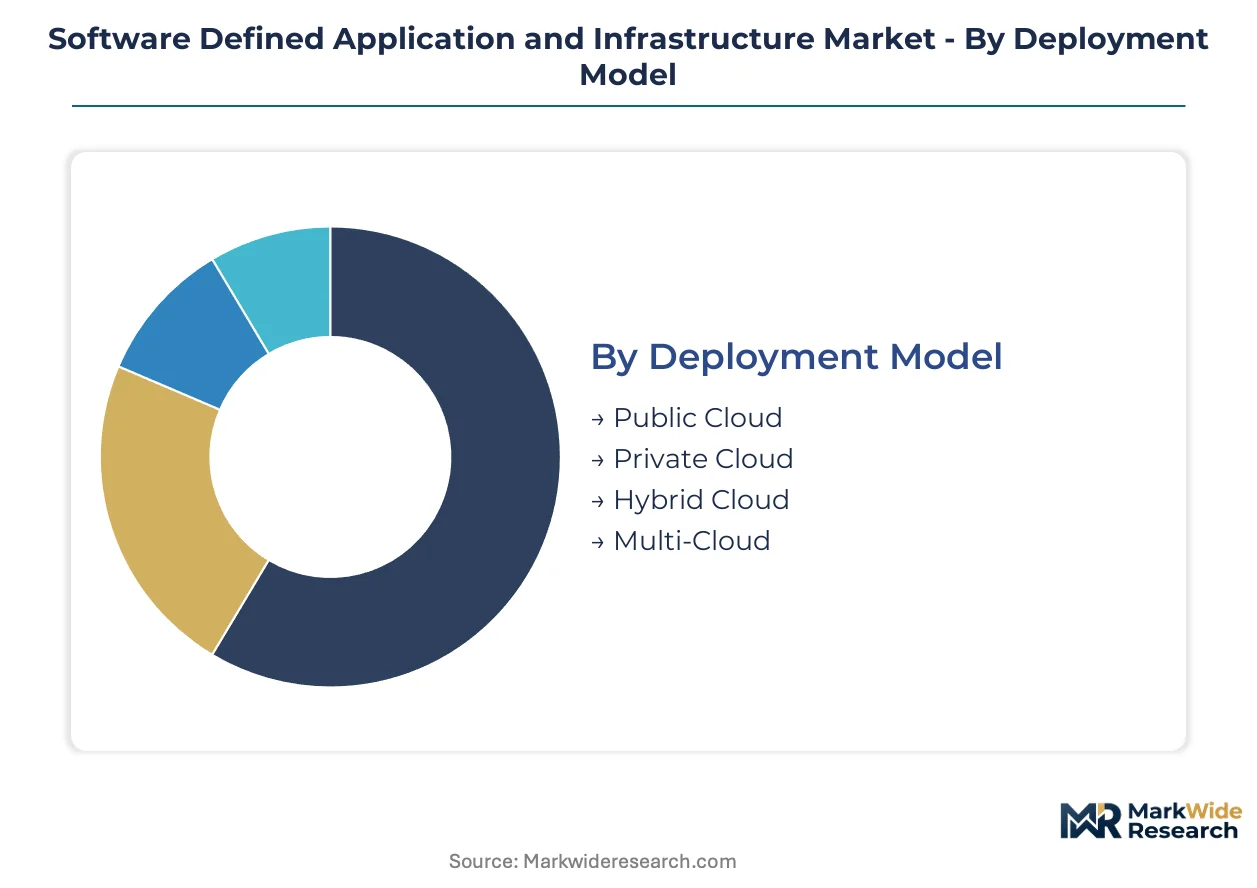
Software-defined infrastructure procurement varies sharply by deployment topology and operational maturity. Buyers select architectural patterns based on data sovereignty requirements, workload portability needs, and internal platform engineering capabilities.
Deployment Model:
Supply concentration among hyperscale cloud providers shapes enterprise deployment preferences and contract negotiation leverage.
- Hybrid Cloud:Enterprises retain on-premises sovereignty for regulated data while bursting compute to public infrastructure. Financial services firms in Germany and Japan anchor demand here due to central bank data localization mandates. This architecture carries the deepest margin pools as orchestration complexity justifies premium licensing.
- Multi-Cloud:Platform engineering teams distribute workloads across AWS, Azure, and Google Cloud to avoid vendor lock-in. Container orchestration standardization enables this portability. Procurement cycles compress from quarters to weeks as consumption-based pricing displaces perpetual licenses.
- Public Cloud:Startups and digital-native enterprises consume fully managed infrastructure without capital expenditure. Latency-sensitive applications in India and Brazil drive regional cloud provider partnerships.
- Private Cloud:Defense contractors and healthcare systems deploy air-gapped infrastructure for classified or protected health information. FedRAMP authorization gates restrict vendor participation in United States federal deployments.
Today's leader: Hybrid Cloud. Tomorrow's challenger: Multi-Cloud.
Service Type:
Cost tier differentiation separates commodity infrastructure from value-added control plane offerings.
- Management Services:Specialized platform operations firms assume 24/7 infrastructure oversight for mid-market enterprises lacking internal SRE benches. Germany and Japan exhibit the strongest concentration here where aging IT demographics limit hiring feasibility. FinOps tooling convergence embeds spend governance directly into subscription pricing.
- Infrastructure as a Service:Bare-metal and virtualized compute resources delivered through API-driven provisioning. Container technology is displacing traditional virtualization as the default abstraction layer.
- Platform as a Service:Managed Kubernetes and serverless execution environments accelerate developer velocity. European procurement teams prioritize EU AI Act-compliant stacks with auditable policy automation.
- Software as a Service:Pre-configured control planes for networking, storage, and security functions. Modular service bundling realigns how enterprise buyers evaluate vendor relationships.
Management Services are climbing the fastest as operational complexity across distributed environments intensifies.
End User:
Customer type determines sales cycle length, technical support requirements, and contract structure preferences.
- Enterprises:Global 2000 organizations operate multi-thousand node Kubernetes clusters with dedicated platform engineering teams. Cisco Systems and Microsoft Corporation compete for hybrid cloud orchestration contracts here. Procurement emphasizes API transparency and sovereign cloud certification.
- Government Agencies:United States federal, state, and local entities require FedRAMP-authorized infrastructure with continuous monitoring. NIST cybersecurity frameworks dictate technical specifications. Nutanix specializes in hyperconverged stacks for government data center refresh cycles.
- Small Businesses:Cloud-native startups consume fully managed services without internal infrastructure expertise. Monthly subscription models dominate with minimal customization.
- Educational Institutions:Universities and research consortia deploy software-defined labs for computational research. Grant-funded procurement favors open-source orchestration platforms.
Enterprises command current vendor attention. Government Agencies represent the steepest expansion trajectory as sovereign cloud requirements harden.
Technology:
Technology maturity curves separate proven virtualization from emerging container-native architectures.
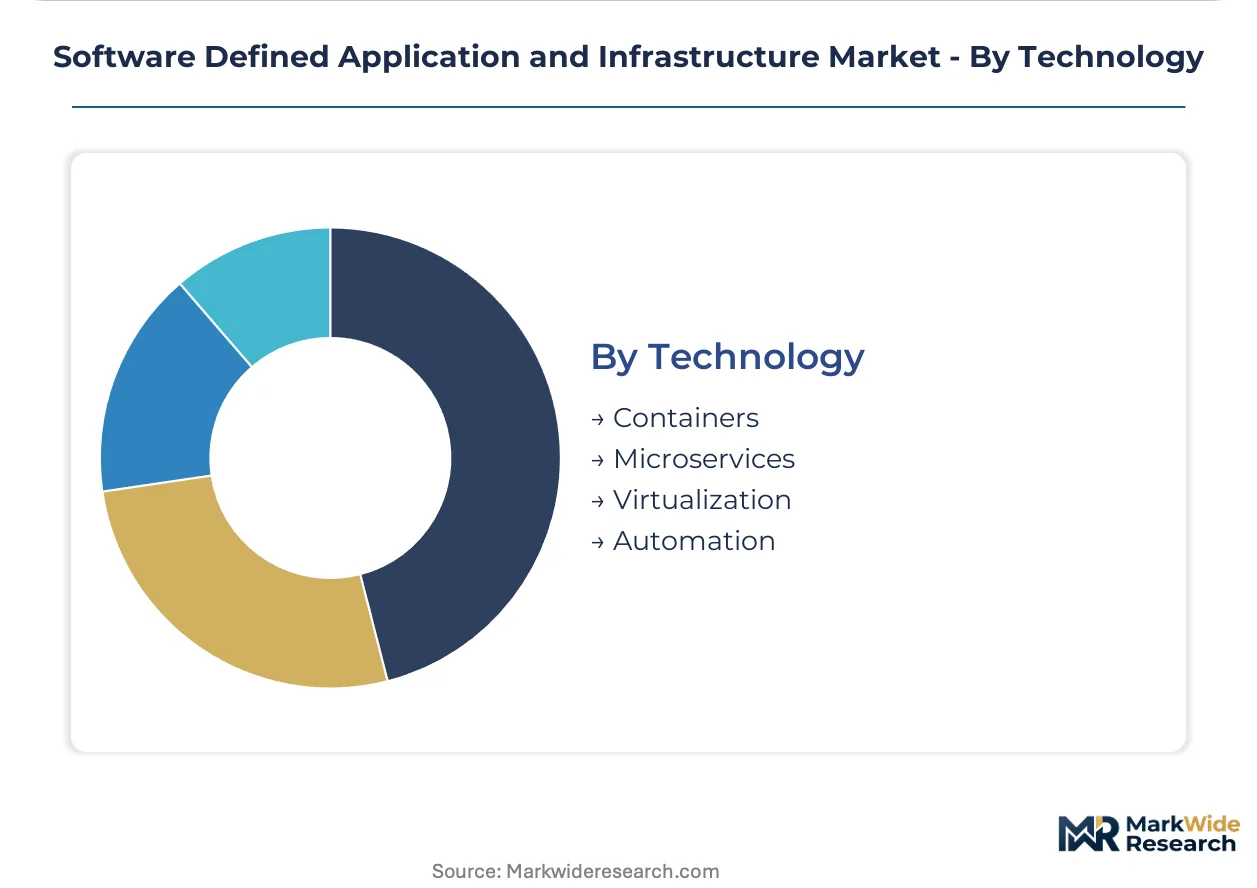
- Containers:Docker and Kubernetes have become the standard abstraction for cloud-native application development. eBPF programs now handle kernel-level networking and observability, eliminating sidecar proxy overhead that previously consumed substantial resource budgets. Site reliability engineering expertise concentrates in technology hubs, creating 6-12 month hiring timelines.
- Microservices:Fine-grained service decomposition enables independent deployment velocity. Stateful workload migration friction persists for databases and message queues requiring persistent storage redesign.
- Virtualization:VMware and Hyper-V stacks persist in legacy enterprise data centers. Containerization and Kubernetes-native infrastructure are displacing these layers in greenfield deployments.
- Automation:Infrastructure-as-code and GitOps pipelines enable declarative resource management. IPv4 address exhaustion limits container cluster scale in on-premises environments before underlay network rearchitecture.
Containers dominate greenfield investment. Microservices face implementation headwinds from data tier portability constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software-defined infrastructure originated in United States enterprise data centers during the 2000s virtualization wave, then scaled through hyperscale cloud provider architectures before diffusing to regulated industries worldwide.
United States
Federal cloud mandates and financial services modernization propel demand. NIST cybersecurity frameworks and FedRAMP authorization gates restrict vendor participation in government deployments. Northern Virginia's data center corridor hosts the densest concentration of hybrid cloud orchestration infrastructure.
Germany
Industrial automation and automotive manufacturing drive sovereign cloud requirements. EU AI Act compliance mandates and GDPR data residency rules shape procurement specifications for auditable infrastructure stacks. Bavaria's Munich-Ingolstadt tech corridor anchors automotive platform engineering teams.
Japan
Aging IT demographics and manufacturing digitization accelerate managed service consumption. METI cloud security guidelines and central bank data localization rules govern financial sector deployments. Tokyo-Osaka corridor enterprises deploy Kubernetes-native infrastructure for precision manufacturing workloads.
India
Digital public infrastructure expansion and startup ecosystem growth fuel consumption. RBI data localization enforcement and TRAI cloud security assessments mandate in-country processing for financial and telecom workloads. Bangalore and Hyderabad clusters concentrate platform engineering talent for global delivery.
United Kingdom
Financial services regulatory technology and government cloud migration sustain investment. FCA operational resilience requirements and NCSC cloud security principles dictate infrastructure architecture standards. London's fintech corridor drives demand for multi-cloud orchestration with audit-grade policy automation.
Software Defined Application and Infrastructure Market Competitive Landscape
The competitive structure tilts toward diversified technology conglomerates with legacy enterprise relationships. Infrastructure software vendors compete across three distinct tiers: hyperscale cloud providers with native control planes, established hardware vendors extending software subscriptions, and specialized platform engineering firms. Consolidation pressures intensify as container orchestration commoditizes traditional virtualization margins. Strategic moves concentrate on API ecosystem partnerships and sovereign cloud certification acquisitions.
Among diversified technology conglomerates, VMware and Cisco Systems exemplify the hardware-heritage-to-software-transition archetype, while Microsoft Corporation occupies the hyperscale control plane position. These three entities anchor the competitive landscape through distinct routes: virtualization legacy, networking hardware installed base, and cloud-native developer ecosystem capture respectively.
| Leading Market Players |
|---|
| VMware |
| Cisco Systems |
| IBM |
| Hewlett Packard Enterprise |
| Oracle Corporation |
| Dell Technologies |
| Microsoft Corporation |
| Nutanix |
| Juniper Networks |
| Others |
Value Network & Pricing Analysis
Container orchestration standardization is compressing infrastructure procurement cycles from quarters to weeks, simultaneously eroding perpetual license premiums and redistributing margin capture toward hyperscale cloud control planes. This shift concentrates pricing power among vendors with sovereign cloud certification depth while fragmenting hardware supply relationships across specialized component producers.
Pricing Analysis
Consumption-based subscription tiers now dominate enterprise procurement, with pricing stratifying across premium sovereign-certified, standard multi-tenant, and economy self-managed deployment levels. Certification grade—particularly FedRAMP authorization and EU AI Act compliance—commands substantial premiums over uncertified alternatives. Cost compression in standard tiers is intensifying because container commoditization enables workload portability across providers. Mid-market enterprises lacking internal platform engineering benches exhibit highest price sensitivity, while financial services firms in Germany and Japan accept premium positioning for data residency guarantees.
Supply Chain Analysis
Advanced networking ASICs and SmartNICs rest on Taiwan-based foundry capacity, with secondary concentration in South Korean memory fabrication and Japanese precision components. Software-defined infrastructure draws from specialized semiconductor lithography, high-bandwidth memory modules, and custom networking silicon. Single-source vulnerability in Taiwan-based wafer production presents acute exposure given geopolitical friction. Distribution runs through hyperscale cloud provider marketplaces, direct enterprise sales forces, and regional systems integrators with sovereign cloud expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's data localization enforcement creates cost-advantaged deployment opportunities against European compliance-heavy infrastructure investments.
For Market Incumbents: Anticipate margin compression in standard virtualization tiers as Kubernetes-native workloads displace legacy hypervisor stacks. Defensive positioning requires deepening sovereign cloud certification portfolios across FedRAMP, EU AI Act, and Japan METI frameworks. Backward integration into specialized networking silicon—particularly SmartNIC development—preserves differentiation against commodity orchestration offerings. For New Entrants and Emerging Players: Launch via managed control plane subscriptions targeting mid-market enterprises in Germany and Japan where aging IT demographics limit internal SRE hiring. White-space concentration sits in FinOps-embedded infrastructure governance and edge computing micro-clusters for manufacturing workloads. Go-to-market acceleration hinges on API-transparent policy automation that satisfies emerging algorithmic audit requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among regional managed service providers with sovereign cloud certification depth but limited hyperscale partnership scale. Long-term viability across the analysis window favors platform engineering firms with demonstrated Kubernetes-native workload density and multi-cloud credential federation capabilities. The signal to watch is consolidation velocity among mid-market infrastructure software vendors as container orchestration commoditization intensifies.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure control plane extension captures hybrid cloud orchestration contracts from enterprise IT departments. |
| Sovereign Cloud Certification Acquisition | FedRAMP authorization pipelines unlock dedicated demand streams in United States federal data centers. |
| Strategic Partnership | Domestic cloud provider alliances in India satisfy RBI data localization mandates for financial workloads. |
| Product Launch | eBPF-native security offerings eliminate sidecar proxy overhead that previously consumed container resource budgets. |
| Geographic Expansion | Tokyo-Osaka corridor presence captures precision manufacturing Kubernetes deployments under METI guidelines. |
Research Methodology
Multiple input streams — primary interviews with platform engineering directors, IT procurement officers, and sovereign cloud compliance leads; secondary validation through hyperscaler capex disclosures, SEC infrastructure software filings, and regional regulatory certification databases — were reconciled through bottom-up deployment modeling and top-down market sizing triangulation.
Historical spending patterns were cross-referenced against panel input from infrastructure vendors and enterprise adopters across the projection horizon. Segmentation dimensions modeled include deployment topology, service type tier, organization scale, vertical regulatory intensity, and regional sovereign compliance pattern. CAGRs were derived from installed base migration curves and greenfield adoption velocity, with specific weighting applied to container-native workload density trajectories and FedRAMP authorization pipeline throughput.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained Taiwan foundry disruption or accelerated EU AI Act enforcement timelines. Forecasts reflect documented assumptions regarding platform engineering talent availability, hyperscale pricing discipline, and sovereign cloud certification harmonization progress. A small set of named triggers — silicon supply concentration events, multi-cloud credential sprawl incidents, and stateful workload containerization breakthroughs — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Core Graphics Market
Digital Solutions
Self Service Technology Market
Digital Solutions
Global Cloud OSS BSS Market
Digital Solutions
Community Engagement Software Market
Digital Solutions
Asia-Pacific Computer Aided Engineering Market
Digital Solutions
Landing Page Builders Market
Digital Solutions
NFT Creation Software Market
Digital Solutions
Big Data As a Service (Bdaas) Market
Digital Solutions
Enterprise Mobility in Manufacturing Market
Digital Solutions
Ad Intelligence Software Market
Digital Solutions
Drone Mapping Software for Agriculture Market
Digital Solutions
Policy Orchestration Market
Digital Solutions
Crowdsourcing Market
Digital Solutions
Contactless Ticketing Ics Market
Digital Solutions
Global Personalization Engines Market
Digital Solutions
Global Advocacy Software Market