
 Enterprise Information Management (EIM) Solution Market | 2026-2036
Enterprise Information Management (EIM) Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Information Management (EIM) Solution Market Insights
The capital-intensity divergence between hyperscale cloud-native platforms and legacy on-premises specialists is rotating competitive dynamics across the EIM landscape. SAP SE leverages its embedded ERP data architecture to sustain enterprise lock-in across manufacturing and financial services verticals. IBM Corporation anchors its position through Watson-powered AI governance layers that differentiate its content analytics stack. Microsoft Corporation dominates the mid-market transition with Azure-native compliance and records management tooling that extends its productivity suite dominance.
Enterprise Information Management solutions encompass integrated software platforms that govern structured and unstructured data lifecycles through metadata tagging, automated classification engines, and policy-driven retention protocols. These systems orchestrate document capture, workflow routing, and archival destruction to ensure regulatory compliance and operational continuity across distributed organizations. Content Management and Data Governance segments lead current revenue pools as organizations confront exponential unstructured data growth and privacy mandates. Cloud-Based deployment is expanding fastest as enterprises retire legacy file servers and adopt API-first architectures, though On-Premises persists in defense and classified government environments where air-gapped infrastructure remains mandatory. Workflow Automation represents an emerging margin concentration point as vendors bundle robotic process orchestration with core document services.
The US HIPAA Security Rule and SEC recordkeeping requirements shape product roadmaps for domestic EIM vendors, while the EU GDPR and AI Act are forcing architecture redesigns for multinational deployments. ISO 27001 and NIST SP 800-53 certifications have become table stakes for vendor selection in regulated industries, narrowing the competitive field to providers with sustained compliance investment. Stakeholders must weigh the trade-off between cloud agility and jurisdictional data sovereignty as cross-border enforcement mechanisms tighten.
Market Dynamics
Cloud migration and AI integration are decomposing legacy on-premises architectures, forcing vendors to rebuild platforms around API-first microservices and federated data fabrics.
Growth Catalysts
- HIPAA Security Rule mandates:Healthcare providers in the United States must implement technical safeguards for electronic health records, accelerating EIM procurement cycles and platform modernization budgets.
- Unstructured data explosion:Manufacturing and financial services verticals generate petabyte-scale document volumes that require automated classification engines and policy-driven retention protocols.
- AI governance layers:Natural language processing and machine learning classification are embedding into core content management stacks, creating new automation revenue pools.
Market Restraints
- Data sovereignty compliance costs:Cross-border data localization requirements under GDPR and emerging national privacy laws force redundant infrastructure deployment.
- Legacy system technical debt:Decades of on-premises document repositories create integration friction that slows cloud migration timelines and inflates professional services costs.
- Specialized talent scarcity:Shortages of certified information governance professionals and data architects constrain implementation velocity for complex deployments.
Strategic Opportunities
- Workflow automation bundling:Robotic process orchestration converges with document capture services to create margin-rich integrated offerings for enterprise buyers.
- Defense and classified government verticals:Air-gapped infrastructure requirements sustain on-premises specialist positions as cloud-native vendors cannot serve these segments.
- EU AI Act compliance tooling:Automated audit trails and explainability documentation for AI-driven classification systems open new product categories for multinational deployments.
Industry Challenges
- ISO 27001 certification timelines:Sustained compliance investment requirements narrow the competitive field and strain mid-tier vendor R&D budgets.
- Multi-cloud orchestration complexity:Enterprises demand portability across Azure, AWS, and Google Cloud platforms, forcing vendors to abstract infrastructure dependencies.
- Metadata standardization gaps:Inconsistent taxonomies across acquired systems impede federated search and unified governance policy enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Information Management (EIM) Solution Market |
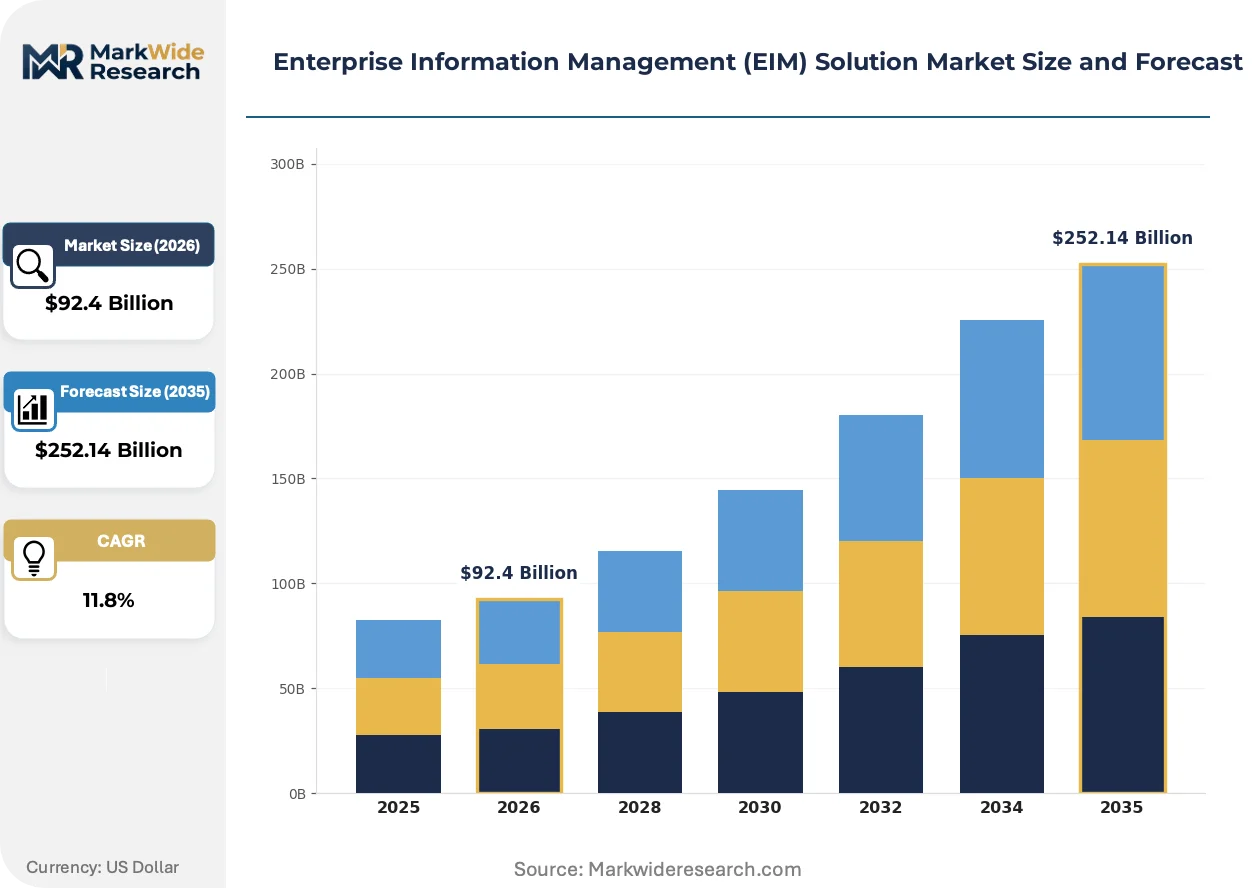
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $252.14 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Governance, Content Management, Workflow Automation, Document Management End User: Manufacturing, Healthcare, Education, Retail Deployment: On-Premises, Cloud-Based, Hybrid, Managed Services Solution: Business Intelligence, Records Management, Data Integration, Compliance |
| Companies Covered | SAP SE, Hewlett Packard Enterprise, IBM Corporation, Informatica, Adobe Inc., Oracle Corporation, Microsoft Corporation, Hyland Software Inc., OpenText Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Information Management (EIM) Solution Market Trends and Innovations
Generative AI and retrieval-augmented generation architectures are reshaping how enterprises discover, synthesize, and act upon distributed information assets.
Large language model-powered semantic search is decomposing traditional keyword-based retrieval systems. Healthcare and legal services buyers are deploying these engines to surface contextual insights across millions of unstructured documents. The technology is compressing time-to-insight metrics and collapsing the distinction between content management and business intelligence platforms.
EU AI Act documentation mandates are forcing architecture redesigns for automated classification systems deployed in European markets. Vendors must now embed explainability logging and human-in-the-loop audit trails into machine learning inference pipelines. Financial services and pharmaceutical sectors face the steepest compliance curves as they deploy high-risk AI applications for document processing.
Subscription-based consumption models are displacing perpetual license arrangements across mid-market buyers. Channel partners are pivoting from implementation resellers to managed service operators who assume ongoing platform operational responsibility. This shift concentrates most visibly in United States commercial segments where IT staffing constraints drive outsourcing preferences.
Enterprise Information Management (EIM) Solution Market Segmentation
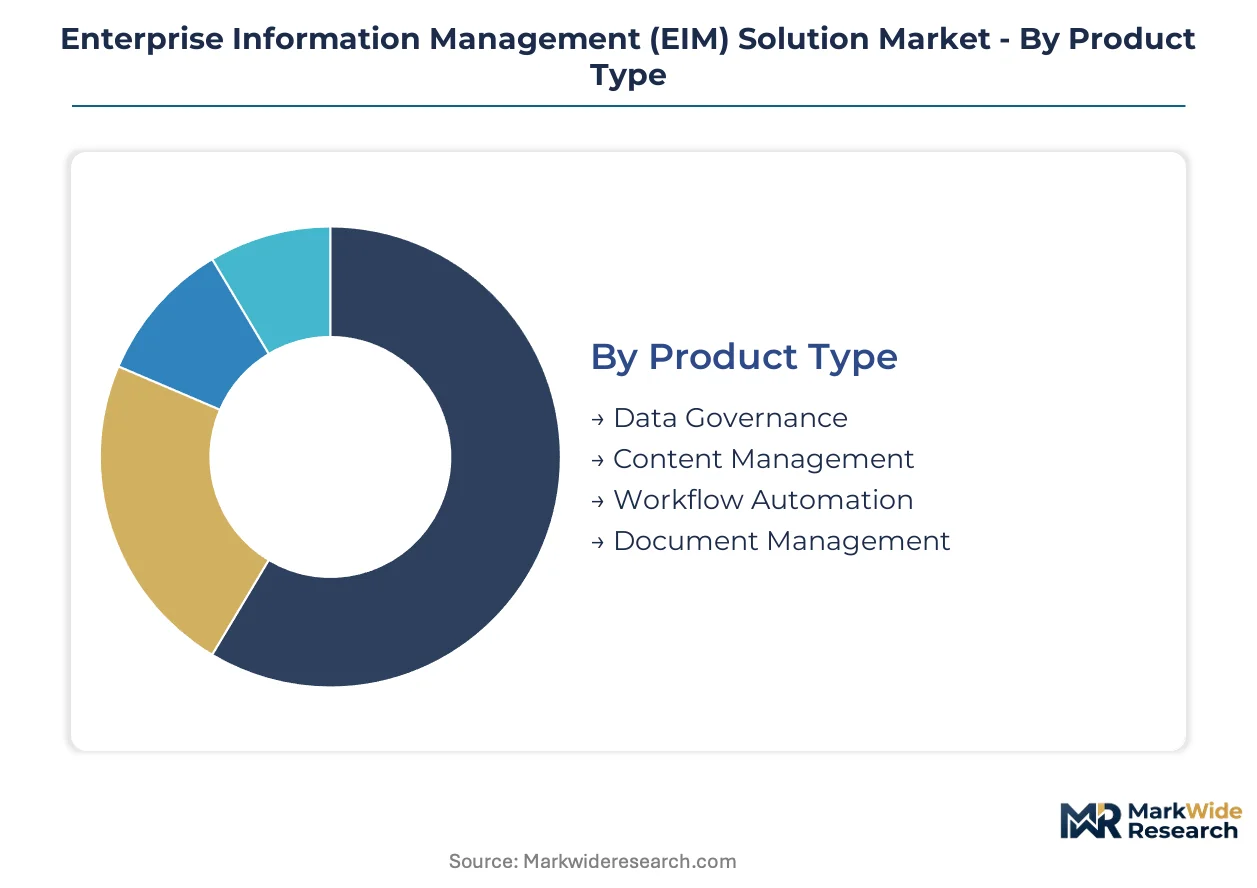
EIM procurement patterns diverge sharply across deployment architectures and regulatory exposure levels. Buyers segment investments by data sensitivity tiers, compliance velocity requirements, and legacy system entanglement depth.
Product Type:
Workflow Automation faces acute substitution pressure from standalone robotic process automation vendors unbundling document services. Content Management and Data Governance defend position through embedded compliance logic that point solutions cannot replicate.
- Content Management:Orchestrates document capture, versioning, and archival destruction across distributed repositories. HIPAA Security Rule mandates in United States healthcare systems sustain premium pricing for systems with embedded audit trails and legal hold capabilities.
- Data Governance:Enforces metadata standards, lineage tracking, and policy-driven retention across structured and unstructured assets. Financial services institutions in New York and London concentrate procurement to satisfy SEC recordkeeping requirements and GDPR accountability principles.
- Workflow Automation:Bundles robotic process orchestration with document routing to compress cycle times. Manufacturing verticals in Germany and Japan deploy these layers to synchronize ERP transactions with shop-floor documentation.
- Document Management:Provides foundational storage, retrieval, and security services for file-centric operations. Education sector buyers in Australia and Canada favor these systems for research archive administration.
Content Management retains volume leadership; Workflow Automation holds the steepest expansion curve.
End User:
Cost tier stratification separates enterprise-grade deployments from mid-market SaaS configurations. Healthcare and Manufacturing absorb the highest per-seat licensing premiums due to compliance complexity and integration depth.
- Healthcare:Electronic health record governance under HIPAA Security Rule and FDA 21 CFR Part 11 drives specialized procurement. United States hospital systems and European clinical networks prioritize systems with automated de-identification and consent management modules.
- Manufacturing:Product lifecycle documentation and supplier quality records generate petabyte-scale retention obligations. German automotive clusters and Japanese precision equipment makers demand ISO 27001-certified platforms with air-gapped deployment options.
- Education:Research data management and student record privacy shape procurement criteria. Australian universities and Canadian provincial systems favor open-standards architectures to avoid vendor lock-in.
- Retail:Customer data platforms and supply chain documentation require lightweight, API-first implementations. United Kingdom and France-based omnichannel operators prioritize real-time inventory synchronization across POS and e-commerce channels.
Healthcare commands the highest average contract value; Retail is expanding most quickly through cloud-native consumption models.
Deployment:
Customer type segmentation separates regulated enterprises with captive infrastructure from agile mid-market buyers outsourcing operational responsibility. Defense and classified government segments sustain on-premises demand that cloud-native vendors cannot serve.
- Cloud-Based:API-first microservices architectures enable rapid provisioning and elastic scaling. United States commercial segments and Nordic enterprise buyers lead migration timelines as IT staffing constraints drive outsourcing preferences.
- On-Premises:Air-gapped infrastructure mandatory for defense, intelligence, and critical infrastructure operators. Saudi Arabia and UAE government entities require sovereign data residency that hyperscale clouds cannot guarantee.
- Hybrid:Federated architectures partition sensitive workloads on-premises while bursting transactional volumes to cloud. Swiss financial institutions and Singapore healthcare networks deploy these configurations to balance agility with jurisdictional compliance.
- Managed Services:Channel partners assume ongoing platform operational responsibility under subscription arrangements. United Kingdom mid-market manufacturers and Australian professional services firms favor this model to internalize governance expertise.
Cloud-Based deployment is gaining share fastest; On-Premises retains strategic importance in sovereign-sensitive segments.
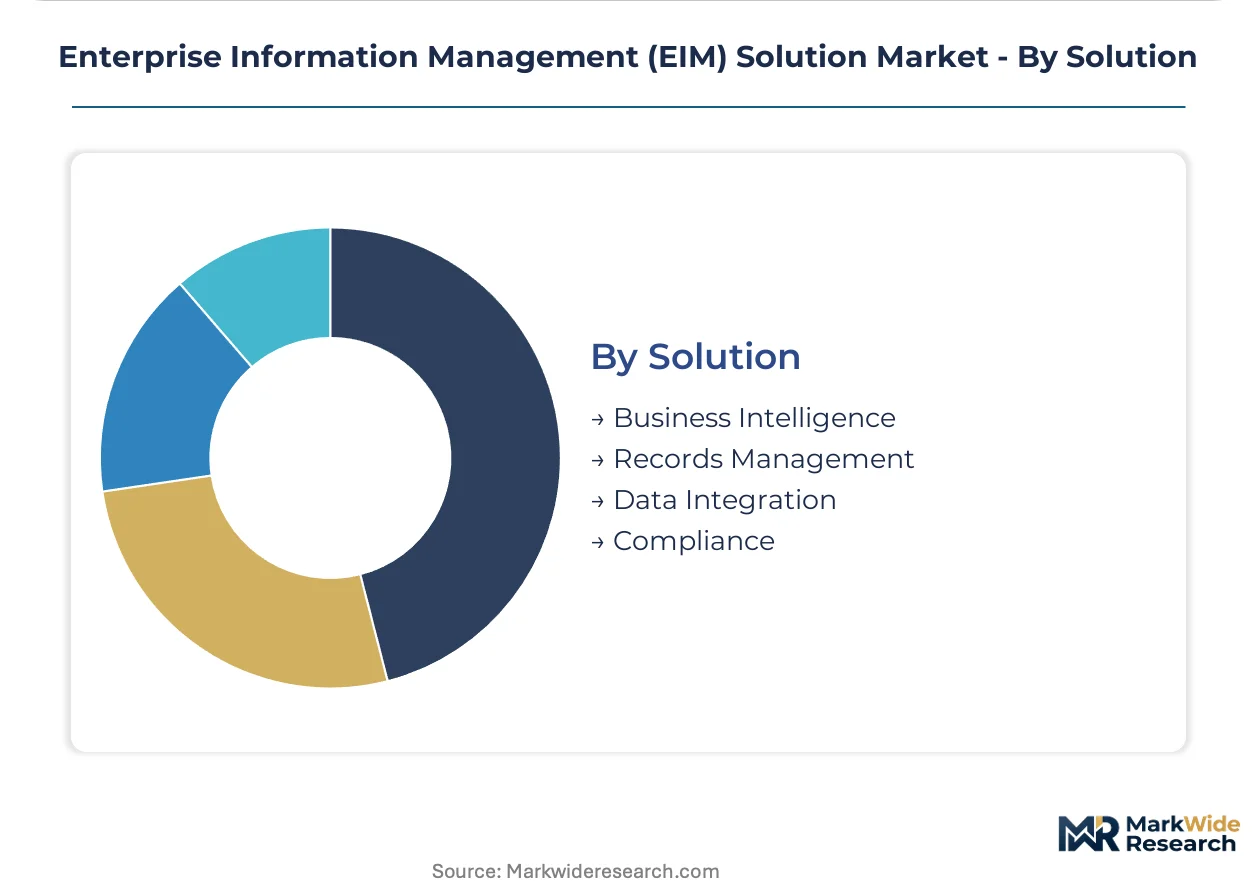
Solution:
Margin concentration varies by solution complexity and integration depth. Compliance and Data Integration solutions command implementation premiums that pure-play Business Intelligence vendors struggle to match.
- Compliance:Automated audit trails, retention scheduling, and legal hold management embed regulatory logic directly into content workflows. United States financial services and European pharmaceutical sectors face the steepest EU AI Act documentation mandates.
- Data Integration:Federated data fabrics unify siloed repositories through semantic layer abstraction. German industrial conglomerates and Japanese keiretsu structures prioritize these investments to harmonize acquired subsidiary systems.
- Records Management:Policy-driven lifecycle governance from creation through certified destruction. Australian government agencies and Canadian provincial archives specify these capabilities under national information management standards.
- Business Intelligence:Embedded analytics and reporting layers that surface operational metrics from managed content. United States retail chains and French logistics operators deploy these tools to compress decision latency.
Compliance solutions sustain the highest margin profile; Data Integration is climbing the fastest as enterprises confront metadata standardization gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers demonstrate the lowest price elasticity as HIPAA Security Rule mandates override budget constraints, while retail and education sectors in Australia and Canada drive hardest negotiations on per-seat licensing.
United States
Healthcare systems and financial institutions absorb premium pricing for compliance-embedded platforms. HIPAA Security Rule and SEC recordkeeping requirements sustain procurement velocity despite economic headwinds. Hospital networks in Boston and Minneapolis prioritize automated de-identification modules for electronic health record governance.
Germany
Automotive and industrial machinery clusters generate petabyte-scale documentation retention obligations. ISO 27001 certification serves as mandatory vendor qualification under national information security frameworks. Bavarian precision equipment makers and Baden-Württemberg automotive suppliers demand air-gapped deployment options for sensitive product lifecycle data.
United Kingdom
Mid-market manufacturers and professional services firms favor managed service consumption models. GDPR accountability principles and emerging FCA operational resilience rules shape architecture requirements. London-based omnichannel retailers deploy API-first implementations for real-time inventory synchronization across POS and e-commerce channels.
Japan
Keiretsu conglomerates prioritize federated data fabrics to harmonize acquired subsidiary systems. METI guidelines on data governance and cross-border transfer protocols influence platform selection. Tokyo and Osaka financial institutions invest in explainability logging for AI-driven classification systems ahead of regulatory enforcement.
Australia
Universities and government agencies specify open-standards architectures to avoid vendor lock-in. National information management standards mandate policy-driven lifecycle governance for public sector archives. New South Wales and Victoria research institutions lead procurement for student record privacy and research data management solutions.
Enterprise Information Management (EIM) Solution Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the EIM landscape. Hyperscale cloud-native vendors command API-first microservices architectures while legacy on-premises specialists retain defensive positions in air-gapped segments. The market structure consolidates around three strategic archetypes: ERP-embedded platform providers, standalone content management specialists, and productivity-suite extenders. Dominant competitive moves include cloud migration acceleration through professional services bundling and AI governance layer integration to differentiate core document services.
Within the ERP-embedded tier, SAP SE and Oracle Corporation exemplify enterprise lock-in strategies across manufacturing and financial services verticals. IBM Corporation occupies a position in AI-augmented governance through Watson-powered content analytics differentiation. Microsoft Corporation anchors the mid-market transition vector with Azure-native compliance tooling that extends productivity suite dominance. Hyland Software Inc. and OpenText Corporation represent standalone content management specialists defending margin through embedded compliance logic that point solutions cannot replicate.
| Leading Market Players |
|---|
| SAP SE |
| Hewlett Packard Enterprise |
| IBM Corporation |
| Informatica |
| Adobe Inc. |
| Oracle Corporation |
| Microsoft Corporation |
| Hyland Software Inc. |
| OpenText Corporation |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud capacity utilization above 75% in United States and Western European data centers compresses marginal delivery costs and establishes price floors that mid-tier SaaS vendors cannot undercut without sacrificing ISO 27001 certification maintenance. This scale concentration rewards API-first architectures while forcing legacy on-premises specialists into defensive bundling strategies that inflate professional services attach rates.
Pricing Analysis
Managed service and extended support contracts drive lifetime value in EIM procurement, with subscription renewal rates exceeding 85% for platforms embedding HIPAA-compliant audit trails. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade governance suites from mid-market SaaS configurations and basic document storage utilities. Cost compression in standard tiers is intensifying because hyperscale cloud-native vendors are absorbing infrastructure overhead through Azure and AWS volume commitments. Healthcare systems in Boston and Minneapolis demonstrate the lowest price sensitivity due to HIPAA Security Rule mandates, while Australian universities and Canadian education authorities negotiate hardest on per-seat licensing.
Supply Chain Analysis
The United States and Ireland anchor hyperscale cloud infrastructure provisioning for North American and European EIM deployments, while India and Poland concentrate professional services delivery and tier-two support operations. Software development draws from domestic engineering talent pools in Germany and Japan for air-gapped government solutions, with API development and quality assurance feeding from Indian technology hubs. Single-source vulnerability in hyperscale cloud substrate creates concentration risk for vendors without multi-cloud abstraction layers. Distribution runs through direct enterprise sales teams for healthcare and financial services accounts, with channel partners assuming operational responsibility for mid-market managed service arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EIM demand cycles track enterprise IT modernization budgets, which are recovering from prior-period austerity as HIPAA enforcement and EU AI Act documentation mandates accelerate replacement timelines.
For Market Incumbents: Consolidate defensive positions by acquiring workflow automation specialists to bundle robotic process orchestration with core document services, countering unbundling pressure from standalone RPA vendors. Deepen backward integration into AI governance layers through Watson-powered or Azure-native content analytics to differentiate against point solutions lacking embedded compliance logic.
For New Entrants and Emerging Players: Lead with air-gapped deployment expertise for defense and classified government verticals in Saudi Arabia and UAE, where sovereign data residency requirements exclude hyperscale cloud-native competitors. Target Australian education authorities and Canadian provincial archives with open-standards architectures that promise vendor independence, leveraging procurement criteria that prioritize interoperability over ecosystem lock-in.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed service operators who assume ongoing platform operational responsibility under subscription arrangements, particularly in United Kingdom mid-market manufacturing and Australian professional services segments. Acquisition screens should prioritize ISO 27001-certified specialists with established HIPAA or GDPR compliance modules. The signal to watch is channel partner pivot velocity from implementation resellers to managed service operators, indicating outsourcing preference consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding AI governance layers into core content management stacks differentiates against point solutions lacking Watson-powered or Azure-native analytics. |
| Acquisition of Specialist Firm | Consolidating workflow automation vendors bundles robotic process orchestration with document capture services to create margin-rich integrated offerings. |
| Strategic Partnership | Channel partner alliances with hyperscale cloud providers enable rapid provisioning and elastic scaling for mid-market buyers outsourcing operational responsibility. |
| Geographic Expansion | Establishing sovereign data residency capabilities in Saudi Arabia and UAE opens defense and classified government segments inaccessible to cloud-native vendors. |
| Product Launch | Explainability logging modules for AI-driven classification systems address EU AI Act documentation mandates in financial services and pharmaceutical sectors. |
Research Methodology
Initial hypotheses were tested against primary input from chief information officers, information governance officers, healthcare compliance directors, and channel partner executives and refined through secondary validation against SEC 10-K filings, hyperscaler capex disclosures, HIPAA enforcement actions, and EU AI Act implementation guidance. Bottom-up sizing triangulated vendor-reported subscription metrics with top-down enterprise IT budget allocation surveys across healthcare, manufacturing, and financial services verticals.
Variance decomposition across deployment model, organization size, vertical compliance exposure, and regional adoption pattern shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated electronic health record governance procurement velocity under HIPAA Security Rule mandates and cloud migration timeline assumptions for legacy on-premises repository retirement.
The analysis sits within stated boundaries; outcomes outside sustained HIPAA enforcement intensity or abrupt hyperscale cloud pricing adjustments would require recalibration. Forecasts reflect documented assumptions regarding AI governance layer adoption curves and channel partner business model transitions. Recalibration cycles align with material shifts in federal data governance mandates and cross-border data localization regulatory developments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Middle East Smart Card Market
Digital Solutions
Middle East and Africa Digital Signage Market
Digital Solutions
Online Classified Ad Platform Market
Digital Solutions
Global Industrial Design Market
Digital Solutions
Enterprise Application Integration (EAI) Market
Digital Solutions
Document Management System Market
Digital Solutions
Database Management Platform Market
Digital Solutions
Online Dating Market
Digital Solutions
India Loyalty Program Market
Digital Solutions
Sales Acceleration Technology Market
Digital Solutions
North America Enterprise Information Archiving (EIA) Market
Digital Solutions
Healthcare Video Conferencing Solutions Market
Digital Solutions
Decision Management Applications Market
Digital Solutions
North America Smart Card Market
Digital Solutions
ICT Investment in Government Market
Digital Solutions
Enterprise Content Management (ECM) Market