
 Smart Dictation Systems Market | 2026-2036
Smart Dictation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Dictation Systems Market Analytics
Multi-source API procurement is restructuring how healthcare enterprises acquire speech recognition capabilities. Microsoft Corporation leverages its Azure cloud infrastructure to embed dictation tools within clinical workflows, while Nuance Communications Inc. sustains deep integration with electronic health record systems through its Dragon platform. iFLYTEK Co. Ltd. anchors its position in Mandarin-language medical dictation across East Asian hospital networks.
Smart dictation systems combine automatic speech recognition engines with natural language processing pipelines to convert spoken audio into structured text, typically operating at latency thresholds below 300 milliseconds for real-time transcription. These systems serve commercial purposes ranging from clinical documentation and legal deposition capture to enterprise meeting transcription and accessibility compliance. Software solutions currently command the largest revenue share due to recurring subscription economics and rapid feature iteration, while natural language processing represents the fastest-expanding technology layer as transformer architectures improve contextual understanding of domain-specific terminology. Cloud-based deployment models are displacing on-premise installations in regulated industries where vendors now offer HIPAA-compliant managed environments.
FDA oversight of clinical decision support software intersects with HIPAA privacy rules to create dual compliance burdens for healthcare-facing dictation vendors. The EU AI Act adds algorithmic transparency requirements for systems deployed in European medical settings, while China's NMPA establishes separate approval pathways for AI-assisted diagnostic documentation tools. Stakeholders must monitor evolving cross-border data localization mandates that could fragment cloud hosting strategies and force region-specific model training investments.
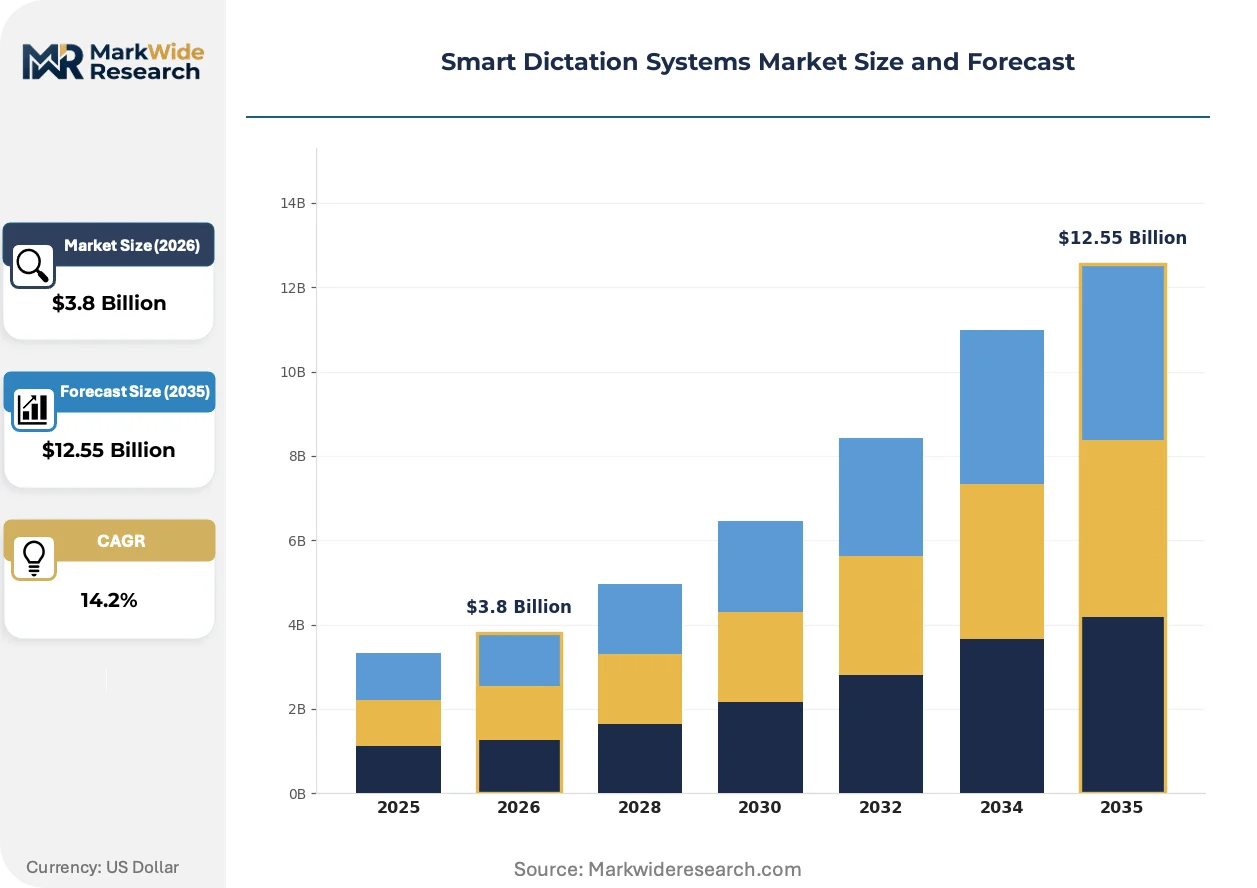
Market Dynamics
Transformer-based natural language processing architectures are compressing latency thresholds below 200 milliseconds, forcing incumbent speech recognition vendors to retrain models on clinical corpora or cede hospital procurement cycles to cloud-native competitors.
Growth Catalysts
- HIPAA-compliant cloud infrastructure:Healthcare systems in the United States are migrating transcription workloads to managed environments that satisfy federal privacy mandates without on-premise hardware overhead.
- Specialty clinic expansion:Ambulatory surgical centers and dermatology practices are deploying voice-driven documentation to reduce physician administrative burden.
- Transformer architectures:Self-attention mechanisms trained on medical ontologies are improving recognition accuracy for abbreviated clinical terminology and multi-speaker consultations.
Market Restraints
- GPU compute cost volatility:Model training and inference scaling for real-time transcription depends on NVIDIA H100 availability and cloud provider pricing tiers.
- Vendor concentration in Mandarin-language models:Hospital networks in East Asia face single-source dependency for dialect-specific acoustic training data.
- FDA software-as-medical-device classification:Clinical decision support integration triggers 510(k) submission requirements that extend vendor commercialization timelines.
Strategic Opportunities
- Rural health clinic underpenetration:Federally qualified health centers in the United States lack capital for enterprise dictation deployments, creating white space for subscription-tier offerings.
- EU AI Act algorithmic transparency mandates:European medical device manufacturers must document training data provenance, opening consulting and audit services for compliance vendors.
- Edge-device speech processing:On-chip neural accelerators in smartphones and tablets are enabling offline transcription for home health nursing workflows.
Industry Challenges
- Computational linguist talent scarcity:Vendors compete for PhD-level expertise in low-resource language modeling and clinical entity extraction.
- EHR integration complexity:Legacy Cerner and Epic installations require custom HL7 FHIR middleware development for bidirectional data exchange.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Dictation Systems Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Hardware Devices, Mobile Applications, Web-Based Platforms End User: Healthcare Providers, Legal Firms, Educational Institutions, Corporate Offices Technology: Cloud-Based, On-Premise, Voice Recognition, Natural Language Processing Deployment: Public Cloud, Private Cloud, Hybrid Model, Local Installation |
| Companies Covered | Alphabet Inc., Microsoft Corporation, Apple Inc., Amazon Web Services Inc., IBM Corporation, iFLYTEK Co. Ltd., Baidu Inc., Nuance Communications Inc., Speech Processing Solutions GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Dictation Systems Market Evolving Landscape
Speech recognition pipelines are fragmenting across deployment topologies as edge compute gains traction and regulatory jurisdictions impose divergent algorithmic accountability requirements.
Federated learning architectures are decentralizing model improvement by training on distributed hospital datasets without centralizing protected health information. Academic medical centers in the United States and university hospitals in Germany are piloting cross-institutional acoustic model updates. This architecture compresses data governance costs while preserving HIPAA and GDPR compliance boundaries.
The EU AI Act's risk classification system for biometric identification and emotion recognition is forcing dictation vendors to document training data demographics and error rate disparities across speaker populations. Medical device manufacturers must submit conformity assessments to notified bodies before deploying in European clinical settings. Specialty clinics are delaying procurement decisions pending regulatory clarity on transcription accuracy thresholds.
Hospital procurement committees are consolidating vendor relationships around integrated clinical documentation platforms rather than standalone dictation tools. Health systems in the United States are bundling speech recognition with computer-assisted physician order entry and radiology information systems. This preference shift favors vendors with existing EHR alliances and compresses pricing power for point-solution providers.
Smart Dictation Systems Market Segmentation
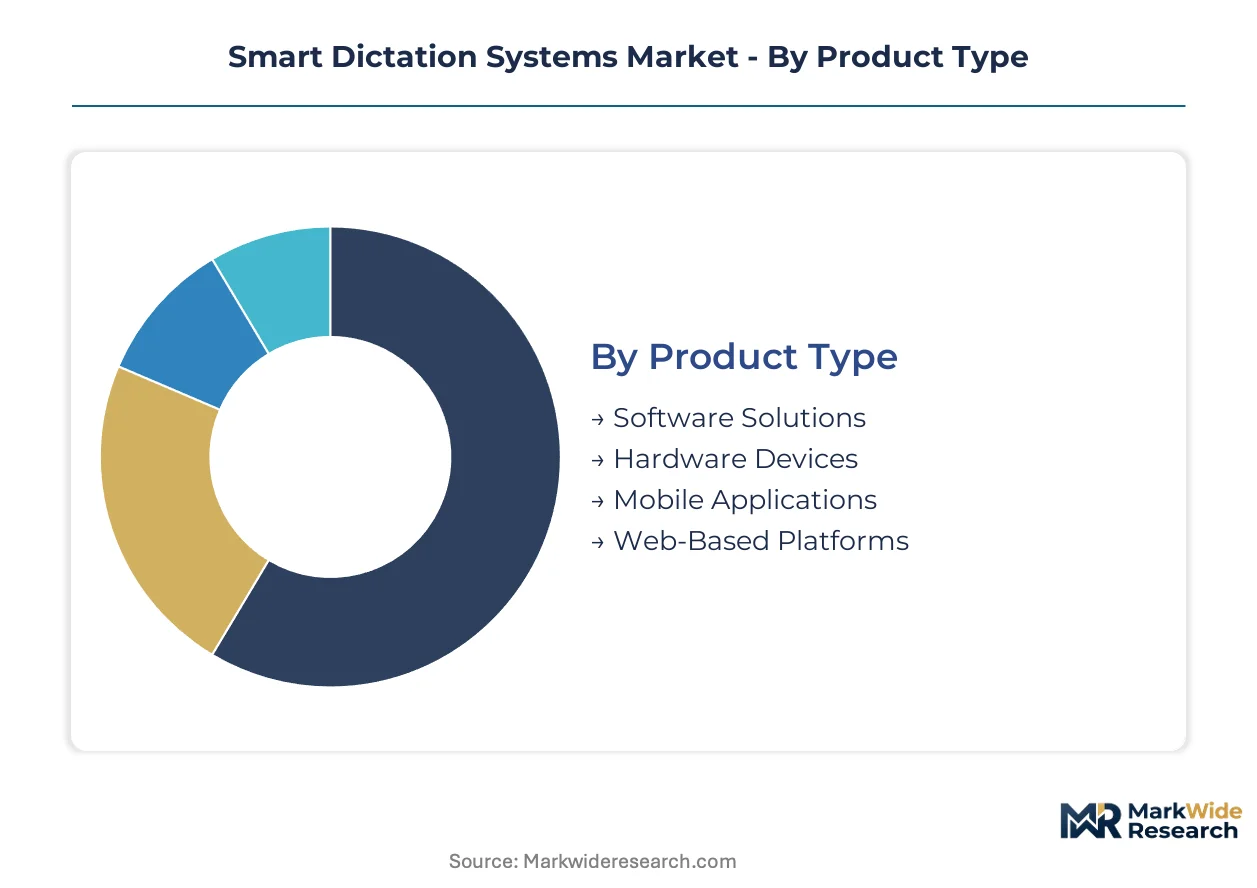
Smart dictation systems fragment across four orthogonal dimensions that reshape procurement criteria. Buyers prioritize HIPAA-compliant cloud infrastructure, EHR integration depth, acoustic model accuracy for clinical terminology, and total cost of ownership across hardware refresh cycles.
Product Type:
Healthcare enterprises and legal practices differentiate procurement decisions by recurring subscription economics versus capital expenditure tolerance.
- Software Solutions:Cloud-native transcription engines with automatic speech recognition pipelines dominate hospital procurement cycles through monthly per-seat licensing. United States health systems favor these deployments for rapid feature iteration without on-premise maintenance overhead. Recurring revenue models attract private equity consolidation.
- Hardware Devices:Dedicated dictation microphones with onboard noise cancellation and push-to-talk controls serve court reporters and pathology departments requiring offline operation. Specialty clinics in Germany and Japan specify these for forensic documentation integrity.
- Mobile Applications:Smartphone dictation tools with cloud sync enable home health nursing workflows and deposition capture outside fixed facilities.
- Web-Based Platforms:Browser-agnostic transcription interfaces reduce IT deployment friction for small legal practices and ambulatory surgical centers.
Software Solutions lead volumes today; Mobile Applications are gaining share fastest.
End User:
Regulatory exposure and documentation liability thresholds separate buyers across vertical markets.
- Healthcare Providers:Hospital systems and specialty clinics deploy voice-driven clinical documentation to reduce physician administrative burden. Epic and Cerner integration requirements dominate United States procurement specifications. FDA software-as-medical-device classification triggers 510(k) submission timelines for clinical decision support features.
- Legal Firms:Court reporting agencies and litigation practices require verbatim deposition capture with speaker diarization and timestamp precision. State bar association ethics rules in California and New York govern confidentiality protocols.
- Educational Institutions:Universities mandate lecture transcription for accessibility compliance under Section 504 and ADA requirements.
- Corporate Offices:Enterprise meeting transcription serves hybrid workforce documentation and regulatory record-keeping.
Healthcare Providers anchor current revenue concentration; Legal Firms show the steepest expansion trajectory.
Technology:
Latency requirements and data residency mandates drive architectural selection between centralized and distributed processing.
- Cloud-Based:Managed transcription APIs from Microsoft Azure and AWS deliver sub-300-millisecond latency for real-time clinical documentation. United States hospital systems migrate workloads to HIPAA-compliant environments. GPU compute cost volatility constrains vendor margin structures.
- Natural Language Processing:Transformer architectures with self-attention mechanisms trained on medical ontologies improve recognition accuracy for abbreviated clinical terminology. Academic medical centers pilot federated learning across institutional boundaries.
- On-Premise:Air-gapped installations serve defense contractors and intelligence agencies with classified information handling requirements.
- Voice Recognition:Legacy acoustic models with speaker-dependent training persist in specialized radiology dictation workflows.
Cloud-Based systems dominate deployment volumes; Natural Language Processing is climbing the fastest.
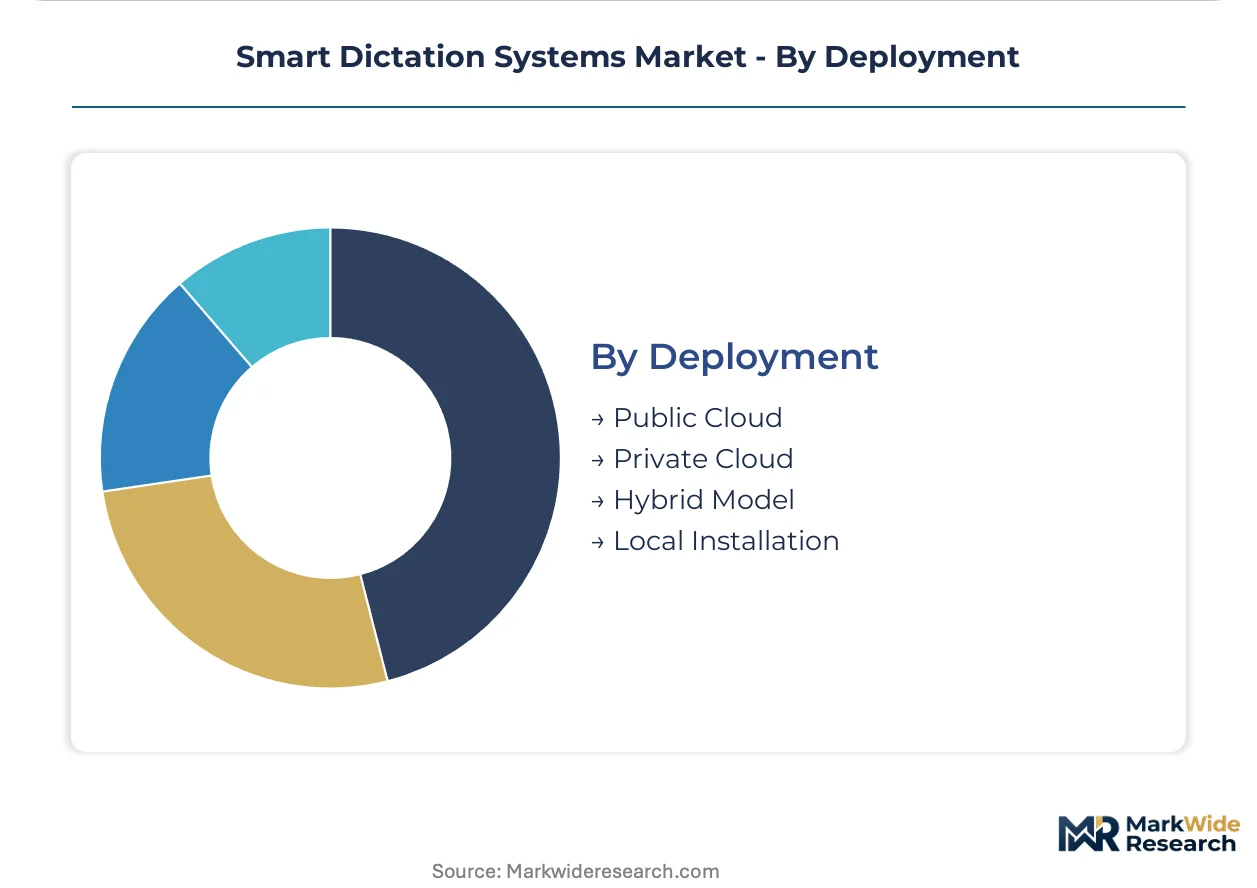
Deployment:
Data sovereignty requirements and cross-border patient flows determine hosting topology preferences.
- Private Cloud:Single-tenant environments satisfy GDPR Article 44 transfer restrictions and China's data localization mandates. German university hospitals and Saudi Arabian health clusters specify these for genomic data protection.
- Hybrid Model:Edge preprocessing with cloud refinement balances latency and compliance for multi-site health systems. United States rural health clinics use this architecture for intermittent connectivity scenarios.
- Public Cloud:Shared infrastructure delivers lowest unit economics for small legal practices and educational technology budgets.
- Local Installation:Offline-only deployments serve maritime, aviation, and expeditionary medical contexts without persistent connectivity.
Private Cloud leads enterprise procurement today; Hybrid Model adoption is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States drive enterprise dictation deployments, while cloud infrastructure investments in Germany and China reshape competitive access patterns across regulatory boundaries.
United States
Epic and Cerner integration requirements dominate health system procurement specifications for voice-driven clinical documentation. HIPAA compliance mandates and FDA software-as-medical-device classification create dual regulatory burdens for vendors seeking hospital contracts. The Mayo Clinic and Cleveland Clinic anchor pilot programs for federated learning architectures across academic medical centers.
Germany
University hospitals in Bavaria and North Rhine-Westphalia specify private cloud deployments to satisfy GDPR Article 44 transfer restrictions for patient genomic data. The EU AI Act's risk classification system forces dictation vendors to document training data demographics before notified body conformity assessments. Berlin-based health clusters delay procurement decisions pending regulatory clarity on transcription accuracy thresholds.
China
East Asian hospital networks in Shanghai and Beijing deploy Mandarin-language medical dictation tools with dialect-specific acoustic training data. NMPA establishes separate approval pathways for AI-assisted diagnostic documentation tools under national AI development priorities. iFLYTEK anchors its position across provincial health networks with localized model training investments.
United Kingdom
NHS trusts in London and Manchester migrate transcription workloads to managed cloud environments with data residency requirements. The Information Commissioner's Office enforces GDPR compliance boundaries for cross-border patient flows and genomic data handling. Cambridge and Oxford academic medical centers pilot edge-device speech processing for home health nursing workflows.
Japan
University hospitals in Tokyo and Osaka deploy voice-driven documentation to reduce physician administrative burden amid workforce shortages. METI promotes AI adoption in healthcare under Society 5.0 initiatives, while PMDA oversees software classification for clinical decision support features. Nagoya-based medical device manufacturers integrate dictation tools with radiology information systems.
Smart Dictation Systems Market Competitive Landscape
Global majors compete with regional champions across cloud infrastructure and EHR integration depth, creating a tiered structure where hyperscale platforms, specialized healthcare vendors, and language-specific regional players occupy distinct competitive positions. Consolidation pressures favor vendors with existing hospital system alliances and HIPAA-compliant managed environments. Three archetypes dominate: cloud-native platforms with transformer architectures, legacy speech recognition specialists with deep EHR integration, and regional champions with dialect-specific acoustic models. M&A activity targets point-solution providers lacking bundled platform capabilities, while strategic partnerships with electronic health record vendors secure procurement committee access.
Within the cloud-platform tier, Microsoft Corporation exemplifies infrastructure-led positioning through Azure-hosted clinical workflows, while Nuance Communications Inc. anchors the EHR-integrated specialist archetype with Dragon platform deployments. iFLYTEK Co. Ltd. represents the regional champion model, occupying a Mandarin-language position across East Asian hospital networks. These three patterns illustrate how competitive differentiation fragments across deployment topology, regulatory jurisdiction, and acoustic model specialization rather than concentrating around unified technology standards.
| Leading Market Players |
|---|
| Alphabet Inc. |
| Microsoft Corporation |
| Apple Inc. |
| Amazon Web Services Inc. |
| IBM Corporation |
| iFLYTEK Co. Ltd. |
| Baidu Inc. |
| Nuance Communications Inc. |
| Speech Processing Solutions GmbH |
| Others |
Value Network & Pricing Analysis
NVIDIA H100 GPU spot pricing volatility cascades through cloud transcription service tiers, compressing margins for real-time clinical dictation vendors while forcing buyers into longer-term committed use contracts to lock in compute rates.
Pricing Analysis
Input-cost pass-through from cloud infrastructure providers reshapes subscription economics across the market. Three-tier pricing structure across premium, standard, and economy levels separates enterprise hospital deployments with dedicated GPU allocation from mid-tier ambulatory subscriptions and basic per-seat offerings for small legal practices. Pricing pressure stems from hyperscaler margin compression as Microsoft Azure and AWS compete for healthcare workloads. Federally qualified health centers exhibit highest price sensitivity, while academic medical centers with NIH funding demonstrate lowest sensitivity due to grant-supported procurement.
Supply Chain Analysis
China's data localization mandates under NMPA guidance reshape sourcing strategies for Mandarin-language acoustic model training. GPU fabrication concentrates in Taiwan, South Korea, and the United States, while rare earth processing for neural accelerator chips feeds from Chinese refining complexes. Single-source vulnerability in NVIDIA H100 supply creates procurement bottlenecks for real-time inference scaling. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams with hospital GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between FDA software-as-medical-device pathways and NMPA AI documentation approvals creates cost-differential opportunities for vendors with dual-jurisdiction compliance capabilities.
For Market Incumbents: Extend EHR integration depth through custom HL7 FHIR middleware development for legacy Cerner and Epic installations, insulating against cloud-native competitors with superior transformer architectures. Deepen backward integration into proprietary clinical corpus training data to reduce dependency on academic medical center partnerships. Prioritize HIPAA-compliant managed environment certifications as hospital procurement committees consolidate vendor relationships.
For New Entrants and Emerging Players: Capture rural health clinic white space through subscription-tier offerings targeting federally qualified health centers with capital constraints. Focus initial deployment on ambulatory surgical centers and dermatology practices with lighter EHR integration requirements. Pursue channel partnerships with regional GPOs to bypass direct hospital procurement committee barriers.
For Investors and Strategic Acquirers: Asymmetric upside sits with point-solution providers possessing specialized acoustic models for low-resource languages or niche clinical domains. Long-term viability hinges on bundled platform capabilities rather than standalone dictation tools. Watch for FDA 510(k) submission timelines as inflection indicators for clinical decision support feature commercialization readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Dragon platform deployments with Epic and Cerner systems secure hospital procurement committee access. |
| Federated Learning Pilot | Mayo Clinic and Cleveland Clinic architectures compress data governance costs while preserving HIPAA boundaries. |
| Geographic Expansion | Berlin health clusters and Bavarian university hospitals drive private cloud deployment specifications under GDPR Article 44. |
| Acquisition of Specialist Firm | Regional champions with dialect-specific acoustic models fill Mandarin-language capability gaps for East Asian networks. |
| Regulatory Certification Investment | EU AI Act conformity assessments open consulting revenue streams for algorithmic transparency documentation. |
Research Methodology
Multiple input streams — hospital procurement database analysis, GPO contract reviews, hyperscaler capex disclosures, and CMS Medicare reimbursement filings — were reconciled against primary interviews with clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) submission databases, NMPA approval registries, EU AI Act implementation guidance, and cloud provider HIPAA compliance attestations. Bottom-up deployment estimates and top-down market sizing were triangulated to constrain variance.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment topology, end-user vertical, integration complexity, and regional regulatory cluster. CAGRs were derived from fitted growth curves against historical adoption patterns. Forecast inputs incorporated GPU availability constraints and hospital EHR refresh cycle timing without year-specific assumptions.
Regulatory reclassification, supply disruption in neural accelerator chips, and hospital capital expenditure freezes are the dominant revision risks that could compress or extend adoption trajectories. Forecasts reflect assumptions about compliance pathway stability and cloud infrastructure pricing continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
North America API Management Market
Digital Solutions
UAE Digital Twin Market
Digital Solutions
Global Automatic Content Recognition (ACR) Market
Digital Solutions
Smart Connected Assets and Operations Market
Digital Solutions
Mexico Digital Twin Market
Digital Solutions
Global Digital Art Software Market
Digital Solutions
Platform Architecture Market
Digital Solutions
Kuwait ICT Market
Digital Solutions
File Sharing Market
Digital Solutions
Everything As a Service (Xaas) Market
Digital Solutions
Next Generation Search Engines Market
Digital Solutions
Personality Assessment Solutions Market
Digital Solutions
Data Integration Market
Digital Solutions
Web Real-Time Communication (Webrtc) Market
Digital Solutions
Workflow Management System Market
Digital Solutions
Virtual Office Market