
 Global Logistics Software Market | 2026-2036
Global Logistics Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Logistics Software Market Foresight
Asset-light leasing models for transportation management platforms is tilting competitive dynamics toward vendors with scalable cloud architectures. SAP SE leverages deep ERP integration to anchor enterprise accounts across European manufacturing hubs. Blue Yonder specializes in AI-native supply chain planning, differentiating its offering from legacy warehouse modules. WiseTech Global dominates freight forwarding software in Asia-Pacific port ecosystems, extending its reach through customs compliance automation.
Logistics software encompasses integrated applications that coordinate transportation, warehousing, and inventory flows through real-time data exchange, API orchestration, and algorithmic optimization engines. These systems process shipment telemetry, carrier rates, and demand signals to minimize transit costs and fulfillment latency. Cloud-based deployment now leads solution uptake as mid-market operators abandon capital-intensive on-premise infrastructure. Warehouse management systems represent the deepest margin pool within solution offerings, while cold chain use cases are expanding fastest due to pharmaceutical and perishable food compliance requirements.
The EU AI Act, FDA track-and-trace mandates for pharmaceutical distribution, and China's SAMR data-localization rules are fragmenting product certification pathways across jurisdictions. Vendors must architect multi-tenant compliance layers to maintain market access without duplicating codebase instances. Stakeholders should monitor regulatory divergence between Brussels and Beijing as the primary determinant of platform development roadmaps and partnership strategies.
Market Dynamics
Cloud-native architectures are displacing on-premise infrastructure as mid-market logistics operators abandon capital-intensive hardware investments, forcing incumbent vendors to re-platform or lose enterprise accounts to API-first competitors.
Growth Catalysts
- EU AI Act compliance mandates:Automated routing systems in Germany, France, and the Netherlands require algorithmic audit trails, creating replacement demand for legacy transportation management platforms lacking explainable AI capabilities.
- Pharmaceutical cold chain expansion:FDA track-and-trace mandates and EMA serialization requirements are forcing 3PLs to deploy temperature-monitoring software with real-time deviation alerting across European distribution networks.
- Asia-Pacific port digitization:China's SAMR data-localization rules and Singapore's Maritime Single Window initiative are accelerating customs compliance automation investments in freight forwarding software.
Market Restraints
- Multi-tenant compliance architecture costs:Vendors must engineer separate certification pathways for EU AI Act, FDA pharmaceutical mandates, and China's SAMR rules without duplicating codebase instances, inflating R&D burn rates.
- Specialized talent scarcity:Supply chain optimization engineers with expertise in operations research and cloud-native development command premium compensation in Germany and the Netherlands, constraining vendor scaling velocity.
- Legacy system entrenchment:European automotive manufacturers maintain decades-old warehouse management installations with deep ERP integration, extending replacement cycles and blocking cloud migration.
Strategic Opportunities
- India's logistics corridor modernization:The Dedicated Freight Corridor Corporation's track expansion and DGFT's digitization push create first-mover advantage for transportation management platforms with rail-truck multimodal optimization.
- Battery supply chain traceability:EU Battery Regulation due diligence requirements and US IRA critical mineral sourcing rules are opening demand for cobalt-lithium supply chain visibility software in automotive and electronics verticals.
- Digital freight brokerage convergence:Real-time rate marketplaces are hybridizing with transportation management systems, enabling small carriers in Brazil and Mexico to access enterprise shipper contracts previously gated by relationship networks.
Industry Challenges
- API orchestration complexity:Mid-market 3PLs struggle to integrate carrier EDI feeds, IoT sensor streams, and customs filing systems into unified data lakes without dedicated integration engineering teams.
- Algorithmic bias certification:EU AI Act requirements for automated routing decisions demand documentation of training data provenance and outcome fairness testing that most vendors lack internal capabilities to produce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Logistics Software Market |
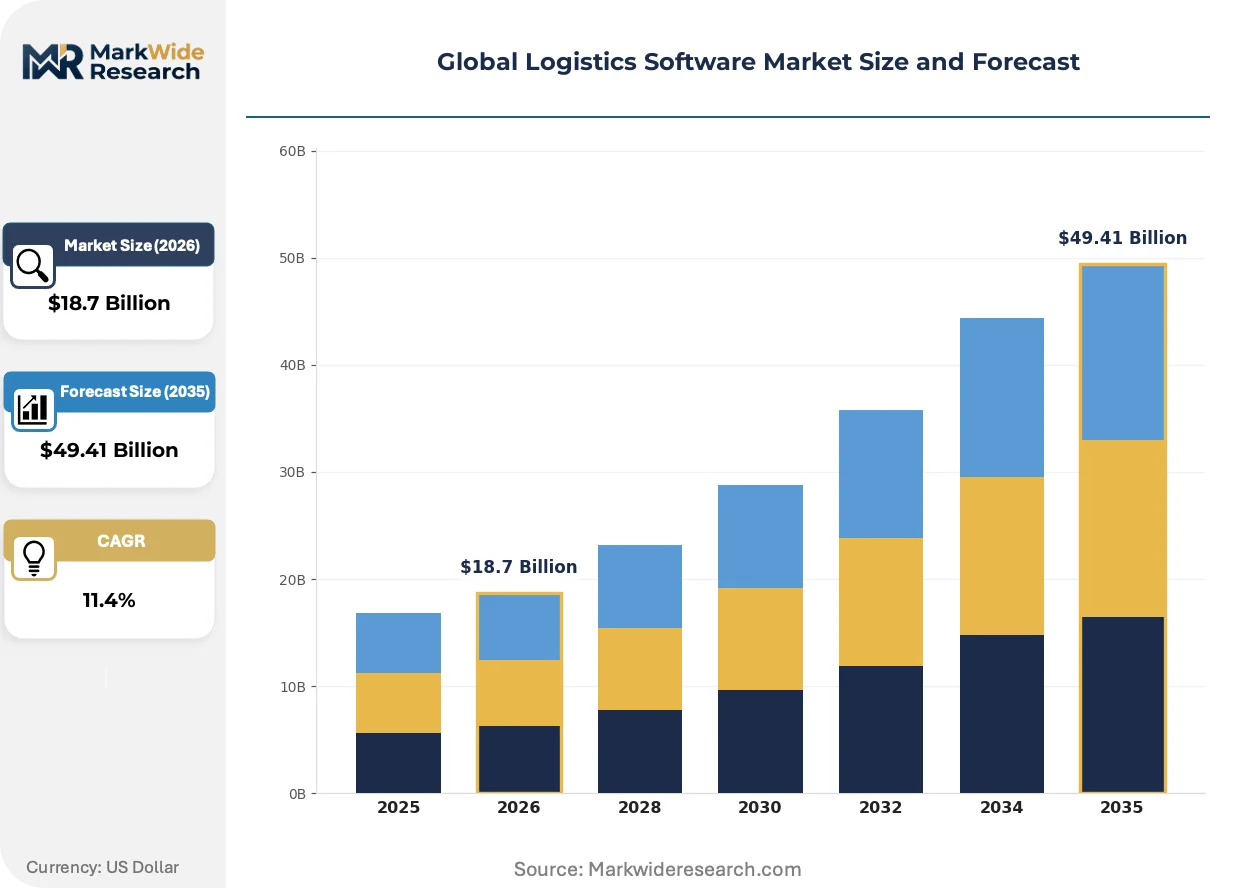
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, SaaS, Hosted Solution Offering: Transportation Management, Warehouse Management, Fleet Management, Inventory Control, Order Management Use Case: Last-Mile Delivery, Freight Forwarding, Cold Chain, Reverse Logistics, Parcel Tracking End User: Third-Party Logistics Providers, E-Commerce Platforms, Retail Chains, Manufacturing Firms, Distribution Centers |
| Companies Covered | Microsoft Corporation, Blue Yonder, SAP SE, Infor, Descartes Systems Group, Oracle Corporation, Manhattan Associates, WiseTech Global, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Logistics Software Market Shifts & Advancements
Generative AI is compressing planning cycle times while edge computing architectures push optimization closer to warehouse floors and vehicle cabs, fragmenting traditional centralized control models.
Digital twin simulation is hybridizing warehouse layout optimization with real-time operational feedback. Retail and grocery distributors in Germany and the UK are deploying physics-based models to test slotting algorithms before physical reconfiguration, cutting implementation risk. The technology is compressing capital deployment timelines for automated storage and retrieval system investments.
REACH chemical compliance and EU AI Act algorithmic accountability are forcing warehouse management vendors to embed audit logging and substance traceability by default. Pharmaceutical and electronics manufacturers face the strictest documentation requirements, driving procurement preference toward platforms with pre-certified compliance modules rather than retrofitting legacy installations.
Shippers are unbundling transportation management from full-service 3PL contracts, procuring software directly from vendors and contracting carriers through digital freight marketplaces. This disintermediation is most advanced in US and European consumer packaged goods verticals, where procurement teams negotiate SaaS subscriptions separately from freight execution services.
Global Logistics Software Market Segmentation
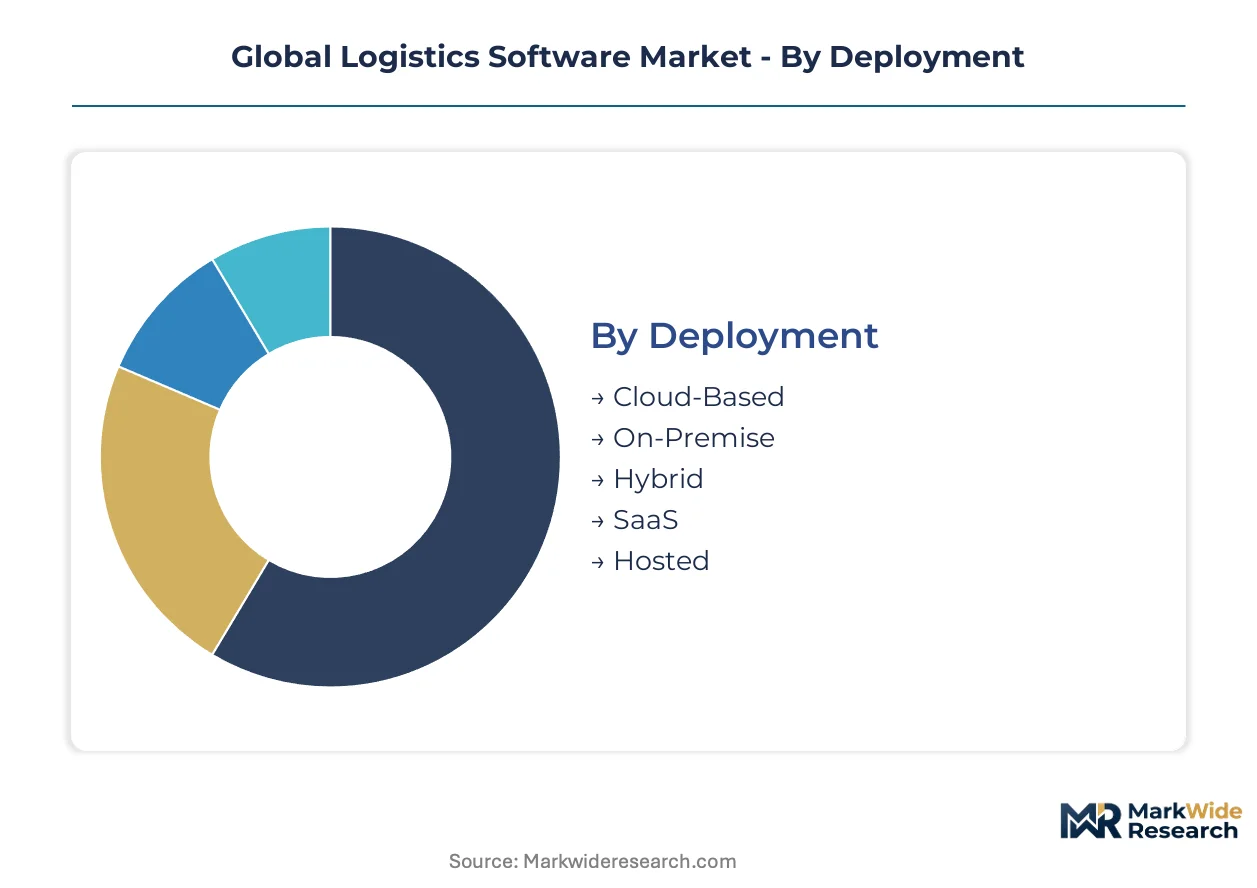
Logistics software segmentation reveals divergent procurement cycles across deployment modes and solution types. Cloud-native platforms refresh every 18-24 months while on-premise warehouse systems persist for 7-10 years, creating portfolio complexity for vendors serving mixed customer bases.
Deployment:
Cycle times vary dramatically by deployment architecture, with SaaS platforms turning over fastest and hybrid installations exhibiting the longest evaluation periods.
- SaaS:Multi-tenant subscription models with automatic feature updates and usage-based pricing tiers. German automotive suppliers and Dutch 3PLs favor SaaS for transportation management to avoid capital expenditure approval cycles.
- Cloud-Based:Dedicated instance cloud deployments offering customization without infrastructure ownership. French pharmaceutical distributors prioritize cloud-based warehouse management for EMA serialization compliance without on-premise server maintenance.
- Hybrid:Split architectures keeping sensitive data on-premise while leveraging cloud analytics. Japanese electronics manufacturers deploy hybrid inventory control to satisfy METI data localization requirements while accessing AI forecasting tools.
- Hosted:Vendor-managed single-tenant environments mimicking on-premise control. Italian fashion retailers prefer hosted order management for direct database access without internal IT overhead.
- On-Premise:Customer-operated infrastructure with perpetual licensing. Spanish food processors retain on-premise fleet management in rural facilities with unreliable broadband connectivity.
SaaS anchors the volume base while cloud-based deployments gain share at the steepest rate.
Solution Offering:
Margin structures diverge sharply across solution types, with warehouse management commanding premium pricing and inventory control facing commoditization pressure.
- Warehouse Management:Real-time slotting optimization, labor orchestration, and automation equipment integration. Cold chain operators in Belgium and the Netherlands pay premiums for temperature-zone compliance modules.
- Transportation Management:Carrier selection, route optimization, and freight audit automation. US consumer packaged goods shippers unbundle TMS from 3PL contracts to negotiate SaaS subscriptions directly.
- Inventory Control:Demand forecasting, safety stock calculation, and multi-echelon replenishment. Indian pharmaceutical distributors adopt inventory control suites following DGFT track-and-trace digitization mandates.
- Fleet Management:Vehicle telematics, driver compliance logging, and fuel optimization. Brazilian agribusiness operators deploy fleet management for soybean corridor truck scheduling.
- Order Management:Omnichannel allocation, promise management, and returns orchestration. UK grocery chains prioritize order management for click-and-collect fulfillment synchronization.
Warehouse management generates the deepest margins while transportation management expands most quickly through shipper direct procurement.
Use Case:
Application maturity spans from established freight forwarding to emerging reverse logistics automation, with cold chain exhibiting the steepest capability gaps.
- Cold Chain:Temperature monitoring, deviation alerting, and chain-of-custody documentation. FDA and EMA pharmaceutical mandates drive replacement of legacy systems lacking real-time sensor integration.
- Last-Mile Delivery:Dynamic routing, customer communication, and proof-of-capture optimization. South Korean e-commerce platforms deploy last-mile solutions for same-day delivery density in Seoul metropolitan zones.
- Freight Forwarding:Customs filing, documentation management, and multi-modal shipment tracking. Singapore's Maritime Single Window initiative accelerates compliance automation investments in port ecosystems.
- Parcel Tracking:Event streaming, exception management, and customer self-service portals. Mexican cross-border e-commerce operators adopt parcel tracking for US-bound shipment visibility.
- Reverse Logistics:Returns authorization, refurbishment routing, and resale channel allocation. German electronics retailers build reverse logistics capabilities for EU Battery Regulation recycling compliance.
Freight forwarding anchors the volume base while cold chain gains share at the steepest rate.
End User:
Customer sophistication tiers separate enterprise manufacturers from mid-market 3PLs, with procurement authority shifting toward IT departments in digitally mature organizations.
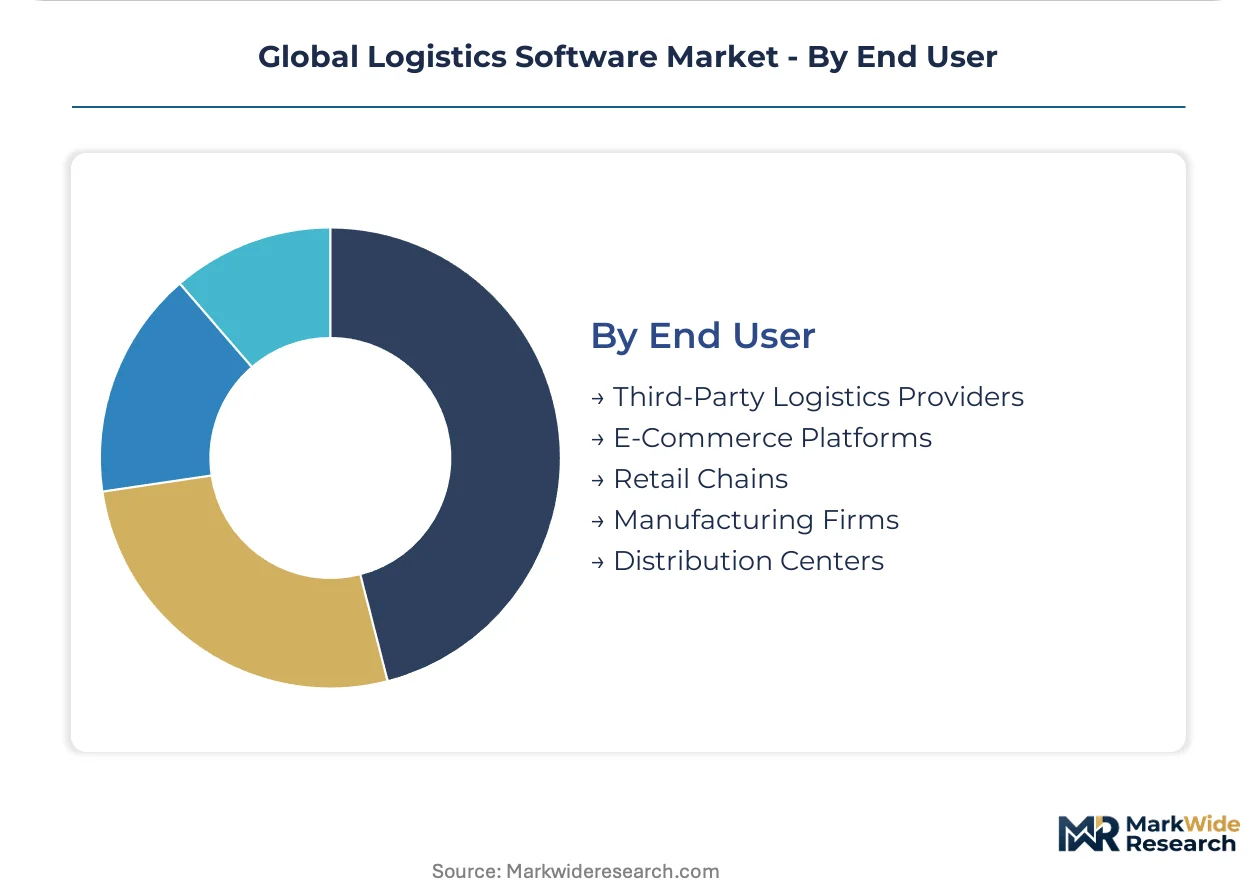
- Third-Party Logistics Providers:Multi-tenant platform operators serving shipper portfolios with specialized vertical expertise. European 3PLs expand platform investments as cloud migration accelerates and shipper clients demand API-first integration.
- Manufacturing Firms:Industrial producers with deep ERP integration requirements and long replacement cycles. German automotive manufacturers maintain decades-old warehouse installations, extending replacement timelines and blocking cloud migration.
- E-Commerce Platforms:Digital-native retailers prioritizing speed-to-implement over customization depth. Indian e-commerce operators adopt transportation management platforms for Dedicated Freight Corridor rail-truck optimization.
- Retail Chains:Omnichannel operators balancing store fulfillment with distribution center efficiency. UK grocery distributors deploy digital twin simulation for warehouse layout testing before automated storage investments.
- Distribution Centers:Specialized operators serving as intermediaries between manufacturers and retail endpoints. US pharmaceutical distributors prioritize FDA track-and-trace compliance in procurement decisions.
Third-party logistics providers anchor the volume base while e-commerce platforms gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade corridor digitization and customs modernization programs are rebalancing procurement authority toward software-native operators in major logistics hubs. Export-import volume intensity directly correlates with platform sophistication requirements across manufacturing and distribution centers.
Germany
Industrial freight corridors through the Rhine-Ruhr and Bavaria drive enterprise transportation management procurement for automotive and machinery exporters. The EU AI Act mandates algorithmic audit trails for automated routing systems, forcing replacement of legacy platforms lacking explainable AI capabilities. Stuttgart and Munich manufacturing clusters anchor demand for warehouse management systems with deep ERP integration.
United States
Pharmaceutical distributors prioritize FDA track-and-trace compliance modules following serialization mandates for drug supply chains. Consumer packaged goods shippers unbundle transportation management from 3PL contracts to negotiate SaaS subscriptions directly with vendors. Chicago and Dallas distribution centers lead adoption of digital freight brokerage convergence for mid-market carrier access.
China
SAMR data-localization rules accelerate customs compliance automation investments in port ecosystems across Shanghai and Shenzhen. Freight forwarding software demand concentrates in Asia-Pacific container terminals processing electronics and automotive exports. The Yangtze River Delta logistics cluster drives multi-modal optimization platform procurement for rail-truck coordination.
India
The Dedicated Freight Corridor Corporation's track expansion creates first-mover advantage for transportation management platforms with rail-truck multimodal capabilities. DGFT digitization mandates push pharmaceutical distributors toward inventory control suites with track-and-trace functionality. Mumbai and Delhi-NCR distribution hubs anchor cold chain software demand for temperature-sensitive pharmaceutical exports.
Singapore
The Maritime Single Window initiative accelerates compliance automation investments in freight forwarding software for transshipment cargo. Port digitization programs drive API-first platform procurement among third-party logistics providers serving Southeast Asian manufacturing networks. The city-state's logistics technology cluster anchors regional headquarters for vendors targeting ASEAN trade corridors.
Global Logistics Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in warehouse management and transportation optimization modules. The vendor landscape exhibits tiered concentration with enterprise ERP-anchored suites occupying the premium segment and API-native challengers penetrating mid-market transportation management. Three archetypes dominate: legacy ERP extenders with deep manufacturing integration, cloud-native specialists in supply chain planning, and freight forwarding automation leaders in port ecosystems. Competitive dynamics center on M&A activity consolidating point solutions into unified suites and strategic partnerships embedding compliance modules into core platforms.
Within the ERP-anchored tier, SAP SE and Oracle Corporation represent the incumbent integration model for European and North American manufacturing accounts. Blue Yonder exemplifies the AI-native planning specialist archetype with differentiated supply chain optimization capabilities. WiseTech Global occupies a position in freight forwarding automation, particularly across Asia-Pacific customs compliance workflows. These three anchors illustrate divergent strategic postures: vertical integration through ERP extension versus horizontal specialization in planning algorithms versus geographic concentration in port-centric trade documentation.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Blue Yonder |
| SAP SE |
| Infor |
| Descartes Systems Group |
| Oracle Corporation |
| Manhattan Associates |
| WiseTech Global |
| IBM Corporation |
| Others |
Supply & Pricing Matrix
EU AI Act compliance chokepoints determine both pricing tier spreads and supply chain shape, forcing vendors to engineer multi-tenant certification layers that inflate R&D burn rates and compress margins on standard-tier offerings.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers command spreads based on EU AI Act pre-certification and FDA track-and-trace module bundling, while standard tiers face compression from open-source API alternatives. Cost compression in the economy tier intensifies because Indian and Brazilian mid-market operators prioritize speed-to-implement over customization depth. Third-party logistics providers exhibit highest price sensitivity due to thin shipper contract margins, whereas German automotive manufacturers show lowest sensitivity where ERP integration depth dominates procurement criteria.
Supply Chain Analysis
US export-control restrictions on advanced AI training hardware limit flows to Chinese and Russian logistics software developers, fragmenting talent access and cloud infrastructure procurement. Engineering talent concentrates in Germany, the Netherlands, and India, while cloud compute capacity draws from US hyperscaler regions and Singapore data centers. Single-source vulnerability sits with NVIDIA GPU supply for edge-computing optimization modules. Distribution runs through direct enterprise sales teams for manufacturing accounts and API marketplace integrations for mid-market transportation management uptake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Logistics software functions as a service-attach opportunity where compliance-as-a-service modules expand faster than core platform subscriptions, with EU AI Act audit-trail offerings outpacing warehouse management license growth.
For Market Incumbents: Pre-empt API-native challengers by embedding EU AI Act compliance modules into existing ERP-anchored suites before shipper direct procurement accelerates. Acquire specialized cold chain sensor integration firms to defend margin position in pharmaceutical verticals where FDA track-and-trace mandates concentrate replacement demand.
For New Entrants and Emerging Players: India's Dedicated Freight Corridor rail-truck multimodal optimization represents the most penetrable white-space target, with DGFT digitization mandates creating procurement urgency among pharmaceutical distributors lacking legacy system entrenchment. Enter through API-first transportation management partnerships with regional 3PLs rather than direct enterprise sales cycles.
For Investors and Strategic Acquirers: EU AI Act enforcement milestones reshape the acquisition landscape, elevating vendors with pre-built algorithmic audit-trail capabilities above legacy warehouse module providers. Target AI-native supply chain planning specialists with explainable routing engines over generic cloud migration plays. Monitor Brussels-Beijing regulatory divergence as the primary inflection signal for platform development roadmap viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Module Pre-Certification | EU AI Act audit-trail capabilities accelerate German automotive procurement cycles against legacy competitors. |
| API-First Platform Architecture | Real-time carrier EDI integration captures mid-market 3PLs abandoning capital-intensive infrastructure. |
| Specialist Firm Acquisition | Cold chain sensor integration adds FDA track-and-trace functionality for pharmaceutical distributor verticals. |
| Geographic Expansion | India Dedicated Freight Corridor presence secures first-mover rail-truck optimization contracts. |
| Strategic Partnership | Digital freight brokerage convergence opens Brazilian and Mexican carrier networks to enterprise shipper contracts. |
Research Methodology
Cross-validation between primary interviews with supply chain directors, CTOs at third-party logistics providers, platform engineers, and integration specialists and secondary sources including SEC filings, EU regulatory databases, customs trade data, and hyperscaler capex disclosures anchors the qualitative findings. Bottom-up vendor revenue triangulation against top-down end-user IT spending surveys validates segment-level estimates.
Calibration against historical deployment cycle data and regulatory implementation timelines shapes the analytical framework across deployment modes, solution types, use cases, and end-user verticals. CAGRs derive from logistic curve adoption modeling with inflection points tied to EU AI Act enforcement phases and FDA serialization mandate deadlines. Cloud migration velocity and pharmaceutical cold chain expansion serve as primary volume drivers in the projection framework.
Practitioners should monitor Brussels-Beijing regulatory divergence, FDA track-and-trace enforcement intensity, and Indian rail infrastructure completion schedules for early signals. Material shifts in EU AI Act liability interpretations or SAMR data-localization scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Employee Recognition and Reward System Market
Digital Solutions
IT As a Service Market
Digital Solutions
Commodity Supply Chain Management Solution Market
Digital Solutions
Global Digital Accessibility Software Market
Digital Solutions
Enterprise Information Management (EIM) Solution Market
Digital Solutions
Global Remote Monitoring and Management (RMM) Tools Market
Digital Solutions
Global Mesh App and Service Architecture Market
Digital Solutions
Reverse Logistics Visibility and Disposition Optimization Platforms Market
Digital Solutions
Hyperlocal Services Market
Digital Solutions
Switzerland ICT Market
Digital Solutions
Digital Twin in Construction Market
Digital Solutions
Managed File Transfer (MFT) Market
Digital Solutions
Web Based E-Detailing Market
Digital Solutions
Global Enterprise Information Archiving Market
Digital Solutions
Online Laundry Services Market
Digital Solutions
Global Interactive Voice Response Market