
 Wood Router Market | 2026-2036
Wood Router Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Router Market Outlook
Multi-source component procurement is consolidating among wood router OEMs seeking supply chain resilience after pandemic-era shortages. Robert Bosch GmbH leverages its power-tool ecosystem to sustain brand loyalty in the European professional segment. HOMAG Group anchors its position through captive control over machine control software and servo systems. SCM Group differentiates via deep specialization in high-speed spindle integration for Italian furniture manufacturing clusters.
A wood router is a motorized cutting machine that spins a collet-mounted bit at speeds typically ranging from 8,000 to 30,000 RPM to shape, groove, or profile wood stock. Its primary commercial purpose centers on precision material removal for dimensioning, joinery preparation, and decorative edge formation across solid wood and engineered panel substrates. CNC routers occupy the highest-margin tier as furniture manufacturers automate batch production of complex joinery and carved decorative work. Electric technology dominates installed base volumes, though hybrid pneumatic-electric spindles gain traction in high-duty-cycle industrial environments where thermal management limits pure electric endurance. Plunge routers retain stronghold status in European woodworking shops performing mortise-and-tenon joinery, while trim routers experience fastest uptake among North American hobbyists executing laminate edge banding and small-scale decorative profiling.
OSHA lockout-tagout standards and machine guarding requirements shape product design for routers sold into US commercial environments, while EU Machinery Directive 2006/42/EC and CE marking obligations enforce emergency-stop integration and noise emission limits across European distribution channels. Germany's KBA-aligned occupational safety frameworks and France's CNIL-influenced data protocols for connected CNC systems add compliance layers for smart routing equipment. Stakeholders must monitor evolving interoperability standards between machine tools and factory ERP systems as woodworking automation deepens.
Market Dynamics
Furniture manufacturers in Guangdong Province are accelerating CNC router deployment as export orders demand tighter dimensional tolerances and shorter batch cycles, compressing the upgrade timeline for manual-to-automated production lines.
Growth Catalysts
- EU Machinery Directive 2006/42/EC:Tightened safety and electromagnetic compatibility requirements for powered woodworking equipment are forcing factory upgrades across German and Italian furniture clusters, creating replacement demand for compliant routing systems.
- High-speed spindle integration:Italian furniture manufacturing clusters are adopting 24,000+ RPM spindles for complex decorative profiling, enabling batch production of carved components previously requiring manual craftsmanship.
- OSHA lockout-tagout standards:US commercial woodworking environments face intensified machine guarding inspections, driving capital expenditure on routers with integrated emergency-stop systems and interlocked guards.
Market Restraints
- Copper and rare-earth magnet cost volatility:Electric router spindle motors depend on neodymium permanent magnets and copper windings, exposing OEM margins to commodity price swings in Chinese and African supply corridors.
- Control software concentration:Captive machine control ecosystems from dominant European suppliers create switching costs for furniture manufacturers seeking to mix equipment brands across production lines.
- Thermal management limitations:Pure electric spindle endurance caps at approximately 8-hour continuous duty cycles in high-load grooving operations, restricting adoption in three-shift mass-production environments without pneumatic-electric hybrid architectures.
Strategic Opportunities
- Underpenetrated North American hobbyist segment:Trim router uptake among small-scale woodworkers executing laminate edge banding remains below European penetration rates, presenting channel expansion potential through direct-to-consumer platforms.
- ERP interoperability mandates:Factory automation deepening in German woodworking corridors is creating demand for routers with native OPC-UA connectivity and real-time production data feeds to enterprise resource planning systems.
- Hybrid pneumatic-electric convergence:High-duty-cycle industrial environments are piloting combined spindle architectures that leverage pneumatic cooling for continuous operation while retaining electric precision control.
Industry Challenges
- CNC programming skill scarcity:Furniture manufacturers in export-oriented Guangdong clusters report 18-month average training periods for operators capable of G-code generation and toolpath optimization for complex joinery.
- CE marking timeline compression:Emergency-stop integration and noise emission validation for European distribution channels extends product development cycles by 4-6 months for OEMs without established notified body relationships.
- Legacy equipment integration friction:Computer-numerically-controlled routing systems require mechanical and electrical interface adaptation with existing dust collection, material handling, and fixturing infrastructure in retrofitted factories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Router Market |
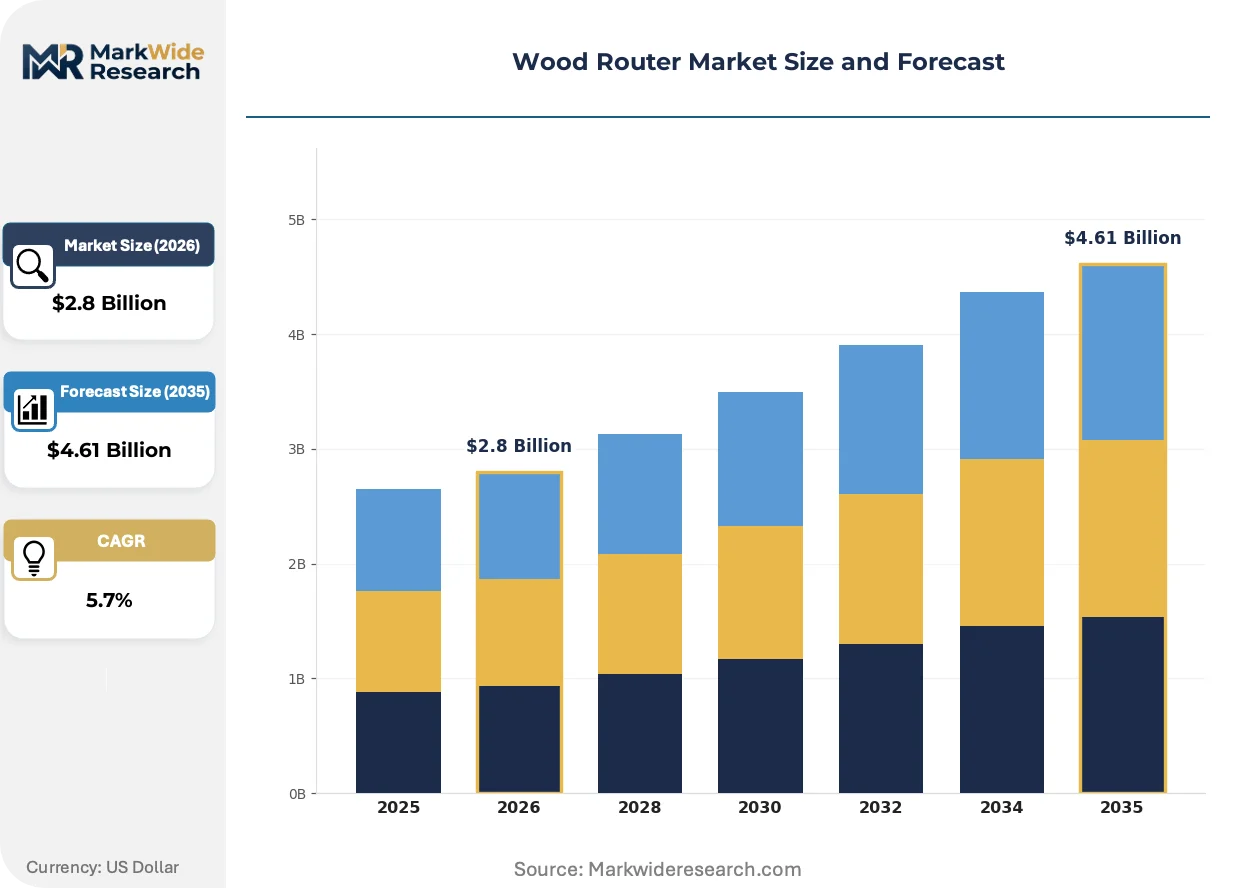
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Base Router, Plunge Router, Trim Router, CNC Router Technology: Electric, Pneumatic, Hybrid, Manual End User: Woodworking Shops, Furniture Manufacturers, Hobbyists, Construction Firms Application: Crafting, Joinery, Edge Treatment, Decorative Work |
| Companies Covered | Festool Group, Biesse Group, Robert Bosch GmbH, Thermwood Corporation, HOMAG Group, Makita Corporation, SCM Group, AXYZ Automation Group, Stanley Black & Decker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Router Market Strategic Shifts
Wood router technology is bifurcating between precision automation for industrial furniture production and connected capability for professional trades, with software-defined functionality displacing hardware-differentiated competition.
Industrial edge computing is integrating directly into CNC router control architectures, enabling real-time adaptive feed rates and tool wear compensation without latency to centralized plant servers. Mid-scale furniture manufacturers in German industrial corridors are piloting these systems to reduce scrap rates in variable-density engineered panel substrates. The technology is integrating predictive maintenance algorithms that compress unplanned downtime intervals by correlating spindle vibration signatures with bearing degradation curves.
France's CNIL-influenced data protocols for connected industrial equipment are mandating encrypted local storage and restricted cloud transmission for CNC production data, creating compliance overhead for smart routing equipment vendors. Woodworking machinery OEMs serving European distribution channels must now embed hardware security modules and audit logging capabilities that were previously optional. French and German furniture manufacturing clusters are responding by demanding on-premise data residency guarantees in procurement specifications, favoring suppliers with European-hosted service infrastructure.
After-sales service unbundling is fragmenting traditional OEM revenue models as large furniture manufacturers insource preventive maintenance and demand spare-part availability commitments rather than bundled service contracts. North American industrial distributors are responding with component-level stocking programs and certified technician training for in-house maintenance teams. This pattern is most visible in US commercial woodworking environments where multi-site furniture producers standardize on single brands to simplify internal technical competency development.
Wood Router Market Segmentation
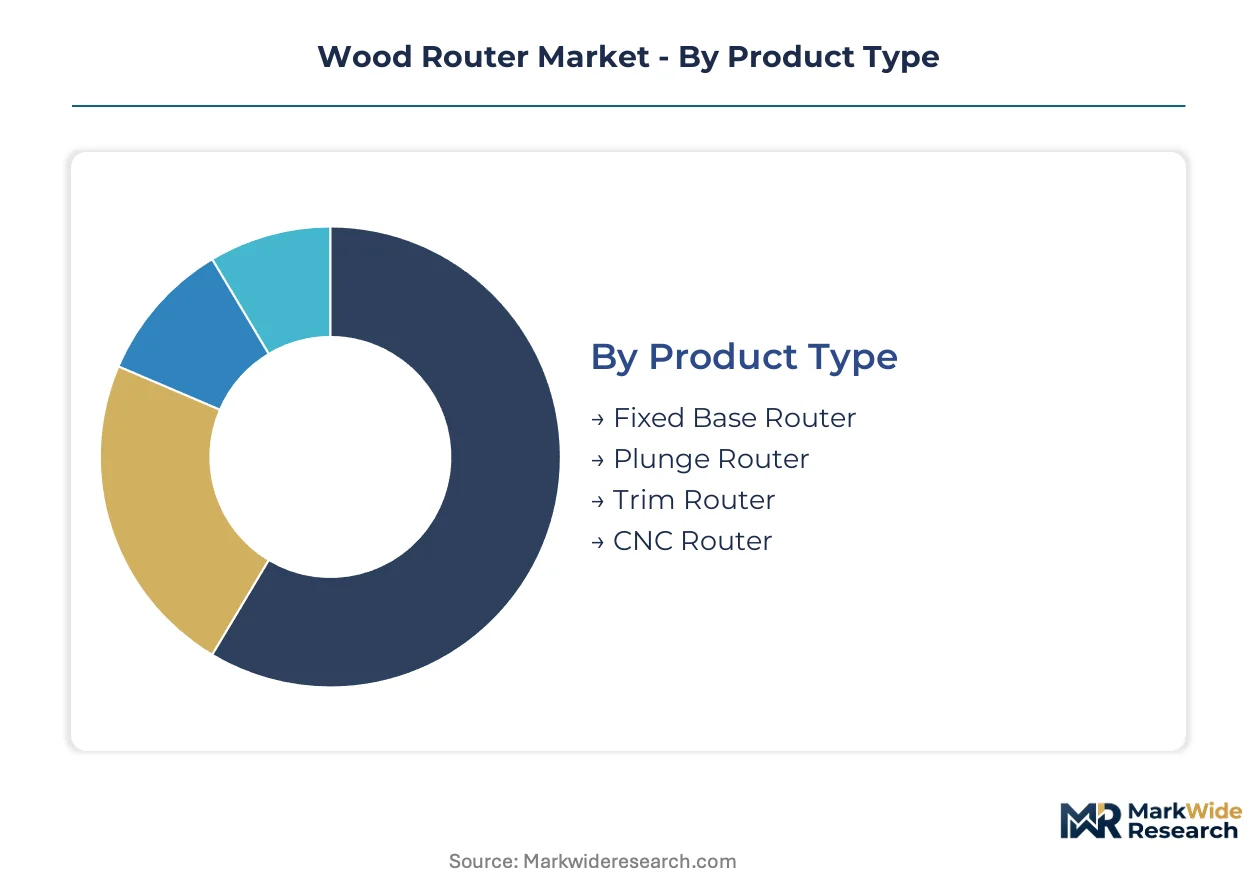
Wood router segmentation reveals how tool architecture aligns with operational intensity. Standalone portable units serve mobile trades, while embedded CNC systems anchor factory automation. Procurement patterns diverge sharply between these integration depths.
Product Type:
Integration depth separates handheld portability from machine-tool embedment, with fixed installations commanding premium pricing against mobile job-site alternatives.
- Fixed Base Router:Motor housing locks at preset cutting depth for consistent edge profiling and dado cutting across repetitive operations. German woodworking shops favor these for cabinet face-frame production where depth uniformity outweighs plunge capability.
- Plunge Router:Spring-loaded motor carriage enables mid-cut depth adjustment for mortise cutting and inlay work. European furniture clusters retain stronghold status for mortise-and-tenon joinery, though thermal management limits continuous duty cycles.
- Trim Router:Compact one-handed units dominate laminate edge banding and small-scale decorative profiling. North American hobbyist uptake runs below European penetration, leaving channel expansion headroom through direct-to-consumer platforms.
- CNC Router:Computer-numerically-controlled gantries execute complex joinery and carved decorative work via G-code toolpaths. Guangdong export furniture factories compress batch cycles through automated dimensional control, though 18-month operator training periods constrain deployment velocity.
Fixed base routers lead volumes today; CNC routers are gaining share fastest.
Technology:
Power delivery architecture determines thermal endurance and precision control trade-offs, with pure electric systems facing duty-cycle ceilings that hybrid architectures address.
- Electric:AC induction and brushless DC motors spin collet-mounted bits at 8,000-30,000 RPM via variable speed control. Installed base volumes concentrate here, though neodymium magnet and copper winding cost volatility squeeze OEM margins.
- Pneumatic:Compressed air drives turbine spindles in explosion-sensitive finishing environments and high-humidity tropical workshops. Southeast Asian furniture corridors deploy these where electrical code compliance lags.
- Hybrid:Combined pneumatic-electric architectures leverage air cooling for continuous three-shift operation while retaining electric precision. German industrial corridors pilot these for high-load grooving where pure electric endurance caps at approximately eight hours.
- Manual:Human-powered spindle rotation persists in heritage craft instruction and ultra-low-volume custom work. Artisanal furniture makers in Italian manufacturing clusters preserve these for demonstrative craftsmanship differentiation.
Electric technology anchors installed capacity; hybrid systems show steepest expansion trajectory.
End User:
Operational scale dictates automation depth, from single-tool job-site mobility to integrated production lines with ERP connectivity requirements.
- Woodworking Shops:Small-batch professional operations combine multiple portable router types across diverse project portfolios. OSHA lockout-tagout compliance drives capital refresh toward interlocked guard configurations.
- Furniture Manufacturers:High-volume producers standardize on CNC gantries with native OPC-UA connectivity for real-time production data feeds. German corridors demand on-premise data residency guarantees under CNIL-influenced protocols.
- Hobbyists:Trim router adoption concentrates in North American DIY segments executing laminate countertops and decorative edge treatments. Direct-to-consumer platform penetration trails European hobbyist equipment density.
- Construction Firms:Job-site rough carpentry and finish trim installation favor fixed-base and plunge portability over precision automation. Dust collection integration lags behind stationary shop environments.
Furniture manufacturers command revenue concentration; hobbyists represent the most underpenetrated addressable base.
Application:
Material removal objectives range from structural joinery preparation to aesthetic surface treatment, with tolerance requirements varying by order of magnitude.
- Crafting:Artistic object production and small-batch custom work prioritizes manual control and bit visibility over production velocity. Artisanal clusters in Italian furniture manufacturing preserve hand-guided techniques for premium positioning.
- Joinery:Mortise-and-tenon, dovetail, and biscuit slot preparation demands plunge depth precision and fence alignment repeatability. Guangdong export factories automate these operations through CNC deployment to meet tightening dimensional tolerances.
- Edge Treatment:Laminate trimming, solid wood profiling, and veneer flush-cutting dominate portable router utilization. North American residential construction drives volume here through countertop and cabinet installation activity.
- Decorative Work:Carved relief, inlay recesses, and complex profiling require high-speed spindle integration at 24,000+ RPM. Italian furniture clusters adopt these for batch production of components previously requiring manual craftsmanship.
Joinery applications anchor current demand; decorative work shows the fastest climb in system complexity requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong Province anchors wood router demand through export-oriented furniture factories upgrading from manual to computer-numerically-controlled routing systems. German and US furniture manufacturers are expanding CNC router adoption as machinery safety directives tighten. Industrial automation corridors across multiple continents are compressing batch cycles through automated dimensional control.
United States
Commercial woodworking environments face intensified OSHA machine guarding inspections, driving capital expenditure on routers with integrated emergency-stop systems. OSHA lockout-tagout standards shape product design for routers sold into US commercial environments. North American hobbyist segments show underpenetrated trim router uptake, leaving channel expansion headroom through direct-to-consumer platforms.
Germany
German furniture clusters generate replacement demand for compliant routing systems under EU Machinery Directive 2006/42/EC safety and electromagnetic compatibility requirements. KBA-aligned occupational safety frameworks add compliance layers for smart routing equipment. Industrial corridors in Baden-Württemberg and North Rhine-Westphalia pilot hybrid pneumatic-electric spindle architectures for continuous three-shift operation.
China
Export-oriented furniture factories in Guangdong Province accelerate CNC router deployment as export orders demand tighter dimensional tolerances. MIIT industrial automation policies support machinery upgrade subsidies in coastal manufacturing zones. The Pearl River Delta manufacturing belt compresses manual-to-automated production line upgrade timelines to meet compressed batch cycles.
Italy
Italian furniture manufacturing clusters adopt 24,000+ RPM spindles for complex decorative profiling, enabling batch production of carved components. CE marking obligations enforce emergency-stop integration and noise emission limits across European distribution channels. Emilia-Romagna and Lombardy furniture districts specialize in high-speed spindle integration for batch production of previously hand-crafted components.
France
CNIL-influenced data protocols mandate encrypted local storage and restricted cloud transmission for CNC production data from connected industrial equipment. GDPR-aligned data residency requirements favor suppliers with European-hosted service infrastructure. Île-de-France manufacturing procurement specifications increasingly demand on-premise data residency guarantees for smart routing equipment.
Wood Router Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue software-defined functionality and service unbundling. The vendor base spans diversified power-tool conglomerates, captive machinery specialists, and automation-focused fabricators. Strategic archetypes include ecosystem-anchored brands leveraging power-tool portfolios, software-captive suppliers controlling machine control ecosystems, and spindle-specialist integrators. Competitive moves concentrate on strategic partnerships for ERP interoperability and geographic expansion into underpenetrated hobbyist channels.
Among German-based diversified producers, Robert Bosch GmbH occupies a position representing ecosystem-anchored competition through power-tool brand loyalty. HOMAG Group exemplifies the software-captive archetype with control over machine control software and servo systems. SCM Group sits within the spindle-specialist tier, anchoring high-speed integration expertise for Italian furniture manufacturing clusters.
| Leading Market Players |
|---|
| Festool Group |
| Biesse Group |
| Robert Bosch GmbH |
| Thermwood Corporation |
| HOMAG Group |
| Makita Corporation |
| SCM Group |
| AXYZ Automation Group |
| Stanley Black & Decker |
| Others |
Value Chain & Pricing Dynamics
CNC-mid-tier divergence separates precision-automation premiums from portable-tool commodity pricing, with German furniture clusters paying capacity premiums for OPC-UA native systems while North American hobbyists drive volume through direct-to-consumer trim router channels. This bifurcation concentrates margin capture among software-captive suppliers while compressing distributor markups in mass-market portable segments.
Pricing Analysis
Input-cost pass-through from neodymium magnet and copper winding volatility squeezes OEM margins unevenly across electric spindle tiers. Three-tier pricing structure across premium, standard, and economy levels differentiates by control software sophistication and CE marking compliance depth. Pricing pressure stems from rare-earth supply corridor instability, with Guangdong export factories exhibiting highest price sensitivity and German industrial corridors least.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale furniture manufacturer demand for CNC gantries, while industrial distributors stock portable units for woodworking shop spot purchases. Component sourcing concentrates in China, Germany, and Italy for control systems, high-speed spindles, and precision mechanics respectively. Supply chains draw from neodymium permanent magnets, copper windings, and servo drive electronics. Single-source vulnerability in Chinese rare-earth processing creates exposure. Distribution runs through certified industrial machinery dealers with service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wood router procurement arbitrage favors hybrid pneumatic-electric sourcing from German industrial corridors over pure-electric alternatives from cost-optimized Asian supply chains, exploiting the eight-hour thermal endurance differential in three-shift environments.
For Market Incumbents: Anchor software ecosystem control against ERP interoperability fragmentation threatening captive machine control revenues. Defend by deepening servo system backward integration and accelerating CE marking pre-certification through notified body partnerships. Prioritize OPC-UA native development to capture German data residency procurement specifications. For New Entrants and Emerging Players: The premium-economy price-point gap in North American hobbyist trim routers opens white-space entry below Festool and Bosch positioning. Target direct-to-consumer platform penetration with compact laminate-edge units. Exploit underpenetrated DIY segments through social-integrated content marketing and community-based toolpath libraries. For Investors and Strategic Acquirers: Consolidation pressure builds where software-captive control architectures face interoperability mandates from factory automation deepening. Five-to-ten year viability favors spindle-specialist integrators with Italian furniture cluster relationships over diversified power-tool conglomerates exposed to portable segment commoditization. Monitor CE marking timeline compression as inflection signal for regulatory-capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| OPC-UA Native Development | Captures German ERP interoperability procurement specifications from furniture manufacturers. |
| Hybrid Spindle Pilot Programs | Addresses thermal endurance limits in Guangdong three-shift export production environments. |
| CE Marking Pre-Certification | Compresses product development cycles by 4-6 months through notified body relationships. |
| Direct-to-Consumer Platform Launch | Penetrates underexploited North American hobbyist segments below European equipment density. |
| After-Sales Service Unbundling | Aligns with large furniture manufacturer insourcing of preventive maintenance and spare-part stocking. |
Study Parameters
Direct dialogue with CNC router operators, furniture production managers, industrial machinery distributors, and aftermarket service technicians grounds qualitative assessment in operational reality. Secondary validation draws from MIIT industrial automation policy filings, EU Machinery Directive implementation guidance, OSHA enforcement data, and customs trade records for woodworking machinery. Bottom-up equipment deployment tracking and top-down furniture production capacity modeling provide cross-referenced triangulation.
Segment-level projections across the analysis window integrate product type, technology architecture, end-user operational scale, and application complexity dimensions. CAGRs derive from correlation between export order tolerance requirements and automation upgrade timelines in Guangdong clusters, with spindle speed adoption curves and control software penetration rates as additional inputs.
Caveats apply where rare-earth export restrictions or machinery safety directive amendments could materially shift the outlook. Forecasts reflect assumptions about training period compression for CNC programming skills and ERP interoperability standardization velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Shredder Blades Market
Tools
Leather Embossing Machine Market
Tools
Bearing Installation Tool Kit Market
Tools
Global Standard Parts for Tool Making Market
Tools
United States Machine Tools Market
Tools
Portable Grinders Market
Tools
Bi-Metal Band Saw Blade Market
Tools
Multi-Tasking Machine Tools Market
Tools
DIY Ball Mill Market
Tools
Saw Blades Market
Tools
Step Ladder Market
Tools
Portable Tools Market
Tools
Cutting Pipe and Perforating Pipe Drilling Tools Market
Tools
China Power Tools Market
Tools
Power Nibbler Market
Tools
Key Cutting Machine Market