
 DIY Ball Mill Market | 2026-2036
DIY Ball Mill Market Size, Share, and Industry Trends Forecast 2026-2036
DIY Ball Mill Market Outlook
Modular motor-drive architectures with variable frequency control is reconfiguring how DIY ball mill kits achieve torque precision and energy efficiency at small scale. Union Process leverages its grinding media expertise to anchor premium positioning in hobbyist-adjacent segments. Fritsch GmbH sustains technology leadership through precision-engineered milling bowl systems. JSB Industrial Solutions competes on configurable frame designs that accommodate multiple drum capacities.
A DIY ball mill is a self-assembly or semi-assembled cylindrical grinding device, typically constructed from a motorized roller frame, interchangeable milling jars of 1-20 liter capacity, and grinding media such as alumina or stainless steel balls, designed to reduce particle size through cascading impact and attrition for materials including pigments, chemicals, and minerals. Hobbyist Kits dominate unit volume due to entry-level pricing and online community documentation, while Industrial Kits capture disproportionate margin pools through reinforced frames and continuous-duty motors. Educational Kits represent the fastest-growing structural segment as university makerspaces and secondary STEM programs expand hands-on material science curricula.
US OSHA machinery guarding standards and FCC electromagnetic emission rules shape product safety and electrical certification requirements for DIY ball mill kits sold through domestic channels. China's SAMR enforces GB mechanical safety standards that constrain motor housing designs and emergency stop configurations for kits manufactured or imported into the mainland. REACH compliance across Europe restricts certain surface coatings and lubricants used in roller assemblies, compelling suppliers to reformulate component specifications. Stakeholders must monitor evolving certification thresholds across these three jurisdictions to avoid market access friction as hobbyist-to-industrial use-case boundaries continue blurring.
Market Dynamics
Modular motor-drive architectures with variable frequency control are compressing the performance gap between hobbyist and semi-professional ball mill systems, forcing suppliers to differentiate through certification grade rather than raw torque specifications.
Growth Catalysts
- GB Standard Harmonization:China's SAMR enforcement of unified mechanical safety and electromagnetic compatibility standards is consolidating supplier bases and accelerating certified kit penetration into mainland maker spaces.
- Ceramics Cluster Demand:Germany's precision engineering hubs in Bavaria and Baden-Württemberg are sourcing modular systems for small-batch metallurgy and ceramic powder processing, anchoring premium kit demand.
- Variable Frequency Drives:Adoption of VFD-enabled roller frames allows precise RPM control for pyrotechnic mixing and pigment dispersion, expanding addressable use cases beyond basic grinding.
Market Restraints
- Alumina Grinding Media Volatility:Ceramic ball input costs fluctuate with bauxite processing energy tariffs, compressing margins for kit suppliers locked into fixed retail pricing.
- Motor Supply Concentration:Compact induction motor production clusters in Zhejiang and Guangdong provinces create geographic single-point vulnerability for frame manufacturers outside China.
- REACH Formulation Constraints:ECHA restrictions on certain roller bearing lubricants and surface coatings force European kit assemblers to reformulate specifications or source compliant substitutes at premium cost.
Strategic Opportunities
- University Makerspace Expansion:Secondary and tertiary STEM programs in the United States are building material science workshops, creating institutional procurement channels for educational-tier kits with documented curricula.
- OSHA-Compliant Guarding Modules:US suppliers can differentiate through pre-certified machinery guarding systems that reduce end-user liability exposure in hobbyist-to-light-industrial transitions.
- IoT-Enabled Torque Monitoring:Integration of load cell sensors with Bluetooth telemetry allows remote process validation, appealing to homebrew material scientists documenting reproducible protocols.
Industry Challenges
- Electromechanical Integration Skill Gaps:Kit assembly requires competency in motor wiring, VFD parameterization, and drum balancing—capabilities scarce among entry-level hobbyists purchasing online.
- FCC Certification Timelines:Variable frequency drives with digital control interfaces face extended electromagnetic emission testing cycles, delaying product launches for US-market kits.
- Cross-Jurisdiction Labeling Complexity:Simultaneous compliance with OSHA guarding, CE machinery directives, and GB standards demands multiple certification tracks, fragmenting inventory and documentation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DIY Ball Mill Market |
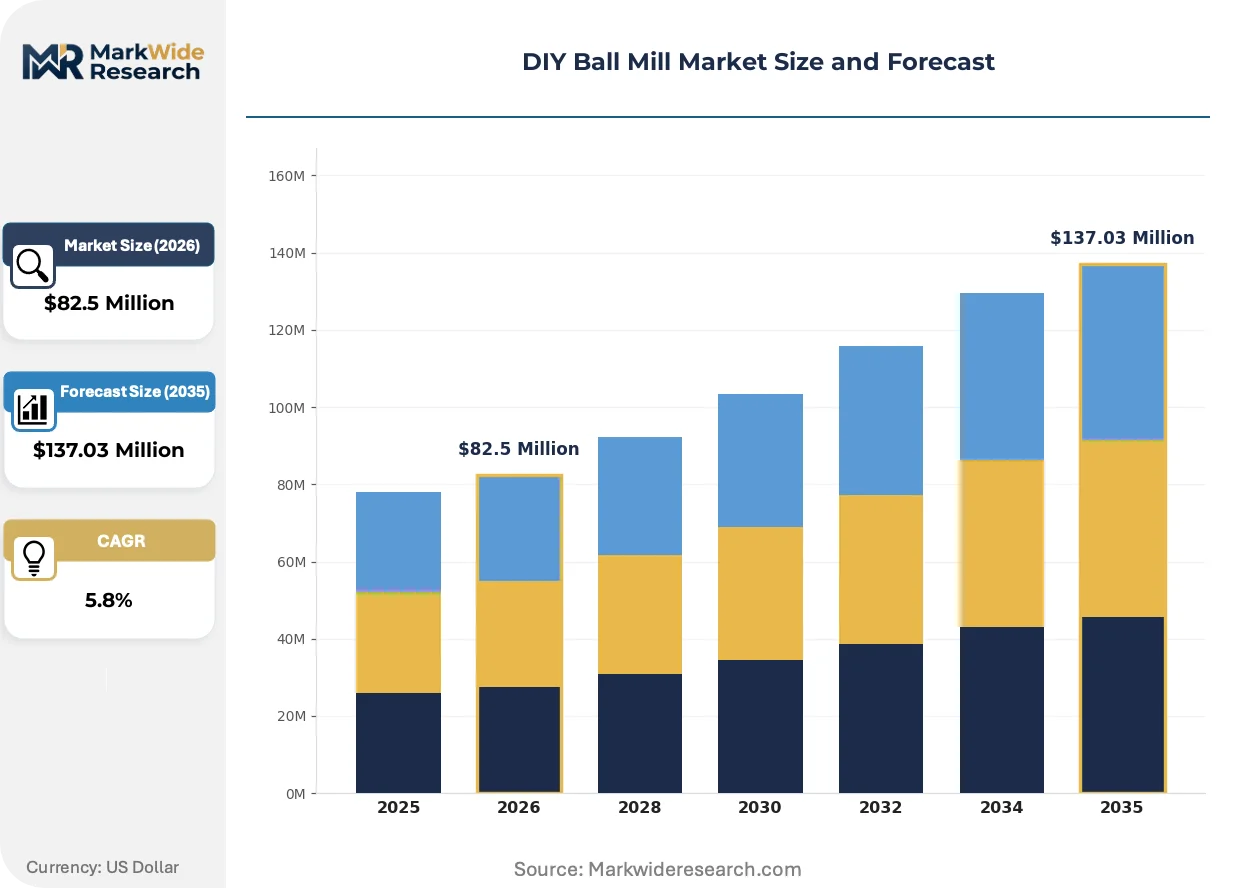
| Market Size in 2026 | $82.5 Million |
| Market Size in 2035 | $137.03 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hobbyist Kits, Industrial Kits, Educational Kits, Custom Kits Material: Stainless Steel, Aluminum, Plastic, Carbon Steel Capacity: 1 Liter, 5 Liters, 10 Liters, 20 Liters End User: Individual Hobbyists, Educational Institutions, Small Businesses, Research Labs |
| Companies Covered | Union Process, Fritsch GmbH, JSB Industrial Solutions, ERWEKA GmbH, Economy Ball Mill, Orbis Machinery, Retsch GmbH, Verder Scientific, Benchmark Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DIY Ball Mill Market Strategic Shifts
Digital control interfaces and connected monitoring systems are transforming how DIY ball mill operators validate process consistency, shifting value capture from hardware margins toward firmware-enabled performance guarantees.
Brushless DC motor systems paired with precision Hall-effect encoders are collapsing the cost-performance boundary that historically separated consumer-grade from laboratory-grade milling equipment. University workshops in Germany and maker collectives in the United States are adopting these systems for sub-micron particle size experiments previously requiring institutional budgets. The technology is collapsing the addressable market for entry-level professional mills by delivering comparable torque stability at one-third the capital outlay.
REACH restrictions on perfluorinated lubricants and certain anti-corrosion surface treatments are compelling European kit suppliers to reformulate roller bearing specifications and drum coating chemistries. Industrial consequence includes extended supplier qualification timelines and accelerated obsolescence of legacy inventory held in regional distribution. German precision engineering clusters are responding fastest, with several frame manufacturers already shipping REACH-compliant variants ahead of 2025 enforcement windows.
Documentation-driven purchasing now dominates hobbyist-adjacent segments, with buyers prioritizing kits bundled with validated protocols for specific materials—pyrotechnic black powder, aluminum pigment flaking, or ceramic glaze preparation. Online community repositories and video tutorial ecosystems are displacing traditional instruction manuals as the primary post-sale support channel. This shift is most visible in United States pyrotechnics communities, where peer-verified safety procedures carry more weight than manufacturer claims in purchase decisions.
DIY Ball Mill Market Segmentation
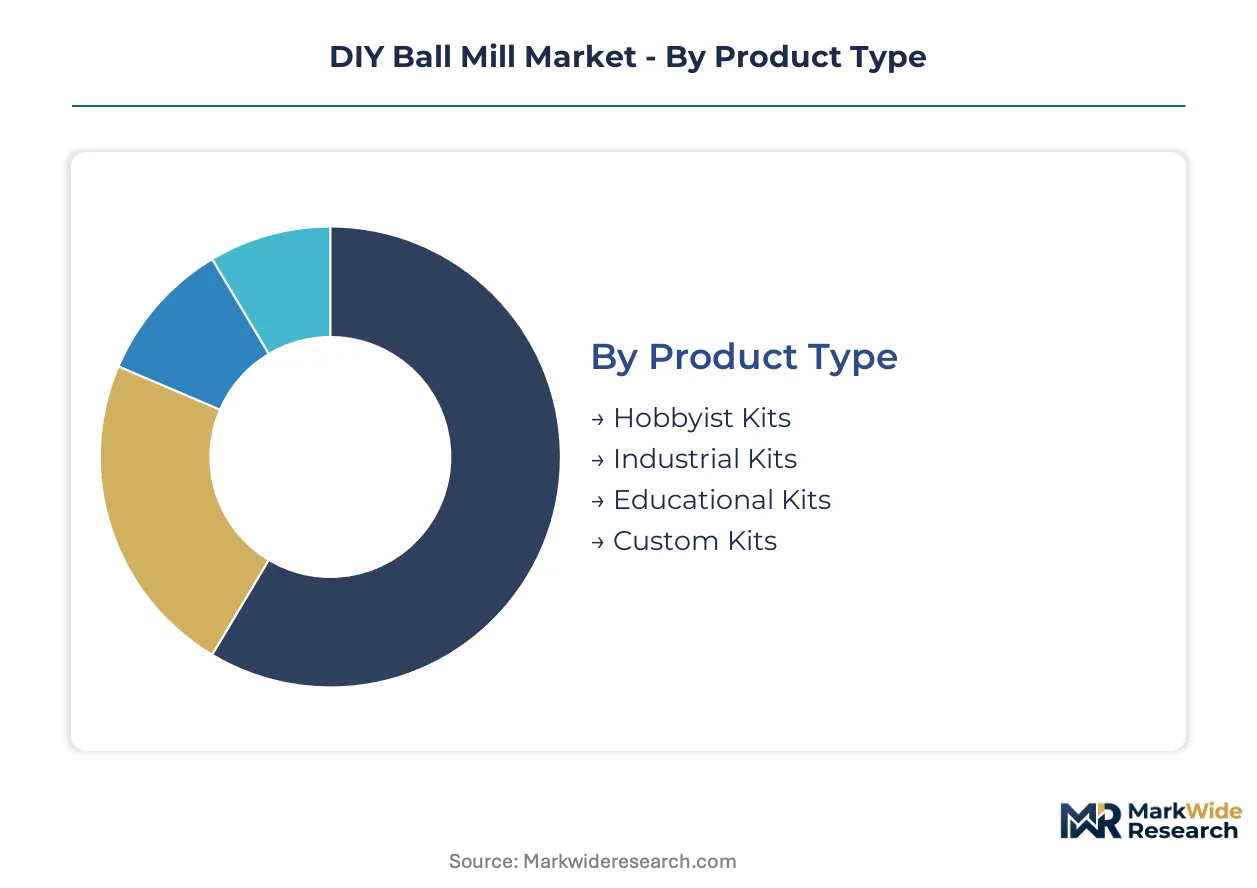
DIY ball mill suppliers must navigate four intersecting segmentation dimensions that determine kit configuration, certification requirements, and channel strategy. Product type and capacity specifications drive hardware margins, while material selection and end-user classification dictate regulatory compliance pathways and aftermarket service intensity.
Product Type:
Mature hobbyist configurations dominate unit flows, while emerging educational formats reshape institutional procurement patterns with documented curricula requirements.
- Hobbyist Kits:Entry-level motorized roller frames with 1-5 liter drum capacity and basic on/off controls. Pyrotechnics communities in the United States source these through online marketplaces, prioritizing peer-verified assembly documentation over manufacturer warranties.
- Industrial Kits:Reinforced steel frames with continuous-duty motors and emergency stop systems certified to OSHA machinery guarding standards. Small-batch ceramics processors in Germany's Bavarian precision engineering clusters anchor premium demand for these configurations.
- Educational Kits:Modular systems bundled with STEM-aligned protocols for secondary and tertiary material science programs.
- Custom Kits:Bespoke frame geometries and specialized drum linings for non-standard grinding media or corrosive chemistries.
Hobbyist Kits handle the majority of throughput; Educational Kits is the fastest mover on share.
Material:
Cost tier differentiation separates commodity-grade housings from precision-engineered contact surfaces, with REACH compliance constraints elevating stainless steel specifications in European channels.
- Stainless Steel:Corrosion-resistant 304 and 316 grades for drum construction and roller assemblies. REACH restrictions on surface coatings in Europe compel German kit assemblers to specify passivated finishes rather than coated alternatives.
- Aluminum:Extruded frame rails and cast motor housings balancing weight reduction with structural rigidity.
- Plastic:ABS and polycarbonate safety guards and control enclosures meeting electrical insulation requirements.
- Carbon Steel:Powder-coated frame components for cost-sensitive hobbyist configurations where corrosion exposure remains limited.
Stainless Steel commands the highest specification premiums; Aluminum delivers the steepest volume scaling.
Capacity:
Volume-based procurement patterns split between individual experimenters optimizing benchtop footprint and institutional buyers maximizing batch throughput per cycle.
- 1 Liter:Benchtop units for pigment dispersion and small-scale pyrotechnic mixing. Individual hobbyists in the United States favor these for residential workspace constraints.
- 5 Liters:Intermediate drums accommodating metallurgical sample preparation and ceramic glaze development.
- 10 Liters:Standard institutional capacity for university makerspace shared equipment pools.
- 20 Liters:Maximum hobbyist-adjacent configuration requiring reinforced frames and upgraded motor torque ratings.
5 Liter drums anchor the commercial sweet spot; 10 Liter configurations are climbing the fastest as makerspace infrastructure expands.
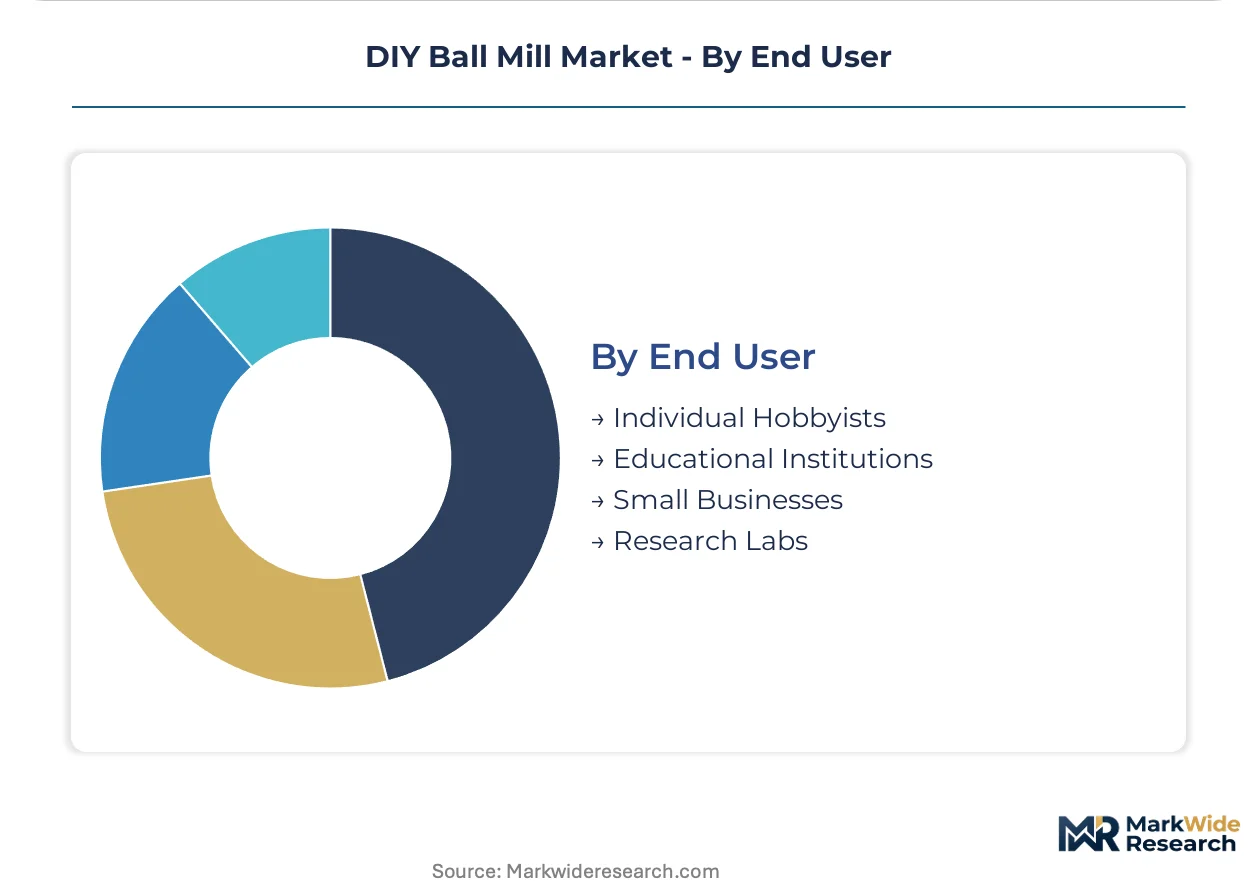
End User:
Customer-type segmentation determines certification depth, with institutional buyers demanding documented safety compliance that individual purchasers often bypass.
- Individual Hobbyists:Price-sensitive buyers prioritizing community-sourced assembly guidance over manufacturer support channels. FCC electromagnetic emission compliance varies widely across direct-import purchases.
- Educational Institutions:Secondary and tertiary programs requiring OSHA-compliant guarding and curriculum-aligned documentation. United States STEM expansion programs are accelerating procurement through formal institutional channels.
- Small Businesses:Artisan ceramics studios and custom pigment blenders seeking semi-professional throughput without industrial capital outlay.
- Research Labs:University and corporate R&D facilities demanding sub-micron particle size reproducibility with protocol documentation for publication.
Individual Hobbyists generate the highest unit velocity; Educational Institutions is gaining share fastest through formal procurement centralization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Individual hobbyists and institutional makerspace buyers concentrate demand across three distinct regulatory environments. The United States, Germany, and China anchor volume, with certification requirements fragmenting supplier strategies by jurisdiction.
United States
Pyrotechnics communities and university makerspaces drive kit adoption, with STEM expansion programs accelerating institutional procurement. OSHA machinery guarding standards and FCC electromagnetic emission rules constrain direct-import configurations. Texas and California host the densest maker collectives, where peer-verified assembly documentation outweighs manufacturer warranties in purchase decisions.
Germany
Precision engineering clusters in Bavaria and Baden-Württemberg source modular systems for small-batch ceramics and metallurgy experiments. ECHA REACH restrictions on roller bearing lubricants compel reformulation of component specifications. Stuttgart and Munich anchor demand for educational-tier kits with documented safety compliance for university workshops.
China
Domestic maker spaces and export-oriented manufacturing shape dual demand tracks. SAMR enforcement of unified GB mechanical safety and electromagnetic compatibility standards consolidates supplier bases. Zhejiang and Guangdong provinces concentrate compact induction motor production, creating geographic supply vulnerability for frame manufacturers elsewhere.
United Kingdom
Secondary STEM programs and artisan ceramics studios generate modest but growing kit demand. CE machinery directives and evolving post-Brexit product safety frameworks complicate cross-border sourcing. London and Birmingham makerspaces prioritize modular configurations with curriculum-aligned documentation for educational procurement channels.
Japan
University R&D facilities and precision manufacturing hobbyists sustain niche demand for sub-micron particle size systems. METI industrial standards and JIS certification requirements elevate specification thresholds for imported kits. Osaka and Nagoya host concentrated maker collectives experimenting with homebrew material science protocols.
DIY Ball Mill Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented tiering. The vendor base distributes between grinding media specialists, precision engineering houses, and configurable frame fabricators. Three archetypes dominate: legacy laboratory equipment manufacturers extending into hobbyist-adjacent segments, industrial machinery suppliers downsizing professional systems, and kit assemblers sourcing modular components from distributed supplier networks. Competitive moves center on certification pre-qualification for multi-jurisdiction sales and curriculum bundling for educational procurement channels.
Within the precision-engineering tier, Fritsch GmbH and Retsch GmbH exemplify laboratory-grade heritage repositioned toward semi-professional use cases. Union Process anchors the grinding media specialist archetype, while JSB Industrial Solutions occupies a position among configurable frame suppliers. German GmbH-structured entities concentrate in premium-tier positioning, whereas US-based Inc. and LLC formations dominate mid-market kit distribution through online channels.
| Leading Market Players |
|---|
| Union Process |
| Fritsch GmbH |
| JSB Industrial Solutions |
| ERWEKA GmbH |
| Economy Ball Mill |
| Orbis Machinery |
| Retsch GmbH |
| Verder Scientific |
| Benchmark Scientific |
| Others |
Value Chain & Pricing Dynamics
Zhejiang and Guangdong motor production clusters concentrate upstream supply for DIY ball mill frame manufacturers, anchoring margin pools with distributors serving hobbyist-adjacent segments in the United States and Germany. Cost pass-through mechanisms from bauxite-processing energy tariffs to alumina grinding media pricing compress kit assembler margins, particularly for fixed-price retail configurations.
Pricing Analysis
Cost-plus contracts with alumina grinding media suppliers index to bauxite processing energy tariffs, creating input cost volatility that kit assemblers struggle to recover through fixed retail pricing. Three-tier pricing structure across premium OSHA-certified, standard CE-marked, and economy direct-import levels separates buyers by liability exposure and documentation requirements. Pricing pressure stems from REACH-compliant lubricant and coating substitutions elevating European kit costs against Asian imports. Individual hobbyists in US pyrotechnics communities exhibit highest price sensitivity, while German precision engineering clusters accept premium specifications for documented safety compliance.
Supply Chain Analysis
Supply-chain finance facilities extended by Zhejiang motor manufacturers to frame assemblers compress working capital cycles for tier-two kit suppliers. Production concentrates in China for compact induction motors, Germany for precision-engineered milling bowl systems, and the United States for configurable frame designs. Raw material dependencies span bauxite-derived alumina balls, 304/316 stainless steel drum stock, and ABS/polycarbonate safety enclosures. Single-source vulnerability in Guangdong motor controller assemblies threatens kit delivery timelines for North American distributors. Distribution runs through online marketplaces for hobbyist segments and institutional procurement channels for educational-tier kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward educational institutions as US STEM program centralization consolidates procurement volumes, fragmenting individual hobbyist price-setting leverage.
For Market Incumbents: Build certification-grade moats through pre-qualified OSHA guarding modules and FCC-compliant VFD configurations that delay new entrant launches by 8-12 month testing cycles. Deepen backward integration into alumina grinding media sourcing to buffer bauxite tariff volatility. Anchor channel control through curriculum-bundled educational kit partnerships with university makerspace procurement offices. For New Entrants and Emerging Players: Pursue white-space capture in REACH-compliant European kit variants ahead of 2025 enforcement windows, where incumbent reformulation lags create temporary supply gaps. Target US secondary STEM programs with modular 10-liter configurations and documented safety protocols as the most penetrable institutional segment. Deploy direct-community engagement through peer-verified video tutorial ecosystems rather than traditional distributor relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision engineering houses in Germany's Baden-Württemberg cluster holding laboratory-grade heritage but lacking hobbyist-channel capabilities. Long-term viability hinges on firmware-enabled torque monitoring differentiation collapsing the consumer-laboratory grade boundary. Watch for IoT-enabled kit adoption rates in US maker collectives as inflection signal for platform-based revenue model transition.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Component Reformulation | Reformulated roller bearing specifications secure European market access ahead of ECHA enforcement windows. |
| IoT-Enabled Torque Monitoring Integration | Bluetooth telemetry load cells appeal to homebrew material scientists documenting reproducible protocols. |
| University Makerspace Curriculum Bundling | STEM-aligned documentation packages capture institutional procurement centralization in US secondary programs. |
| OSHA-Compliant Guarding Module Pre-Certification | Pre-qualified machinery guarding reduces end-user liability exposure in hobbyist-to-light-industrial transitions. |
| Backward Integration into Grinding Media Sourcing | Captive alumina ball supply buffers margin compression from bauxite processing energy tariff volatility. |
Study Parameters
The analysis maps hobbyist kit configurations, industrial-grade systems, educational-tier bundles, and custom geometries, each validated through kit assemblers, motor suppliers, grinding media distributors, and university makerspace procurement officers. Primary interviews with frame manufacturers in Germany and Zhejiang motor production clusters combined with secondary validation from customs trade data, GB standard enforcement disclosures, and SEC filings from laboratory equipment manufacturers. Bottom-up kit shipment estimates triangulate against top-down addressable market sizing across the four product type segments.
Assumptions held fixed include SAMR GB standard enforcement timelines, REACH lubricant restriction scope, and FCC electromagnetic emission testing protocols, while alumina input cost trajectories and US STEM funding levels varied across scenario paths. Segmentation modeling spanned product type, material specification, drum capacity tier, and end-user classification across the projection horizon. CAGRs derived from fitted growth curves against historical kit adoption patterns in pyrotechnics and ceramics processing communities, with motor-drive technology substitution rates and educational procurement centralization velocity as key forecast inputs.
Sensitivities concentrate around bauxite tariff regime shifts, SAMR certification timeline acceleration, and FCC testing backlog durations. Forecasts reflect documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Sand Control Tools Market
Tools
Automatic Heat Press Machines Market
Tools
Power Press Machines Market
Tools
North America Power Tools Market
Tools
Industrial Floor Scrubber Market
Tools
Tool Hammer Market
Tools
Vise-Grip Pliers Market
Tools
Thickness Planers Market
Tools
Machining Centers Market
Tools
Yard Scraper Market
Tools
Cordless Fillet Weld Grinder Market
Tools
Nut Runner Market
Tools
US Power Tools Market
Tools
Saw Blades Market
Tools
Striking Tools Market
Tools
Extensometer Market