
 Portable Tools Market | 2026-2036
Portable Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Tools Market Outlook
Tool-as-a-service subscription models and software-enabled diagnostics are broadening what manufacturers deliver beyond the physical unit. Stanley Black & Decker leverages its service network to anchor recurring revenue streams. Robert Bosch GmbH sustains technology leadership through in-house brushless motor development. Techtronic Industries Co. Ltd. dominates the cordless segment with proprietary battery platforms that lock in user ecosystems.
Portable tools encompass handheld, transportable power and hand equipment engineered for cutting, drilling, fastening, grinding, and material removal, typically operating at voltages from 12V to 60V for battery units and incorporating brushless DC motors, lithium-ion cells, and composite housings to balance power density with ergonomic weight distribution. These devices serve construction crews, automotive technicians, and facility maintenance teams requiring mobility without tethered power access. Drills and impact drivers occupy the largest volume tier due to universal jobsite demand, while battery-powered saws represent the fastest-expanding category as lithium-ion energy density climbs and corded tool replacement accelerates. Grinders and wrenches command stronger margins in industrial maintenance applications where pneumatic legacy systems still dominate but face cordless displacement.
OSHA workplace safety mandates and EPA hazardous dust exposure limits shape product design requirements for ventilation, vibration damping, and particulate containment. CE marking under EU machinery directives and RoHS substance restrictions govern market access for tools sold across Europe. Battery transportation regulations from ICAO and IATA impose packaging and state-of-charge limits that complicate cross-border fulfillment. Stakeholders must monitor how evolving right-to-repair legislation and extended producer responsibility frameworks will reshape aftermarket parts availability and battery recycling obligations.
Market Dynamics
Battery platform ecosystem lock-in is reshaping competitive dynamics as proprietary lithium-ion architectures and cross-compatible tool systems create high switching costs for professional contractors and institutional buyers.
Growth Catalysts
- Infrastructure stimulus packages:Federal and state capital programs in the United States, Germany, and China are accelerating commercial construction starts and residential renovation permits, directly lifting equipment procurement volumes for electrical and mechanical trades.
- OSHA silica dust regulations:Tighter permissible exposure limits for respirable crystalline silica mandate integrated vacuum systems and tool-mounted dust collection, forcing tool replacement cycles and premium attachment sales.
- Brushless motor adoption:Permanent magnet synchronous motor designs eliminate commutator wear, extending mean time between failures by 40-50% and reducing heat generation in high-torque fastening applications.
Market Restraints
- Lithium carbonate price volatility:Battery cell input costs fluctuate with South American brine and Australian spodumene supply disruptions, compressing OEM margins on cordless platforms priced for market share defense.
- Semiconductor fab concentration:Motor controller ICs and battery management system chips depend on Taiwanese and South Korean foundry capacity, exposing tool manufacturers to allocation rationing during automotive sector demand surges.
- Pneumatic legacy infrastructure:Established industrial maintenance facilities retain sunk investments in compressed air distribution networks, slowing cordless displacement in high-volume assembly environments despite total cost of ownership advantages.
Strategic Opportunities
- India construction equipment rental:Organized rental penetration remains below 15% in Indian metropolitan construction markets, creating channel infrastructure gaps that battery-platform leasing models can capture.
- EU Green Deal circularity mandates:Extended producer responsibility frameworks and battery passport requirements favor OEMs with reverse logistics capabilities and modular repair architectures.
- 5G-enabled predictive maintenance:Embedded vibration sensors and cloud-connected diagnostics converge with fleet management software, enabling subscription revenue streams from uptime guarantees rather than unit sales.
Industry Challenges
- Power electronics engineering scarcity:Brushless motor control algorithms and thermal management design require specialized firmware talent concentrated in automotive and aerospace sectors, inflating R&D recruitment costs.
- Multi-certification timelines:Simultaneous UL, CE, and GB standard compliance for global product launches extends development cycles by 8-14 months, delaying revenue recognition on platform refreshes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Tools Market |
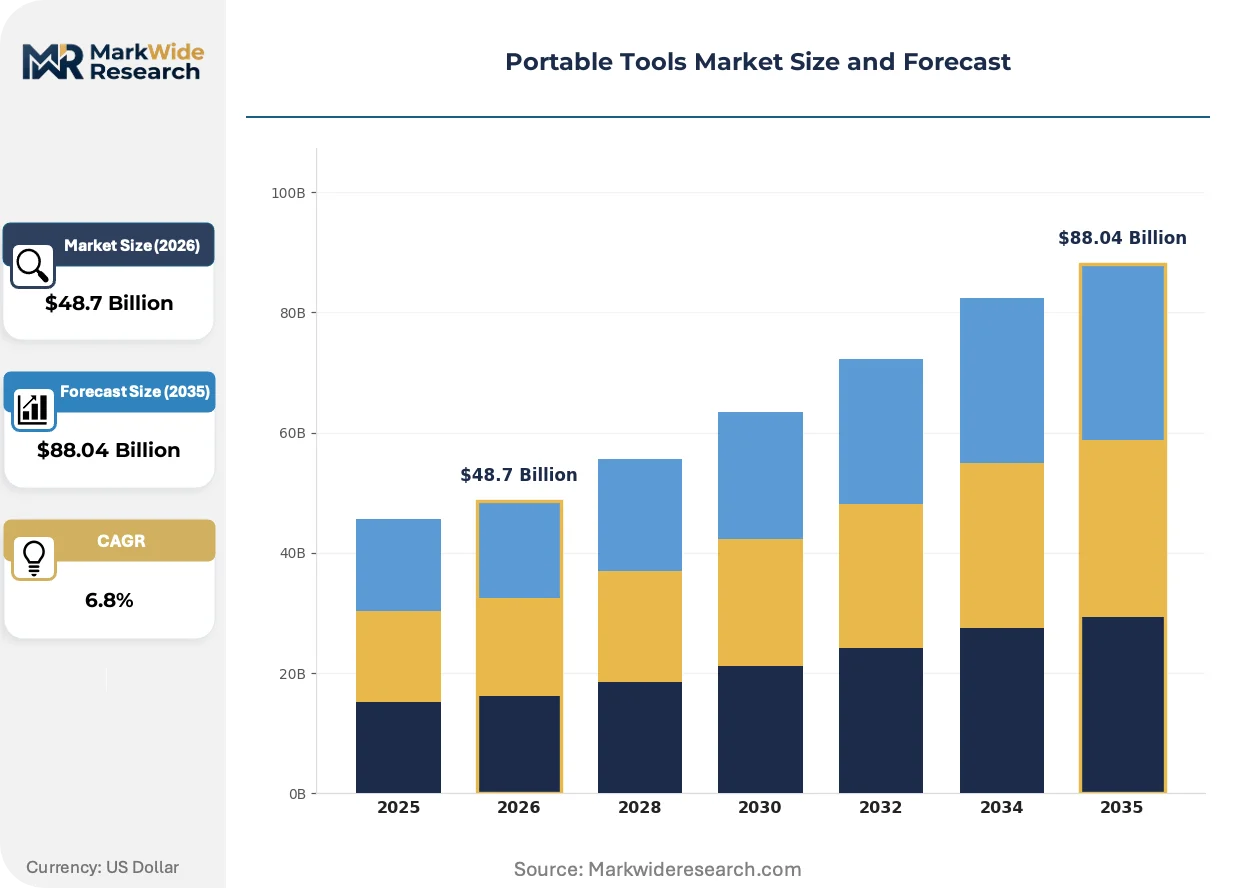
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drills, Saws, Grinders, Wrenches Application: Construction, Automotive Repair, Home Improvement, Landscaping Power Source: Battery-Powered, Corded, Pneumatic, Solar End User: Contractors, DIY Enthusiasts, Industrial Users, Maintenance Providers |
| Companies Covered | Stanley Black & Decker, Inc., Robert Bosch GmbH, Techtronic Industries Co. Ltd., Makita Corporation, Hilti Corporation, Atlas Copco AB, Apex Tool Group, Snap-on Incorporated, Ingersoll Rand Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Tools Market Strategic Shifts
Tool intelligence and connectivity layers are transforming hardware margins into recurring software and service revenue, while battery chemistry advances compress form factors without sacrificing torque output.
Silicon carbide MOSFETs in motor drives are expanding into professional-grade impact wrenches and rotary hammers previously restricted by thermal constraints. European automotive maintenance chains are retrofitting service bays with 60V fast-charging infrastructure to support these platforms. The technology is expanding into pneumatic tool displacement in heavy equipment repair facilities where downtime costs exceed equipment premiums.
REACH substance restrictions on PFAS and specific flame retardants are forcing housing material substitutions in tools sold across European Union member states. Compound suppliers must reformulate glass-filled nylon and thermoplastic elastomer grips to maintain impact resistance without restricted chemistries. German power tool distributors report 6-9 month qualification delays as OEMs resubmit for CE marking compliance.
Professional contractors in North American commercial construction are consolidating vendor relationships around single-battery-platform fleets to simplify inventory and training. General contractors specify approved tool lists for subcontractor compliance, concentrating procurement authority at the project-owner level. This concentration is most visible in Texas and Florida healthcare facility construction, where infection-control protocols mandate sealed battery systems with documented sterilization compatibility.
Portable Tools Market Segmentation
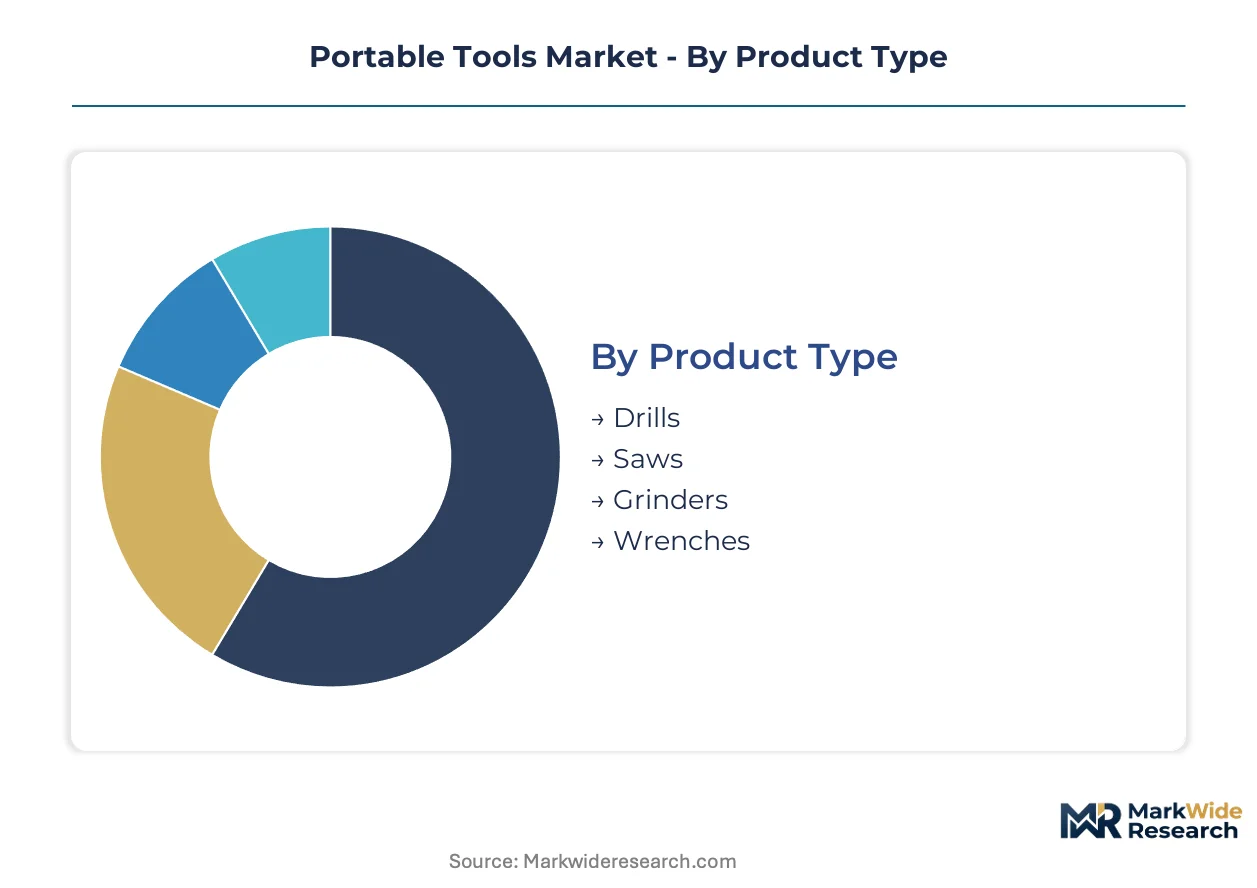
Portable tools segment along four critical axes that determine procurement patterns, margin structures, and technology roadmaps. Product type and power source classifications drive engineering investment priorities, while application and end-user dimensions shape channel strategy and service model design.
Product Type:
Tool category segmentation reflects torque requirements, duty cycles, and replacement frequency patterns across professional and consumer tiers.
- Drills:Rotary and hammer drill configurations dominate procurement volumes across residential and commercial construction. Demand concentrates in United States metropolitan renovation corridors where electrical and mechanical trades require compact 12V-20V platforms for overhead work.
- Saws:Circular, reciprocating, and miter variants are gaining share fastest as lithium-ion energy density enables corded displacement in framing and finish carpentry. German timber-frame construction crews and Chinese prefabricated housing factories are accelerating cordless platform adoption.
- Grinders:Angle and die grinder formats serve metal fabrication and weld preparation with high thermal loads requiring advanced brushless motor cooling.
- Wrenches:Impact and torque wrench categories command premium pricing in automotive assembly and heavy equipment maintenance where pneumatic legacy systems face cordless substitution pressure.
Mature deployment sits with drills. Newer deployment is concentrated in saws.
Application:
End-use context determines tool specification, durability requirements, and fleet management complexity.
- Construction:Commercial building, infrastructure, and residential development drive the largest equipment procurement volumes with demanding duty cycles. OSHA silica dust regulations in United States job sites mandate integrated dust collection systems on cutting and grinding tools.
- Automotive Repair:Service bay operations and collision centers require sealed battery systems compatible with parts washer and sterilization protocols. Fastest platform refresh cycles occur here as vehicle electrification changes fastener torque specifications.
- Home Improvement:Residential renovation and DIY activity supports mid-tier cordless platforms with moderate duty ratings and price-sensitive feature sets.
- Landscaping:Outdoor power equipment for grounds maintenance is expanding battery platform boundaries into previously gas-dominated categories like chainsaws and blowers.
Construction applications anchor established fleet deployments. Automotive repair represents the steepest expansion trajectory for connected diagnostics and subscription service models.
Power Source:
Energy delivery architecture defines tool mobility, runtime economics, and regulatory compliance boundaries.
- Battery-Powered:Lithium-ion platforms from 12V to 60V are displacing corded and pneumatic alternatives across professional tiers. Brushless motor integration and silicon carbide power electronics extend thermal margins in high-torque applications previously restricted to corded designs.
- Corded:AC mains tools retain cost advantages in stationary shop environments and developing markets with unreliable charging infrastructure. CE marking under EU machinery directives and GB standards in China govern safety certification requirements.
- Pneumatic:Compressed air systems persist in high-volume industrial assembly where sunk infrastructure investments slow cordless transition despite total cost of ownership disadvantages.
- Solar:Photovoltaic charging integration serves off-grid construction and remote maintenance applications with intermittent grid access.
Battery-powered architectures dominate new platform development. Pneumatic systems concentrate in legacy industrial maintenance environments.
End User:
Customer type segmentation determines pricing tolerance, service expectations, and ecosystem lock-in susceptibility.
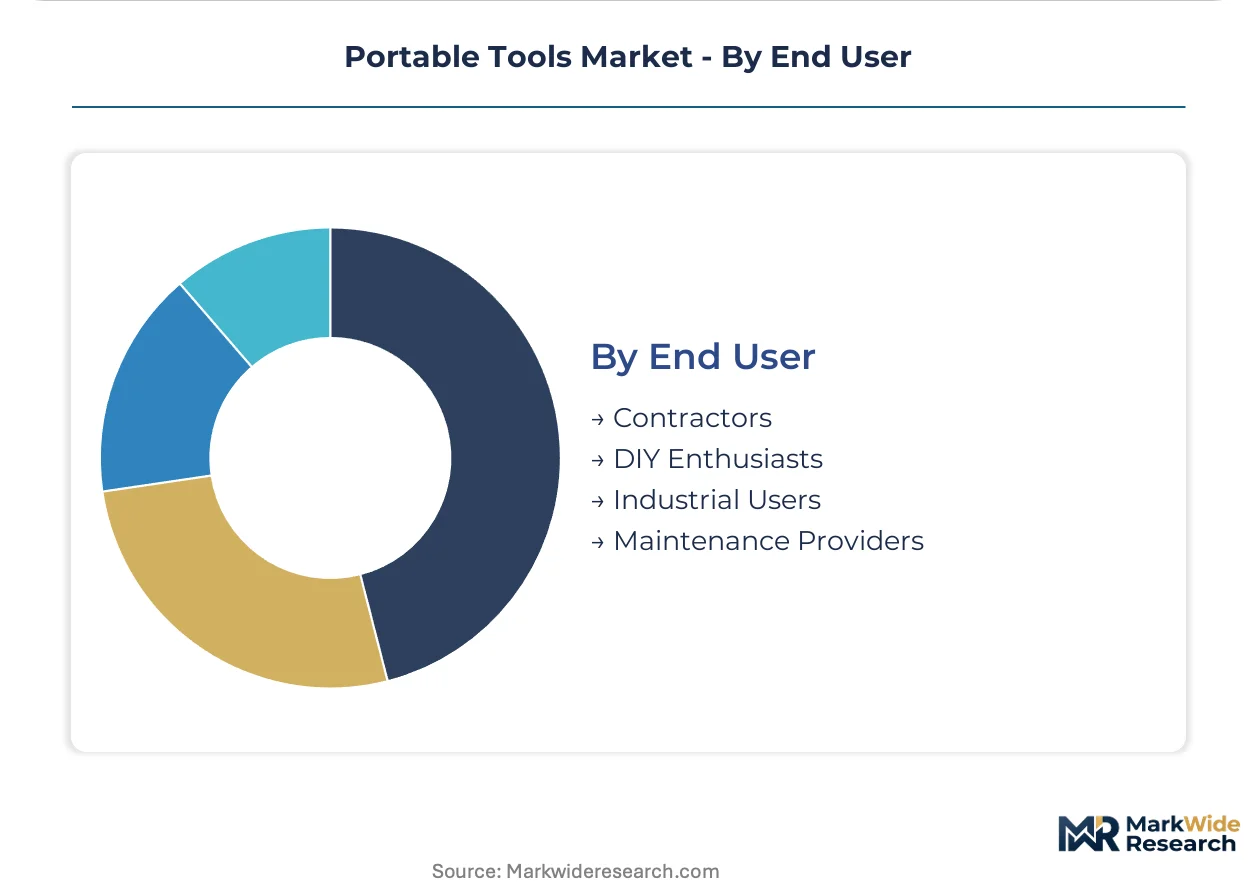
- Contractors:Professional tradespeople prioritize runtime, durability, and cross-platform battery compatibility. United States general contractors increasingly specify approved tool lists for subcontractor compliance, concentrating procurement authority at project-owner level.
- DIY Enthusiasts:Consumer-tier buyers respond to retail promotion cycles and brand recognition with lower utilization intensity and price-sensitive feature trade-offs.
- Industrial Users:Manufacturing and process industry maintenance departments require fleet management software integration and predictive maintenance capabilities. REACH substance restrictions and EU battery passport mandates shape procurement criteria for European facilities.
- Maintenance Providers:Facility management and third-party service contractors value tool tracking, utilization analytics, and outcome-based service contracts over unit ownership.
Industrial users lead connected fleet and subscription service adoption. DIY enthusiasts remain most sensitive to initial acquisition cost and promotional pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in China and Germany while consumption concentrates in the United States, Germany, and China. Infrastructure spending differentials and regulatory timelines create asynchronous replacement cycles across major economies.
United States
Commercial construction starts and residential renovation permits drive equipment procurement volumes for electrical and mechanical trades. OSHA silica dust regulations mandate integrated vacuum systems on cutting and grinding tools, accelerating replacement cycles. Texas and Florida healthcare facility construction concentrates demand for sealed battery systems with documented sterilization compatibility.
Germany
Timber-frame construction crews and automotive maintenance chains accelerate cordless platform adoption with 60V fast-charging infrastructure. REACH substance restrictions and EU machinery directives govern CE marking compliance for tools sold across member states. Baden-Württemberg industrial clusters anchor brushless motor development and power electronics engineering talent pools.
China
Prefabricated housing factories and infrastructure stimulus programs lift procurement volumes for high-duty-cycle equipment. GB standards and MIIT regulations shape safety certification requirements for domestic and export markets. Yangtze River Delta manufacturing bases concentrate lithium-ion cell production and brushless motor assembly capacity.
India
Organized rental penetration below 15% in metropolitan construction markets creates channel infrastructure gaps for battery-platform leasing models. BIS certification and DGFT import regulations govern market access for foreign OEMs. Maharashtra and Gujarat industrial corridors concentrate construction activity and equipment distribution networks.
Japan
Automotive electrification changes fastener torque specifications, driving platform refresh cycles in service bay operations. METI efficiency standards and JIS certification requirements shape product development priorities. Kanto and Kansai industrial regions concentrate precision manufacturing and maintenance provider networks.
Portable Tools Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the portable tools sector. The market structure concentrates around integrated manufacturers with captive battery platforms and specialized component suppliers serving multiple OEMs. Three archetypes dominate: diversified industrial conglomerates with service networks, pure-play power tool specialists with proprietary ecosystems, and pneumatic heritage companies transitioning to cordless architectures. M&A activity targets battery management system capabilities and regional distribution networks.
Among diversified industrial conglomerates, Stanley Black & Decker, Inc. and Robert Bosch GmbH exemplify scale-driven positions anchored by service infrastructure and in-house technology development. Techtronic Industries Co. Ltd. occupies a specialist tier focused on cordless platform dominance through proprietary battery ecosystems. These three companies represent the competitive spectrum from broad industrial portfolios to concentrated power tool expertise.
| Leading Market Players |
|---|
| Stanley Black & Decker, Inc. |
| Robert Bosch GmbH |
| Techtronic Industries Co. Ltd. |
| Makita Corporation |
| Hilti Corporation |
| Atlas Copco AB |
| Apex Tool Group |
| Snap-on Incorporated |
| Ingersoll Rand Inc. |
| Others |
Value Chain & Pricing Dynamics
Brushless motor firmware engineers concentrated in Baden-Württemberg and the Yangtze River Delta feed labor-cost differentials that widen pricing-tier spreads between premium cordless platforms and economy corded alternatives.
Pricing Analysis
Margin tightening in professional-grade cordless tiers reflects lithium carbonate volatility and semiconductor allocation rationing from Taiwanese foundries. Three-tier pricing structure across premium, standard, and economy levels separates contractor-specified fleet systems from retail DIY bundles. Price differentiation hinges on brushless motor thermal performance and OSHA silica compliance certification. DIY enthusiasts exhibit highest price sensitivity; industrial maintenance departments prioritize total cost of ownership over acquisition cost.
Supply Chain Analysis
India's phased manufacturing program and China's MIIT domestic-content mandates are reshaping sourcing patterns for lithium-ion cells and motor controller ICs. Supply concentrates in China for battery cell production, Taiwan for semiconductor fabrication, and Germany for precision motor assembly. Raw material dependencies span lithium brine from South America, rare earth magnets from China, and copper windings from Chilean smelters. Single-source vulnerability in Taiwanese foundry capacity exposes tool OEMs to automotive sector demand surges. Distribution runs through authorized dealer networks for professional tiers and big-box retail for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cordless battery platforms are displacing pneumatic legacy systems in industrial maintenance, creating a technology-transition phase where ecosystem lock-in determines competitive survival.
For Market Incumbents: Anchor market position through captive battery platform expansion and in-house silicon carbide power electronics development. Defend against emerging leasing-model entrants by deepening service network density in Texas and Florida healthcare construction corridors. Prioritize backward integration into lithium-ion cell supply through joint ventures with Yangtze River Delta manufacturers. For New Entrants and Emerging Players: Launch via battery-platform leasing models targeting India's sub-15% organized rental penetration in metropolitan construction markets. Exploit white-space in 5G-enabled predictive maintenance subscriptions for automotive maintenance chains. Penetrate through outcome-based uptime guarantees rather than unit sales to facility management contractors. For Investors and Strategic Acquirers: The window for entry favors battery management system specialists with automotive-grade firmware capabilities and modular repair architectures. Long-term viability rests on circular economy compliance infrastructure for EU battery passport mandates. Watch for inflection when right-to-repair legislation forces OEM parts availability disclosures.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Ecosystem Expansion | Proprietary 12V-60V architectures lock in contractor fleets and simplify inventory management. |
| Silicon Carbide Power Electronics Integration | Advanced MOSFETs extend thermal margins in rotary hammers and impact wrenches. |
| Predictive Maintenance Software Development | Cloud-connected diagnostics convert hardware margins into recurring subscription revenue. |
| Reverse Logistics Infrastructure Buildout | Modular repair capabilities satisfy EU Green Deal extended producer responsibility mandates. |
| Organized Rental Channel Partnership | Leasing models capture India's underpenetrated metropolitan construction equipment market. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with procurement directors at general contracting firms, maintenance managers at automotive service chains, and aftermarket service heads at power tool distributors complemented secondary validation. OSHA enforcement databases, ECHA REACH substance registers, and MIIT certification records provided regulatory context. Bottom-up unit shipment estimates triangulated against top-down construction spending correlations.
Data-stream reconciliation across product type, power source, application, and end-user dimensions shaped the analytical framework. Modeled segments spanned drills, saws, grinders, and wrenches by battery, corded, pneumatic, and solar architectures. CAGRs derived from infrastructure stimulus tracking and replacement cycle analysis. Forecast inputs included lithium-ion energy density improvement curves and brushless motor adoption rates.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook. Forecasts reflect assumptions about OSHA silica enforcement intensity and EU circularity mandate timelines. Semiconductor fab capacity allocation and South American lithium supply disruptions present specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Digital Laser Levels Market
Tools
Structural Wood Screws Market
Tools
Woodworking Router Bits Market
Tools
Global Cutting Discs Market
Tools
Europe Woodworking Power Tools Market
Tools
Digital Cutting Machine Market
Tools
Cutting Tools Market
Tools
Theodolite Market
Tools
Scroll Saws Market
Tools
Hand Tools and Woodworking Tools Market
Tools
Wood Floor Grinding Machine Market
Tools
Global Standard Parts for Tool Making Market
Tools
End Milling Machine Market
Tools
Bi-Metal Band Saw Blade Market
Tools
Telescopic Tool Boxes Market
Tools
Orbital Recip Saw Market