
 Static Mixer Market | 2026-2036
Static Mixer Market Size, Share, and Industry Trends Forecast 2026-2036
Static Mixer Market Outlook
Process engineering talent shortages across North America and Western Europe are rotating capital budgets toward low-maintenance inline mixing systems that reduce operator intervention. Sulzer Ltd leverages its Swiss manufacturing base to sustain premium positioning in high-pressure polymer applications. SPX FLOW Inc anchors its portfolio through extensive food-grade certification coverage, while Komax Systems specializes in custom helical element geometries for viscous fluid processing.
A static mixer is a motionless in-line device that blends fluids through engineered internal elements—helical blades, corrugated plates, or perforated discs—without moving parts, typically achieving homogeneity within 10 to 20 pipe diameters downstream. Its primary purpose is to deliver continuous, energy-efficient mixing for laminar and turbulent flow regimes in process industries. Helical mixers dominate installed base volume due to mature design standards and broad viscosity compatibility, while multi-stage configurations capture expanding margin pools in pharmaceutical aseptic processing. Inline technology leads capital deployment across water treatment and chemical manufacturing, whereas low-shear designs are gaining fastest in biopharmaceutical protein stabilization workflows.
EPA effluent guidelines and FDA cGMP standards govern material selection and surface finish requirements for static mixers deployed in US water treatment and pharmaceutical production. REACH and the EU MDR impose complementary substance restrictions and traceability obligations on European suppliers serving medical and chemical end users. Stakeholders must monitor evolving PFAS regulations and bioprocessing purity standards, as these frameworks will determine which mixer architectures retain market access across priority jurisdictions.
Market Dynamics
Energy-intensive process industries are accelerating capital rotation toward motionless mixing architectures that eliminate mechanical seals, bearings, and motor drives while satisfying tightening effluent and purity mandates.
Growth Catalysts
- REACH substance restrictions:European chemical manufacturers are retrofitting production lines with corrosion-resistant static mixers to maintain market access under evolving ECHA substance authorization protocols.
- Helical element standardization:Mature design codes for twisted-blade geometries are reducing engineering validation cycles and accelerating procurement decisions across polymer compounding operations.
- Germany's industrial corridor:Specialty chemical producers in the Rhine-Ruhr and Bavarian chemical triangles are driving concentrated demand for high-pressure stainless steel mixing systems.
Market Restraints
- High-grade stainless steel volatility:Aerospace and medical device sectors compete for 316L and duplex alloy feedstock, compressing margins on corrosion-resistant mixer fabrication.
- Swiss manufacturing concentration:Premium high-pressure polymer mixing capacity clusters in Central European precision machining ecosystems, creating supply vulnerability for North American project timelines.
- Viscosity ceiling limitations:Conventional helical designs encounter mixing efficiency degradation above 500,000 cP, restricting addressable share in heavy bitumen and asphalt modification.
Strategic Opportunities
- Biopharmaceutical protein stabilization:Low-shear static mixing architectures are capturing workflow share in monoclonal antibody formulation where mechanical agitation risks denaturation.
- Modular skid-mounted systems:Packaged plant designs are opening channel access through engineering-procurement-construction firms serving mid-scale water treatment deployments.
- EPA water quality standards:Evolving effluent guidelines for nutrient removal are mandating precise chemical dosing that favors inline static mixing over conventional tank-based approaches.
Industry Challenges
- Process engineering talent scarcity:North American and Western European facilities lack sufficient inline mixing specialists to specify, validate, and troubleshoot custom element geometries.
- FDA cGMP surface finish compliance:Pharmaceutical-grade mixers require sub-20 Ra electropolished internals with full material traceability, extending qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Static Mixer Market |
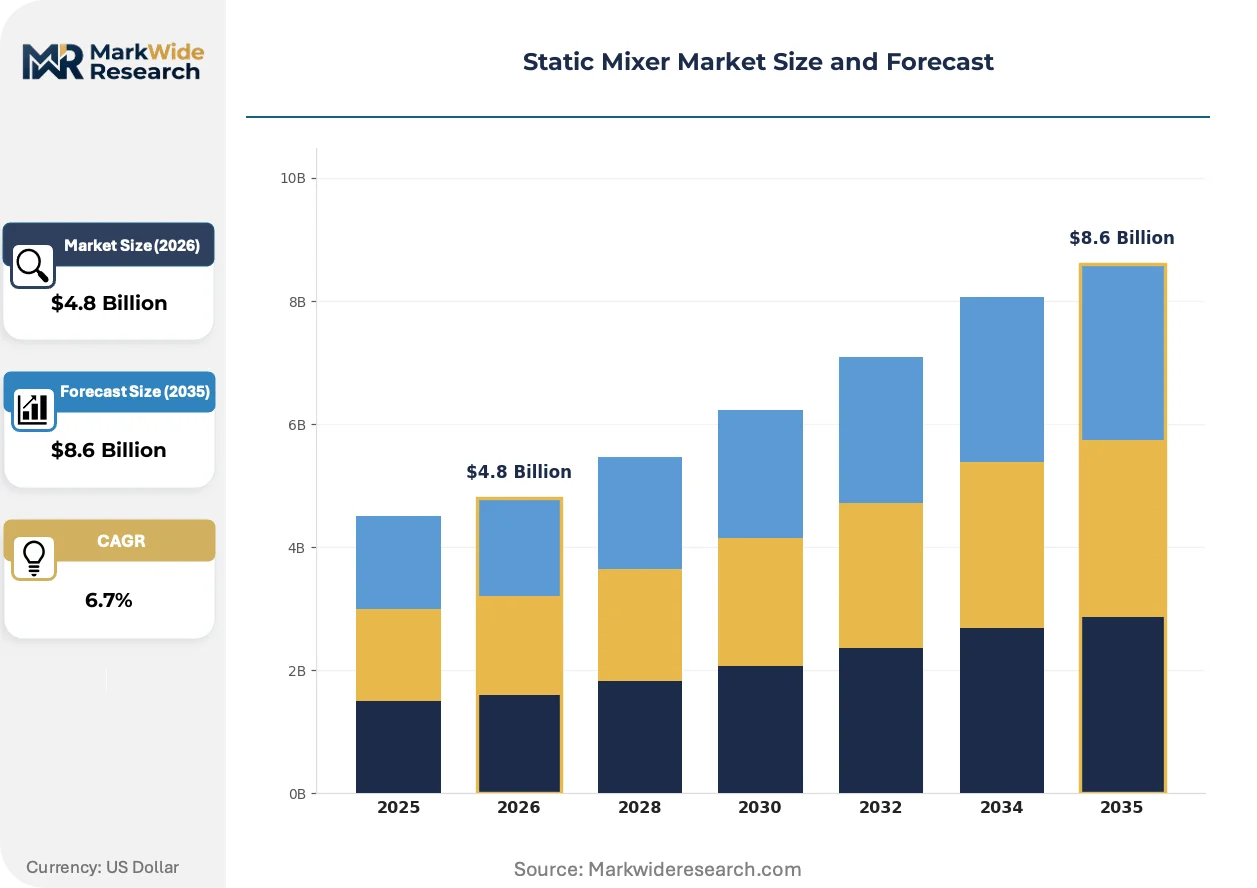
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: T-shaped Mixers, Helical Mixers, Disc Mixers, Multi-stage Mixers Application: Adhesives, Food Processing, Chemical Manufacturing, Water Treatment End User: Food & Beverage, Pharmaceuticals, Oil & Gas, Plastics Technology: Inline Mixers, Batch Mixers, High-Pressure Mixers, Low-Shear Mixers |
| Companies Covered | Sulzer Ltd, SPX FLOW Inc, Koflo Corp, Statiflo Group, Komax Systems, Admix Inc, Stamixco AG, NOV Inc, Mott Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Static Mixer Market Strategic Shifts
Additive manufacturing of complex internal geometries is collapsing the trade-off between mixing precision and pressure drop, enabling geometries previously machined from solid billets.
Computational fluid dynamics-optimized corrugated plate designs are displacing conventional helical configurations in turbulent-flow water treatment applications. Municipal utilities in the US Southwest are specifying these elements for rapid chlorine disinfection contact chambers. The shift is compressing installed footprint requirements while maintaining log-reduction performance.
REACH authorization timelines and evolving PFAS restrictions are forcing material specification reviews across European chemical process installations. Stainless steel suppliers must now document full alloy composition traceability to ECHA standards. Pharmaceutical and food-grade mixer producers are responding by qualifying alternative fluoropolymer-free surface coatings.
Specification authority is migrating from plant maintenance departments to centralized corporate engineering functions with standardized vendor qualification protocols. This consolidation is squeezing regional distributors and favoring direct manufacturer relationships with documented aftermarket service capabilities. The pattern is most pronounced in German and US multinational chemical portfolios.
Static Mixer Market Segmentation
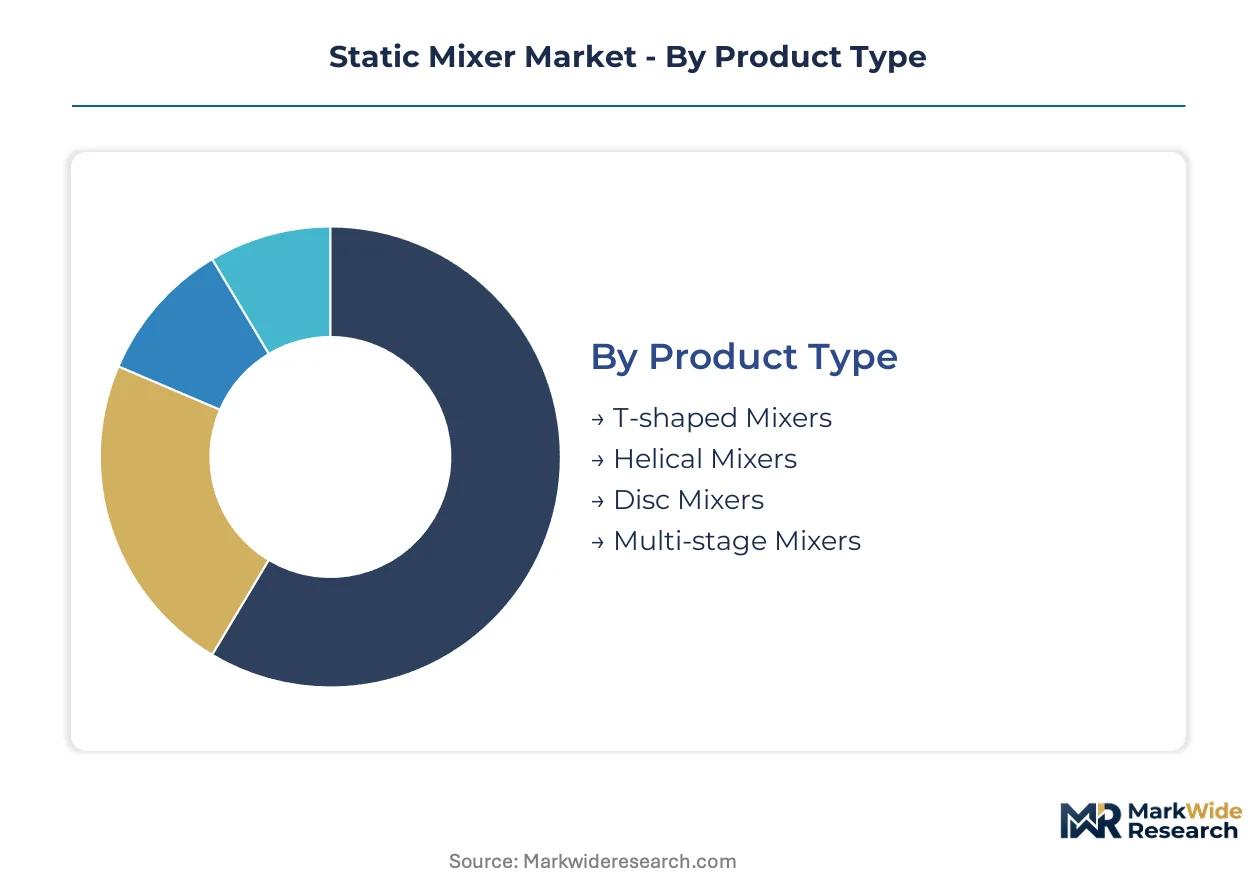
Static mixer procurement patterns diverge sharply across product architectures and end-use specifications. Channel access depends on matching mixer technology to regulatory compliance tiers and maintenance capability profiles.
Product Type:
Channel mix varies by complexity—standard helical units move through distributors, while custom multi-stage systems require direct manufacturer engagement.
- Helical Mixers:Twisted-blade geometries fabricated from stainless steel billets achieve homogeneity through laminar flow division and recombination. Rhine-Ruhr chemical producers specify these for polymer compounding under REACH substance authorization protocols. Helical designs dominate installed base due to mature engineering codes and broad viscosity compatibility.
- Multi-stage Mixers:Cascaded element arrays enable precise residence time distribution control for pharmaceutical aseptic processing. FDA cGMP surface finish requirements and full material traceability obligations drive specification toward electropolished 316L configurations with documented alloy composition.
- T-shaped Mixers:Simple junction geometries serve low-viscosity blending in water treatment chlorine contact chambers.
- Disc Mixers:Perforated plate configurations address turbulent-flow applications with moderate pressure drop tolerance.
Helical mixers dominate installed base. Multi-stage configurations are where expansion concentrates.
Application:
Cost tier stratification separates premium pharmaceutical-grade systems from standard industrial offerings.
- Chemical Manufacturing:High-pressure stainless steel architectures handle corrosive reagents and viscous intermediates in continuous reactor feed systems. Germany's specialty chemical corridor drives specification authority toward documented aftermarket service capabilities and REACH-compliant material certification.
- Water Treatment:CFD-optimized corrugated plate designs displace conventional helical elements in municipal chlorine disinfection. US Southwest utilities specify these for log-reduction performance within compressed footprint constraints under evolving EPA effluent guidelines.
- Adhesives:Viscous fluid processing demands custom element geometries for uniform catalyst dispersion.
- Food Processing:3-A sanitary standards and USDA compliance govern surface finish and clean-in-place compatibility.
Chemical manufacturing absorbs the highest unit values. Water treatment is climbing the fastest.
End User:
Customer type determines specification authority—centralized corporate engineering functions versus plant-level maintenance procurement.
- Pharmaceuticals:Monoclonal antibody formulation workflows demand low-shear architectures that eliminate mechanical agitation risks to protein stability. EU MDR traceability obligations and FDA cGMP standards impose sub-20 Ra electropolished internals with full material documentation, extending qualification timelines.
- Plastics:Polymer compounding operations prioritize helical element standardization to reduce engineering validation cycles and accelerate capital deployment.
- Food & Beverage:SPX FLOW Inc's food-grade certification coverage anchors procurement decisions for aseptic processing lines.
- Oil & Gas:Heavy bitumen modification encounters viscosity ceiling limitations above 500,000 cP with conventional helical designs.
Pharmaceuticals command premium pricing tiers. Plastics represents the steepest expansion trajectory.
Technology:
Supply concentration in Swiss and German precision machining ecosystems shapes regional availability for high-pressure variants.
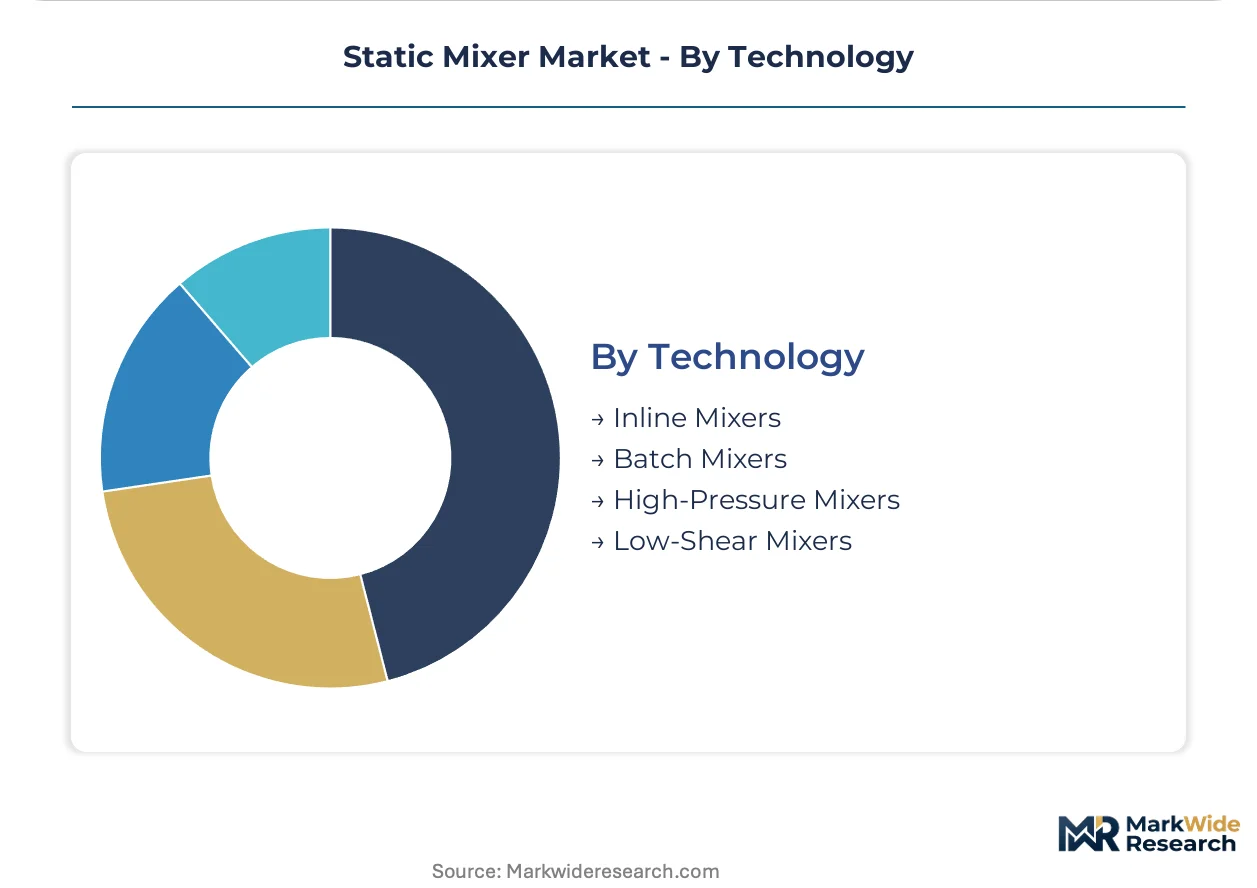
- Inline Mixers:Motionless architectures eliminate mechanical seals, bearings, and motor drives while satisfying tightening effluent mandates. Capital rotation toward these systems accelerates as North American facilities face process engineering talent shortages.
- Low-Shear Mixers:Gentle blending profiles capture workflow share in biopharmaceutical protein stabilization where conventional agitation risks denaturation.
- High-Pressure Mixers:Central European manufacturing concentration creates supply vulnerability for North American project timelines.
- Batch Mixers:Tank-based approaches face displacement pressure from continuous processing mandates in chemical manufacturing.
Inline technology dominates capital deployment. Low-shear designs are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH substance restrictions and EPA effluent guidelines anchor regulatory pressure across the two largest national markets. Specialty chemical corridors and municipal water utilities drive differentiated equipment specifications by geography.
United States
EPA water quality standards for nutrient removal mandate precise chemical dosing in municipal treatment plants. Southwest utilities specify CFD-optimized corrugated plate designs for compressed chlorine contact chambers. The industrial Midwest hosts polymer compounding operations rotating capital toward low-maintenance inline architectures.
Germany
ECHA authorization protocols under REACH force material specification reviews across Rhine-Ruhr chemical installations. Bavarian specialty chemical producers concentrate procurement authority for high-pressure stainless steel mixing systems. Precision machining ecosystems in Baden-Württemberg sustain premium fabrication capacity for polymer applications.
China
GB standards for industrial wastewater discharge tighten compliance obligations for chemical manufacturing facilities. Yangtze River Delta process industries expand continuous reactor feed system deployments. Shandong Peninsula petrochemical complexes address viscosity ceiling limitations in heavy bitumen modification workflows.
Switzerland
Swissmedic traceability requirements intersect with EU MDR obligations for pharmaceutical-grade mixer exports. Central European precision machining clusters concentrate high-pressure polymer mixing capacity. Zurich-region fabricators serve North American project timelines with documented aftermarket service capabilities.
India
BIS certification mandates and CDSCO pharmaceutical regulations shape material selection for domestic production. Maharashtra chemical corridors adopt inline mixing technology to reduce energy consumption in continuous processing. Gujarat specialty chemical producers qualify corrosion-resistant architectures under evolving central pollution control standards.
Static Mixer Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the static mixer market. Swiss and German precision fabricators anchor premium-tier positioning in high-pressure polymer applications. North American and Asian suppliers compete on food-grade certification coverage and modular skid-mounted system integration. The competitive landscape stratifies into three archetypes: precision machining specialists, diversified process equipment conglomerates, and application-specific engineering houses. Capacity expansion in Central European machining ecosystems and strategic partnerships with engineering-procurement-construction firms represent the dominant competitive moves.
Among Swiss-based precision fabricators, Sulzer Ltd occupies a position exemplifying high-pressure polymer specialization. SPX FLOW Inc represents the diversified conglomerate archetype with extensive food-grade certification coverage. Komax Systems sits within the application-specific tier, anchoring custom helical element geometry capabilities for viscous fluid processing. These three entities collectively illustrate how geographic origin and organizational structure map to distinct competitive positioning vectors across regulatory compliance tiers and end-use specifications.
| Leading Market Players |
|---|
| Sulzer Ltd |
| SPX FLOW Inc |
| Koflo Corp |
| Statiflo Group |
| Komax Systems |
| Admix Inc |
| Stamixco AG |
| NOV Inc |
| Mott Corp |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Swiss precision machining clusters shapes both supply concentration and price floors across high-pressure polymer mixing tiers. German specialty chemical buyers absorb premium markups for documented REACH compliance and electropolished 316L internals, while North American water utilities negotiate corrugated plate configurations on compressed municipal budgets.
Pricing Analysis
Central European fabricators command 40-60% premiums over Asian competitors for identical helical geometries, reflecting alloy traceability documentation and Swissmedic export certification. Three-tier pricing structure across premium, standard, and economy levels segments on certification grade and after-sales service bundling. Cost compression in standard helical tiers is intensifying because commodity stainless distributors are qualifying alternative East Asian billet sources. Municipal water utilities exhibit highest price sensitivity, while pharmaceutical monoclonal antibody producers accept premium positioning to secure FDA cGMP surface finish compliance.
Supply Chain Analysis
Switzerland and Germany anchor high-pressure polymer mixing fabrication through Baden-Württemberg precision machining ecosystems and Zurich-region electropolishing capacity. Raw material flows draw from Swedish duplex alloy producers, Japanese specialty steel mills, and Italian seamless tube manufacturers. Single-source vulnerability concentrates in Swissmedic-authorized surface finishing facilities serving North American pharmaceutical timelines. Distribution runs through direct manufacturer relationships with documented aftermarket service capabilities, squeezing regional distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Static mixer demand is accelerating as EPA effluent guidelines and REACH substance restrictions eliminate tank-based alternatives in water treatment and chemical manufacturing. Additive manufacturing of complex internal geometries is collapsing the precision-versus-pressure-drop trade-off, reshaping procurement criteria across laminar and turbulent flow applications.
For Market Incumbents: Secure captive supply of 316L and duplex alloy feedstock through backward integration into European specialty steel distribution channels. Defend margin position by accelerating FDA cGMP qualification timelines for electropolished multi-stage configurations, as emerging Asian fabricators lack pharmaceutical surface finish expertise.
For New Entrants and Emerging Players: Aftermarket service capability gaps in North American water treatment utilities present white-space entry points for modular skid-mounted system integrators. Target US Southwest municipal chlorine contact chamber retrofits with CFD-optimized corrugated plate offerings priced below Sulzer Ltd premiums. Partner with engineering-procurement-construction firms to bypass specification authority concentrated in centralized corporate engineering functions.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision fabricators with pharmaceutical-grade aftermarket service contracts and documented alloy traceability systems. Long-term viability favors Swiss and German machining specialists with EU MDR export authorization and captive electropolishing capacity. Monitor PFAS restriction timelines as the inflection signal determining which fluoropolymer-coated architectures retain market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Supply | Captive 316L and duplex feedstock secures margin against aerospace and medical device competition. |
| Modular Skid-Mounted System Expansion | Packaged plant designs open channel access through EPC firms serving mid-scale water treatment deployments. |
| Pharmaceutical cGMP Qualification Acceleration | Sub-20 Ra electropolished internals with full material traceability extend qualification timelines for monoclonal antibody workflows. |
| Additive Manufacturing Capability Investment | Complex internal geometries previously machined from solid billets collapse pressure drop penalties. |
| REACH-Compliant Surface Coating Development | Alternative fluoropolymer-free coatings preserve market access under evolving ECHA substance authorization protocols. |
Study Parameters
A standing panel of plant engineers, maintenance directors at chemical manufacturing facilities, procurement leads at municipal water utilities, and aftermarket service heads provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against SEC 10-K filings, Cefic chemical industry reports, EPA effluent guideline dockets, and customs trade data. Bottom-up unit economics triangulated against top-down market sizing across product architectures and end-use specifications.
Consistency checks validated volume and value outputs against external benchmarks throughout the projection horizon. The analytical framework modeled segmentation across mixer technology type, application vertical, certification tier, and regional regulatory cluster. CAGRs were derived from installed base rotation rates and capital expenditure patterns across chemical manufacturing and water treatment end uses. Forecast inputs incorporated REACH authorization timeline assumptions and evolving PFAS restriction scenarios.
Underlying assumptions cover continuous processing mandates and tightening effluent standards, with deviation risk concentrated in aerospace and medical device alloy feedstock competition and process engineering talent scarcity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Plastic Compounding Machinery Market
Industrial Materials
Tablet Press Tooling Market
Industrial Materials
Gaskets and Seals Market
Industrial Materials
Gravity Die Casting Market
Industrial Materials
Air Classifiers Market
Industrial Materials
Global High Temperature Gaskets Market
Industrial Materials
Hardfacing Rods Market
Industrial Materials
Global Industrial Fastener Seal Market
Industrial Materials
Thermal Spray Guns Market
Industrial Materials
Gypsum Plaster Market
Industrial Materials
Grouting Materials Market
Industrial Materials
Global Polyurethane Screen Panels Market
Industrial Materials
Wood Fiber Insulation Market
Industrial Materials
Chalk Reel and Line Chalk Market
Industrial Materials
Neoprene Foam Market
Industrial Materials
Heavy Gauge and Thin Gauge Thermoformed Plastics Market