
 Continuous Mesh Belt Furnaces Market | 2026-2036
Continuous Mesh Belt Furnaces Market Size, Share, and Industry Trends Forecast 2026-2036
Continuous Mesh Belt Furnaces Market Insights
EPA emissions rules for industrial heat-treatment equipment is recalibrating the cost-of-entry calculus for furnace operators across North America. SECO/WARWICK leverages its European manufacturing base to serve American automotive suppliers navigating these compliance thresholds. Ipsen sustains technology leadership in vacuum-compatible mesh belt architectures for aerospace-grade processing. Aichelin Group anchors its competitive position through backward integration into burner and control system production.
Continuous mesh belt furnaces are industrial thermal processing systems that transport workpieces on an articulated metal mesh conveyor through controlled heating and cooling zones, typically achieving temperatures between 800°C and 1,150°C for atmosphere-controlled brazing, annealing, and sintering operations. Resistance heating configurations dominate installed capacity in semiconductor producer facilities where atmosphere purity requirements exclude combustion-based alternatives. Continuous furnace architectures capture the majority of revenue in metal heat treatment applications due to throughput economics that batch systems cannot match. Gas combustion technology retains share in energy equipment fabrication where natural gas availability and lower operating costs outweigh capital efficiency considerations.
FDA oversight of medical device sintering processes and ISO quality certifications for aerospace suppliers impose documentation and traceability requirements that favor established furnace vendors with compliance engineering capabilities. The EU Green Deal's industrial decarbonization targets and China's GB energy efficiency standards for thermal equipment are reshaping R&D priorities toward hydrogen-ready burner designs and waste-heat recovery integration. Stakeholders must evaluate whether to retrofit existing gas combustion lines or commit to full electric heating transitions before regulatory phase-in timelines crystallize.
Market Dynamics
Electric heating retrofits are compressing the technology lifecycle for installed gas combustion lines as EPA emissions standards force capital redeployment decisions across North American heat-treatment facilities.
Growth Catalysts
- Aerospace Component Demand:Precision heat treatment requirements for turbine blades and vanes are pulling continuous mesh belt architectures into supplier qualification programs. FAA certification pathways for additive-manufactured aerospace parts require documented thermal processing traceability that these systems provide.
- EU Green Deal Industrial Decarbonization:The framework's binding emissions reduction targets are accelerating hydrogen-ready burner R&D and waste-heat recovery integration across European furnace installations. Germany's automotive tooling sector is anchoring procurement of compliant equipment.
- Semiconductor Fabrication Expansion:Atmosphere purity requirements in wafer processing are excluding combustion-based alternatives and driving resistance heating configurations into new cleanroom facilities.
Market Restraints
- Nickel-Chromium Alloy Supply Concentration:Mesh belt fabrication depends on specialized high-temperature alloys sourced from a limited supplier base concentrated in Germany and Japan, creating input cost volatility and lead time risk.
- Natural Gas Price Arbitrage:Regions with pipeline gas access retain operating cost advantages that delay electric transition economics, fragmenting technology adoption timelines across geographies.
- Vacuum-Atmosphere Technical Ceiling:Mesh belt seals face fundamental pressure differential limitations that exclude the architecture from certain aerospace vacuum brazing specifications, ceding share to pusher furnace alternatives.
Strategic Opportunities
- India PLI Scheme Manufacturing:Production-linked incentives for automotive and electronics manufacturing are creating greenfield furnace demand as component suppliers localize heat-treatment capacity.
- Medical Device Sintering:FDA oversight of implantable device manufacturing is expanding addressable market for atmosphere-controlled systems with batch documentation capabilities in orthopedic and dental applications.
- Hydrogen Combustion Convergence:Integration of hydrogen-ready burner designs with existing furnace architectures offers a transition pathway that preserves capital investment while meeting EU decarbonization mandates.
Industry Challenges
- Controls Engineering Talent Scarcity:Multi-zone temperature profiling and atmosphere management require specialized expertise that outpaces vocational training pipeline output in mature manufacturing economies.
- ISO Certification Timeline Compression:Aerospace supplier audits demand 12-18 month qualification periods for new furnace installations, extending sales-to-revenue cycles and working capital requirements.
- Legacy System Integration Friction:Retrofit projects face control protocol incompatibilities between 1990s-era installations and modern SCADA architectures, inflating project scope and commissioning risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuous Mesh Belt Furnaces Market |
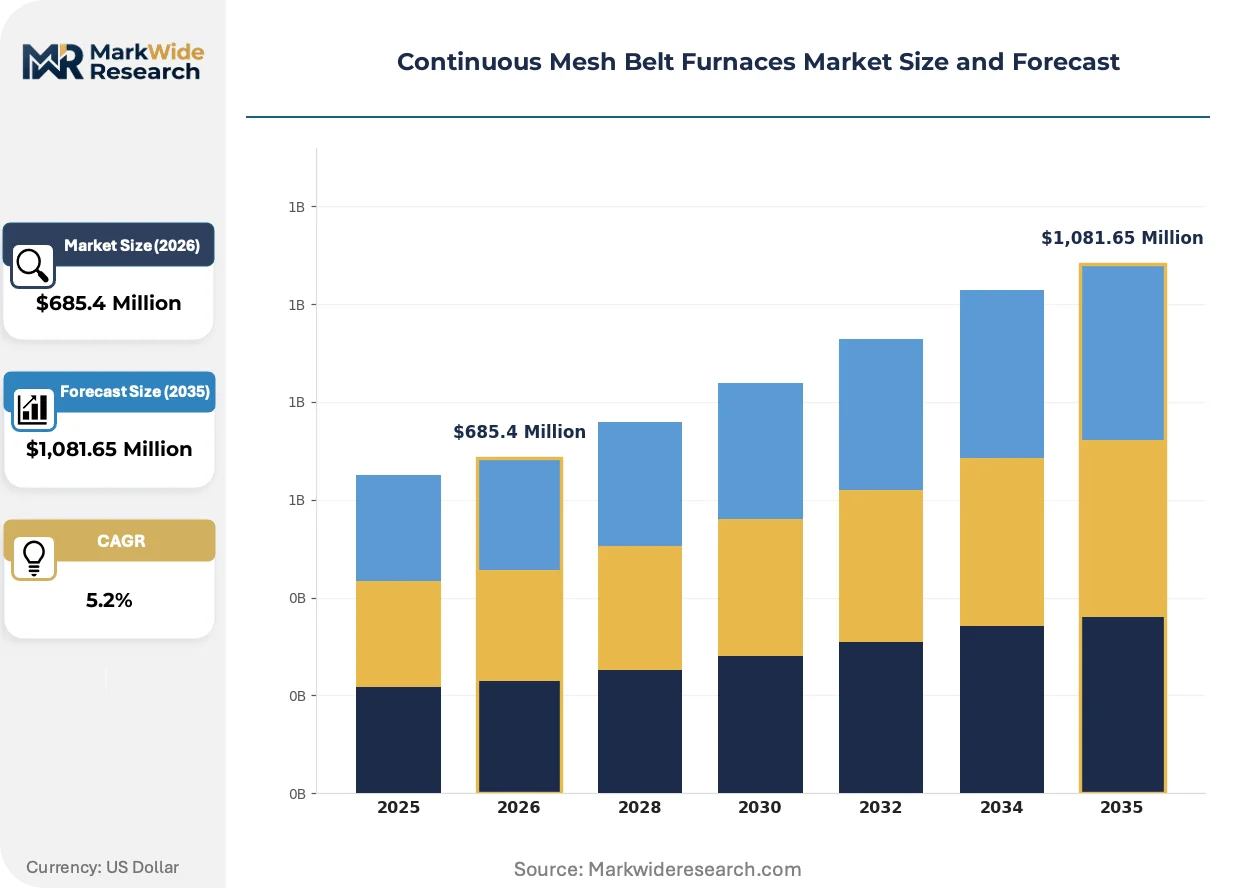
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Furnaces, Continuous Furnaces, Vacuum Furnaces, Rotary Furnaces, Pit Furnaces Heating Technology: Resistance Heating, Induction Heating, Infrared Heating, Gas Combustion, Electric Heating Application: Metal Heat Treatment, Ceramic Sintering, Electronics Manufacturing, Glass Processing, Powder Metallurgy End User Industry: Aerospace Manufacturers, Tooling Facilities, Semiconductor Producers, Automotive Suppliers, Energy Equipment Fabricators |
| Companies Covered | Aichelin Group, Ipsen, SECO/WARWICK, CAN-ENG Furnaces, Lindberg/MPH, Surface Combustion, Gasbarre, AFC-Holcroft, Nutec Bickley, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuous Mesh Belt Furnaces Market Trends and Innovations
Digital twin architectures and predictive maintenance platforms are reconfiguring how furnace operators manage throughput optimization and unplanned downtime risk across continuous thermal processing lines.
Advanced sensor fusion combining infrared thermography, oxygen probe analytics, and conveyor tension monitoring is unifying previously siloed process control loops into single-dashboard visibility. Semiconductor manufacturers in South Korea and Taiwan are deploying these integrated architectures at scale. This unification is compressing the competitive window for standalone control system vendors and favoring furnace OEMs with captive automation engineering.
China's GB energy efficiency standards for industrial thermal equipment are mandating waste-heat recovery integration and minimum combustion efficiency thresholds for new installations. Domestic furnace producers are accelerating heat exchanger and regenerative burner development to maintain market access. Export-oriented automotive component suppliers in Jiangsu and Zhejiang provinces are prioritizing compliant equipment to preserve OEM qualification status.
Consolidated procurement through integrated heat-treatment service providers is displacing fragmented captive furnace ownership among mid-tier automotive suppliers. Tier-2 component manufacturers in Germany's Baden-Württemberg and Bavaria clusters are outsourcing precision brazing and annealing to specialized toll processors. This channel shift concentrates equipment purchasing authority with fewer, larger buyers with greater negotiating leverage and technical specification influence.
Continuous Mesh Belt Furnaces Market Segmentation
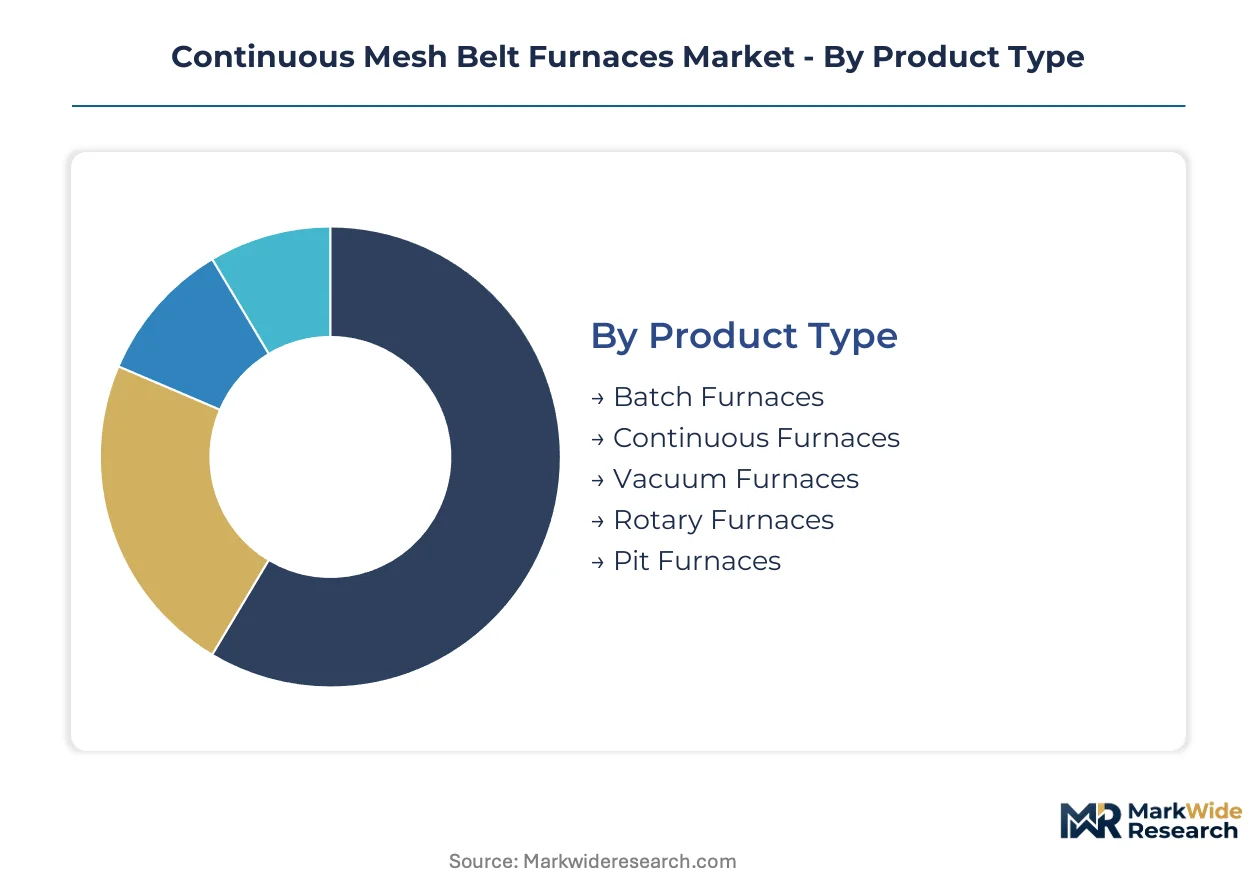
Equipment specification pathways diverge sharply across end-use requirements, with furnace architectures selected based on throughput economics, atmosphere purity demands, and regulatory compliance obligations. Segmentation clarity enables procurement teams to align capital deployment with qualification timelines and operational cost structures.
Product Type:
Replacement cycles favor continuous architectures where throughput economics justify capital intensity, while batch systems retain footholds in low-volume precision applications.
- Continuous Furnaces:Articulated mesh belt conveyors transport workpieces through sequential heating and cooling zones, achieving 800°C to 1,150°C for atmosphere-controlled brazing and sintering. Aerospace turbine component suppliers in Germany specify these systems for FAA-traceable thermal processing documentation.
- Batch Furnaces:Enclosed chamber designs process discrete loads with flexible atmosphere control, suiting prototype development and small-lot aerospace qualification runs. Tooling facilities in Baden-Württemberg deploy batch units for die steel heat treatment where product mix variability exceeds continuous line economics.
- Vacuum Furnaces:Sealed cold-wall chambers eliminate oxidation through pumped atmosphere environments, serving nickel superalloy processing for turbine blade manufacturers.
- Rotary Furnaces:Rotating retort designs enable uniform powder exposure for calcination and reduction operations in cemented carbide production.
- Pit Furnaces:Vertical shaft configurations accommodate long workpieces such as drive shafts and landing gear struts for automotive and aerospace verticals.
Volume placements concentrate in Continuous Furnaces; the faster expansion belongs to Vacuum Furnaces.
Heating Technology:
Operating cost structures and emissions compliance timelines are fragmenting technology adoption across geographies with divergent energy pricing and regulatory phase-ins.
- Resistance Heating:Nickel-chromium or silicon carbide elements deliver precise temperature control without combustion byproducts, satisfying semiconductor cleanroom atmosphere purity requirements. Wafer fabrication facilities in Taiwan and South Korea specify resistance configurations exclusively.
- Electric Heating:Advanced element designs and power modulation enable rapid thermal response for electronics manufacturing applications. Jiangsu province automotive suppliers are prioritizing electric retrofits to preserve OEM qualification status under tightening GB energy efficiency standards.
- Gas Combustion:Direct-fired burner arrays retain operating cost advantages where pipeline natural gas access undercuts electricity tariffs.
- Induction Heating:Electromagnetic coupling generates subsurface heating for selective hardening of gear teeth and bearing races.
- Infrared Heating:Radiant panel configurations deliver rapid response for glass tempering and thin-film drying operations.
Procurement volumes cluster around Resistance Heating; Induction Heating is climbing the fastest as automotive powertrain electrification reshapes component metallurgy requirements.
Application:
Process temperature windows and atmosphere specifications create distinct equipment requirements that resist cross-application standardization.
- Metal Heat Treatment:Austenitizing, quenching, and tempering operations for ferrous alloys dominate installed capacity, with continuous lines capturing throughput-intensive automotive and tooling demand.
- Electronics Manufacturing:Solder reflow and ceramic substrate firing demand sub-ppm atmosphere control, excluding combustion heating from advanced packaging facilities.
- Powder Metallurgy:Delubrication and sintering of ferrous and non-ferrous compacts for structural automotive components.
- Ceramic Sintering:High-temperature densification of alumina, zirconia, and silicon nitride for medical implants and cutting tools.
- Glass Processing:Thermal conditioning and tempering for architectural and automotive glazing applications.
Revenue concentration sits with Metal Heat Treatment; Electronics Manufacturing is gaining share fastest as semiconductor capacity expansion accelerates.
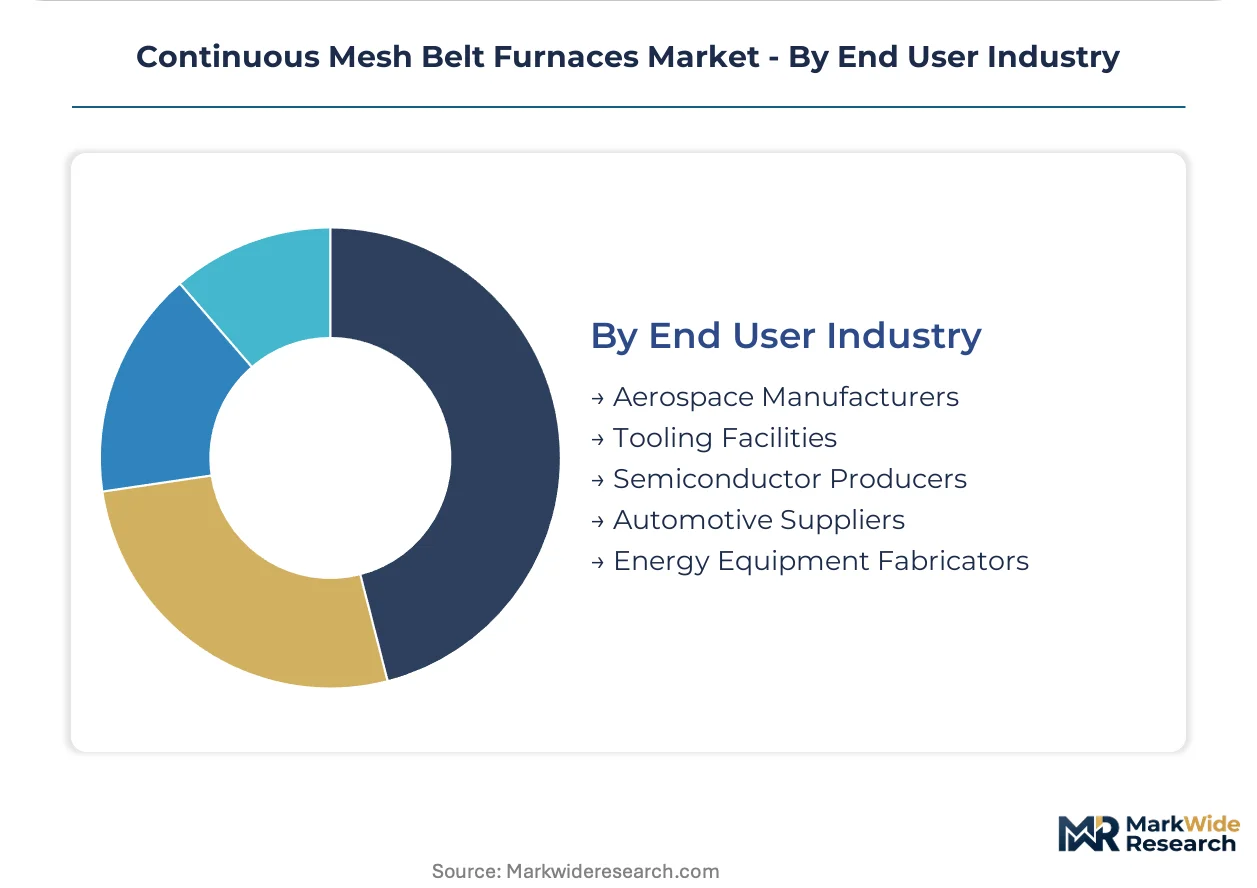
End User Industry:
Qualification protocols and certification timelines fragment purchasing authority across captive and outsourced heat-treatment models.
- Semiconductor Producers:Cleanroom-compatible resistance heating systems with documented particle and moisture control satisfy wafer processing requirements. Memory and logic foundries in Hsinchu and Pyeongtaek anchor demand for atmosphere-purity-rated equipment.
- Aerospace Manufacturers:FAA and EASA certification pathways for additive-manufactured turbine components mandate thermal processing traceability that continuous mesh belt architectures deliver. Precision casting suppliers in Bavaria specify vacuum-compatible configurations for nickel superalloy processing.
- Automotive Suppliers:Powertrain component heat treatment and brazing operations for electric vehicle thermal management systems.
- Tooling Facilities:Die and mold steel hardening for injection molding and stamping operations.
- Energy Equipment Fabricators:Large-scale brazing of heat exchangers and turbine components for power generation infrastructure.
Equipment placements concentrate among Semiconductor Producers; Aerospace Manufacturers are expanding most quickly as additive manufacturing qualification broadens addressable thermal processing demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement concentrates in Germany's automotive tooling corridors, where tier suppliers anchor demand for FAA-traceable thermal processing systems. Foundries across Baden-Württemberg and Bavaria are retrofitting gas combustion lines ahead of EU Green Deal phase-ins.
United States
Aerospace turbine component manufacturers in Connecticut and Ohio are qualifying continuous mesh belt architectures for additive-manufactured parts. EPA emissions standards for industrial combustion equipment are compressing technology lifecycles and forcing capital redeployment decisions. Precision casting suppliers in the Hartford-Springfield corridor specify vacuum-compatible configurations for nickel superalloy processing.
Germany
Automotive suppliers in Baden-Württemberg and tooling facilities in Bavaria anchor European equipment procurement volumes. EU Green Deal industrial decarbonization targets are accelerating hydrogen-ready burner R&D across furnace installations. The Stuttgart and Munich industrial clusters are outsourcing precision brazing to specialized toll processors, consolidating purchasing authority.
China
Export-oriented automotive component suppliers in Jiangsu and Zhejiang provinces are prioritizing GB energy efficiency-compliant equipment to preserve OEM qualification status. Domestic furnace producers are accelerating waste-heat recovery integration to maintain market access. Yangtze River Delta semiconductor fabrication expansion is driving resistance heating configurations into new cleanroom facilities.
Japan
High-temperature alloy mesh belt fabrication depends on specialized suppliers concentrated in Japanese and German industrial bases. JIS standards for industrial thermal equipment impose efficiency thresholds that shape R&D priorities. Nagoya-area tooling facilities deploy batch units for die steel heat treatment where product mix variability exceeds continuous line economics.
South Korea
Memory and logic foundries in Hsinchu and Pyeongtaek anchor demand for atmosphere-purity-rated resistance heating systems. MFDS oversight of medical device manufacturing is expanding addressable market for batch documentation capabilities. Advanced sensor fusion architectures are unifying process control loops into single-dashboard visibility at scale.
Continuous Mesh Belt Furnaces Market Competitive Landscape
German and Austrian producers anchor the premium equipment tier; North American specialists hold positions in aerospace-qualified system integration. The vendor base separates into consolidated furnace OEMs with captive automation engineering and mid-scale fabricators serving regional tooling demand. Three archetypes dominate: vertically integrated thermal equipment conglomerates, atmosphere-control engineering specialists, and regional batch furnace fabricators. Capacity expansion and strategic partnerships represent the dominant competitive vectors as compliance timelines compress.
Within the European integrated tier, Aichelin Group exemplifies backward integration into burner and control system production. Ipsen occupies a position among atmosphere-control engineering specialists, while SECO/WARWICK represents the transatlantic configuration serving American automotive suppliers navigating EPA compliance thresholds. CAN-ENG Furnaces and Lindberg/MPH sit within the North American specialist segment.
| Leading Market Players |
|---|
| Aichelin Group |
| Ipsen |
| SECO/WARWICK |
| CAN-ENG Furnaces |
| Lindberg/MPH |
| Surface Combustion |
| Gasbarre |
| AFC-Holcroft |
| Nutec Bickley |
| Others |
Pricing and Supply Chain Analysis
Consolidated procurement through German automotive tooling clusters is forcing furnace OEMs to absorb certification engineering costs upfront, compressing margins on standard configurations while premium vacuum-compatible systems retain pricing power through technical differentiation.
Pricing Analysis
Volume placements in continuous mesh belt architectures run on thin project-based margins, while vacuum-compatible and hydrogen-ready configurations command premium positioning through FAA-traceable documentation and EU Green Deal compliance bundling. Price differentiation hinges on ISO certification tier and after-sales service integration, with aerospace-qualified systems carrying substantial brand premiums over standard tooling equipment. Pricing pressure stems from buyer consolidation in Germany's Baden-Württemberg corridor, where toll processors leverage scale to extract favorable terms. Mid-tier automotive suppliers exhibit highest price sensitivity, whereas semiconductor producers prioritize atmosphere purity over capital efficiency.
Supply Chain Analysis
High-temperature nickel-chromium alloy mesh belt fabrication rests on specialized suppliers concentrated in Germany and Japan, creating input cost volatility when raw material markets tighten. Furnace OEMs draw from Japanese specialty steel producers, German burner component specialists, and Taiwanese control system vendors to assemble finished systems. Single-source vulnerability in mesh belt alloys represents the dominant supply chain risk, with limited qualified suppliers capable of meeting aerospace traceability requirements. Distribution runs through direct OEM sales for large automotive and semiconductor accounts, while regional fabricators serve fragmented tooling demand through distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around furnace OEMs with captive automation engineering as EPA emissions timelines and EU decarbonization mandates force capital-constrained regional fabricators toward exit or acquisition.
For Market Incumbents: Deepen backward integration into burner and control system production to defend margin position against emerging Asian competitors. Prioritize hydrogen-ready R&D investment ahead of EU Green Deal phase-ins, while acquiring regional batch furnace specialists in Japan and Central Europe to secure alloy supply relationships and local service density. For New Entrants and Emerging Players: Digital-channel aftermarket service platforms offer a lower-capital entry path for furnace control system retrofit and predictive maintenance software. Target India's PLI-driven automotive component localization as the most penetrable geography, positioning on rapid commissioning timelines that incumbent OEMs cannot match for greenfield installations. For Investors and Strategic Acquirers: The window for entry favors atmosphere-control engineering specialists with vacuum-compatible architectures and established aerospace qualification pathways. Long-term viability centers on hydrogen combustion convergence capabilities and waste-heat recovery integration. Watch for EU Green Deal enforcement acceleration as the inflection signal triggering premium asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Burner Development | Preserves capital investment while meeting EU Green Deal decarbonization mandates for installed gas combustion lines. |
| Waste-Heat Recovery Integration | China's GB energy efficiency standards require heat exchanger systems for market access in Jiangsu and Zhejiang provinces. |
| Digital Twin Platform Deployment | South Korean semiconductor foundries deploy predictive maintenance architectures to compress unplanned downtime risk. |
| Aerospace Qualification Investment | FAA certification pathways for additive-manufactured turbine components mandate 12-18 month furnace qualification timelines. |
| Regional Service Network Expansion | India's PLI scheme for automotive manufacturing creates greenfield demand requiring local commissioning and spare parts capability. |
Research Methodology
Trade association filings, customs import records, and SEC equipment supplier disclosures formed the secondary backbone, cross-referenced with primary interviews involving maintenance directors at automotive heat-treatment facilities, plant engineers at semiconductor fabrication sites, OEM procurement teams at aerospace casting suppliers, and aftermarket service heads at furnace distributors. Bottom-up and top-down triangulation validated installed base estimates against capital expenditure disclosures and regional production capacity data.
Bottom-up modeling tracked equipment shipments by heating technology, product architecture, and end-use qualification tier across the projection horizon, while top-down analysis calibrated aggregate market sizing against industrial thermal processing capital expenditure patterns. Segmentation dimensions included furnace type, heating configuration, application process requirements, and end-user industry certification intensity. CAGRs were derived from regression analysis of historical procurement cycles and regulatory phase-in timelines, with semiconductor fabrication expansion and aerospace additive manufacturing qualification serving as primary demand-side forecast inputs.
The model holds under steady regulatory enforcement schedules and intact alloy supply channels; deviation in EPA emissions timeline acceleration or nickel-chromium trade restrictions would shift replacement cycle assumptions. Forecasts reflect documented qualification periods and technology transition economics. A small set of named triggers—hydrogen infrastructure buildout pace, EU carbon border adjustment implementation, and China GB standard enforcement intensity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Warehouse Drums and Barrels Market
Industrial Materials
Heat-Insulation Boards for Industrial Equipment Market
Industrial Materials
Europe Wood Activated Carbon Market
Industrial Materials
Industrial Mixers Market
Industrial Materials
Lip Seals Market
Industrial Materials
North America Phenolic Insulation Market
Industrial Materials
Extruders and Compounding Machines Market
Industrial Materials
Cork Material Market
Industrial Materials
Static Mixer Market
Industrial Materials
Plain Bearing Market
Industrial Materials
Industrial Pails and Drums Market
Industrial Materials
Global Medical Plastics Extrusion Market
Industrial Materials
Wire Drawing Dies Market
Industrial Materials
Industrial Kiln Market
Industrial Materials
Gypsum Plaster Market
Industrial Materials
High Performance Random Packing Market