
 Paper Products Market | 2026-2036
Paper Products Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Products Market Intelligence
The EU Green Deal is hardening requirements for recyclable and fiber-based packaging across member states, compelling manufacturers to re-engineer product portfolios toward sustainable substrates. International Paper Company leverages its North American containerboard scale to supply e-commerce fulfillment networks with high-performance corrugated solutions. Smurfit Westrock plc anchors European demand through integrated paper-to-box operations spanning recycled fiber collection through finished packaging. Mondi plc differentiates via specialty kraft paper grades engineered for industrial wrapping and consumer goods applications.
Paper products encompass mechanically or chemically processed cellulose fibers formed into sheets for writing, packaging, hygiene, or industrial applications, with basis weights ranging from lightweight tissue below 20 gsm to heavy-duty corrugated board exceeding 300 gsm. Their primary purpose centers on information recording, product protection, sanitation, and material handling across commercial and consumer contexts. Tissue paper and cardboard command dominant volume positions, with tissue sustained by institutional hygiene mandates and cardboard expanding through e-commerce logistics demand. Specialty paper captures concentrated margin pools in filtration, electrical insulation, and pharmaceutical packaging where technical specifications command premium pricing.
EPA guidelines on recycled content in federal procurement shape US demand thresholds, while ECHA's REACH framework governs chemical inputs in European pulp processing. China's MEE enforces wastewater discharge standards that constrain small-scale mill operations and consolidate production capacity. BIS certification requirements in India mandate product testing for writing and printing paper sold to educational institutions. Stakeholders must monitor evolving extended producer responsibility frameworks that transfer end-of-life collection costs upstream to manufacturers and reshape competitive economics across regional markets.
Market Dynamics
E-commerce fulfillment networks are compressing order-to-delivery cycles, forcing containerboard producers to align production schedules with real-time inventory replenishment demands from automated distribution centers.
Growth Catalysts
- EU Green Deal packaging directives:Member states are mandating fiber-based alternatives to plastic substrates in consumer goods packaging, expanding addressable demand for kraft and corrugated grades.
- China's domestic e-commerce logistics:Massive consumption of containerboard by domestic fulfillment networks drives sustained volume expansion for linerboard and medium producers.
- Recycled fiber collection infrastructure:Investments in automated sorting and de-inking capacity are lowering input costs for integrated paper-to-box operations across North American and European markets.
Market Restraints
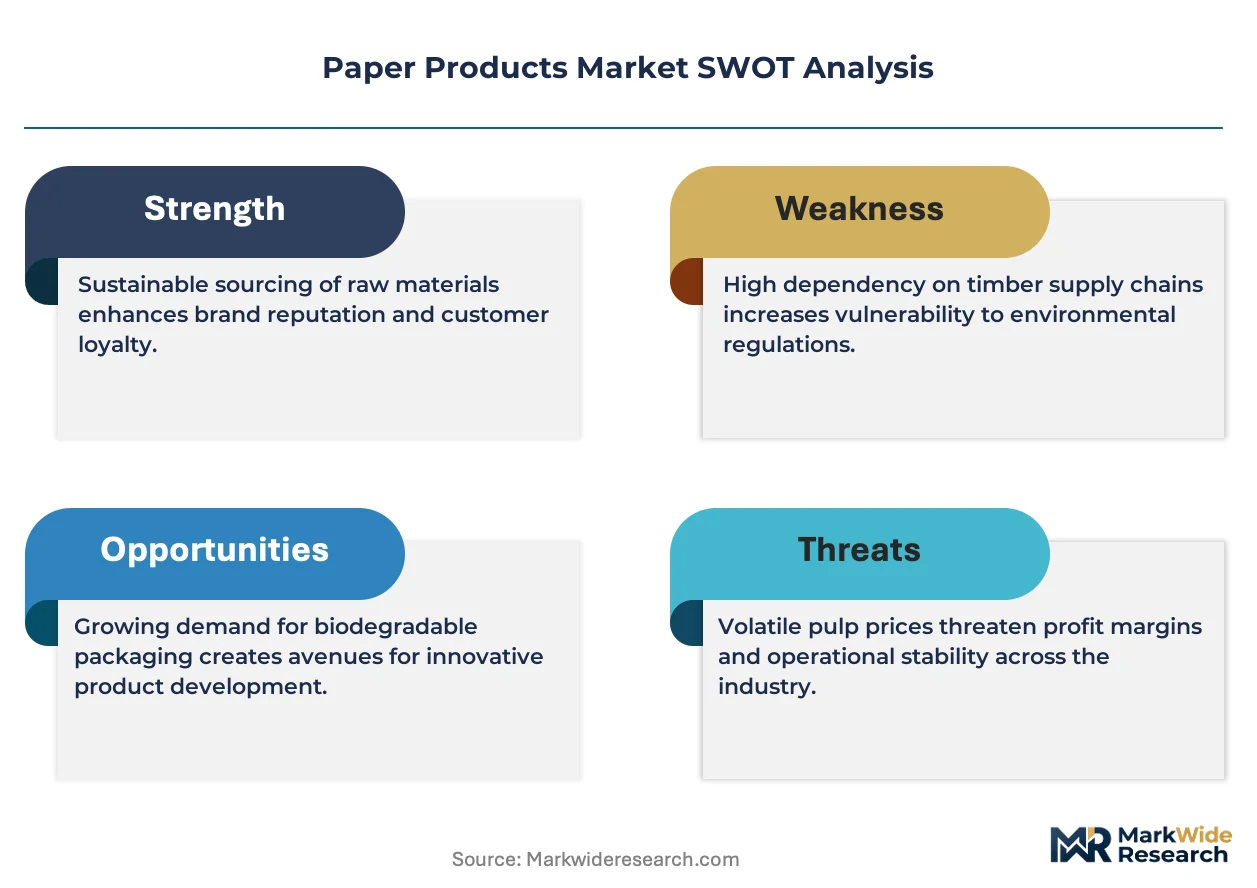
- Pulp price volatility:Softwood and hardwood pulp contracts fluctuate with Brazilian and Scandinavian supply disruptions, compressing margin predictability for non-integrated mills.
- China MEE wastewater standards:Stricter discharge limits on chemical oxygen demand and suspended solids are forcing capacity consolidation among small-scale regional producers.
- Digital substitution in information recording:Electronic documentation and cloud-based archiving are displacing writing and printing paper volumes in corporate and educational procurement.
Strategic Opportunities
- India's educational procurement expansion:BIS certification requirements for institutional paper supplies create captive demand pools for compliant domestic and import suppliers.
- Barrier-coated foodservice packaging:Oil and moisture-resistant kraft grades are penetrating quick-service restaurant and ready-meal segments previously served by plastic laminates.
- Extended producer responsibility frameworks:EU member state implementations of packaging waste fees are shifting end-of-life collection economics toward fiber-based solutions with established recycling pathways.
Industry Challenges
- De-inking and contamination control:Rising adhesive and plastic contamination in post-consumer fiber streams degrades pulp yield and increases chemical consumption at recycled mills.
- Legacy equipment retrofit timelines:Converting machines built for graphic paper grades require multi-year capital cycles to reconfigure for packaging and specialty paper production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Products Market |
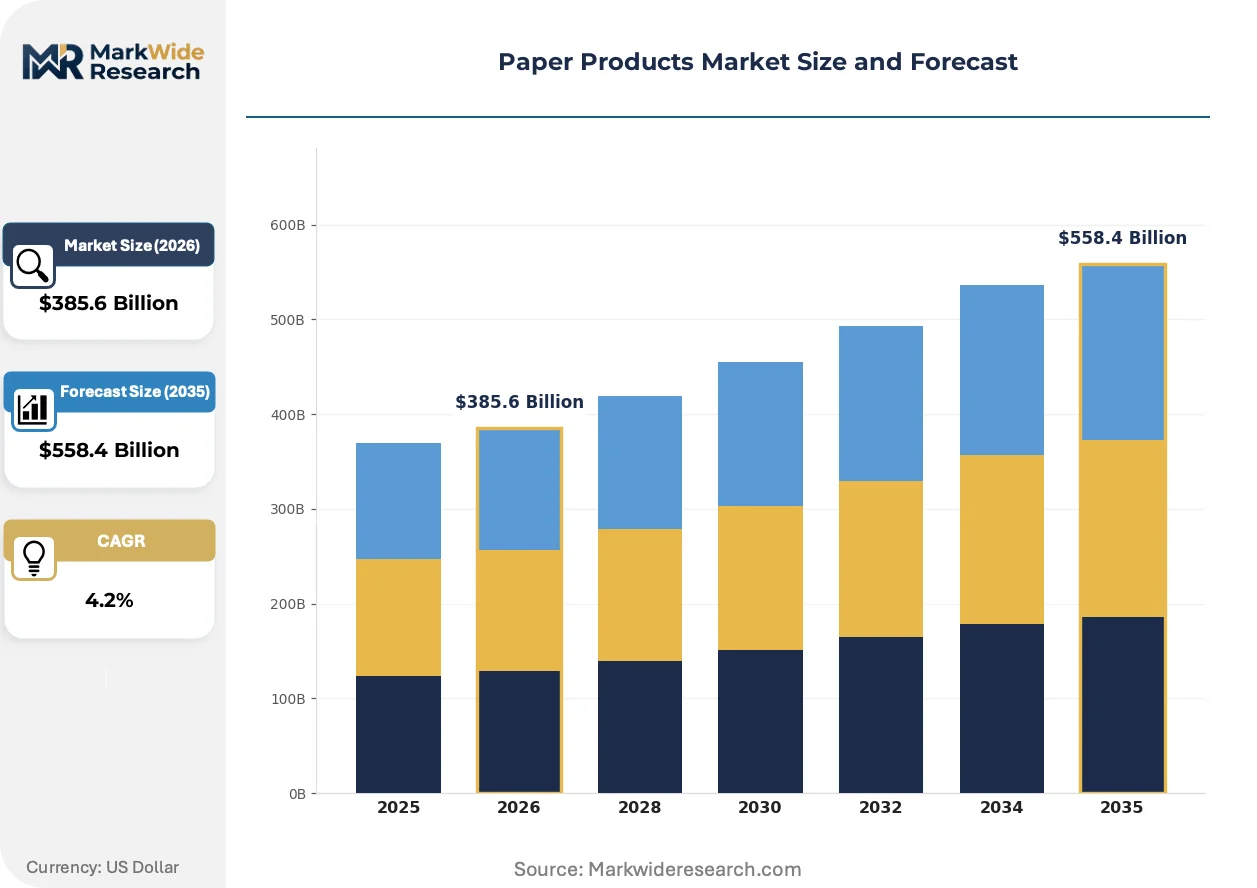
| Market Size in 2026 | $385.6 Billion |
| Market Size in 2035 | $558.4 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Writing Paper, Tissue Paper, Cardboard, Specialty Paper End User: Office Supplies, Educational Institutions, Food Service, Retail Packaging Distribution Channel: Direct Sales, Online Retail, Wholesale, Supermarkets Material: Recycled Paper, Virgin Fiber, Specialty Coated, Uncoated |
| Companies Covered | International Paper Company, Smurfit Westrock plc, Mondi plc, Packaging Corporation of America, Stora Enso Oyj, Kimberly-Clark Corporation, Oji Holdings Corporation, Nine Dragons Paper Holdings Ltd., UPM-Kymmene Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Products Market Strategic Shifts & Innovations
Digital printing and smart packaging technologies are collapsing minimum order quantities, enabling mass customization while compressing traditional economies of scale in long-run production.
Barrier coating chemistry is unifying grease resistance, moisture protection, and heat sealability into single-substrate foodservice packaging. Quick-service chains and meal-kit distributors are adopting these grades to eliminate plastic windows and liners. This unification is compressing the multi-material laminates segment and redirecting R&D spending toward bio-based coating formulations.
REACH framework amendments are tightening restrictions on per- and polyfluoroalkyl substances in food-contact paper. European converters are reformulating grease-resistant grades with plant-based alternatives or mineral oil barriers. The quick-service and bakery segments are most affected, with major chains accelerating supplier audits to preempt regulatory non-compliance.
Consolidation among e-commerce platforms is concentrating procurement leverage in fewer buying centers. Third-party logistics providers and direct-to-consumer brands are negotiating multi-year containerboard supply agreements with performance-based pricing clauses. This concentration is most visible in North American and Chinese markets, where fulfillment network density supports direct mill relationships bypassing traditional merchant distribution.
Paper Products Market Segmentation
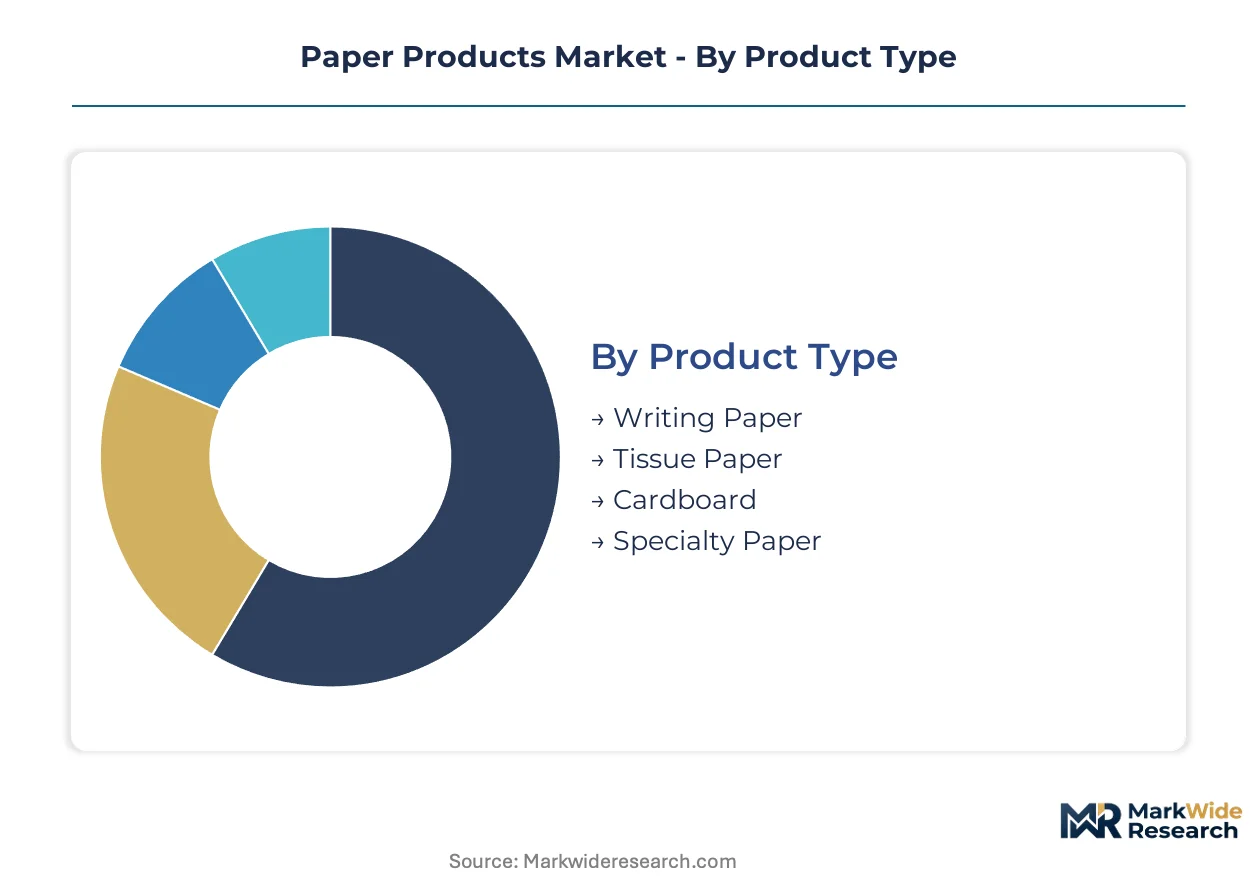
Paper products segmentation reveals how supply-side capabilities align with diverging demand patterns across hygiene mandates, e-commerce logistics, and regulatory-driven material substitution. Understanding these splits exposes where integrated mills command pricing power versus where merchant converters compete on service flexibility.
Product Type:
Supply concentration varies sharply across grades, with containerboard and tissue dominated by integrated producers while specialty paper remains fragmented among regional specialists.
- Cardboard:Containerboard and corrugated medium engineered for burst strength and crush resistance specifications. Demand concentrates in China's domestic e-commerce fulfillment networks where JD Logistics and SF Holding consume massive linerboard volumes for automated sortation systems. The EU Green Deal's packaging waste directives are accelerating fiber-based substitution for plastic shipping substrates.
- Tissue Paper:Lightweight creped sheets below 25 gsm basis weight, mechanically softened for absorbency and bulk. North American and European institutional procurement mandates sustain volume, though pulp price volatility compresses margin predictability for non-integrated mills reliant on spot market softwood pulp.
- Writing Paper:Sized wood-free sheets for inkjet and laser printing applications. Electronic documentation and cloud-based archiving are displacing corporate and educational procurement volumes.
- Specialty Paper:Engineered grades for filtration, electrical insulation, and pharmaceutical packaging where technical specifications command premium pricing. Barrier-coated foodservice variants are penetrating quick-service restaurant segments previously served by plastic laminates.
Today's leader: Cardboard. Tomorrow's challenger: Specialty Paper.
End User:
Application-specific performance requirements fragment procurement patterns, with institutional buyers prioritizing compliance certification while commercial users emphasize total delivered cost.
- Retail Packaging:Corrugated and folding carton grades for consumer goods protection and shelf presentation. Extended producer responsibility frameworks in EU member states are shifting end-of-life collection economics toward fiber-based solutions with established recycling pathways.
- Food Service:Grease-resistant kraft and molded pulp for quick-service restaurants and meal-kit distributors. REACH framework amendments tightening restrictions on per- and polyfluoroalkyl substances are forcing reformulation toward plant-based barrier coatings.
- Educational Institutions:Writing and printing paper for instructional materials and examination booklets. India's BIS certification requirements create captive demand pools for compliant domestic and import suppliers.
- Office Supplies:Copier paper, envelopes, and filing products for administrative operations. Digital substitution is compressing addressable demand as enterprises migrate to electronic documentation workflows.
Food Service is gaining share fastest as regulatory bans on single-use plastics redirect R&D spending toward bio-based coating formulations.
Distribution Channel:
Channel economics reflect order fragmentation patterns, with bulk direct sales sustaining integrated mill utilization while digital channels enable mass customization at compressed minimum order quantities.
- Direct Sales:Mill-direct containerboard and linerboard supply to integrated box plants and large corrugated converters. Consolidation among e-commerce platforms is concentrating procurement leverage in fewer buying centers negotiating multi-year supply agreements.
- Wholesale:Merchant distribution of commodity printing and writing grades to regional converters and jobbers. Rising adhesive and plastic contamination in post-consumer fiber streams degrades pulp yield and increases chemical consumption at recycled mills serving this channel.
- Online Retail:Digital platforms for specialty paper, custom stationery, and small-format packaging. Smart packaging technologies are collapsing minimum order quantities and enabling mass customization.
- Supermarkets:Consumer tissue and towel products through retail grocery channels. Private label penetration intensifies price competition against branded manufacturers.
Direct Sales currently dominates volume throughput. Online Retail shows the steepest expansion trajectory as digital printing technologies compress traditional economies of scale.
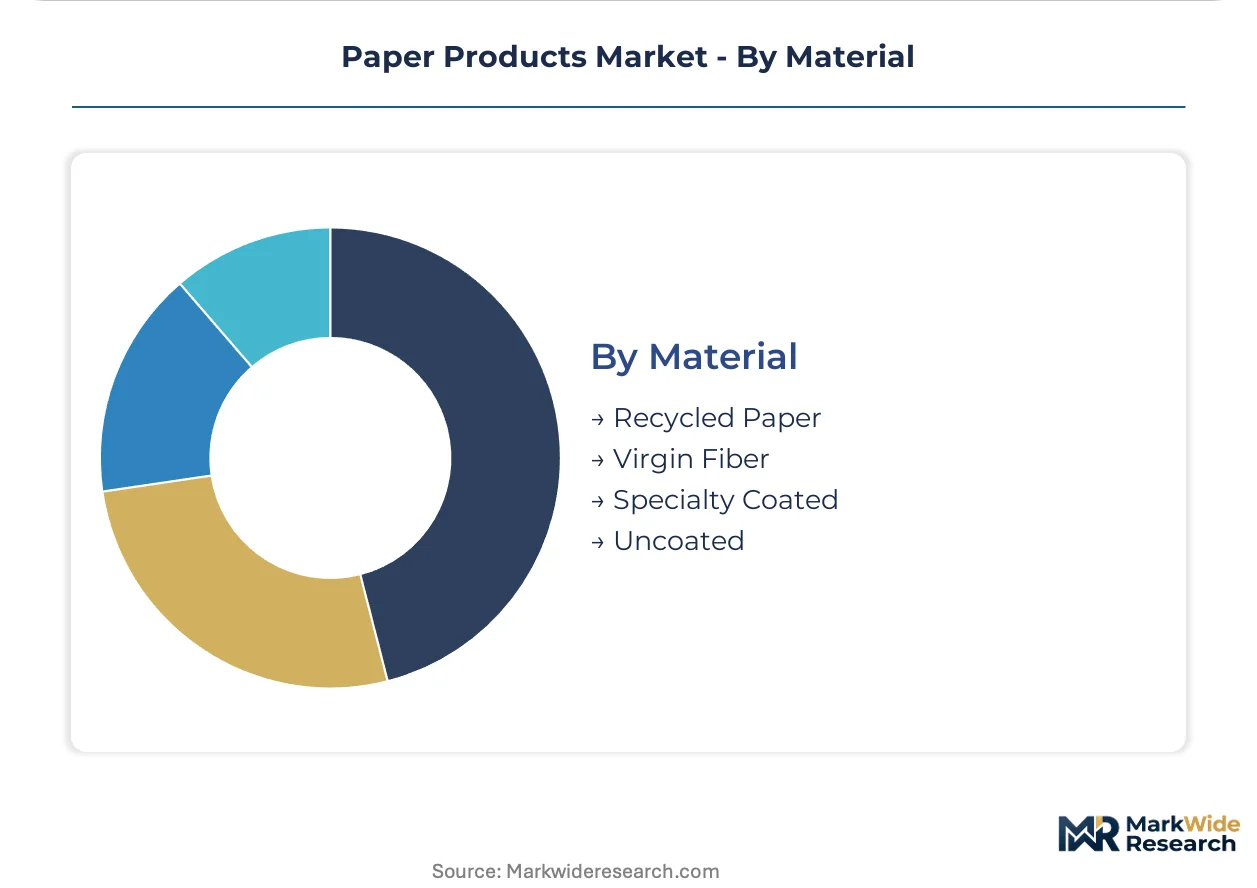
Material:
Input cost structures and regulatory compliance burdens diverge sharply between virgin fiber systems and recycled fiber operations, reshaping competitive economics across regional markets.
- Recycled Paper:Post-consumer fiber collected through municipal and commercial streams, processed through automated sorting and de-inking. Investments in contamination control infrastructure are lowering input costs for integrated paper-to-box operations across North American and European markets.
- Virgin Fiber:Softwood and hardwood pulp from managed timberlands, prized for strength and cleanliness in food-contact and medical applications. Brazilian and Scandinavian supply disruptions generate contract price volatility that compresses margin predictability.
- Specialty Coated:Clay, latex, or bio-based surface treatments for printability, barrier properties, or optical performance. Quick-service chains are accelerating supplier audits to preempt REACH non-compliance on perfluorinated substances.
- Uncoated:Unfinished sheets for writing, copying, and general packaging applications. Legacy equipment built for graphic paper grades requires multi-year capital cycles to reconfigure for packaging and specialty production.
Recycled Paper holds current volume leadership. Specialty Coated is climbing fastest as barrier chemistry unifies grease resistance, moisture protection, and heat sealability into single-substrate foodservice solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paper production originated in China during the Han Dynasty, establishing East Asia's millennia-long dominance in fiber processing. Modern capacity expansion now concentrates in manufacturing corridors where e-commerce logistics, regulatory mandates, and recycled fiber infrastructure intersect.
United States
Containerboard consumption surges from Amazon, Walmart, and Target fulfillment networks across the Southeast and Midwest. EPA procurement guidelines mandate minimum recycled content thresholds for federal agency purchases. Georgia-Pacific and International Paper operate massive integrated mills in the Atlanta-Tennessee corridor serving automated distribution centers.
China
Domestic e-commerce platforms JD.com and Pinduoduo drive linerboard demand through automated sortation systems. MEE wastewater discharge standards force consolidation among small-scale regional producers. Nine Dragons Paper anchors production in Guangdong and Jiangsu provinces with recycled fiber collection networks spanning coastal manufacturing zones.
Germany
EU Green Deal packaging directives accelerate fiber-based substitution for plastic substrates in consumer goods. ECHA REACH framework governs chemical inputs in pulp processing. Smurfit Westrock's integrated operations in the Rhineland and Bavaria span recycled fiber collection through finished corrugated packaging.
India
BIS certification requirements for writing and printing paper create captive demand pools for educational procurement. Central Pollution Control Board mandates tighten effluent standards for pulp mills along the Ganga basin. ITC and West Coast Paper operate major facilities in Karnataka and Maharashtra serving institutional buyers.
Japan
Specialty kraft paper grades penetrate industrial wrapping and precision packaging for automotive component exports. METI carbon neutrality targets drive mill energy efficiency investments. Oji Holdings and Nippon Paper maintain production clusters in Hokkaido and Kyushu with integrated forestry-to-pulp operations.
Paper Products Market Key Industry Players
Capital-heavy integrated mills compete with asset-light merchant converters across distinct value chain positions. The market structures around three tiers: global scale producers with captive fiber supply, regional specialists serving niche grades, and merchant distributors bridging fragmented end-user demand. Consolidation accelerates through mill acquisitions and box plant integration. Portfolio diversification into barrier-coated foodservice grades represents the dominant competitive maneuver alongside geographic expansion into high-growth Asian logistics corridors.
Within the integrated producer tier, International Paper Company exemplifies North American containerboard scale, while Smurfit Westrock plc anchors European demand through paper-to-box operations. Mondi plc occupies a position as specialty kraft paper specialists, differentiating via engineered grades for industrial and consumer applications. These three represent the archetypal strategies: fiber security through vertical integration, geographic density in high-demand corridors, and technical specification leadership in premium segments.
| Leading Market Players |
|---|
| International Paper Company |
| Smurfit Westrock plc |
| Mondi plc |
| Packaging Corporation of America |
| Stora Enso Oyj |
| Kimberly-Clark Corporation |
| Oji Holdings Corporation |
| Nine Dragons Paper Holdings Ltd. |
| UPM-Kymmene Oyj |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap mills across Scandinavia and the American Southeast anchor recycled fiber collection networks, translating captive pulp supply into pricing discipline that resists spot market volatility. Their ownership structures prioritize long-term fiber security over quarterly margin optimization, compressing price competition in containerboard grades while amplifying cost pass-through power when softwood pulp contracts fluctuate.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments containerboard by burst strength certification and recycled content percentage. Price differentiation hinges on FSC chain-of-custody certification and volume scale commitments from e-commerce fulfillment networks. Cost compression in standard grades is intensifying because Brazilian hardwood pulp supply disruptions feed into linerboard input costs. Quick-service restaurant chains show least price sensitivity for barrier-coated foodservice grades, while merchant converters serving educational institutions exhibit highest sensitivity to basis weight pricing.
Supply Chain Analysis
Freight cost differentials between coastal mill locations and inland distribution centers dictate procurement radius for corrugated converters serving Amazon and Walmart fulfillment networks. Supply concentrates in China, the United States, and Germany, with containerboard capacity clustering near major e-commerce logistics corridors. Raw material flows draw from post-consumer fiber collection systems, Brazilian eucalyptus pulp, and Scandinavian softwood. Single-source vulnerability runs through China's MEE-mandated mill consolidation, which threatens regional linerboard availability. Distribution runs through direct mill relationships with integrated box plants, bypassing traditional merchant channels in high-volume corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between EU Green Deal-mandated fiber substitution and China's wastewater-driven capacity consolidation creates margin capture opportunities for producers with cross-border logistics capabilities. Regulatory cost differentials favor integrated mills operating in jurisdictions with established extended producer responsibility frameworks.
For Market Incumbents: Deploy barrier-coated foodservice grade expansion to preempt REACH restrictions on perfluorinated substances in quick-service packaging. Consolidate recycled fiber collection infrastructure in the American Southeast to defend against pulp price volatility from Brazilian supply disruptions. Backward integration into de-inking capacity lowers input costs while tightening contamination control.
For New Entrants and Emerging Players: Launch via digital printing platforms serving customized short-run packaging for direct-to-consumer brands. India's BIS-certified educational paper procurement represents the most penetrable white-space target, with institutional mandates creating captive demand pools. Specialty kraft grades for industrial wrapping offer entry with lower capital intensity than containerboard scale.
For Investors and Strategic Acquirers: Valuations sit cheapest among non-integrated merchant converters facing legacy equipment retrofit burdens for packaging grade conversion. Long-term viability across the analysis window favors producers with in-house pulp supply and established recycling pathways. Watch EU member state implementations of packaging waste fees as the signal for accelerated fiber-based substitution economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber Collection | Captive pulp supply insulates margin from Brazilian hardwood price volatility. |
| Barrier-Coated Foodservice Grade Expansion | REACH amendments on perfluorinated substances redirect quick-service procurement toward compliant suppliers. |
| Digital Printing Platform Deployment | Mass customization capabilities compress minimum order quantities for direct-to-consumer brands. |
| Direct Mill Relationships with Fulfillment Networks | Amazon and JD Logistics procurement concentration rewards bypassing merchant distribution layers. |
| Geographic Expansion into India Educational Procurement | BIS certification requirements create institutional demand pools with import compliance barriers. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's major production corridors. Primary interviews with mill operations directors, corrugated converter procurement heads, e-commerce logistics planners, and regulatory compliance officers combined with secondary validation from EPA procurement databases, ECHA REACH substance registrations, China MEE discharge filings, and customs trade records. Bottom-up capacity utilization data triangulated against top-down e-commerce packaging demand estimates.
Rate-of-change decomposition separates volume growth into e-commerce logistics expansion, regulatory-driven material substitution, and digital displacement effects across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use application, distribution channel structure, and fiber input type. CAGRs derive from correlated regression against e-commerce transaction velocity and pulp contract price indices. Forecast inputs incorporate EU Green Deal implementation timelines and China MEE enforcement intensity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under pulp supply disruption scenarios or accelerated digital substitution in educational procurement. Forecasts reflect assumptions about regulatory enforcement consistency and e-commerce fulfillment network expansion rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
White Top Testliner Market
Paper Products
White Line Chipboard Market
Paper Products
Pulp and Paper Chemicals Market
Paper Products
Recording Chart Paper Market
Paper Products
GCC Paper Products Market
Paper Products
Canada Honeycomb Paper Market
Paper Products
Paper Dry Strength Agents Market
Paper Products
Solid Bleached Sulfate (SBS) Board Market
Paper Products
Organic Tissue Paper Market
Paper Products
Pulp and Paper Market
Paper Products
Sanitary Paper Products Market
Paper Products
High-Speed Production Inkjet Printer Paper Market
Paper Products
Bleached Softwood Kraft Pulp Market
Paper Products
Clay Coated Paper Market
Paper Products
Decor Paper Market
Paper Products
Pp Synthetic Paper Market