
 BPA Free Thermal Paper Market | 2026-2036
BPA Free Thermal Paper Market Size, Share, and Industry Trends Forecast 2026-2036
BPA Free Thermal Paper Market Outlook
Multi-source procurement for thermal paper coatings is expanding as converters seek supply resilience against raw material volatility. Koehler Paper Group leverages integrated pulp-to-paper operations to secure coating chemical supply chains. Mitsubishi Paper Mills anchors its position through R&D intensity in phenol-free developer systems. Appvion Operations, Inc. competes on specialized coating capabilities for high-speed printing environments.
BPA free thermal paper substitutes bisphenol A with alternative developers such as urea-based compounds, ascorbic acid derivatives, or Pergafast systems in a thermal-sensitive coating applied to base paper; this coating reacts with thermal print heads to produce durable images without exposing handlers to endocrine-disrupting chemicals. The product type dimension shows rolls dominating volume throughput in high-frequency retail and logistics settings while specialty products command margin pools in healthcare and custom ticketing applications. End user demand concentrates in retail point-of-sale and logistics labeling, where regulatory pressure intersects with high daily touch volumes.
REACH restrictions across Europe and FDA guidance under the Federal Food, Drug, and Cosmetic Act in the United States directly shape product formulation standards and market access conditions for thermal paper imports. ECHA's inclusion of BPA on the candidate list of substances of very high concern has accelerated reformulation timelines throughout the supply chain. Stakeholders must monitor evolving state-level prohibitions in the US and forthcoming GB standard revisions in China to anticipate compliance-driven procurement shifts.
Market Dynamics
REACH restrictions on endocrine-disrupting chemicals are forcing thermal paper converters to abandon legacy BPA formulations entirely, triggering a supply chain reconfiguration toward phenol-free developer systems.
Growth Catalysts
- Retail POS conversion:High-frequency retailers across Germany and France are replacing legacy receipt paper to comply with ECHA candidate list restrictions on substances of very high concern.
- Ascorbic acid chemistry:Improved image stability in vitamin C-based thermal coatings is expanding application scope into healthcare patient wristbands and prescription labeling.
- Logistics labeling demand:E-commerce fulfillment centers require BPA-free shipping labels to meet corporate ESG procurement mandates and worker safety protocols.
Market Restraints
- Leuco dye input volatility:Specialized dye intermediates for urea-based developers face supply concentration among Asian chemical manufacturers, creating price instability.
- Technical image durability gap:Phenol-free coatings still exhibit shorter archival lifespans than legacy BPA systems in high-temperature storage conditions.
- Substitution threat:Digital receipt adoption via smartphone apps and email delivery is compressing addressable volume in premium retail segments.
Strategic Opportunities
- Healthcare expansion:Hospital systems in Switzerland and Austria are mandating BPA-free patient identification materials, opening specialty margin pools.
- Custom ticketing applications:Event venues and transportation operators seek durable phenol-free thermal stock for high-heat outdoor environments.
- Regulatory tailwind:Anticipated GB standard revisions in China will force export-oriented thermal paper mills to adopt BPA-free formulations for cross-border compliance.
Industry Challenges
- Coating equipment reconfiguration:Converters must retrofit existing thermal coating lines to handle alternative developer chemistries with different viscosity and drying profiles.
- Certification timeline compression:ECHA SVHC list updates require rapid reformulation validation, straining R&D bandwidth at mid-size paper mills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BPA Free Thermal Paper Market |
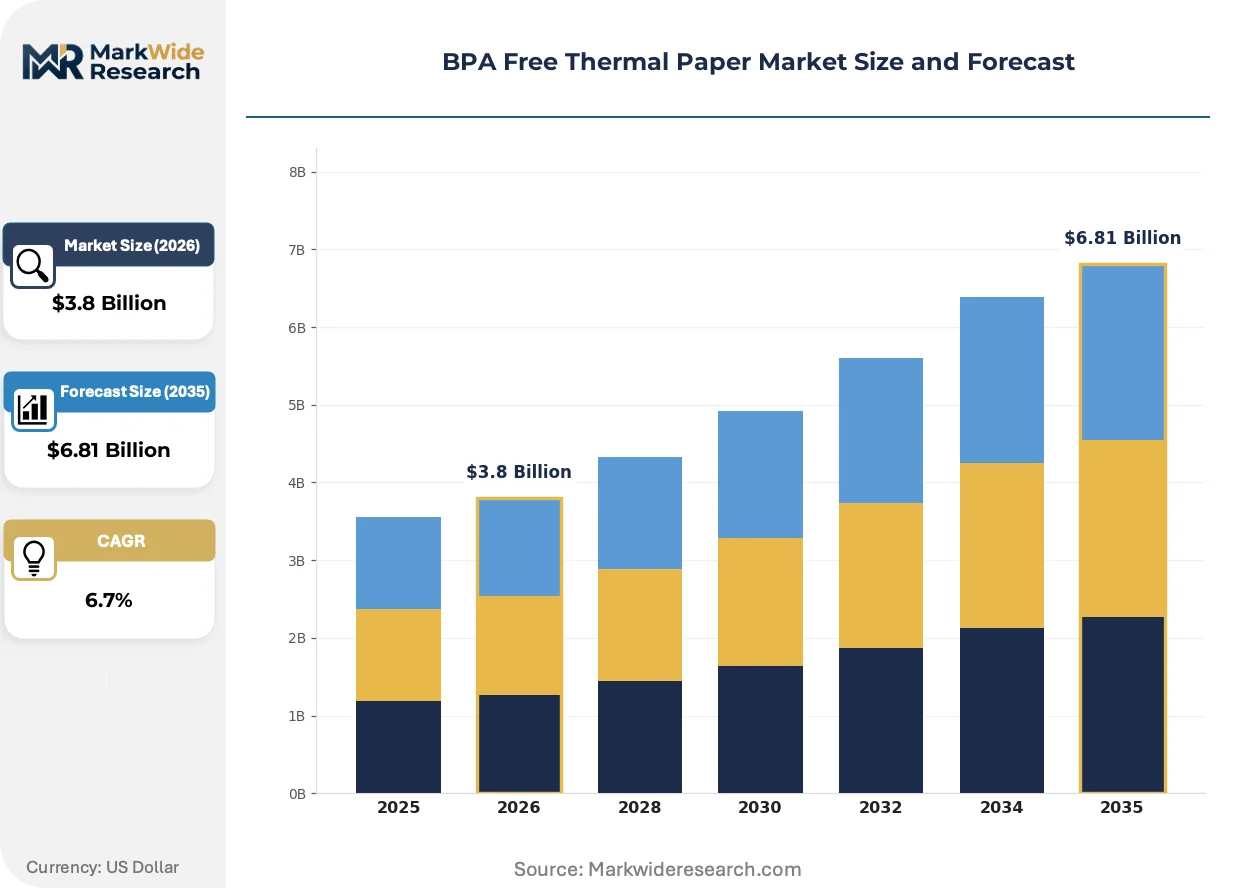
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rolls, Sheets, Specialty Products, Custom Sizes End User: Retail, Hospitality, Logistics, Healthcare Application: Point of Sale, Labeling, Ticketing, Printing Solutions Distribution Channel: Online, Retail Stores, Wholesale, Direct Sales |
| Companies Covered | Koehler Paper Group, Mitsubishi Paper Mills, Appvion Operations, Inc., Oji Paper, Ricoh Company, Ltd., Hansol Paper Co., Ltd., Iconex LLC, Nippon Paper Industries, Shandong Chenming Paper Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BPA Free Thermal Paper Market Strategic Shifts
Phenol-free developer chemistry is advancing through three distinct vectors: molecular innovation in coating compounds, regulatory acceleration across multiple jurisdictions, and procurement model evolution favoring certified supply chains.
Pergafast systems based on urea-urethane chemistry are rewriting competitive positioning in high-speed printing environments. Major logistics operators in the Netherlands and Belgium have adopted these coatings for automated sorting facilities. The technology is compressing the performance gap between BPA-free and legacy thermal systems in demanding industrial settings.
REACH candidate list expansion is mandating systematic chemical inventory reviews across European thermal paper importers. ECHA's 2023-2024 updates to SVHC classification have triggered batch testing requirements at port of entry. German retailers are responding by demanding full formulation disclosure from coating suppliers upstream.
Corporate ESG procurement mandates are displacing price-only sourcing in retail and healthcare verticals. Buyers now require third-party BPA-free certification as a table-stakes qualification, not a premium feature. This pattern concentrates most visibly in Scandinavian markets where institutional purchasing guidelines embed chemical safety protocols.
BPA Free Thermal Paper Market Segmentation
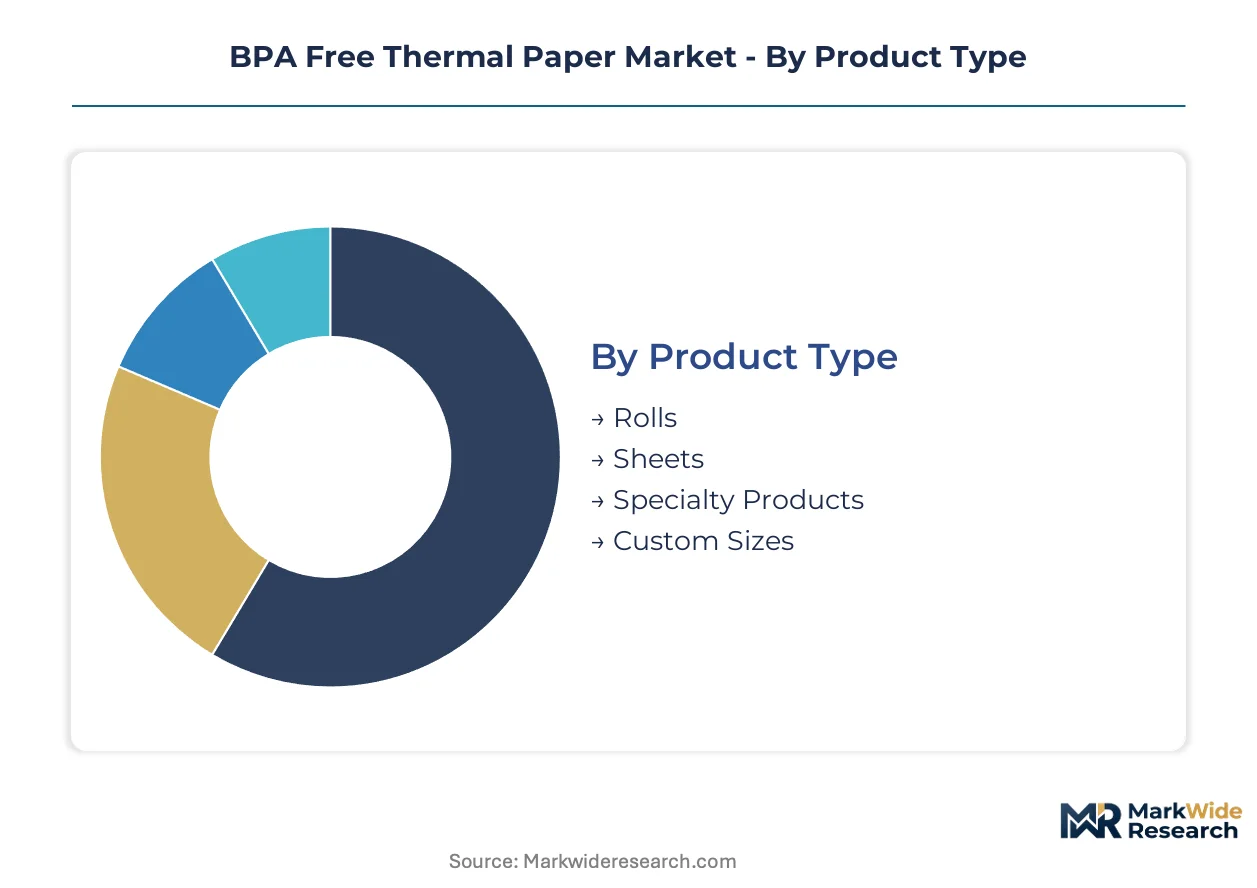
BPA-free thermal paper segments diverge sharply in certification burden, with healthcare and food-contact applications demanding REACH SVHC documentation while retail POS prioritizes volume throughput. Understanding these tiered compliance requirements illuminates where margin pools concentrate versus where scale economics dominate procurement decisions.
Product Type:
Certification burden escalates from standard roll formats, where ECHA compliance documentation suffices, through specialty products requiring FDA food-contact notification or Swissmedic medical device material certification.
- Rolls:Continuous web formats dominate high-frequency retail POS and automated logistics labeling installations. German supermarket chains and French hypermarkets drive volume demand as ECHA SVHC restrictions force systematic paper stock replacement across thousands of checkout lanes.
- Specialty Products:Pre-cut wristbands, prescription labels, and medical imaging tags incorporate phenol-free coatings with enhanced moisture resistance. Hospital systems in Switzerland and Austria mandate these formats for patient identification, creating margin premiums tied to biocompatibility testing documentation.
- Sheets:Fan-fold and cut-sheet formats serve intermittent-use environments like small hospitality operators and mobile payment terminals.
- Custom Sizes:Non-standard widths and lengths address legacy equipment retrofits and specialized printing machinery in industrial settings.
Rolls sit at the top of the volume ranking, with specialty products climbing the fastest.
End User:
Cost tier stratification separates high-touch retail environments, where paper costs amortize across transaction volume, from healthcare settings where material safety documentation commands price premiums independent of sheet economics.
- Retail:Supermarkets, convenience stores, and specialty merchants constitute the primary demand base for standard thermal rolls. E-commerce fulfillment centers in the Netherlands and Belgium now specify BPA-free shipping labels to satisfy corporate ESG procurement mandates.
- Healthcare:Hospitals, pharmacies, and diagnostic laboratories require patient wristbands, prescription labels, and specimen tags with full formulation disclosure. Swissmedic guidance on endocrine-disrupting chemical exposure drives adoption of urea-based developer systems in Alpine healthcare networks.
- Logistics:Parcel carriers and warehousing operators utilize thermal labels for automated sorting and inventory tracking.
- Hospitality:Restaurants, hotels, and entertainment venues deploy receipt paper and guest identification materials.
Retail commands absolute volume leadership, while healthcare expands most quickly on a percentage basis.
Application:
Application maturity determines whether phenol-free coatings must match legacy BPA archival performance or merely satisfy immediate-use durability requirements.
- Point of Sale:Receipt printing at retail checkout represents the most standardized use case, with image stability requirements measured in weeks rather than years. French retailers under ANSM consumer protection oversight have accelerated POS paper replacement schedules.
- Labeling:Shipping labels, inventory tags, and asset tracking materials face mechanical stress during automated handling. Pergafast urea-urethane coatings are gaining share in high-speed Belgian distribution centers where smudge resistance determines operational efficiency.
- Ticketing:Event admission and transit passes require thermal stability across outdoor temperature ranges.
- Printing Solutions:Mobile printers and specialty imaging equipment utilize custom-coated stocks.
Point of Sale maintains volume dominance, with labeling gaining share fastest.
Distribution Channel:
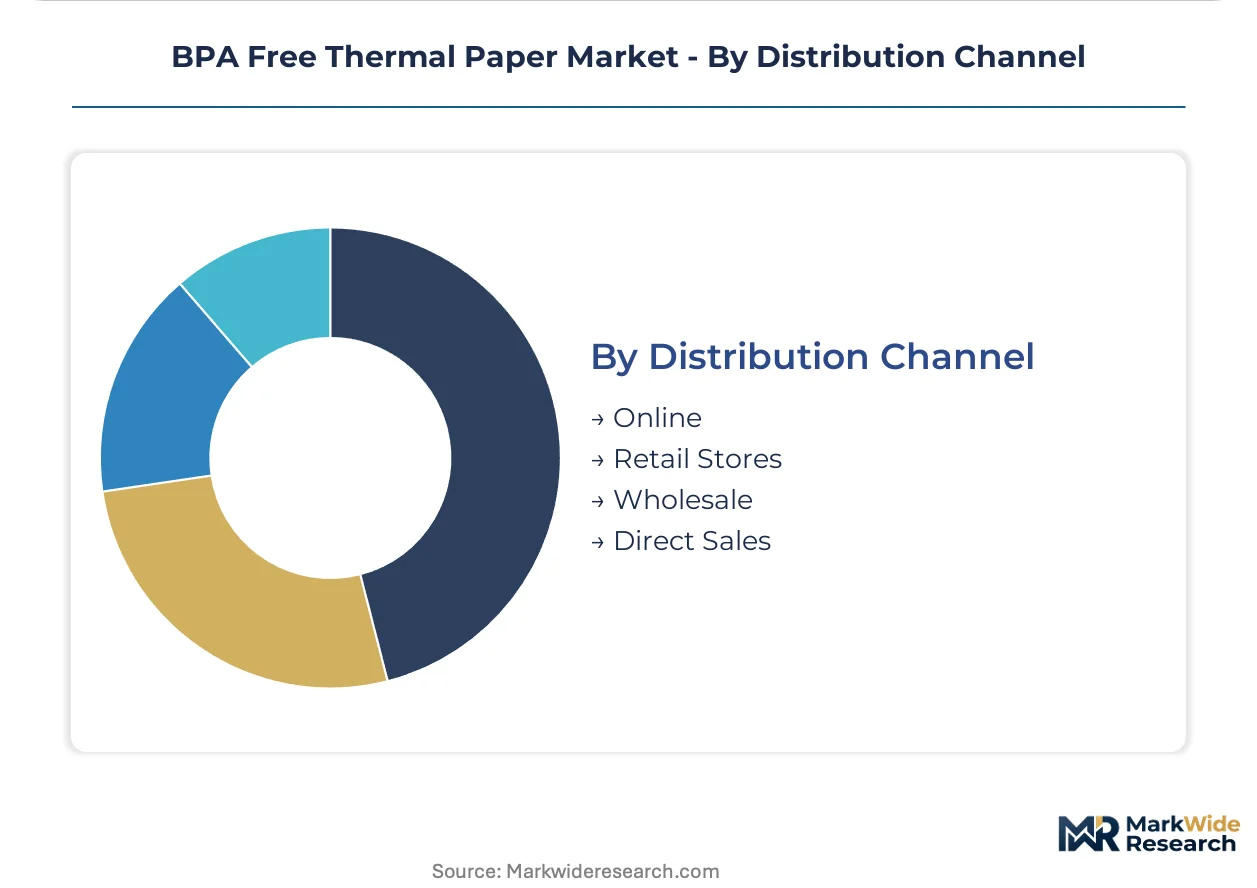
Customer type and order scale dictate channel selection, with enterprise procurement offices consolidating purchases through direct contracts while fragmented small merchants rely on wholesale intermediaries.
- Wholesale:Paper merchants and industrial distributors aggregate demand from mid-size retail chains and regional logistics operators. German wholesalers now stock exclusively REACH-compliant thermal paper grades following Federal Institute for Risk Assessment guidance.
- Direct Sales:Major retail conglomerates and healthcare systems negotiate multi-year supply agreements with coating mills. Koehler Paper Group and Mitsubishi Paper Mills anchor this channel through integrated pulp-to-paper operations that guarantee formulation consistency.
- Online:E-procurement platforms serve small merchants and replacement-stock buyers.
- Retail Stores:Office supply and electronics retailers stock consumer-format thermal paper for immediate purchase.
Wholesale channels handle the greatest tonnage, with direct sales expanding most rapidly among enterprise accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as thermal paper converters migrate coating operations toward jurisdictions with harmonized chemical safety standards, reducing compliance fragmentation costs while maintaining access to premium European and North American markets.
Germany
Federal Institute for Risk Assessment guidance drives supermarket chains toward systematic BPA-free receipt paper replacement. ECHA SVHC list updates mandate rapid reformulation validation across coating supply chains. The Rhine-Main industrial corridor hosts integrated pulp-to-paper operations securing coating chemical supply resilience.
United States
FDA guidance under the Federal Food, Drug, and Cosmetic Act shapes thermal paper imports for food-contact applications. State-level prohibitions on endocrine-disrupting chemicals accelerate procurement shifts in California and New York retail markets. Midwestern logistics hubs specify BPA-free shipping labels to satisfy corporate ESG mandates.
China
Anticipated GB standard revisions will force export-oriented thermal paper mills toward BPA-free formulations for cross-border compliance. Dual carbon goals pressure coating manufacturers to reduce process emissions. Yangtze River Delta concentration of specialty chemical production supplies urea-based developer intermediates.
Switzerland
Swissmedic guidance on endocrine-disrupting chemical exposure drives hospital systems toward BPA-free patient identification materials. Alpine healthcare networks mandate full formulation disclosure for prescription labeling and wristband applications. Basel pharmaceutical cluster procurement embeds chemical safety protocols in institutional purchasing guidelines.
Netherlands
Belgian and Dutch distribution centers adopt Pergafast urea-urethane coatings for automated sorting facilities. Rotterdam logistics corridor operators specify smudge-resistant phenol-free thermal stock for high-speed handling environments. National chemical safety frameworks align with REACH SVHC restrictions, eliminating regulatory friction for EU market access.
BPA Free Thermal Paper Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized coating capabilities for healthcare and high-durability applications. Market structure consolidates around integrated pulp-to-paper operators with captive chemical supply, mid-size converters with flexible coating lines, and regional specialists serving niche certification requirements. Dominant competitive moves include backward integration into developer chemistry production and geographic expansion through distribution partnerships in regulated European markets.
Among German integrated producers, Koehler Paper Group exemplifies the upstream-control archetype through captive pulp and coating chemical operations. Mitsubishi Paper Mills occupies a position representing R&D-intensive phenol-free developer system specialization. Appvion Operations, Inc. sits within the high-speed printing capability tier, anchoring industrial-format coating expertise.
| Leading Market Players |
|---|
| Koehler Paper Group |
| Mitsubishi Paper Mills |
| Appvion Operations, Inc. |
| Oji Paper |
| Ricoh Company, Ltd. |
| Hansol Paper Co., Ltd. |
| Iconex LLC |
| Nippon Paper Industries |
| Shandong Chenming Paper Holdings |
| Others |
Value Chain & Pricing Dynamics
Coating chemistry specialists concentrated in Germany's Rhine-Main corridor and Japan's Kanto region command wage premiums that compress margin spreads between economy-grade retail rolls and certified healthcare stock. Labor-cost differentials between integrated pulp-to-paper operators and merchant converters translate directly into pricing-tier stratification across REACH-compliant and standard-grade product lines.
Pricing Analysis
Distributor margin layers absorb certification documentation costs before product reaches fragmented retail merchants, while direct-to-OEM channels for major supermarket chains negotiate volume discounts off list. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and formulation disclosure depth. Cost compression in economy-grade retail rolls is intensifying because Asian merchant converters are flooding European wholesale channels with minimally compliant stock. Small hospitality operators and mobile payment terminal users exhibit highest price sensitivity, whereas Swiss hospital systems purchasing patient wristband materials show minimal elasticity tied to biocompatibility documentation requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German supermarket chains and French hypermarkets, while wholesale distributors aggregate fragmented mid-size retail demand. Geographic supply concentrates in Germany, Japan, and China, with coating chemical production anchored in the Yangtze River Delta and Kanto industrial belt. Raw material dependencies center on urea-based developer intermediates, leuco dye compounds, and specialty pulp grades. Single-source vulnerability in Asian chemical manufacturers for leuco dye inputs creates price instability risk. Distribution runs through paper merchants and industrial distributors serving regional logistics operators and retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where ECHA SVHC list expansion mandates systematic reformulation, converting compliance costs into structural demand for certified supply chains.
For Market Incumbents: Lock in coating chemical supply through backward integration into urea-based developer production or long-term offtake agreements with Rhine-Main specialty chemical producers. Digital receipt adoption via smartphone apps threatens volume in premium retail segments; defend position by embedding formulation disclosure services into direct sales contracts with major healthcare systems.
For New Entrants and Emerging Players: Enter via healthcare patient identification materials in Switzerland and Austria, where Swissmedic guidance creates certification barriers that filter out commodity converters. Custom ticketing for high-heat outdoor environments represents the most penetrable application segment. Pursue white-label coating partnerships with established paper merchants lacking in-house phenol-free formulation capability.
For Investors and Strategic Acquirers: Integrated paper producers with captive pulp operations are the most active acquirer in this space, seeking coating technology to complete vertical control. Long-term viability hinges on regulatory trajectory rather than cyclical demand; target merchant converters with flexible coating lines and existing REACH documentation infrastructure. Watch ECHA candidate list update frequency as the signal indicating reformulation urgency and replacement demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Developer Chemistry | Captive supply of urea-based compounds insulates Koehler Paper Group from Asian dye intermediate volatility. |
| Healthcare Certification Investment | Swissmedic-aligned biocompatibility documentation unlocks margin premiums in Alpine hospital procurement. |
| High-Speed Coating Capability Expansion | Pergafast system deployment positions converters for Dutch and Belgian automated logistics contracts. |
| Direct Sales Channel Deepening | Multi-year supply agreements with German retail conglomerates reduce exposure to wholesale price erosion. |
| Regulatory Monitoring Infrastructure | Dedicated ECHA SVHC tracking capabilities compress reformulation validation timelines for mid-size mills. |
Study Parameters
Direct dialogue with thermal paper coating mill technical directors, retail chain procurement officers, German wholesale distributors, and ECHA regulatory affairs consultants grounded qualitative assessment in operational reality. Secondary validation drew from REACH SVHC candidate list updates, BfR guidance documents, customs trade data for thermal paper imports, and SEC filings from listed paper producers. Bottom-up volume estimates from end-user segment interviews triangulated against top-down coating capacity assessments across integrated producers.
Segment-level demand projections across product type, end user, application, and distribution channel dimensions fed into analytical framework spanning the projection horizon. CAGRs emerged from regression analysis against regulatory milestone timing and replacement cycle assumptions. Model inputs incorporated ECHA SVHC list expansion velocity, coating line retrofit lead times, and digital receipt substitution rates in premium retail segments.
The model holds under steady regulatory enforcement intensity and stable coating chemistry innovation pace; deviation in ECHA acceleration or breakthrough digital receipt adoption would shift volume trajectories. Forecasts reflect base-case assumptions about REACH alignment in GB standards and sustained corporate ESG procurement mandates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Global Thin Papers Market
Paper Products
North America Specialty Paper Market
Paper Products
Uncoated Fine Paper Market
Paper Products
White Top Testliner Market
Paper Products
Duplex Paper and Board Market
Paper Products
Recording Chart Paper Market
Paper Products
Unbleached Softwood Kraft Pulp Market
Paper Products
Drum Pulper Market
Paper Products
Insulation Paper Market
Paper Products
Global Security Paper Market
Paper Products
Industrial Paper Shredder Machine Market
Paper Products
Office Printing Papers Market
Paper Products
Asia-Pacific Thermal Paper Market
Paper Products
GCC Paper Products Market
Paper Products
Global Cellulose Sponge Market
Paper Products
Graphic Paper Market