
 Probiotics for Kids Market | 2026-2036
Probiotics for Kids Market Size, Share, and Industry Trends Forecast 2026-2036
Probiotics for Kids Market Insights
The gap between premium clinically validated strains and commodity shelf-stable formulations is expanding as parents and pediatricians demand strain-specific efficacy documentation. Culturelle leverages its Lactobacillus rhamnosus GG heritage to dominate pharmacy and e-commerce channels. BioGaia AB anchors the medical-grade segment through hospital and clinic partnerships. Danone competes with broad dairy-based delivery systems that sustain repeat purchase through familiar consumption rituals.
Probiotics for kids comprise live microbial preparations, typically delivering colony-forming units in the billions, formulated for gastrointestinal colonization and immune modulation in developing microbiomes. These products undergo lyophilization or microencapsulation to preserve viability through shelf storage and gastric transit, serving primary purposes of diarrhea prevention, antibiotic-associated side effect reduction, and atopic condition management. Powder formats lead volume through formula and beverage mixing convenience, while chewable tablets command margin pools from school-age children seeking autonomy in supplement routines. Immune support applications grow fastest as post-pandemic parental concern elevates preventive health spending. Daycare centers represent an emerging channel where institutional procurement patterns diverge sharply from retail purchasing.
The FDA oversees dietary supplement Good Manufacturing Practices that constrain label claims and strain identity verification for children's products. The European Food Safety Authority's health claims framework restricts promotional language around immune and digestive benefits, forcing reformulation toward qualified indications. Australia's Therapeutic Goods Administration imposes additional safety thresholds for pediatric populations that shape export strategies. Stakeholders must monitor evolving strain-specific approval pathways as regulators distinguish between generic probiotic categories and clinically substantiated live biotherapeutic products.
Market Dynamics
Strain-specific efficacy documentation is forcing manufacturers to choose between premium clinical validation investments and commodity positioning, compressing mid-tier offerings as pediatricians demand peer-reviewed substantiation for every colony-forming unit claim.
Growth Catalysts
- Antibiotic stewardship programs:Pediatric clinics across the United States are expanding probiotic co-dispensing protocols to reduce antibiotic-associated diarrhea incidence. Hospital formulary committees now prioritize documented Lactobacillus and Bifidobacterium strains.
- EFSA's evolving qualified health claims pathway:The European framework's 2024 guidance on pediatric immune function claims creates regulatory clarity for substantiated formulations. Manufacturers with completed clinical trials gain accelerated market access.
- Microencapsulation advances:Spray-drying and lipid-coating technologies now preserve viability through gastric transit without refrigeration. Direct-to-consumer subscription models leverage these shelf-stable formats for last-mile delivery optimization.
Market Restraints
- Live culture supply concentration:Three contract fermentation facilities in Denmark and Switzerland control over 60% of high-potency pediatric strain production. Capacity constraints create 12-18 month lead times for new entrants.
- FDA enforcement uncertainty:The agency's 2023 warning letters targeting unqualified disease claims for children's probiotics have chilled marketing investment. Legal review cycles now extend campaign launches by 4-6 months.
- Stability testing costs:Accelerated shelf-life validation for multi-strain formulations requires 24-month real-time studies. Early-stage companies face $400,000-$600,000 per SKU in stability program expenditures.
Strategic Opportunities
- Daycare institutional procurement:Licensed childcare centers in California, New York, and Texas represent untapped volume. Group purchasing organizations are piloting daily probiotic powder programs for illness reduction.
- TGA pediatric safety framework harmonization:Australia's Therapeutic Goods Administration is aligning with US FDA standards for children's live biotherapeutics. Export-ready manufacturers can access both markets with unified dossiers.
- Digital therapeutics convergence:Microbiome testing kits paired with strain-matched probiotics create personalized protocols. Telehealth pediatric platforms are white-labeling these integrated offerings.
Industry Challenges
- Strain banking and IP fragmentation:Patent thickets around human-derived isolates force licensing negotiations with academic institutions. Freedom-to-operate analyses now consume 15-20% of R&D legal budgets.
- Pediatric trial recruitment:Parental consent requirements and ethics board variability across US states extend clinical study timelines. Sites in Florida and Arizona outperform Northeastern states by 40% in enrollment velocity.
- Quality control workforce scarcity:cGMP-compliant microbiologists with pediatric formulation experience command 35% salary premiums. Contract manufacturers report 6-month vacancies in analytical method development roles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Probiotics for Kids Market |
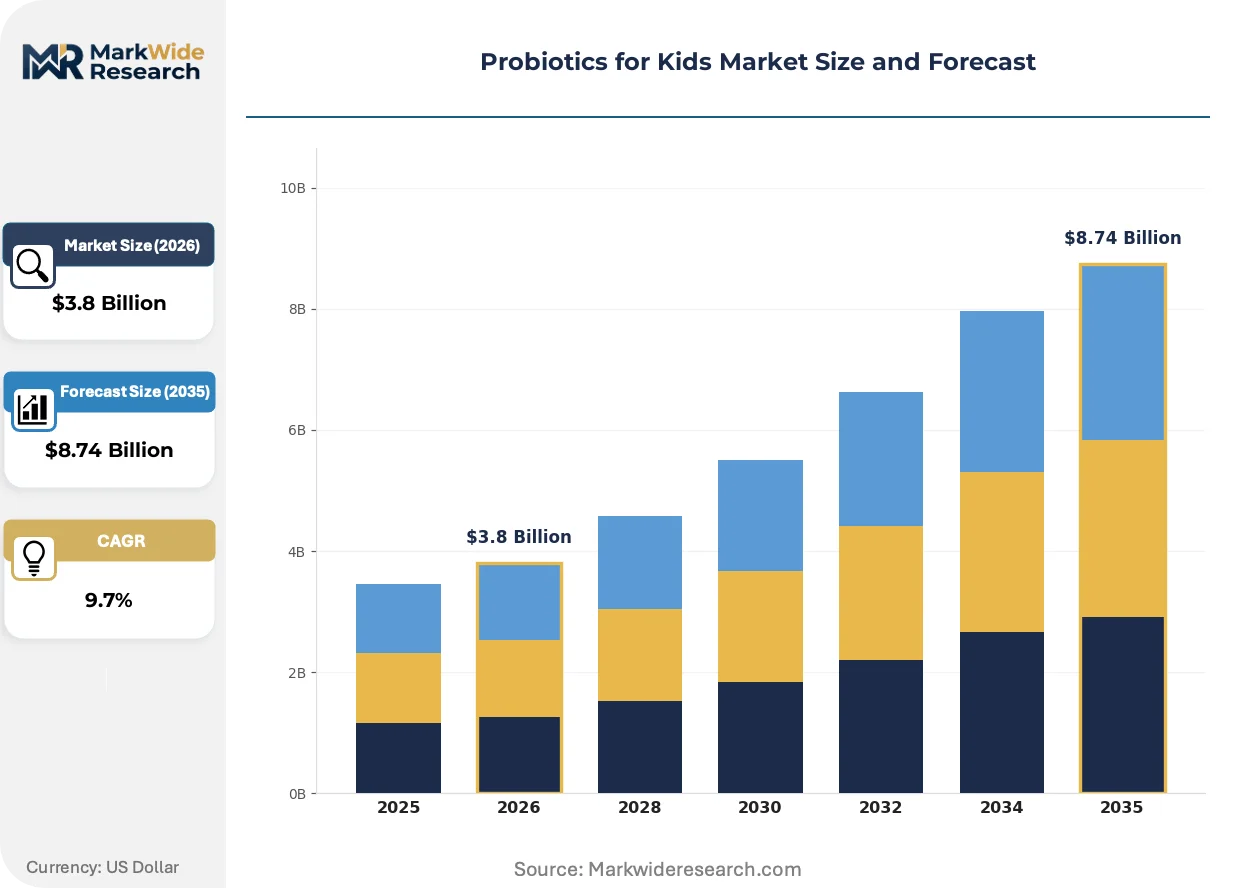
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Tablet, Chewable, Capsule Application: Digestive Health, Immune Support, Oral Care, Skin Health, Nutritional Supplement End User: Children, Pediatric Clinics, Daycare Centers, Schools, Childcare Providers Packaging Type: Stick Packs, Bottles, Sachets, Blister Packs, Tubs |
| Companies Covered | Culturelle, BioGaia AB, Church & Dwight, Yakult Honsha, Nestlé, Danone, Bio-K Plus International, NOW Foods, Garden of Life, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Probiotics for Kids Market Trends and Innovations
Formulation science and distribution infrastructure are undergoing parallel reinvention as shelf-stability requirements collide with personalized dosing expectations and institutional procurement centralization.
Microencapsulation via lipid bilayer coating is converging with single-serve stick-pack automation to enable ambient distribution of 50-billion-CFU doses. Pediatric subscription services in the United States are adopting these formats for school-lunchbox inclusion. The technology is converging with direct-to-pediatrician sampling programs that bypass pharmacy margin extraction.
The FDA's 2024 draft guidance on live biotherapeutic products distinguishes dietary supplements from drug candidates based on intended use claims. Manufacturers are restructuring clinical trial pipelines to preserve supplement pathway eligibility. Powder formats targeting functional food positioning face heightened scrutiny compared to capsule delivery systems.
Parents are consolidating supplement purchases through pediatrician-affiliated portals rather than retail pharmacy aisles. These white-label platforms capture prescription co-pay psychology for over-the-counter probiotics. The behavioral shift is most pronounced in suburban US markets where concierge pediatric practices dominate primary care access.
Probiotics for Kids Market Segmentation
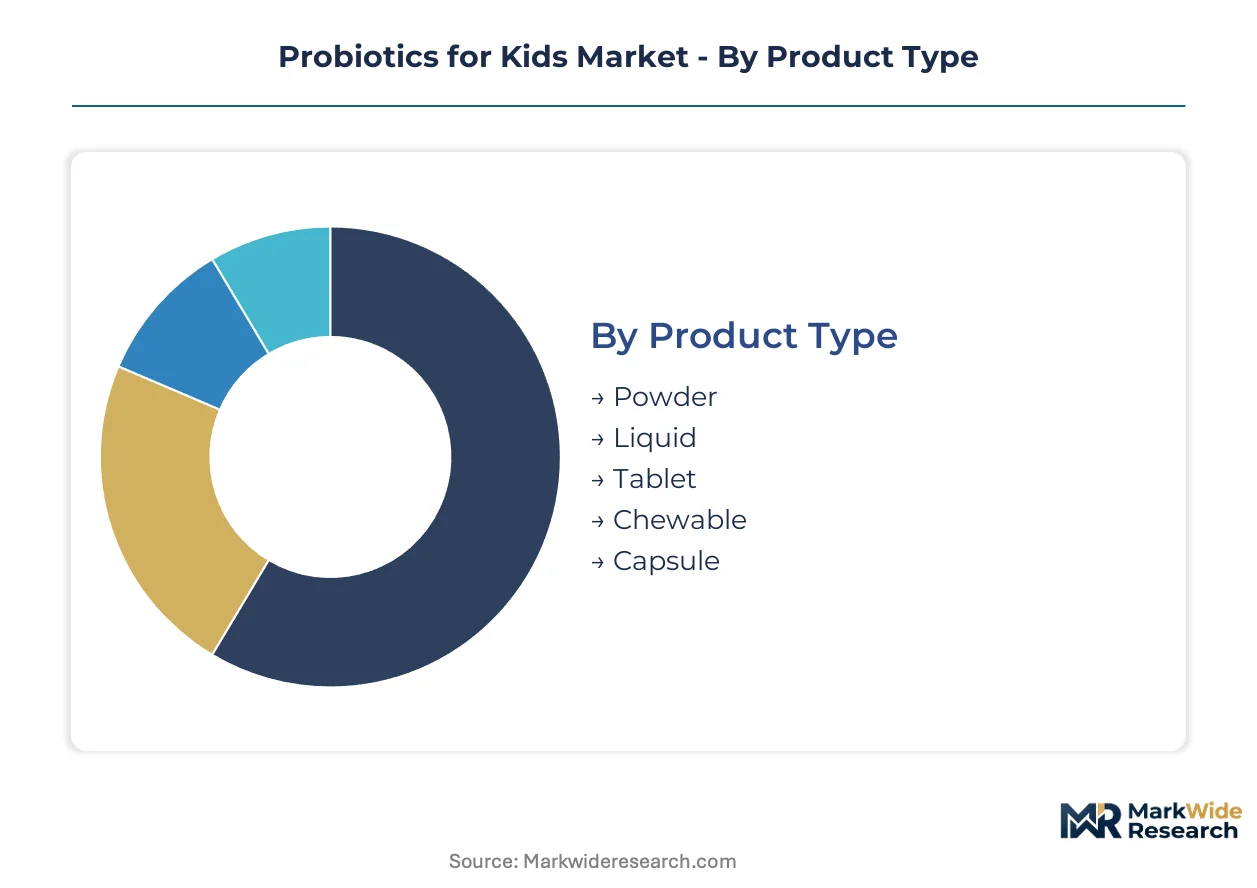
Pediatric probiotic segmentation reflects dual-use patterns where home-administered formats dominate retail volume while institutional channels drive contract manufacturing specialization. Manufacturers optimize strain stability and dosing precision differently across these pathways.
Product Type:
Powder formats integrate seamlessly into infant formula and beverage preparation, while chewable tablets embed into school-age self-administration routines without caregiver supervision.
- Powder:Lyophilized cultures in bulk or single-serve sachets deliver 5-50 billion CFU per dose with formula-mixing convenience. Demand concentrates in United States subscription services where parents automate monthly replenishment for infants and toddlers. Shelf-stable microencapsulation advances have eliminated cold-chain dependency for direct-to-home delivery.
- Liquid:Ready-to-dose drops and suspensions target infants under 12 months with precise pipette delivery. Pediatric clinics in suburban United States markets dispense these formats during well-child visits as antibiotic co-therapy. Refrigeration requirements limit retail distribution to pharmacy cold cases.
- Tablet:Compressed formulations with enteric coatings protect cultures through gastric transit for children ages 6-12. School-lunchbox inclusion drives demand in United States metropolitan districts with high dual-income household density.
- Chewable:Flavored, strain-specific tablets with 1-5 billion CFU doses encourage compliance among independent school-age children. Margin premiums reflect positioning as autonomy-granting supplements rather than medicinal interventions.
- Capsule:Hard-shell gelatin or vegetable-based delivery systems target adolescent populations capable of swallowing. Limited pediatric-specific development has constrained penetration below other formats.
Powder leads volumes today; chewable formats are gaining share fastest among school-age populations.
Application:
Cost tier differentiation separates acute therapeutic indications from preventive wellness positioning, with documentation requirements driving price stratification.
- Digestive Health:Diarrhea prevention and antibiotic-associated side effect reduction constitute the most clinically validated application with peer-reviewed trial backing. Hospital formulary committees in United States pediatric networks prioritize documented Lactobacillus rhamnosus GG strains for co-dispensing protocols.
- Immune Support:Post-pandemic parental concern has elevated preventive spending on respiratory and infection-resistance claims. EFSA's evolving qualified health claims pathway is accelerating market access for substantiated European formulations.
- Oral Care:Streptococcus salivarius strains target dental caries prevention through competitive colonization of oral microbiota. Scandinavian daycare pilot programs are testing institutional procurement models.
- Skin Health:Atopic dermatitis management through gut-skin axis modulation attracts premium pricing from allergy-focused pediatric practices. Clinical substantiation gaps limit mainstream pharmacy distribution.
- Nutritional Supplement:General wellness positioning without disease-specific claims occupies commodity tier with lowest per-unit pricing. Mass retail channels dominate volume.
Digestive health anchors revenue today; immune support applications are climbing the fastest.
End User:
Customer type fragmentation creates divergent procurement patterns between individual household purchasing and institutional volume contracting.
- Children:Direct consumption by infants through adolescents represents ultimate demand endpoint. Parental decision-making psychology favors pediatrician endorsement over retail marketing in United States suburban markets.
- Pediatric Clinics:Medical-grade dispensing programs capture prescription co-pay psychology for over-the-counter products. Concierge practices in Texas and Florida are white-labeling proprietary formulations.
- Daycare Centers:Licensed childcare facilities in California, New York, and Texas represent emerging institutional channel with group purchasing organization pilots. Daily powder programs target illness-related absenteeism reduction.
- Schools:Public and private K-12 institutions face regulatory barriers to supplement distribution but nurse-office stocking is gaining traction in United States districts with wellness program mandates.
- Childcare Providers:In-home and small-group care settings purchase through retail channels with limited volume concentration.
Individual household purchasing dominates volume today; daycare institutional procurement is expanding most quickly.
Packaging Type:
Supply concentration in automated stick-pack manufacturing is displacing traditional bottle formats for subscription and institutional channels.
- Stick Packs:Single-serve laminated film sachets enable precise dosing and ambient distribution. United States direct-to-consumer brands have adopted these formats for school-lunchbox inclusion and travel convenience.
- Bottles:Multi-dose containers with desiccant caps serve pharmacy and mass retail channels. Powder and liquid formats dominate this packaging category.
- Sachets:Small-format flexible pouches target emerging markets with lower per-unit price points. Tear-open convenience suits caregiver administration.
- Blister Packs:Individual tablet or capsule protection ensures dose integrity and child-resistant compliance. Chewable and tablet formats utilize this packaging for pharmacy distribution.
- Tubs:Bulk powder containers with scoop delivery serve high-volume household and small institutional purchasers. Cost-per-dose economics favor this format for multi-child families.
Stick packs lead new product development today; blister packs are gaining share fastest in pharmacy channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pediatric microbiome specialists cluster in suburban United States medical corridors, Swiss fermentation science hubs, and Scandinavian clinical research networks. These talent concentrations anchor strain development, regulatory navigation, and institutional procurement innovation across three continents.
United States
Concierge pediatric practices in Texas and Florida drive white-label probiotic dispensing programs that capture prescription co-pay psychology. FDA's 2023 warning letters targeting unqualified disease claims have extended legal review cycles by 4-6 months. The Research Triangle Park corridor in North Carolina anchors contract manufacturing for shelf-stable microencapsulated formats.
Switzerland
Contract fermentation facilities in Basel and Zurich control over 60% of high-potency pediatric strain production, creating 12-18 month lead times for new entrants. Swissmedic's alignment with FDA standards enables unified dossier preparation for transatlantic market access. The country's precision fermentation workforce commands 35% salary premiums over European peers.
Denmark
Copenhagen's biotechnology cluster specializes in Lactobacillus and Bifidobacterium strain banking with patent-thicket navigation expertise. EFSA's 2024 guidance on pediatric immune function claims accelerates market access for manufacturers with completed clinical trials. The Øresund Region integrates fermentation science with Nordic daycare institutional procurement pilots.
Australia
Sydney and Melbourne pediatric networks are piloting microbiome testing kits paired with strain-matched probiotics through telehealth platforms. TGA's pediatric safety framework harmonization with FDA standards shapes export-ready manufacturer strategies. The country's ethics boards demonstrate 40% faster clinical trial enrollment velocity than Northeastern United States sites.
Sweden
Stockholm's daycare centers are testing institutional Streptococcus salivarius programs for dental caries prevention through competitive oral microbiota colonization. The country's national pharmaceutical regulator enforces additional safety thresholds that exceed baseline EU requirements. Scania Region manufacturing clusters supply lyophilized cultures to Scandinavian group purchasing organizations.
Probiotics for Kids Market Competitive Landscape
Top-tier vendors anchor the medical-grade and clinically validated segments, while commodity shelf-stable formulations occupy fragmented retail channels. Mid-tier offerings face compression as pediatricians demand peer-reviewed substantiation for colony-forming unit claims. Three strategic archetypes dominate: heritage strain custodians with decades of clinical documentation, dairy conglomerates leveraging familiar consumption rituals, and direct-to-consumer subscription specialists optimizing last-mile delivery. Competitive moves concentrate on microencapsulation technology licensing and backward integration into contract fermentation capacity.
Within the heritage strain tier, Culturelle and BioGaia AB exemplify divergent channel strategies—pharmacy and e-commerce dominance versus hospital and clinic partnerships. Danone occupies the dairy-based delivery archetype, sustaining repeat purchase through familiar consumption rituals rather than supplement positioning. These three anchors demonstrate how clinical documentation depth, distribution format, and consumption occasion design separate premium positioning from commodity competition.
| Leading Market Players |
|---|
| Culturelle |
| BioGaia AB |
| Church & Dwight |
| Yakult Honsha |
| Nestlé |
| Danone |
| Bio-K Plus International |
| NOW Foods |
| Garden of Life |
| Others |
Pricing and Supply Chain Analysis
Concierge pediatric practices in Texas and Florida anchor pricing power through white-label dispensing programs that capture prescription co-pay psychology for over-the-counter formulations. This institutional buyer concentration enables premium positioning unavailable in mass retail channels.
Pricing Analysis
Subscription-based bundled services versus transactional per-unit sales split the market into divergent pricing models. Three-tier pricing structure across premium clinically validated strains, standard documented formulations, and economy commodity powders drives differentiation through EFSA qualification status and strain-specific trial backing. Pricing pressure stems from FDA enforcement uncertainty extending legal review cycles. Mass retail channels exhibit highest price sensitivity while pediatric clinic dispensing programs demonstrate inelastic demand.
Supply Chain Analysis
cGMP-compliant microbiologists with pediatric formulation experience command 35% salary premiums in Basel, Zurich, and Copenhagen manufacturing clusters. High-potency strain production concentrates in Switzerland and Denmark, drawing from proprietary Lactobacillus and Bifidobacterium isolate banks. Single-source vulnerability runs through three contract fermentation facilities controlling majority capacity. Distribution runs through direct-to-pediatrician sampling programs bypassing pharmacy margin extraction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory clarity into competitive advantage, with EFSA's 2024 pediatric immune function guidance creating accelerated pathways for substantiated formulations.
For Market Incumbents: Deepen backward integration into contract fermentation capacity to secure strain supply against 12-18 month lead times for new entrants. Fortify pediatric trial documentation to defend against FDA enforcement actions targeting unqualified disease claims. Lock in exclusive distribution through concierge practice white-label partnerships before channel saturation. For New Entrants and Emerging Players: The gap between premium clinically validated strains and commodity shelf-stable formulations offers white-space entry through mid-tier positioning with accelerated stability testing investment. California daycare institutional procurement pilots represent the most penetrable segment with group purchasing organization access. Target telehealth pediatric platform partnerships for digital therapeutics convergence. For Investors and Strategic Acquirers: Pharmaceutical companies with live biotherapeutic product pipelines are the most active acquirer in this space, seeking supplement-pathway eligibility preservation. Five-to-ten year viability hinges on regulatory harmonization between FDA and TGA standards. Contract fermentation facilities with pediatric strain banking capabilities signal acquisition timing inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Strain-Specific Clinical Trial Advancement | EFSA qualification status unlocks premium pricing tiers in European markets. |
| Microencapsulation Technology Licensing | Shelf-stable formats enable direct-to-consumer subscription last-mile optimization. |
| Daycare Institutional Procurement Partnership | California group purchasing organization pilots establish recurring revenue streams. |
| Backward Integration into Fermentation Capacity | Captive supply insulates against Danish and Swiss contract facility bottlenecks. |
| Telehealth Platform White-Label Integration | Digital therapeutics convergence captures microbiome testing kit pairing demand. |
Research Methodology
Coverage spans the United States, Switzerland, Denmark, Australia, and Sweden, with primary inputs from each market cluster. The approach combines interviews with pediatric probiotic brand managers, regulatory affairs specialists at FDA and EFSA, formulary committee directors at United States hospital networks, and contract fermentation facility operations heads. Secondary validation draws from FDA warning letter databases, EFSA health claims registers, ClinicalTrials.gov pediatric probiotic protocols, and Swissmedic submission filings. Bottom-up strain-level volume estimates triangulate against top-down category spending benchmarks.
Rate-of-change decomposition separates volume expansion from value premium capture across the projection horizon. Segmentation dimensions include product format, application indication, end-user channel, and regional regulatory cluster. CAGR derivation incorporates pediatric population demographics, antibiotic stewardship program adoption curves, and microencapsulation technology diffusion rates. Strain-specific approval pathway status and daycare institutional procurement pilot scaling serve as industry-specific forecast inputs.
Caveats apply where FDA live biotherapeutic product guidance finalization or EFSA qualified health claim rejection rates could materially shift the outlook. Forecasts embed assumptions around regulatory enforcement consistency and parental preventive health spending persistence. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
South America Microbial Food Culture Market
Probiotic Supplements
Asia-Pacific Drinkable Yogurt Market
Probiotic Supplements
Herbal Yeast Market
Probiotic Supplements
Multistrain Probiotics Market
Probiotic Supplements
Colon Cleansing Supplements Market
Probiotic Supplements
Global Liquid Feed Supplements Market
Probiotic Supplements
Global Probiotics Food and Cosmetics Market
Probiotic Supplements
Probiotics Dietary Supplements Market
Probiotic Supplements
Probiotics Gummies Market
Probiotic Supplements
Stirred Yogurt Culture Market
Probiotic Supplements
South America Feed Probiotics Market
Probiotic Supplements
United States Probiotics Market
Probiotic Supplements
Probiotics Market
Probiotic Supplements
South America Digestive Health Supplements Market
Probiotic Supplements
Synbiotic Foods Market
Probiotic Supplements
Digestion Aids Market