
 Brazil Probiotics Market | 2026-2036
Brazil Probiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Probiotics Market Outlook
Pharmacy chain consolidation across Brazil's Southeast is realigning how probiotic brands secure shelf presence and professional endorsement. Danone SA leverages its fermented dairy heritage to dominate refrigerated yogurt segments in major metropolitan areas. Yakult Honsha Co. Ltd sustains its direct-store-delivery model, anchoring daily consumption habits through specialized distribution networks. Nestlé SA competes across powder and capsule formats, extending its nutrition portfolio into pharmacy and health store channels.
Probiotics comprise live microorganisms, primarily Lactobacillus and Bifidobacterium strains, that confer health benefits when administered in adequate doses, typically measured in colony-forming units. These cultures undergo controlled fermentation, freeze-drying, or microencapsulation to ensure viability through manufacturing, storage, and gastric transit, serving primarily to modulate intestinal microbiota and support host immune function. Dietary supplements and functional beverages capture margin pools through higher per-unit pricing and concentrated CFU formulations, while yogurt remains the volume anchor due to entrenched breakfast and snacking rituals. The capsules and tablets form commands pharmacy premium positioning, whereas liquid formats drive trial and pediatric acceptance.
ANVISA governs probiotic health claim substantiation and manufacturing facility inspections, while the Ministry of Agriculture and Livestock oversees dairy-based probiotic products under distinct sanitary legislation. Mercosur technical regulations on functional foods create additional harmonization pressures for cross-border formulation strategies. Stakeholders must monitor pending ANVISA resolutions on novel probiotic strain registration, as these will determine which suppliers can introduce next-generation formulations into Brazilian commerce.
Market Dynamics
ANVISA's pending resolutions on novel probiotic strain registration are compressing formulation pipelines and forcing suppliers to pre-validate clinical dossiers before commercial entry. This regulatory tightening concentrates competitive advantage among incumbents with established strain libraries and in-house clinical capabilities.
Growth Catalysts
- Functional beverage demand:Health-conscious Brazilian consumers in São Paulo and the Southeast region are shifting breakfast and snacking rituals toward probiotic-enriched liquid formats.
- ANVISA labeling evolution:Tightening quality benchmarks for live culture claims are professionalizing pharmacy channel endorsement and filtering out subtherapeutic formulations.
- Microencapsulation advances:Controlled-release technologies are improving gastric transit survival rates for Lactobacillus and Bifidobacterium strains in capsule and tablet formats.
Market Restraints
- Freeze-drying input volatility:Specialized cryoprotectant chemicals and low-temperature processing equipment face concentrated global supplier bases.
- Strain registration backlog:ANVISA's pending novel strain protocols create multi-year validation timelines that freeze new entrant pipelines.
- Dairy-based substitution:Plant-based fermented alternatives using non-dairy substrates are capturing trial among lactose-intolerant consumer segments.
Strategic Opportunities
- Northeast underpenetration:Pharmacy chain consolidation has yet to reach Recife and Salvador, creating first-mover shelf presence potential.
- Pediatric liquid formats:Daily consumption habit formation through direct-store-delivery models remains underdeveloped outside Southeast metropolitan cores.
- Mercosur harmonization:Technical regulations on functional foods create cross-border formulation standardization advantages for Brazilian-registered strains.
Industry Challenges
- Clinical validation talent scarcity:Microbiome researchers and biostatisticians capable of designing ANVISA-acceptable human trials command premium compensation.
- Cold chain capex intensity:Refrigerated yogurt segments require specialized fleet investments that strain mid-cap distribution economics.
- Strain IP licensing friction:Proprietary Lactobacillus and Bifidobacterium isolates face complex academic-to-commercial transfer agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Probiotics Market |
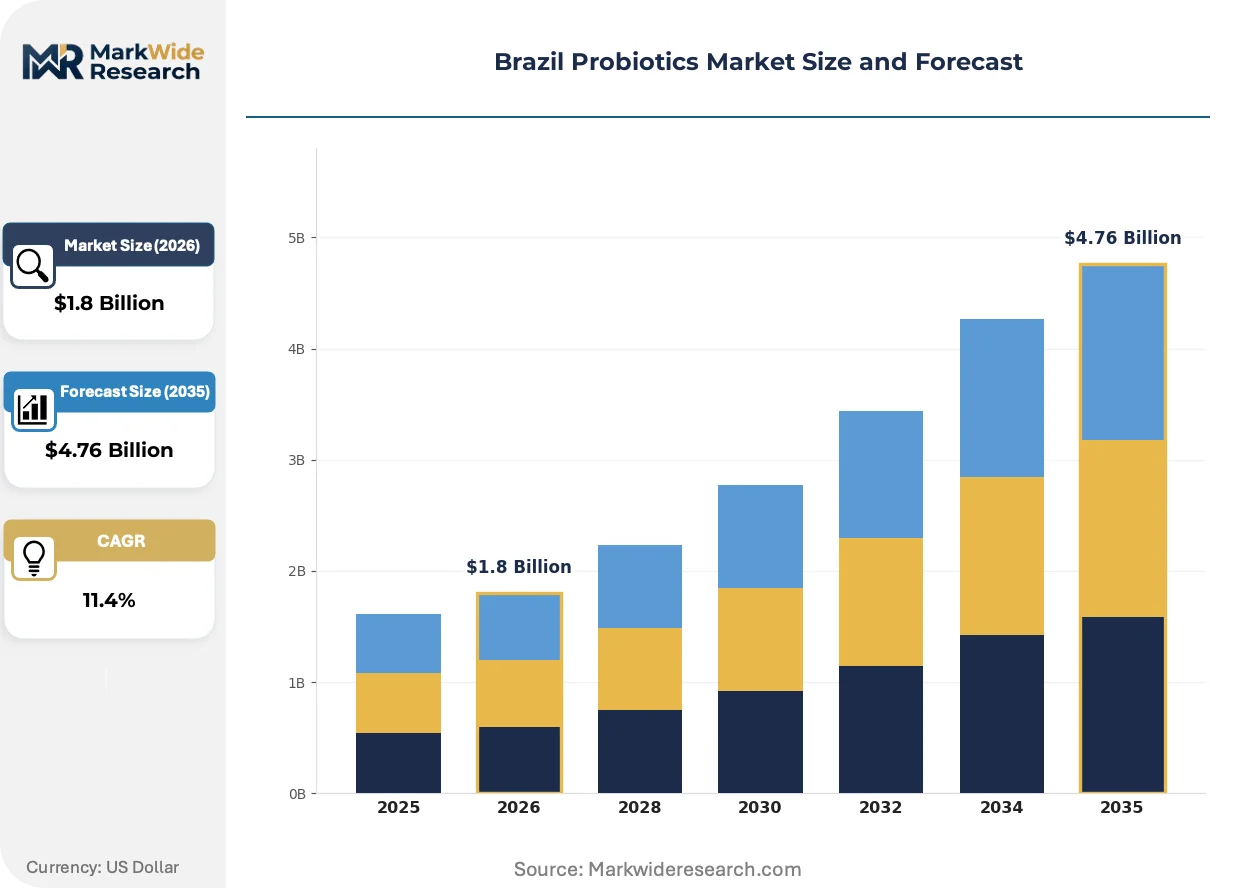
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dietary Supplements, Yogurt, Functional Beverages, Fermented Foods Application: Gut Health, Immune Support, Women's Health, Weight Management Form: Powder, Liquid, Capsule, Tablet Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | Lallemand Inc., Novonesis, Yakult Honsha Co. Ltd, Lactalis Ingredients, Kerry Group, Danone SA, Chr. Hansen, Beliv, Nestlé SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Probiotics Market Strategic Shifts
Microbiome science is migrating from clinical research into mainstream consumer positioning, reshaping how brands communicate strain-specific benefits beyond generic digestive claims. This shift demands new substantiation architectures and professional channel education.
Microencapsulation technology is integrating lipid-based coating systems with alginate bead matrices to shield probiotic cells from gastric acid exposure. Pharmaceutical-grade manufacturers in São Paulo are adopting these systems for pharmacy-positioned capsules. This convergence is integrating viability assurance into premium pricing structures and compressing shelf-life risk for ambient-stable formulations.
ANVISA's evolving nutritional labeling requirements are mandating quantitative live culture disclosure at product end-of-shelf-life rather than manufacture date. Dairy-based probiotic products fall under Ministry of Agriculture and Livestock sanitary legislation, creating dual-track compliance obligations. Capsule and tablet formats face the steepest reformulation costs as manufacturers recalculate overage factors to meet declared counts.
Pharmacy channel consolidation across Brazil's Southeast is displacing independent health store distribution as the primary professional endorsement pathway. São Paulo-based retail chains now require clinical dossier review before shelf placement. This concentration is most visible in metropolitan pharmacy networks where pharmacist recommendation drives trial conversion for premium-positioned dietary supplements.
Brazil Probiotics Market Segmentation
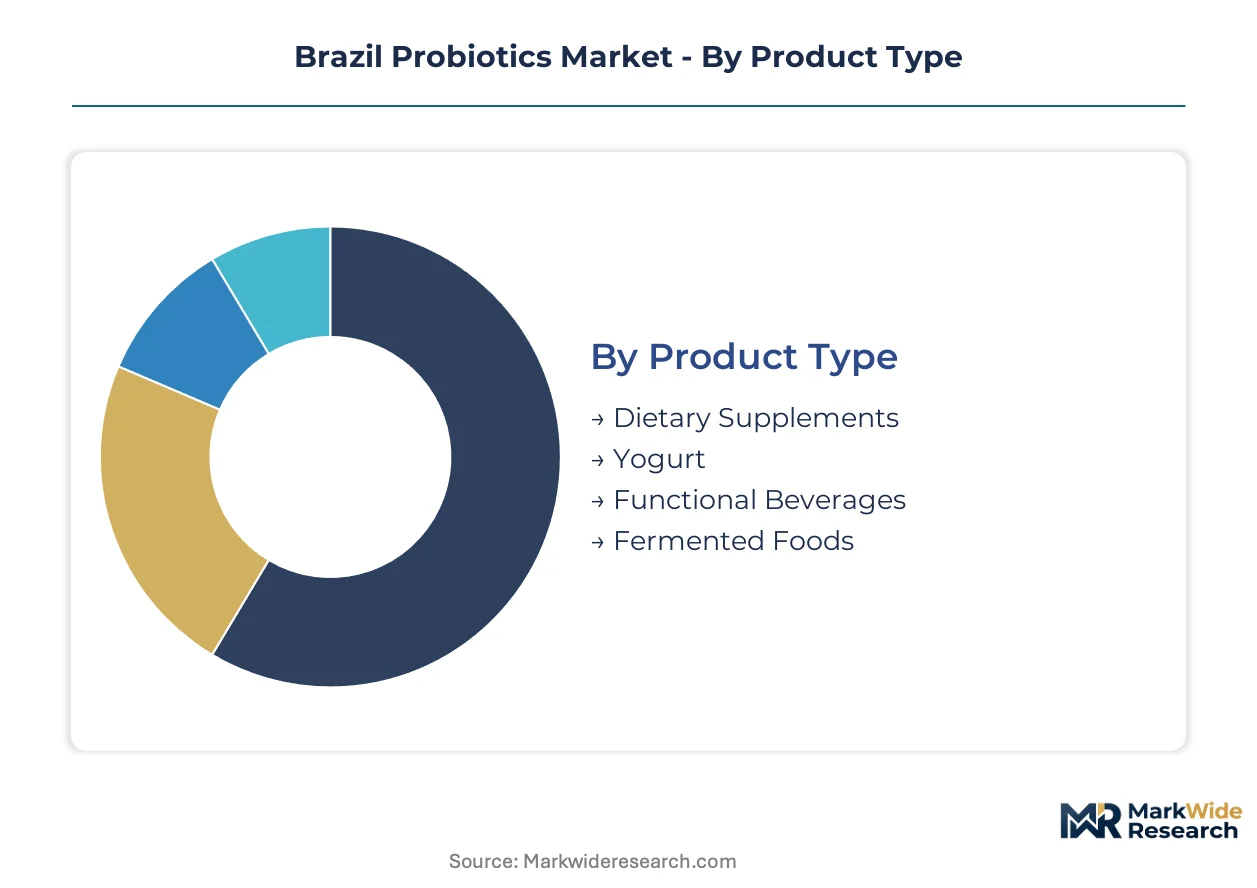
Segmentation in Brazil's probiotics market reveals how ANVISA compliance costs, regional pharmacy consolidation, and strain-specific clinical dossiers reshape competitive positioning across distinct product architectures and channel strategies.
Product Type:
Strain viability requirements and cold chain intensity separate margin structures across delivery formats.
- Dietary Supplements:Concentrated CFU formulations in capsule and tablet formats command pharmacy premium positioning. São Paulo's consolidated retail chains now require clinical dossier review before shelf placement, filtering subtherapeutic entrants.
- Yogurt:Fermented dairy remains the volume anchor due to entrenched breakfast rituals, though refrigerated distribution demands specialized fleet investments that strain mid-cap economics outside Southeast metropolitan cores.
- Functional Beverages:Liquid probiotic-enriched formats drive trial conversion and pediatric acceptance through daily consumption habit formation.
- Fermented Foods:Traditional substrates including kimchi and kefir capture lactose-intolerant consumer segments seeking non-dairy alternatives.
Dietary Supplements leads on scale; Functional Beverages leads on momentum.
Application:
Clinical substantiation depth determines which health claims survive ANVISA's tightening quality benchmarks.
- Gut Health:Generic digestive positioning dominates mass-market yogurt and beverage segments with lower regulatory burden.
- Immune Support:Strain-specific immunomodulation claims require human trial dossiers that concentrate advantage among incumbents with in-house microbiome research capabilities.
- Women's Health:Vaginal microbiome formulations represent a specialized subsegment with concentrated pharmacy channel presence and professional endorsement dependency.
- Weight Management:Metabolic health positioning demands emerging clinical validation that ANVISA's pending novel strain protocols may delay.
Gut Health anchors volume; Immune Support climbs the fastest as microbiome science migrates into mainstream positioning.
Form:
Manufacturing technology and gastric transit survival rates differentiate pricing tiers.
- Powder:Ambient-stable formulations reduce cold chain dependency and extend shelf presence into Northeast regions where refrigerated infrastructure remains underdeveloped.
- Liquid:Direct-store-delivery models sustain daily consumption habits, with Yakult's specialized distribution networks anchoring metropolitan São Paulo penetration.
- Capsule:Microencapsulation advances using lipid-based coatings and alginate matrices shield cells from gastric acid, integrating viability assurance into premium pharmacy positioning.
- Tablet:Compressed formats face steepest reformulation costs as manufacturers recalculate overage factors to meet ANVISA's end-of-shelf-life live culture disclosure mandates.
Capsule commands margin; Powder gains share fastest in underpenetrated geographies.
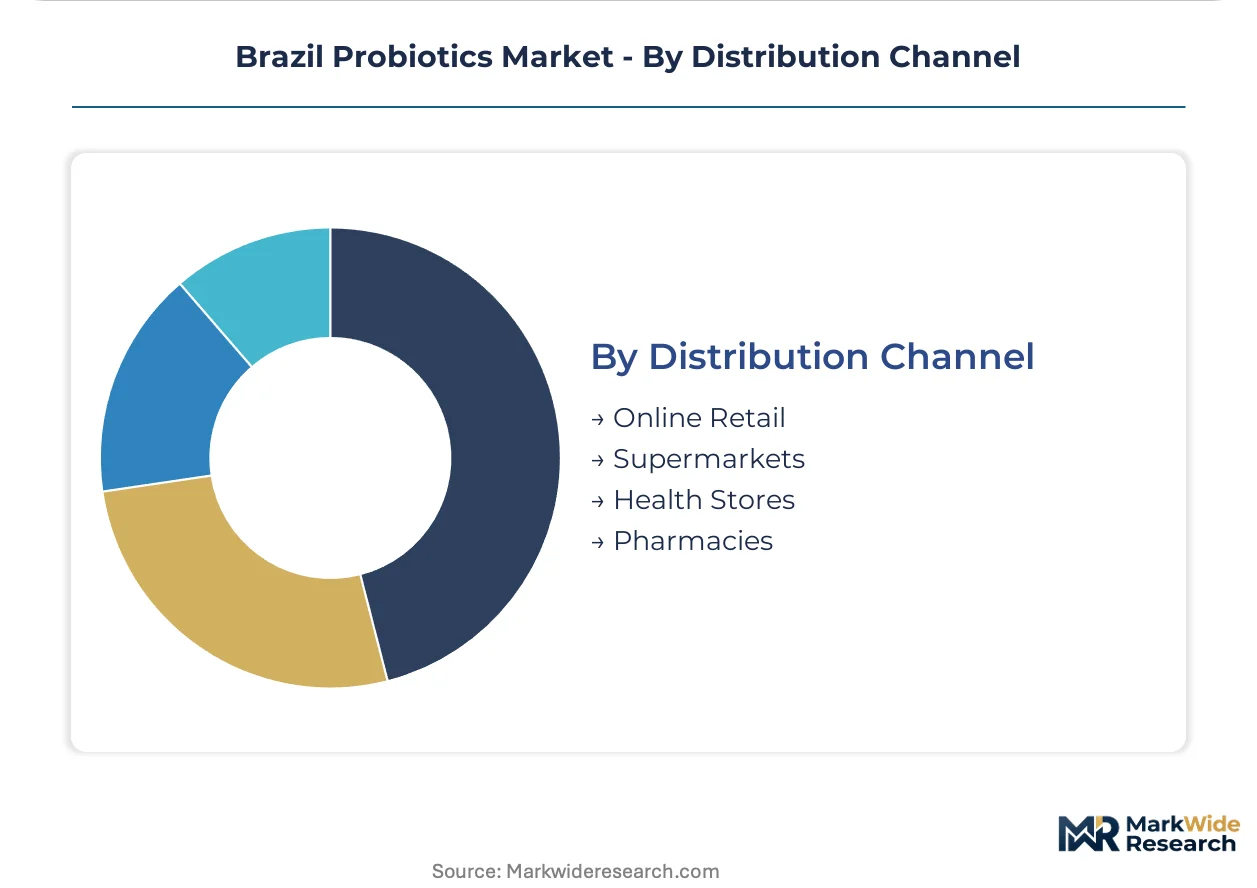
Distribution Channel:
Professional endorsement intensity and customer acquisition economics vary sharply across channel architectures.
- Online Retail:E-commerce platforms capture subscription-based replenishment for dietary supplement formats, though cold chain limitations constrain yogurt and refrigerated beverage penetration.
- Supermarkets:Mass-market yogurt volume concentrates in São Paulo and Southeast urban centers where purchasing power and refrigerated shelf space align.
- Health Stores:Independent distribution faces displacement as pharmacy chain consolidation professionalizes the primary endorsement pathway for premium supplements.
- Pharmacies:São Paulo-based retail networks now require clinical dossier review before shelf placement, concentrating recommendation-driven trial conversion for high-CFU capsules and tablets.
Pharmacies leads on professional endorsement density; Online Retail expands most quickly in subscription supplement segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil concentrates probiotic demand more intensely than Mexico, where functional beverage penetration remains nascent and pharmacy channel consolidation has not yet reached comparable density. São Paulo anchors national volume, while Northeast sub-regions present underpenetrated expansion vectors.
São Paulo
Metropolitan pharmacy chains command professional endorsement density, with consolidated retail networks requiring clinical dossier review before shelf placement. ANVISA's evolving labeling mandates filter subtherapeutic formulations from premium-positioned capsules. The city's specialized distribution infrastructure supports direct-store-delivery models that anchor daily consumption habits.
Minas Gerais
Belo Horizonte's emerging health-conscious consumer base drives functional beverage trial conversion through supermarket and convenience channels. The Ministry of Agriculture and Livestock oversees dairy-based probiotic manufacturing facilities across the state's dairy belt. Cold chain investments concentrate in the capital region, leaving interior municipalities dependent on ambient-stable powder formats.
Rio Grande do Sul
Porto Alegre's pharmacy networks are consolidating toward professional endorsement models similar to São Paulo, though with lagging clinical dossier requirements. State-level sanitary legislation aligns with federal ANVISA frameworks while preserving distinct dairy inspection protocols. The metropolitan area's refrigerated logistics infrastructure supports yogurt volume distribution.
Bahia
Salvador represents the most significant underpenetrated pharmacy market among Northeast state capitals, with independent health stores still dominating probiotic supplement distribution. ANVISA's pending novel strain registration protocols create entry barriers that favor incumbents with established clinical capabilities. Ambient-stable powder formats bypass underdeveloped cold chains in interior municipalities.
Paraná
Curitiba's health-conscious demographic profile mirrors São Paulo consumption patterns at reduced scale, with functional beverage demand concentrated in affluent neighborhoods. State agricultural research institutions collaborate with industry on fermentation substrate development. The metropolitan pharmacy channel remains fragmented compared to Southeast consolidation benchmarks.
Brazil Probiotics Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Brazil's probiotic value chain, creating tiered competitive dynamics where scale advantages clash with strain-specific technical depth. The market structure concentrates around three strategic archetypes: multinational nutrition conglomerates with broad portfolio diversification, specialized probiotic culture suppliers with deep fermentation expertise, and regional dairy processors with captive distribution networks. Dominant competitive moves include pharmacy channel consolidation partnerships and microencapsulation technology licensing arrangements that secure gastric transit survival claims.
Among specialized culture suppliers, Lallemand Inc., Chr. Hansen, and Novonesis occupy positions defined by proprietary strain libraries and technical service capabilities. These companies exemplify the pure-play archetype, anchoring competitive positioning around fermentation science rather than end-consumer brand equity. Their business models concentrate on B2B supply relationships with finished product manufacturers, representing a fundamentally different value capture mechanism than retail-facing conglomerates.
| Leading Market Players |
|---|
| Lallemand Inc. |
| Novonesis |
| Yakult Honsha Co. Ltd |
| Lactalis Ingredients |
| Kerry Group |
| Danone SA |
| Chr. Hansen |
| Beliv |
| Nestlé SA |
| Others |
Value Chain & Pricing Dynamics
Freeze-drying cryoprotectant chemical indices cascade through Brazilian probiotic manufacturing into three distinct pricing tiers, with specialized low-temperature processing equipment costs compressing margin structures for mid-cap entrants while concentrating pricing power among incumbents with captive fermentation infrastructure.
Pricing Analysis
Capacity additions in São Paulo's pharmaceutical-grade manufacturing corridors are reshaping price floors for microencapsulated capsule formats. Three-tier pricing structure across premium pharmacy-positioned, standard supermarket, and economy powder segments stratifies around clinical dossier depth and cold chain intensity. Pricing pressure stems from ANVISA's end-of-shelf-life live culture disclosure mandates forcing overage recalculation in tablet formulations. Mass-market yogurt buyers exhibit highest price sensitivity; dietary supplement purchasers in consolidated pharmacy chains show lowest elasticity due to professional endorsement dependency.
Supply Chain Analysis
Probiotic strain libraries rest on concentrated supplier bases in France, Denmark, and the United States, with Chr. Hansen and Lallemand anchoring global culture propagation. Specialized cryoprotectant chemicals, alginate bead matrices, and lipid-based coating systems feed into Brazilian microencapsulation facilities. Single-source vulnerability concentrates in freeze-drying equipment where German and Japanese OEMs dominate installed base. Distribution runs through direct-store-delivery networks for liquid formats and consolidated pharmacy chains for capsule and tablet segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's probiotics market offers margin expansion through microencapsulation technology licensing and pediatric liquid format premiumization, with cold chain infrastructure gaps in the Northeast creating arbitrage opportunities for ambient-stable powder investments.
For Market Incumbents: Anticipate ANVISA's pending novel strain registration protocols by pre-validating clinical dossiers for next-generation immunomodulation claims. Secure backward integration into proprietary Lactobacillus and Bifidobacterium strain libraries to reduce IP licensing friction. Deepen pharmacy chain consolidation partnerships in underpenetrated Northeast metropolitan corridors before first-mover shelf presence windows close. For New Entrants and Emerging Players: Launch via ambient-stable powder formats targeting Salvador and Recife pharmacy networks where cold chain infrastructure remains underdeveloped. Exploit pediatric liquid format white space through direct-store-delivery models outside Southeast metropolitan cores. Anchor initial positioning around lactose-intolerant consumer segments seeking non-dairy fermented alternatives with lower competitive density. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized probiotic culture suppliers possessing ANVISA-acceptable human trial capabilities and established strain libraries. Five-to-ten year viability hinges on regulatory navigation expertise rather than brand equity alone. Watch ANVISA resolution timelines on novel strain protocols as the critical inflection signal determining which suppliers can introduce next-generation formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Licensing | Lipid-based coating systems from São Paulo pharmaceutical manufacturers shield gastric transit survival claims. |
| Pediatric Liquid Format Expansion | Daily consumption habit formation through direct-store-delivery models anchors trial conversion in underpenetrated geographies. |
| Pharmacy Chain Consolidation Partnership | Clinical dossier review requirements in São Paulo-based retail networks professionalize endorsement pathways. |
| ANVISA Pre-Validation Investment | Early clinical trial positioning for novel strain registration protocols compresses new entrant formulation pipelines. |
| Northeast Cold Chain Infrastructure Buildout | Refrigerated logistics investments in Salvador and Recife displace ambient-stable powder dependence in pharmacy channels. |
Study Parameters
Multiple input streams — executive interviews with fermentation science directors, regulatory affairs leads at ANVISA-registered facilities, pharmacy chain category managers, and microbiome research principal investigators — were reconciled against ANVISA resolution filings, Ministry of Agriculture sanitary inspection records, Mercosur technical regulation harmonization documents, and customs trade data for cryoprotectant chemical imports. Bottom-up strain-level demand modeling and top-down category value triangulation anchored market sizing.
Historical consumption patterns cross-referenced against panel input from São Paulo-based retail chains and Belo Horizonte supermarket operators informed trajectory assumptions across the projection horizon. Segmentation dimensions spanned product type, application claim substantiation depth, delivery form manufacturing technology, and distribution channel professional endorsement intensity. CAGRs derived from fitted growth curves incorporating ANVISA regulatory timeline uncertainty and cold chain infrastructure rollout schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged strain registration backlogs or accelerated pharmacy consolidation in the Northeast. Assumptions reflect ANVISA resolution timing, cryoprotectant chemical import tariff stability, and regional cold chain investment flows. A small set of triggers — novel strain protocol finalization, Northeast pharmacy chain M&A activity, and microencapsulation equipment localization — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Probiotics Gummies Market
Probiotic Supplements
Lactobacillus Acidophilus Market
Probiotic Supplements
D-Lactate Free Probiotics Market
Probiotic Supplements
United States Probiotics Market
Probiotic Supplements
Global Enteric Softgel Capsules Market
Probiotic Supplements
Asia-Pacific Drinkable Yogurt Market
Probiotic Supplements
Probiotics for Kids Market
Probiotic Supplements
Asia-Pacific Feed Probiotics Market
Probiotic Supplements
Japan Probiotics Market
Probiotic Supplements
Probiotic Confectionery Market
Probiotic Supplements
ASEAN Probiotic Supplements Market
Probiotic Supplements
Global Liquid Feed Supplements Market
Probiotic Supplements
South America Feed Probiotics Market
Probiotic Supplements
United Kingdom Probiotics Market
Probiotic Supplements
North America Oral Health Probiotics Market
Probiotic Supplements
Europe Microbial Food Culture Market