
 Stirred Yogurt Culture Market | 2026-2036
Stirred Yogurt Culture Market Size, Share, and Industry Trends Forecast 2026-2036
Stirred Yogurt Culture Market Analytics
Asset-light contract fermentation is fragmenting the competitive landscape for stirred yogurt culture supply. Chr. Hansen A/S leverages its strain library depth to dominate probiotic-enhanced segments. Danisco A/S (DuPont) sustains global reach through multi-regional production nodes. Lesaffre Group differentiates via specialized culture blends for regional taste profiles.
Stirred yogurt culture comprises defined blends of Streptococcus thermophilus and Lactobacillus delbrueckii subsp. bulgaricus, typically freeze-dried to 10^11 CFU/g potency for industrial inoculation at 0.01-0.05% w/v. These cultures drive post-pasteurization acidification to pH 4.0-4.6, enabling gel formation and shelf-stable flavor development in stirred-format dairy. Plain and organic product types command premium positioning as retailers expand private-label lines with shorter ingredient decks. Pouch packaging is gaining velocity in food service channels where portion control and reduced freight weight cut logistics spend.
EFSA novel food assessments and EU organic regulations shape strain approval timelines and label claims across member states. The EU F-Gas Regulation indirectly pressures cold-chain logistics costs for culture distribution. Stakeholders must monitor evolving strain patent expiries and local dairy cooperative consolidation patterns to secure supply agreements before capacity tightens in premium culture tiers.
Market Dynamics
Contract fermentation networks are fragmenting stirred yogurt culture supply as dairy cooperatives bypass traditional distributors to source directly from strain libraries. This disintermediation compresses margin capture for intermediaries while accelerating EFSA compliance timelines for artisanal producers.
Growth Catalysts
- EFSA Novel Food pathways:Accelerated strain approval timelines under centralized EU assessment are reducing market entry barriers for probiotic-enhanced cultures. Dairy processors in France and Germany leverage these streamlined protocols.
- Clean-label retail mandates:Supermarket chains across the Netherlands and Belgium now require full fermentation ingredient disclosure. This specification pull is forcing culture suppliers to reformulate blends with shorter decks.
- Artisanal dairy cluster density:Concentrated production in Normandy, Bavaria, and Friesland creates localized demand pools. Regional culture blending facilities co-locate with these clusters to minimize cold-chain distribution costs.
Market Restraints
- Freeze-dried culture input volatility:Lactobacillus bulgaricus propagation requires precisely controlled fermentation media. Supply tightness in pharmaceutical-grade peptone sources creates batch-to-batch potency variation.
- Strain patent concentration:Core thermophilic starter intellectual property remains concentrated among three legacy culture houses. Independent dairy cooperatives face licensing friction when developing proprietary blends.
- EU F-Gas Regulation compliance:Refrigerated distribution of high-potency freeze-dried cultures faces escalating cold-chain cost pressure. Logistics providers pass through HFC phase-down compliance expenses.
Strategic Opportunities
- Polish and Romanian dairy expansion:Underpenetrated markets in Eastern European member states present white space for culture suppliers. Local dairy cooperatives are modernizing with EU structural fund support.
- Pouch format food service penetration:Single-serve packaging for hospitality channels reduces freight weight and portion waste. This format innovation opens direct supply relationships with institutional buyers.
- EU organic regulation alignment:Stricter strain provenance requirements for organic certification create tiered product positioning. Culture houses with documented non-GMO propagation lines capture premium placement.
Industry Challenges
- Phage resistance assay standardization:No unified ISO method exists for validating starter culture robustness against viral contamination. Dairy processors face inconsistent quality assurance across supplier certifications.
- Legacy ERP integration with batch tracking:Smaller culture blending facilities operate paper-based genealogy records. EU digital product passport requirements force expensive system overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stirred Yogurt Culture Market |
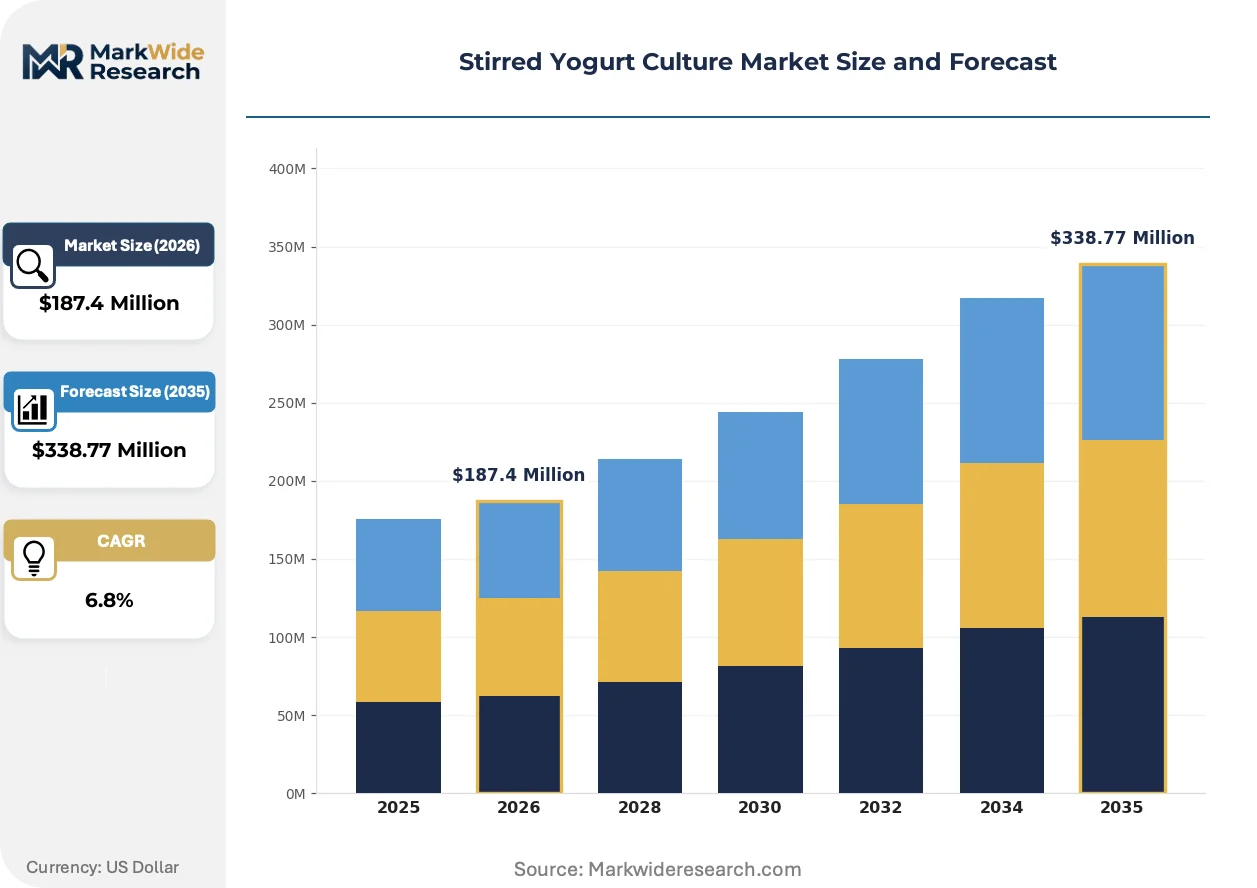
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plain, Flavored, Organic, Low-fat Packaging Type: Plastic Containers, Glass Jars, Pouches, Bulk Packaging End User: Food Industry, Retailers, Restaurants, Home Consumers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service |
| Companies Covered | Chr. Hansen A/S, Danisco A/S (DuPont), DSM Nutritional Products, Lesaffre Group, Beneo GmbH, Lallemand Inc., Sacco System S.r.l., AB Vista, Bioprox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stirred Yogurt Culture Market Evolving Landscape
Digital strain characterization tools are compressing product development cycles for culture houses. These platforms enable rapid phenotype screening without extensive wet-lab validation.
High-throughput sequencing platforms are virtualizing traditional microbiological assay workflows. Culture houses in Denmark and the Netherlands deploy these systems to accelerate phage resistance screening. Dairy processors receive strain performance data in days rather than weeks, compressing supplier qualification timelines.
EFSA's evolving stance on postbiotic health claims is reshaping label architecture for functional stirred yogurts. Strain-specific dossier requirements now demand human intervention studies for immunity positioning. German and French dairy marketers are reformulating away from unverified probiotic language toward fermentation process storytelling.
Food service buyers are consolidating culture procurement through centralized cooperative purchasing. This channel concentration displaces fragmented distributor relationships with direct manufacturer contracts. Netherlands-based dairy service providers lead this consolidation, negotiating volume commitments that lock out smaller blending facilities.
Stirred Yogurt Culture Market Segmentation
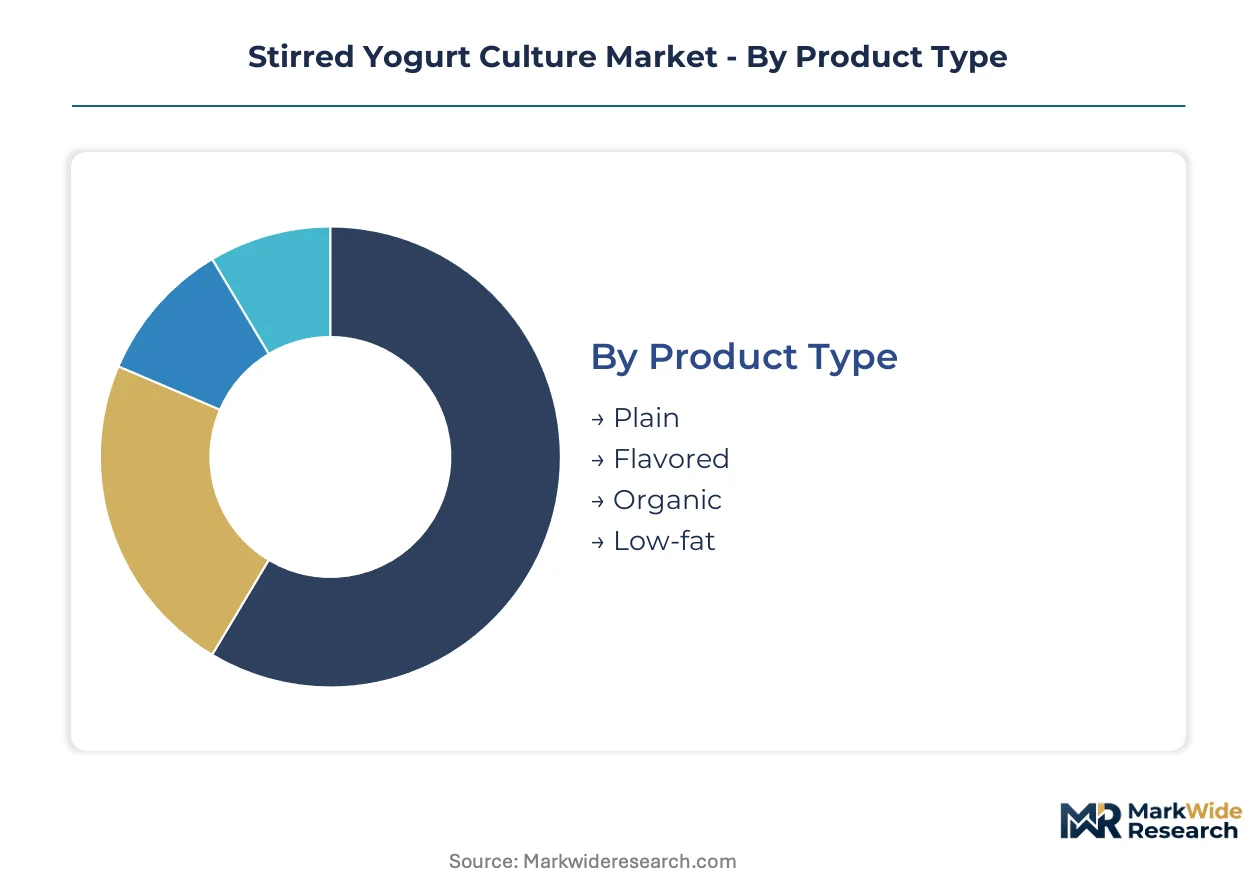
Stirred yogurt culture procurement patterns diverge sharply across product formats and buyer categories. Each segment imposes distinct strain potency requirements, cold-chain specifications, and regulatory documentation burdens that reshape supplier relationships.
Product Type:
Manufacturers configure culture blends to match the acidification speed and flavor intensity each yogurt variant demands.
- Plain:Unsweetened base yogurts require robust thermophilic starters capable of rapid pH drop without masking flavor compounds. French dairy cooperatives in Normandy anchor demand here, prioritizing short ingredient decks for clean-label positioning.
- Organic:Strain propagation must occur on certified organic media under EU organic regulations, with full genealogy documentation from fermentation to freeze-drying. German retailers now mandate this tier for private-label lines, compressing approval timelines for culture houses with existing organic propagation lines.
- Flavored:Post-fermentation fruit additions tolerate wider starter performance variation, opening procurement to lower-potency culture tiers.
- Low-fat:Reduced milk solids demand modified fermentation kinetics to achieve comparable gel strength, favoring specialized strain blends.
The dominant share belongs to Plain, while Organic is closing the gap fastest.
Packaging Type:
Container selection dictates culture potency calibration and shelf-life testing protocols.
- Pouches:Single-serve flexible packaging reduces freight weight and enables precise portion control for food service channels. Netherlands hospitality distributors are consolidating procurement around this format, negotiating direct supply agreements with culture houses that bypass traditional intermediaries.
- Plastic Containers:Standard retail tubs dominate volume, with culture suppliers optimizing for extended refrigerated shelf stability under EU F-Gas Regulation cold-chain constraints.
- Glass Jars:Premium positioning in Belgian and Dutch specialty retail demands strain blends with minimal syneresis over extended storage.
- Bulk Packaging:Food manufacturers receive high-potency freeze-dried cultures in industrial totes, minimizing per-dose packaging cost.
Plastic Containers retain volume leadership, though Pouches are expanding most quickly through food service consolidation.
End User:
Each buyer category imposes distinct technical service requirements and contract structures on culture suppliers.
- Food Industry:Large dairy processors in Bavaria and Friesland negotiate multi-year strain supply agreements with embedded phage resistance guarantees.
- Retailers:Supermarket chains across Belgium and the Netherlands now specify full fermentation ingredient disclosure, forcing culture reformulation toward shorter decks.
- Restaurants:Food service operators prioritize portion-controlled pouch formats with consistent texture batch-to-batch.
- Home Consumers:Small-batch culture sachets for DIY yogurt production concentrate in French and German direct-to-consumer channels.
Food Industry commands the largest procurement volumes, yet Retailers are driving specification tightening fastest.
Distribution Channel:
Channel selection determines cold-chain integrity requirements and documentation depth.
- Supermarkets:Centralized dairy distribution in France and Germany demands culture suppliers maintain regional blending facilities to minimize refrigerated transport distances under F-Gas Regulation cost pressure.
- Food Service:Netherlands-based cooperative purchasing groups consolidate procurement, locking in volume commitments that exclude smaller blending facilities.
- Online Retail:Direct-to-consumer culture sales require specialized packaging for ambient shipping stability.
- Specialty Stores:Artisanal dairy shops in Normandy and Bavaria source small-batch cultures with documented regional strain provenance.
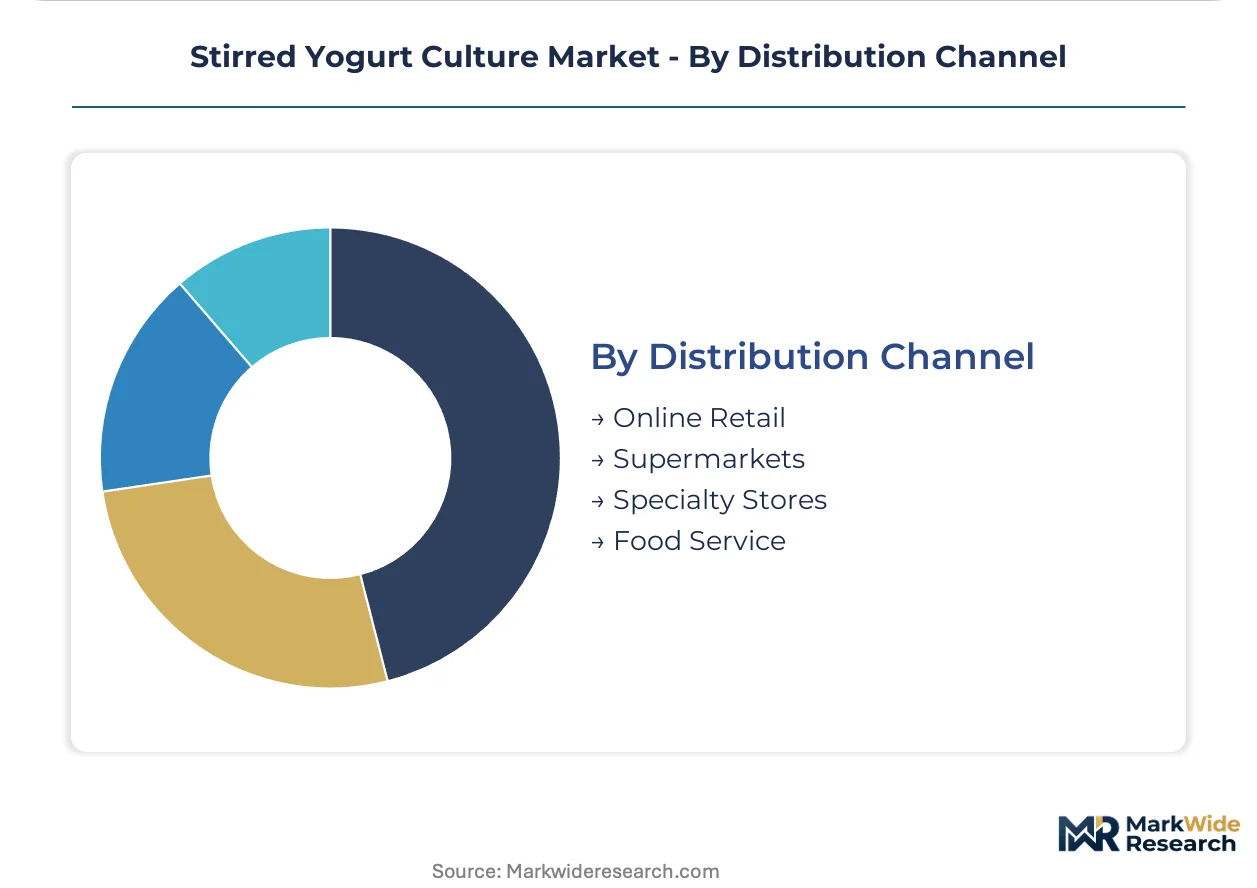
Supermarkets dominate throughput, while Food Service is gaining share fastest through cooperative consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European stirred yogurt culture production generates substantial export surplus against import dependence in North American and Asian markets. France, Germany, and the Netherlands anchor outbound shipment volumes through specialized fermentation facilities.
France
Normandy's artisanal dairy cooperatives drive demand for heritage strain blends with documented regional provenance. ANSM enforces strict microbial contamination thresholds for culture propagation facilities. Paris-based retailers now mandate full fermentation ingredient disclosure, compressing supplier qualification timelines for clean-label positioning.
Germany
Bavarian dairy processors negotiate multi-year supply agreements with embedded phage resistance guarantees. BfR guidelines shape strain safety assessment protocols for novel culture introductions. The Friesland cluster in Lower Saxony co-locates blending facilities with concentrated production to minimize cold-chain distribution costs under F-Gas Regulation pressure.
Netherlands
Food service cooperative purchasing groups consolidate procurement around single-serve pouch formats. The country's national food safety authority enforces rapid alert systems for culture batch contamination. Wageningen-based research institutions accelerate phenotype screening through high-throughput sequencing platforms.
Poland
Eastern European dairy modernization with EU structural fund support creates white space for culture suppliers. The country's national pharmaceutical regulator aligns strain approval timelines with EFSA centralized assessment protocols. Masovian dairy cooperatives are bypassing traditional distributors to source directly from strain libraries.
Belgium
Specialty retail channels in Flanders demand strain blends with minimal syneresis over extended storage. AFSCA-FAVV coordinates with EFSA on novel food dossier requirements for probiotic-enhanced positioning. Antwerp logistics hubs face escalating refrigerated distribution costs from HFC phase-down compliance.
Stirred Yogurt Culture Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with strain-specific capabilities. Three legacy culture houses concentrate core thermophilic starter intellectual property while independent cooperatives fragment procurement through direct sourcing. Strategic archetypes include strain library aggregators, regional blending specialists, and contract fermentation networks. Dominant competitive moves encompass M&A for propagation capacity and strategic partnerships for phage resistance assay standardization.
Among Danish-origin platform integrators, Chr. Hansen A/S occupies a position exemplifying strain library depth, while DuPont-affiliated Danisco A/S represents multi-regional production node architecture. Lesaffre Group anchors the specialized culture blend archetype for regional taste profile differentiation.
| Leading Market Players |
|---|
| Chr. Hansen A/S |
| Danisco A/S (DuPont) |
| DSM Nutritional Products |
| Lesaffre Group |
| Beneo GmbH |
| Lallemand Inc. |
| Sacco System S.r.l. |
| AB Vista |
| Bioprox |
| Others |
Value Network & Pricing Analysis
Normandy's artisanal dairy clusters concentrate freeze-dried culture production capacity, granting regional blending facilities outsized leverage in contract negotiations with pan-European dairy processors. This geographic tightness amplifies pricing power for heritage strain suppliers while compressing margins for distributors caught between concentrated supply and fragmented retail demand.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing, with three-tier pricing structure across premium, standard, and economy levels differentiating by organic certification grade and phage resistance assay depth. Price differentiation reflects EFSA novel food dossier completion status and volume scale commitments, with supermarket private-label procurement teams exhibiting highest sensitivity due to margin pressure from clean-label reformulation mandates. Cost compression in standard tiers is intensifying because pharmaceutical-grade peptone supply tightness propagates through fermentation media costs.
Supply Chain Analysis
EU F-Gas Regulation compliance restricts refrigerant choice for cross-border culture shipments, indirectly constraining distribution flexibility for high-potency freeze-dried products. Supply concentrates in Denmark, France, and the Netherlands, with propagation facilities drawing from pharmaceutical-grade peptone, specialized fermentation media, and cryogenic storage infrastructure. Single-source vulnerability in thermophilic starter intellectual property creates structural risk, as three legacy culture houses control core strain patents. Distribution runs through regional blending facilities co-located with dairy clusters to minimize refrigerated transport distances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deep strain library archives and documented non-GMO propagation lines constitute scarce, non-replicable assets in this market, with capability gaps widening between legacy culture houses and fragmented contract fermentation networks.
For Market Incumbents: Insulate proprietary strain portfolios through accelerated EFSA novel food dossier filings ahead of patent cliff exposure, while securing backward integration into pharmaceutical-grade peptone supply to buffer fermentation media cost volatility. Channel control through direct supply agreements with consolidating food service cooperatives in the Netherlands locks out smaller blending facilities from volume commitments. For New Entrants and Emerging Players: Build out specialized organic propagation lines in Poland and Romania where EU structural fund support modernizes dairy cooperatives and strain approval timelines align with centralized EFSA assessment. Food service pouch format penetration offers the most penetrable entry vector, with direct institutional buyer relationships bypassing traditional distributor intermediaries. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional blending specialists with documented phage resistance capabilities and established organic certification pathways. Long-term viability hinges on consolidation resilience as digital strain characterization tools compress product development cycles. Watch for inflection when EFSA postbiotic health claim rulings force reformulation investments exceeding smaller facilities' capital thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Advancement | Accelerated strain approval timelines under centralized EU assessment reduce market entry barriers for probiotic-enhanced cultures. |
| Backward Integration into Fermentation Media | Captive supply of pharmaceutical-grade peptone buffers batch-to-batch potency variation from input volatility. |
| Organic Propagation Line Certification | Full genealogy documentation under EU organic regulations captures premium placement in German retailer private-label lines. |
| Food Service Pouch Format Expansion | Single-serve packaging reduces freight weight and enables direct supply relationships with Netherlands hospitality distributors. |
| Phage Resistance Assay Standardization Partnership | Collaborative protocol development addresses quality assurance inconsistency across supplier certifications. |
Research Methodology
Initial hypotheses were tested against primary input from culture house R&D directors, dairy cooperative procurement managers, food service distribution heads, and EFSA regulatory affairs specialists and refined through secondary validation against EFSA novel food register entries, EU organic regulation implementation guidance, customs trade data for freeze-dried culture shipments, and dairy processor SEC filings. Bottom-up strain volume estimates triangulated with top-down market sizing across product type, packaging format, end user, and distribution channel dimensions.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation modeling spanning plain, organic, flavored, and low-fat product types alongside pouch, plastic container, glass jar, and bulk packaging formats. CAGRs were derived from regression analysis against dairy production volume trends and clean-label retail penetration rates, incorporating EFSA approval timeline assumptions and F-Gas Regulation cold-chain cost trajectories as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by platform integrators pursuing M&A for propagation capacity would shift outcomes. Material shifts in EFSA postbiotic health claim stance or EU organic regulation strain provenance requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
South America Microbial Food Culture Market
Probiotic Supplements
Digestion Aids Market
Probiotic Supplements
D-Lactate Free Probiotics Market
Probiotic Supplements
Global Probiotics Food and Cosmetics Market
Probiotic Supplements
United Kingdom Probiotics Market
Probiotic Supplements
Colon Cleansing Supplements Market
Probiotic Supplements
Japan Probiotics Market
Probiotic Supplements
Brewer Yeast Powder Market
Probiotic Supplements
Synbiotic Foods Market
Probiotic Supplements
Europe Probiotics Market
Probiotic Supplements
Vegan Probiotics Market
Probiotic Supplements
Europe Microbial Food Culture Market
Probiotic Supplements
Infant and Kids Probiotics Market
Probiotic Supplements
United States Digestive Supplement Market
Probiotic Supplements
Poultry Probiotics Market
Probiotic Supplements
Multistrain Probiotics Market