
 Women Apparel Market | 2026-2036
Women Apparel Market Size, Share, and Industry Trends Forecast 2026-2036
Women Apparel Market Intelligence
Premium sustainable certification is bifurcating the women apparel competitive landscape into traceable supply chain leaders and conventional operators. Inditex leverages its integrated design-to-retail platform to control garment lifecycle transparency. LVMH anchors ultra-luxury positioning through heritage craftsmanship and limited artisanal production. Fast Retailing competes on functional fabric innovation at accessible price points across Asian and European markets.
Women apparel encompasses finished garments designed for female consumers, constructed through cut-and-sew assembly, digital pattern-making, and finishing processes including dyeing, printing, and surface treatment for aesthetic and functional performance. The category serves commercial purposes spanning daily wear, professional dress codes, athletic activity, and ceremonial occasions. Dresses and tops command the largest revenue pools within product type segmentation, while silk and organic cotton variants capture disproportionate margin in material categories. The luxury price tier sustains profitability through scarcity and brand equity, whereas Gen Z customer segments drive velocity in digital-native channels and resale platforms.
REACH restricts chemical inputs in European textile manufacturing, compelling reformulation of dyes and finishing agents. The EU Green Deal mandates extended producer responsibility for garment collection and recycling, altering cost structures for brands distributing in France, Germany, and Italy. China's GB standards govern fiber content labeling and textile safety testing for domestic sale and export production. Stakeholders must monitor regulatory divergence between European circular economy mandates and Asian manufacturing compliance frameworks to align sourcing decisions with emerging market access requirements.
Market Dynamics
The EU Green Deal's extended producer responsibility mandates are forcing apparel brands to internalize end-of-life garment costs, fundamentally restructuring sourcing economics and supplier relationships across the value chain.
Growth Catalysts
- REACH chemical reformulation:European dye and finishing agent restrictions are accelerating adoption of bio-based colorants and waterless dyeing technologies among contract manufacturers supplying EU markets.
- Working professional wardrobe refresh cycles:Hybrid office policies in France, Germany, and the United Kingdom are driving replacement demand for versatile garments bridging formal and casual dress codes.
- Digital pattern-making automation:AI-driven grading and nesting software is compressing sample development timelines from weeks to days for mid-tier brands.
Market Restraints
- Organic cotton supply concentration:Premium fiber availability depends heavily on Indian and Turkish agricultural output, exposing brands to monsoon variability and currency fluctuation.
- GB standards compliance friction:China's fiber content labeling and safety testing requirements create documentation bottlenecks for brands dual-sourcing domestic and export production.
- Silk price volatility:Mulberry cultivation contraction in traditional producing regions is compressing margins on luxury material categories.
Strategic Opportunities
- Resale platform integration:Certified pre-owned garment channels are opening incremental revenue streams for heritage brands with established archive depth.
- EU circular economy subsidies:France's textile waste sorting infrastructure investments and Italy's recycling technology tax credits are lowering compliance cost burdens for participating brands.
- On-demand micro-factory networks:Distributed cut-and-sew automation is enabling proximity production for time-sensitive capsule collections in urban European markets.
Industry Challenges
- Traceability data architecture:Mapping tier-three and tier-four suppliers for certification compliance requires substantial ERP system reconfiguration and supplier onboarding investment.
- Artisanal skill attrition:Heritage craft techniques including hand-embroidery and couture construction face generational transfer gaps in France and Italy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Women Apparel Market |
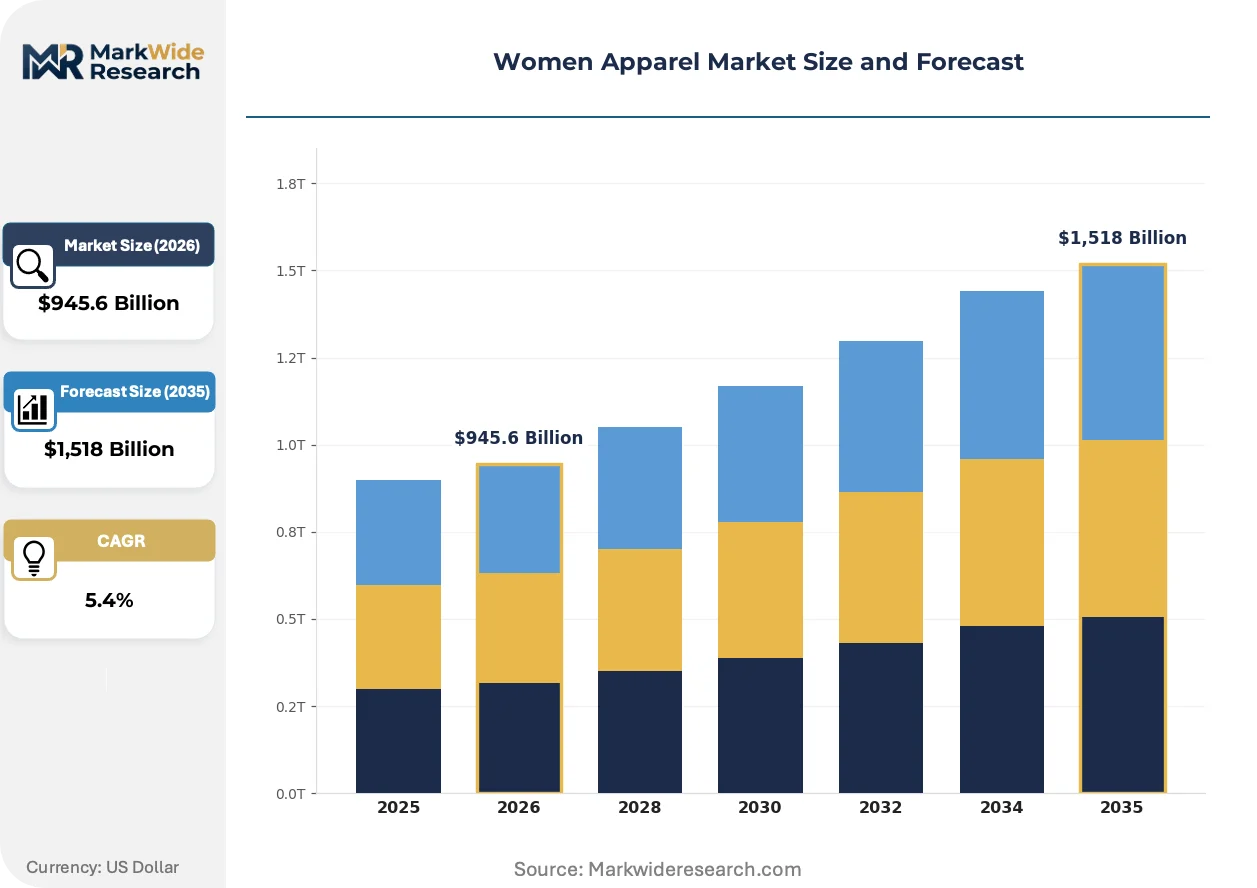
| Market Size in 2026 | $945.6 Billion |
| Market Size in 2035 | $1,518 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dresses, Tops, Skirts, Pants Material: Cotton, Wool, Polyester, Silk Price Tier: Luxury, Mid-range, Affordable, Budget Customer Type: Millennials, Gen Z, Working Professionals, Casual Shoppers |
| Companies Covered | Inditex, H&M Group, Fast Retailing, LVMH, Lululemon Athletica, Gap Inc., PVH Corp., Giorgio Armani S.p.A., TJX Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Women Apparel Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory compliance automation are converging to reshape how garments are designed, produced, and brought to market across price tiers.
Blockchain-enabled fiber provenance tracking is miniaturizing supply chain transparency costs, making batch-level traceability economically viable for mid-market brands. Premium and luxury segments are piloting QR-linked garment passports first, with adoption cascading to mass-market lines as platform licensing fees decline. This transparency infrastructure is miniaturizing the competitive gap between heritage houses with captive supply chains and digitally native entrants.
REACH authorization requirements for restricted substance categories are compelling reformulation of wrinkle-resistant finishes and antimicrobial treatments. Chemical suppliers serving the European market are consolidating compliant ingredient portfolios, passing R&D recovery costs to dye houses and finishers. Sportswear and performance categories face the steepest adaptation curves given functional finish dependencies.
Consignment and rental platform membership models are displacing traditional seasonal purchase patterns among urban professional segments in London, Paris, and Berlin. Digital-native brands are launching dedicated resale verticals to capture customer lifetime value from secondary transactions. This channel diversification is most pronounced among Gen Z and millennial cohorts with lower home storage capacity and higher sustainability preference expression.
Women Apparel Market Segmentation
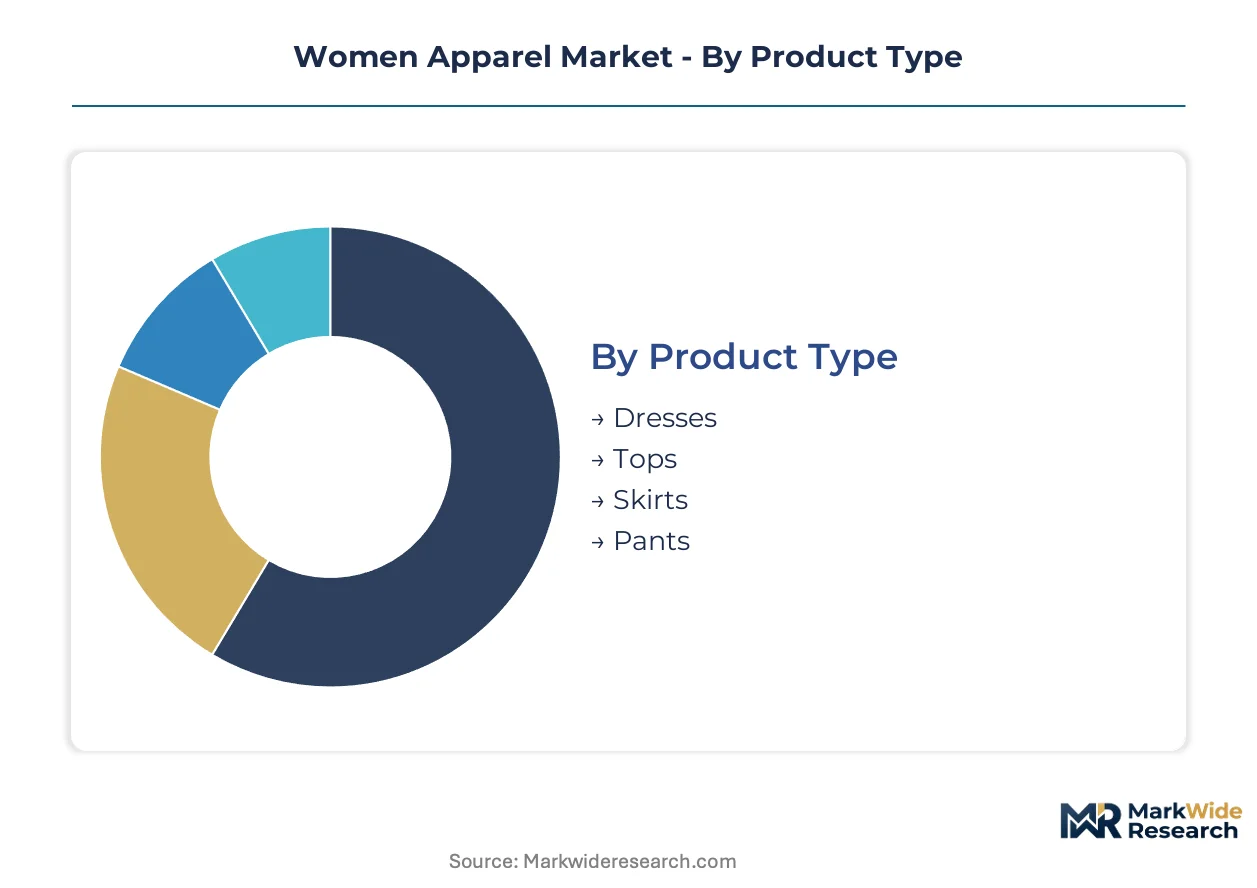
Women apparel segmentation reveals divergent sourcing economics across product types and materials. Demand concentration in China versus export-oriented European markets creates distinct procurement strategies for each category.
Product Type:
Dresses and tops concentrate domestic demand in China and India, while pants and skirts drive European export volumes.
- Dresses:Constructed through cut-and-sew assembly with digital pattern-making for fit precision. Demand concentrates in China's premium domestic channels where local brands expand mid-range positioning, constrained by silk price volatility from mulberry cultivation contraction.
- Tops:Span blouses, shirts, and knitwear with varied construction techniques. Working professionals in France, Germany, and the United Kingdom drive replacement demand for versatile garments bridging formal and casual dress codes under hybrid office policies.
- Skirts:Seasonal velocity items with shorter design cycles. Fast fashion retailers in Spain and Italy optimize rapid replenishment.
- Pants:Technical construction demands precise grading and fit consistency. Denim and tailored variants face divergent raw material cost pressures.
Dresses holds the largest share; momentum sits with tops.
Material:
Natural fibers command margin premiums while synthetic blends scale volume in mass-market channels.
- Cotton:Organic variants capture disproportionate margin but depend on Indian and Turkish agricultural output, exposing brands to monsoon variability and currency fluctuation. REACH chemical reformulation is accelerating bio-based colorant adoption among EU-facing suppliers.
- Silk:Mulberry silk requires specialized sericulture and hand-finishing. Heritage craft techniques face generational transfer gaps in France and Italy, compressing artisanal capacity for ultra-luxury positioning.
- Wool:Merino and cashmere grades serve cold-climate markets. Australian and New Zealand sourcing dominates premium tiers.
- Polyester:Recycled PET variants gain share under EU Green Deal mandates. Chemical suppliers consolidate compliant ingredient portfolios for European market access.
Cotton dominates volume; silk claims the steepest expansion trajectory in value per unit.
Price Tier:
Three-tier pricing structure separates scarcity-driven luxury from velocity-focused accessible segments.
- Luxury:Anchored through heritage craftsmanship and limited artisanal production. LVMH and comparable houses sustain profitability through brand equity and controlled distribution.
- Mid-range:Domestic Chinese brands expand share through design localization and faster trend response than multinational competitors.
- Affordable:Functional fabric innovation at accessible price points drives Fast Retailing's competitive position across Asian and European markets.
- Budget:Volume-dependent with thin margin buffers. GB standards compliance friction creates documentation bottlenecks for dual-sourcing strategies.
Luxury captures highest margin per unit; affordable tier scales fastest in transaction velocity.
Customer Type:
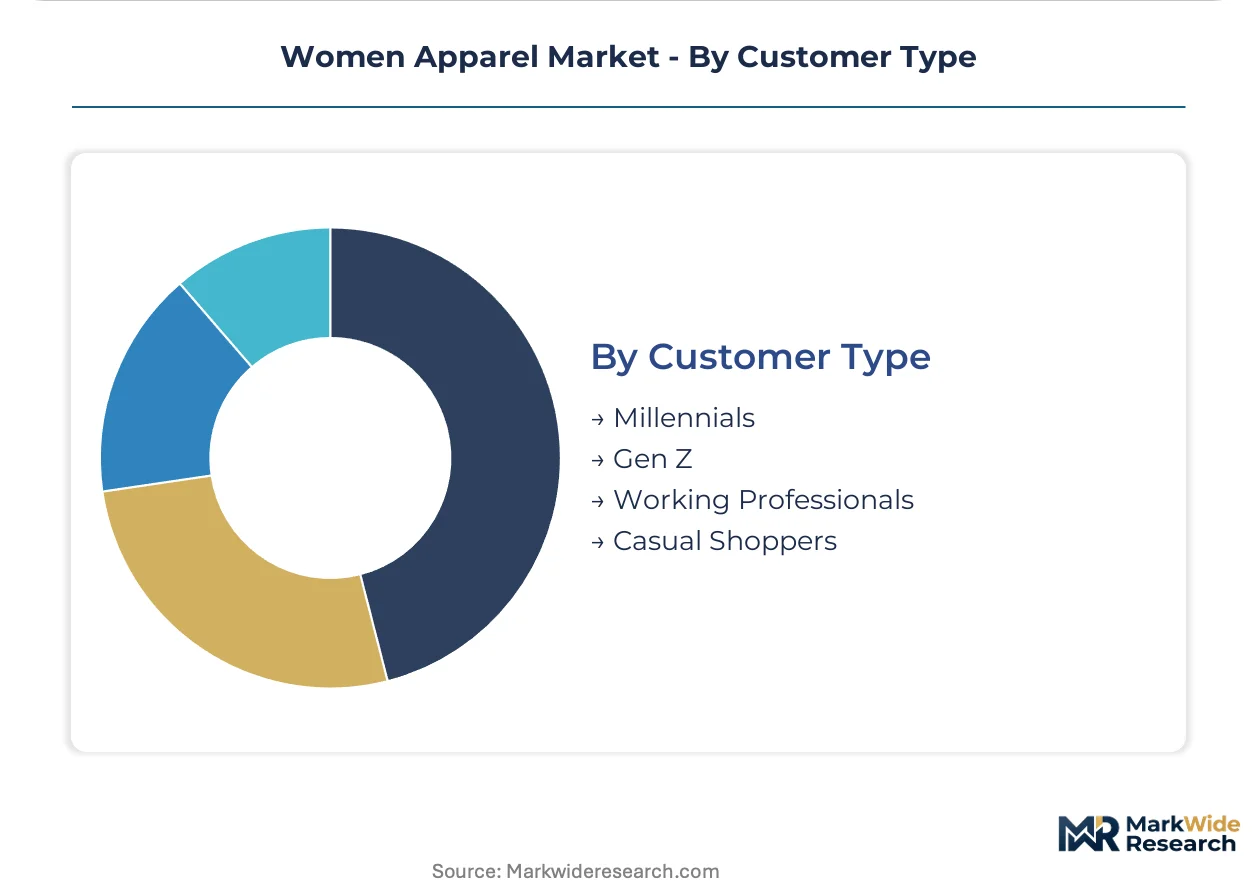
Generational cohorts diverge sharply in channel preference and sustainability willingness-to-pay.
- Working Professionals:Hybrid office policies drive wardrobe refresh cycles for versatile formal-casual bridging garments. Replacement demand concentrates in France, Germany, and the United Kingdom.
- Gen Z:Digital-native channels and resale platforms dominate purchase behavior. Lower home storage capacity and explicit sustainability preference expression shape platform membership model adoption.
- Millennials:Peak earning years support premium tier entry. Consignment and rental displacement of seasonal purchase patterns is most pronounced in London, Paris, and Berlin.
- Casual Shoppers:Price-sensitive with low brand loyalty. Promotional calendar dependency erodes full-price sell-through.
Working professionals hold the largest share; Gen Z is gaining share fastest in digital channel engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturing clusters in Asia supply finished garments to import-dependent European and North American consumer markets, creating asymmetric trade flows that concentrate production risk in sourcing hubs while retail value capture remains concentrated in destination markets.
China
Domestic brands capture premium and mid-range category share through design localization and accelerated trend response. GB standards govern fiber content labeling and textile safety testing for domestic sale and export production, creating documentation friction for dual-sourcing strategies. The Yangtze River Delta and Pearl River Delta host vertically integrated manufacturing clusters where cut-and-sew automation is compressing sample development timelines.
France
Heritage craftsmanship and limited artisanal production anchor ultra-luxury positioning in Paris and Lyon. The EU Green Deal mandates extended producer responsibility for garment collection and recycling, altering cost structures for brands distributing domestically. Textile waste sorting infrastructure investments in the Île-de-France region are lowering compliance cost burdens for participating heritage houses.
Germany
Working professionals in Berlin, Munich, and Hamburg drive replacement demand for versatile garments bridging formal and casual dress codes under hybrid office policies. REACH restricts chemical inputs in textile manufacturing, compelling reformulation of dyes and finishing agents among contract manufacturers supplying the market. Recycling technology tax credits are accelerating circular economy adoption among mid-tier brands.
Italy
Artisanal skill concentration in Lombardy and Tuscany sustains couture construction and hand-embroidery capacity for luxury tiers, though generational transfer gaps threaten heritage techniques. The EU Green Deal's extended producer responsibility mandates are restructuring supplier relationships across the value chain. Proximity production networks in Milan and Florence enable time-sensitive capsule collection delivery.
United States
Digital-native channels and resale platforms dominate purchase behavior among Gen Z and millennial cohorts in New York, Los Angeles, and Chicago. No federal textile-specific regulation matches EU chemical restrictions, creating regulatory divergence for brands operating across both markets. Sustainable certification demand concentrates in coastal metropolitan markets with higher willingness-to-pay for traceable supply chains.
Women Apparel Market Key Industry Players
Concentration sits with integrated design-to-retail platforms and heritage luxury houses that control garment lifecycle transparency or anchor scarcity-driven positioning. The vendor base spans mass-market velocity players, premium domestic champions in China, and ultra-luxury artisanal operators. Three archetypes dominate: vertically integrated fast-fashion platforms, heritage craftsmanship houses, and functional innovation specialists. Competitive moves center on resale platform integration and on-demand micro-factory network deployment.
Within the integrated platform tier, Inditex and Fast Retailing exemplify design-to-retail control over supply chain transparency. LVMH occupies a position anchoring ultra-luxury scarcity through heritage craftsmanship and limited artisanal production. These three represent divergent strategic paths: velocity-scale integration, brand-equity scarcity, and functional accessibility across Asian and European markets.
| Leading Market Players |
|---|
| Inditex |
| H&M Group |
| Fast Retailing |
| LVMH |
| Lululemon Athletica |
| Gap Inc. |
| PVH Corp. |
| Giorgio Armani S.p.A. |
| TJX Companies |
| Others |
Cost & Logistics Intelligence
EU Green Deal certification tiers simultaneously gate supplier qualification and stratify price premiums across the women apparel value chain. Working professionals purchasing versatile formal-casual bridging garments face tiered pricing that reflects traceability depth rather than construction cost alone.
Pricing Analysis
Working professionals anchor a three-tier pricing structure across premium, standard, and economy levels in the women apparel market. Price differentiation stems from certification grade (EU Green Deal compliance tier) and brand heritage equity, with luxury houses commanding scarcity premiums through limited artisanal production. Cost compression in the affordable tier is intensifying because of organic cotton supply concentration and REACH-driven chemical reformulation expenses. Casual shoppers exhibit highest price sensitivity, while heritage luxury buyers demonstrate lowest elasticity due to archive depth and resale value retention.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for brands sourcing finished garments from Bangladesh, Vietnam, and China. Raw material dependencies center on Indian and Turkish organic cotton, Chinese polyester recycling capacity, and Italian silk finishing expertise. Single-source vulnerability concentrates in mulberry sericulture regions facing generational skill attrition. Distribution runs through vertically integrated design-to-retail platforms for velocity players and controlled boutique networks for heritage houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Resale platform interoperability is creating platform-economics inflection in women apparel, with blockchain-enabled garment passports enabling secondary market revenue capture previously inaccessible to primary manufacturers.
For Market Incumbents: Consolidate tier-three supplier traceability data through ERP reconfiguration to preempt EU Green Deal audit requirements. Capture artisanal craft capacity in Lombardy and Tuscany through structured apprenticeship programs before generational transfer gaps permanently erode couture construction expertise. Channel control through dedicated resale verticals defends against digital-native entrants capturing Gen Z lifetime value from secondary transactions. For New Entrants and Emerging Players: Lead with on-demand micro-factory networks in urban European markets where proximity production commands time-sensitive capsule collection premiums. The most penetrable white space sits in certified pre-owned channels for mid-market brands lacking archive depth, with sustainability-native positioning as the go-to-market angle. Target working professionals in Berlin, Munich, and Hamburg through rental membership models displacing traditional seasonal purchase patterns. For Investors and Strategic Acquirers: EU Green Deal extended producer responsibility mandates reshape the acquisition landscape toward traceable supply chain operators with compliant ERP architectures. Long-term viability favors vertically integrated platforms with captive dye-house relationships and waterless finishing technology adoption. The signal to watch is France's textile waste sorting infrastructure subsidy allocation rates as indicator of circular economy compliance cost trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Resale Platform Integration | Blockchain-enabled garment passports open secondary revenue streams for heritage brands with archive depth. |
| On-Demand Micro-Factory Deployment | Distributed cut-and-sew automation in Milan and Florence compresses capsule collection delivery timelines. |
| EU Green Deal Compliance Investment | Extended producer responsibility mandates alter cost structures for brands distributing in France and Germany. |
| Artisanal Skill Preservation Program | Structured apprenticeships in Lyon and Tuscany counter generational transfer gaps in couture construction. |
| Digital Pattern-Making Automation | AI-driven grading software compresses sample development timelines from weeks to days for mid-tier brands. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with brand sustainability officers, textile procurement directors, heritage house atelier managers, and resale platform operations leads. Secondary validation drew from EU ECHA REACH substance restriction databases, French textile waste sorting infrastructure investment disclosures, Chinese GB standards fiber content labeling requirements, and Italian circular economy tax credit filings. Bottom-up garment volume estimates triangulated against top-down category spending patterns across the analysis window.
Across the projection horizon, the analytical framework modeled women apparel demand through product type, material composition, price tier positioning, and generational customer cohort segmentation. CAGRs were derived from trend extrapolation anchored in hybrid office policy permanence, EU regulatory compliance cost trajectories, and digital channel adoption curves. Industry-specific inputs included silk price volatility indices, organic cotton harvest yield variability, and blockchain traceability platform licensing fee decline rates.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement intensity, stable Asia-Europe shipping lane capacity, or continued Gen Z resale platform engagement would require recalibration. Forecasts reflect documented assumptions regarding regulatory implementation timelines, fiber substitution elasticity, and platform membership model retention. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Luxury Vegan Men's Fashion Market
Apparel & Footwear
Women's T-Shirts Market
Apparel & Footwear
Polo Shirt Market
Apparel & Footwear
Tennis (Apparel and Footwear) and Golf (Apparel and Footwear) Market
Apparel & Footwear
Headwear Market
Apparel & Footwear
Intimate Lingerie Market
Apparel & Footwear
Women's Dresses and Skirts Market
Apparel & Footwear
Heated Jacket Market
Apparel & Footwear
Luxury Fashion Market
Apparel & Footwear
Compression Wear and Shapewear Market
Apparel & Footwear
US Thermal Underwear Market
Apparel & Footwear
Global Leggings Market
Apparel & Footwear
Bra Market
Apparel & Footwear
Fast Fashion Market
Apparel & Footwear
Global Apparel and Footwear Market
Apparel & Footwear
Swimwear and Beachwear Market