
 Snow Boots for Women Market | 2026-2036
Snow Boots for Women Market Size, Share, and Industry Trends Forecast 2026-2036
Snow Boots for Women Market Analytics
Apparel-pattern engineering talent is bifurcating the competitive landscape as heritage bootmakers struggle to hire thermal-design specialists fluent in 3D foot-scanning technology. Sorel leverages its vertically integrated rubber-compounding facility in Canada to control vulcanization quality for arctic-rated soles. The North Face sustains R&D intensity through its Summit Series innovation lab, where aerogel insulation prototypes undergo minus-forty-degree testing. L.L. Bean anchors direct-to-consumer loyalty through its century-old mail-order heritage now translated into digital customization portals.
Snow boots for women are technically defined as cold-weather footwear engineered with thermal insulation ratings between minus-twenty and minus-forty degrees Celsius, waterproof membrane construction, and lug-pattern outsoles designed for traction on ice and packed snow, serving both recreational winter sports and daily urban commuting in freezing climates. Waterproof styles now command the largest revenue pool as consumers prioritize seam-sealed construction over aesthetic flexibility, while insulated variants with Thinsulate or PrimaLoft fill represent the fastest-expanding segment driven by polar vortex frequency in the Great Lakes region. Lace-up closure types dominate professional and backcountry segments for adjustability, yet zipper configurations gain share among urban commuters seeking rapid on-off functionality.
FDA oversight of footwear chemical safety through its Title 21 regulations on phthalate content intersects with EPA guidelines on perfluorinated compound discharge from waterproofing treatments, compelling brands to reformulate DWR coatings. The EU REACH regulation restricts chromium VI in leather tanning, directly impacting material sourcing for European-market production lines. Stakeholders must monitor evolving state-level extended producer responsibility laws in California and New York that will soon mandate recycled-content minimums and take-back infrastructure for footwear end-of-life management.
Market Dynamics
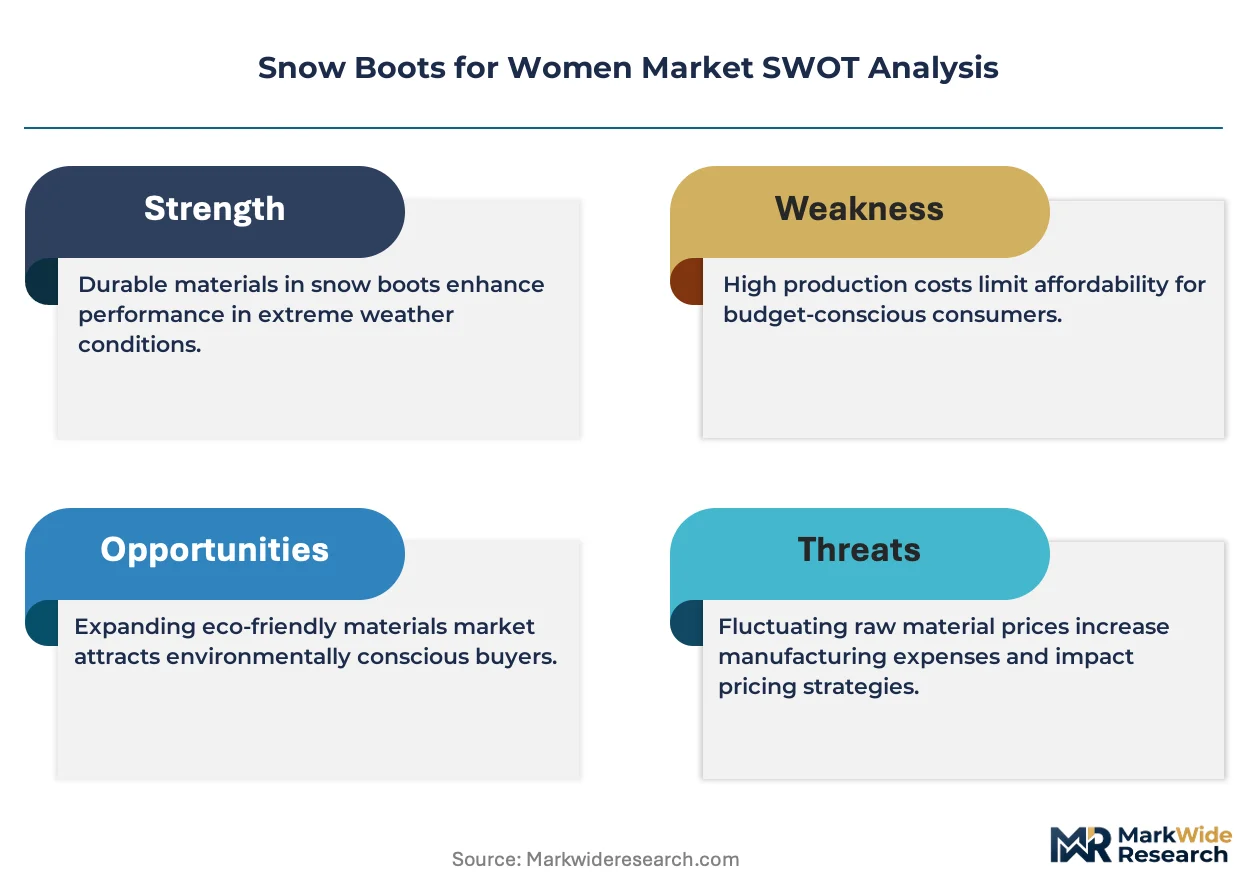
Thermal-engineering talent scarcity and EU chemical restrictions are compressing margins for heritage manufacturers while rewarding vertically integrated competitors with captive R&D capabilities.
Growth Catalysts
- Polar vortex frequency:Extreme cold events across the Great Lakes region extend the functional selling season for arctic-rated insulation systems. Urban commuters in Chicago, Detroit, and Cleveland now purchase technical snow boots as essential cold-weather infrastructure.
- EU Green Deal chemical restrictions:Mandatory phase-outs of perfluorinated compounds in waterproofing treatments accelerate reformulation investment. Brands achieving bio-based DWR certification capture shelf space in German and French retail channels.
- Alpine tourism infrastructure expansion:Resort operators in Colorado, Utah, and Vermont are outfitting staff with uniform-grade technical footwear. This institutional procurement channel delivers volume contracts with multi-year replacement cycles.
Market Restraints
- Natural rubber price volatility:Plantation supply concentration in Thailand and Indonesia creates input cost unpredictability. Vulcanization-dependent manufacturers face margin compression during La Niña weather patterns.
- REACH compliance complexity:Chromium VI restrictions in leather tanning force European-market production lines to source from certified tanneries in Italy and Portugal. This geographic concentration limits supplier flexibility.
- Synthetic insulation substitution:Down-filled alternatives from outdoor apparel brands compete for consumer cold-weather spending. Price-sensitive buyers prioritize jacket upgrades over footwear replacement.
Strategic Opportunities
- Extended producer responsibility mandates:California and New York state laws will mandate recycled-content minimums and take-back infrastructure. First-movers establishing circular logistics networks capture regulatory goodwill.
- 3D foot-scanning customization:Digital morphology matching converges with thermal-mapping algorithms. Direct-to-consumer portals offering bespoke last construction penetrate the premium gift market.
- Urban commuter zipper configurations:Rapid on-off functionality addresses subway-to-office transitions. Japanese and South Korean metropolitan buyers demonstrate willingness-to-pay premiums for magnetic closure systems.
Industry Challenges
- Thermal-design specialist scarcity:Apparel-pattern engineers fluent in aerogel prototyping and minus-forty-degree testing command compensation premiums. Heritage bootmakers struggle to recruit against outdoor apparel competitors.
- FDA-EPA regulatory intersection:Phthalate content oversight through Title 21 overlaps with perfluorinated compound discharge guidelines. Reformulation timelines compress as dual-agency compliance requirements diverge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snow Boots for Women Market |
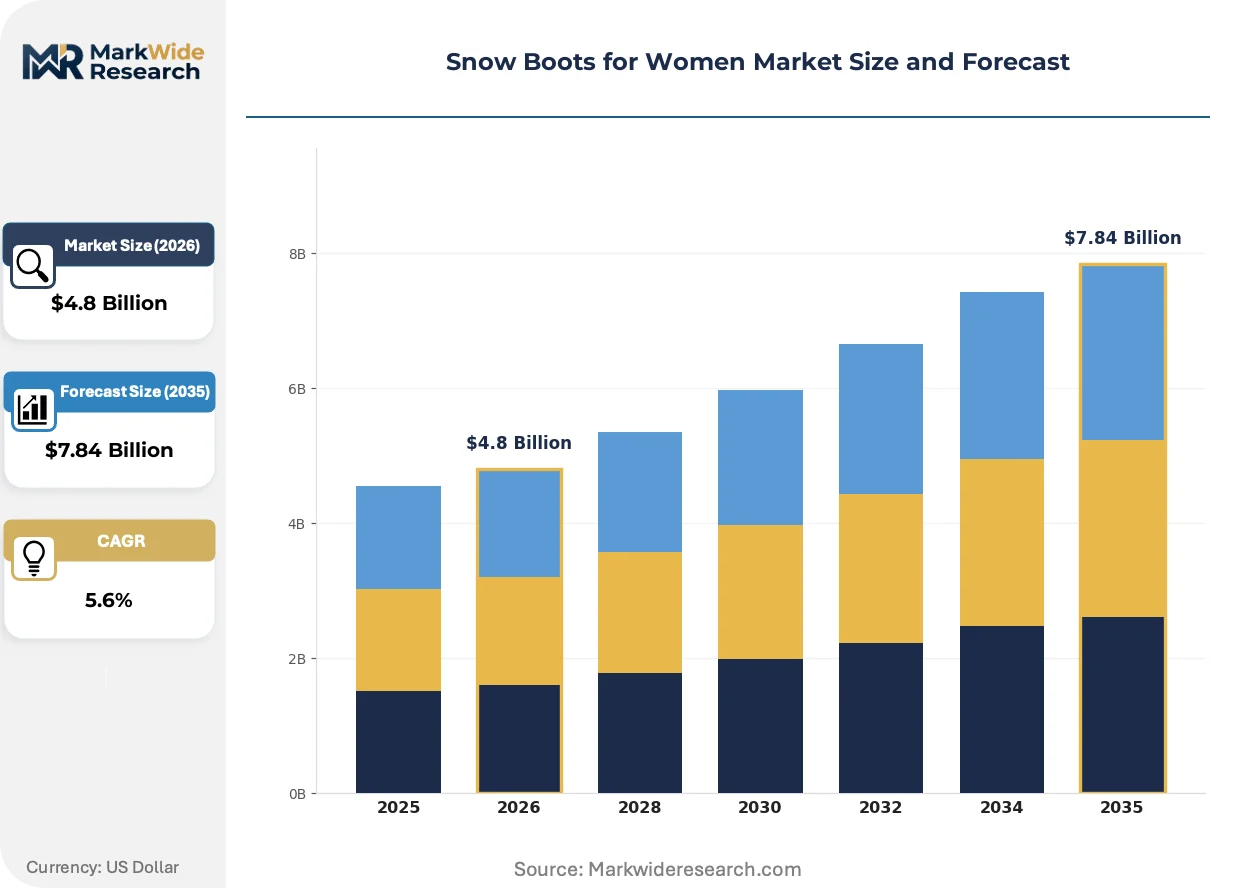
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Style: Classic, Waterproof, Insulated, Lightweight Material: Leather, Synthetic, Rubber, Textile Closure Type: Lace-up, Zipper, Slip-on, Velcro Brand: North Face, Columbia, Sorel, Merrell |
| Companies Covered | Sorel, UGG, The North Face, Pajar, Hunter, L.L. Bean, Baffin, Keen, Timberland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snow Boots for Women Market Evolving Landscape
Aerogel insulation and bio-based waterproofing are displacing conventional synthetic fills, while digital customization portals transform how technical cold-weather footwear reaches end consumers.
Phase-change material integration is bifurcating the thermal-performance tier. Backcountry skiers and ice-fishing enthusiasts adopt boots with paraffin-based microencapsulation that absorbs and releases body heat. This technology is compressing the addressable market for passive synthetic insulation, forcing mid-tier brands to retreat toward urban-commuter positioning or invest in licensed thermal IP.
REACH chemical restrictions on chromium VI and perfluorinated compounds are forcing material-system redesigns. European-market production lines must source from certified Italian and Portuguese tanneries and reformulate DWR coatings to bio-based alternatives. Waterproof styles with seam-sealed construction face 18-24 month recertification timelines, advantaging manufacturers with captive testing facilities.
Direct-to-consumer digital customization is displacing wholesale-dependent distribution. Urban commuters in Tokyo, Seoul, and New York access 3D foot-scanning portals that translate biometric data into bespoke last construction. This channel shift compresses inventory risk for technical footwear brands while fragmenting retail concentration in outdoor specialty stores.
Snow Boots for Women Market Segmentation
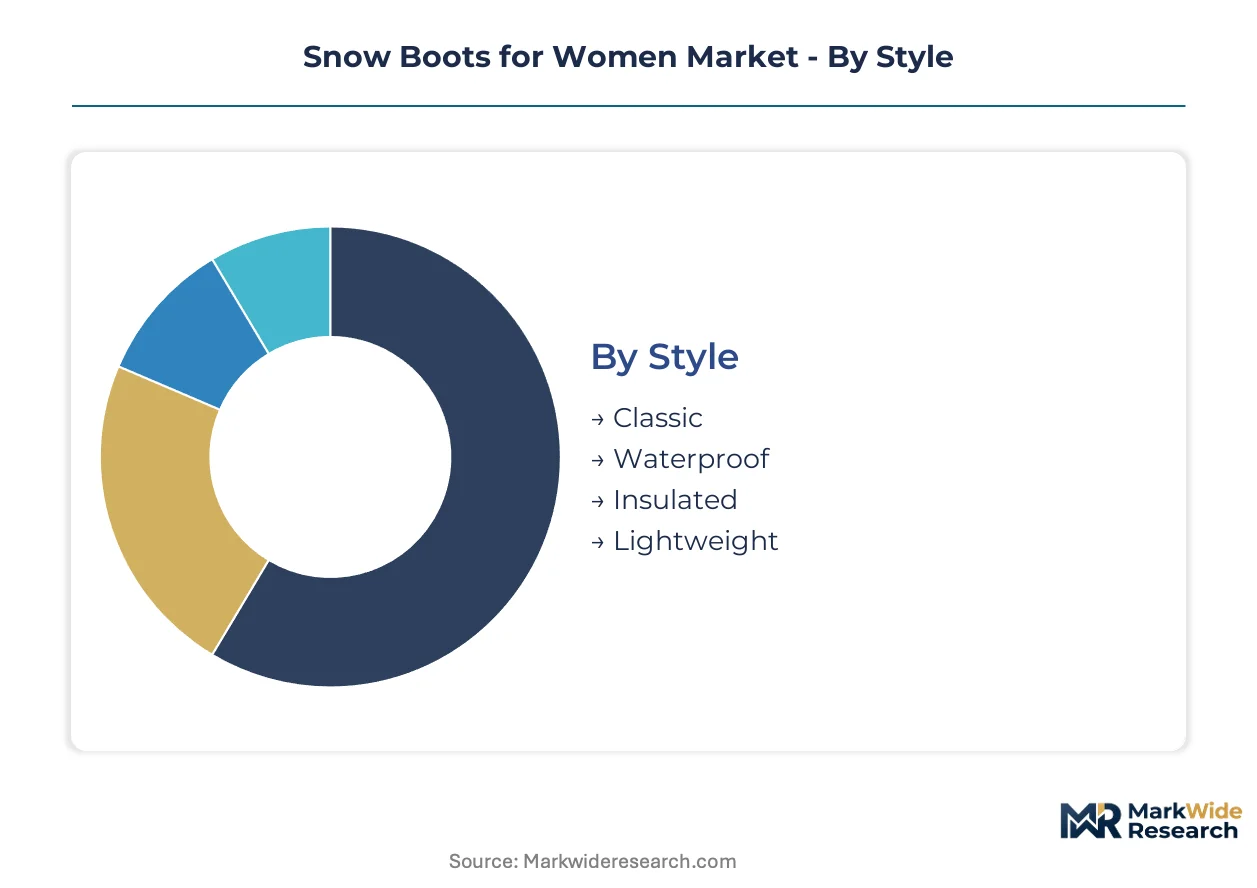
Segmentation in women's snow boots reveals how functional requirements diverge between urban commuters and outdoor recreationists. Each dimension—style, material, closure mechanism, and brand positioning—carries distinct substitution pressures from adjacent footwear categories.
Style:
Substitution pressure from fashion boots and athletic winter sneakers concentrates most intensely on aesthetic-driven segments rather than performance-oriented designs.
- Waterproof:Seam-sealed construction with membrane barriers blocks moisture infiltration while maintaining breathability. Demand concentrates in Chicago, Detroit, and Cleveland where polar vortex events have normalized technical footwear as daily infrastructure. FDA Title 21 phthalate oversight and EPA perfluorinated compound guidelines force reformulation of DWR coatings, extending product development timelines.
- Insulated:Thermal systems rated between minus-twenty and minus-forty degrees Celsius incorporate Thinsulate or PrimaLoft synthetic fill. Alpine tourism expansion across Colorado, Utah, and Vermont drives institutional procurement from resort operators seeking uniform-grade durability with multi-year replacement cycles.
- Classic:Heritage silhouettes prioritize aesthetic versatility over technical ratings, appealing to consumers seeking transitional office-to-casual wear.
- Lightweight:Streamlined constructions reduce material bulk for moderate-climate commuting where extreme cold protection is unnecessary.
Waterproof retains volume leadership; insulated holds the steepest expansion curve.
Material:
Cost tier stratification separates premium natural inputs from mass-market synthetics, with regulatory compliance adding friction to leather sourcing.
- Synthetic:Polyurethane and nylon constructions offer consistent thermal properties at lower unit costs. REACH chromium VI restrictions in leather tanning accelerate adoption across European production lines seeking tannery certification flexibility.
- Leather:Full-grain hides provide durability and breathability heritage, requiring sourcing from REACH-certified Italian and Portuguese tanneries. Chicago and Minneapolis urban commuters demonstrate willingness-to-pay premiums for vegetable-tanned options.
- Rubber:Vulcanized compounds dominate outsole and lower-shaft applications, with natural plantation supply concentration in Thailand and Indonesia creating input cost volatility during La Niña patterns.
- Textile:Woven uppers reduce weight for lightweight style variants, competing with sneaker-boot hybrids from athletic brands.
Synthetic leads volume; leather maintains premium positioning despite regulatory compression.
Closure Type:
Application context dictates preference—adjustability for backcountry versus speed for urban transitions.
- Lace-up:Multi-point adjustment systems secure fit across variable sock thicknesses and terrain angles. Backcountry skiers and ice-fishing enthusiasts in Vermont and Maine prioritize this configuration for precision fit.
- Zipper:Rapid on-off functionality addresses subway-to-office transitions in New York and Boston. Japanese and South Korean metropolitan buyers pay premiums for magnetic closure variants.
- Slip-on:Elasticized goring enables hands-free entry, appealing to drivers and casual users in moderate cold zones.
- Velcro:Strap systems accommodate swollen feet during extended cold exposure, penetrating senior and medical-use niches.
Lace-up dominates technical applications; zipper configurations are expanding most quickly in urban commuter channels.
Brand:
Customer type segmentation separates heritage loyalty from performance-seeking newcomers, with direct-to-consumer portals fragmenting traditional retail concentration.
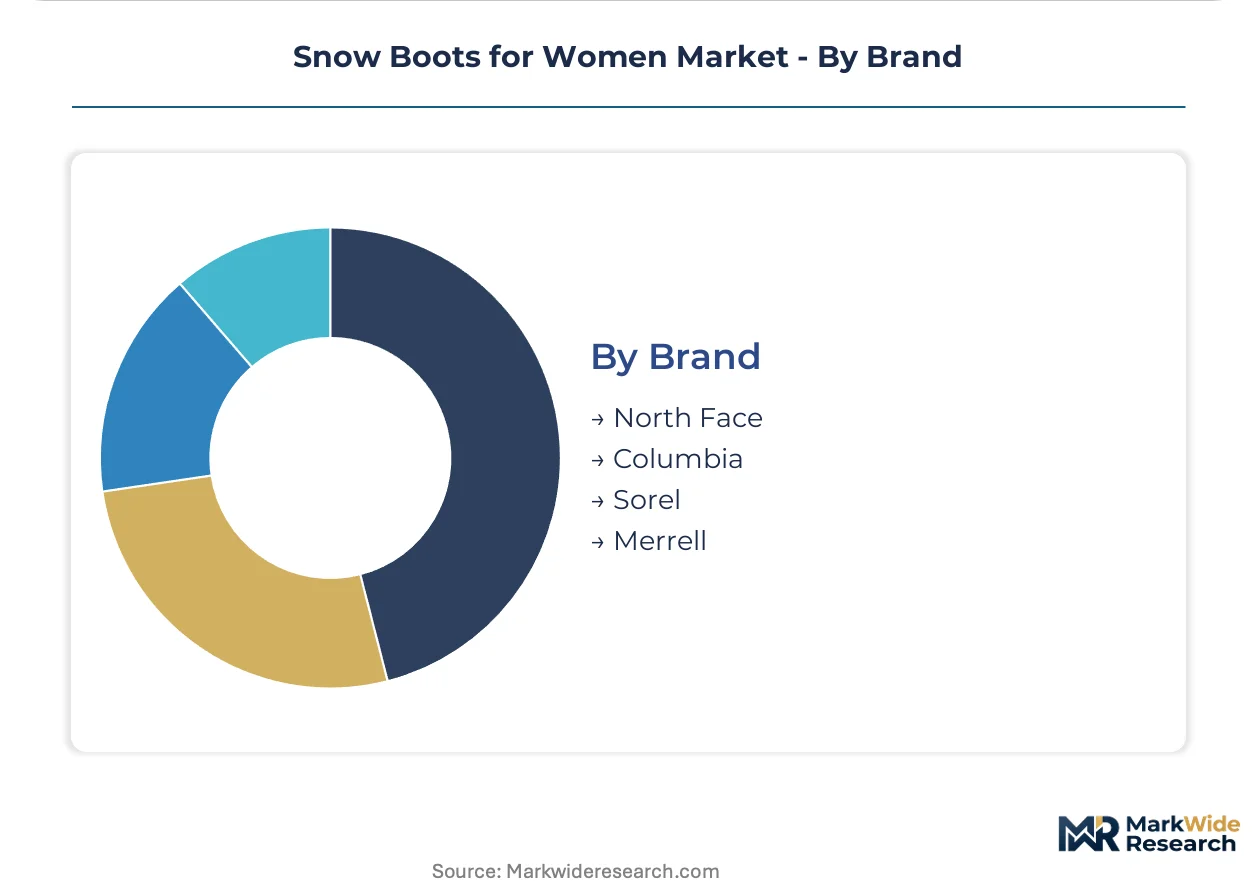
- North Face:Summit Series innovation lab sustains R&D intensity through aerogel insulation prototypes undergoing minus-forty-degree testing. Digital customization portals translate technical credibility into bespoke urban commuter offerings.
- Sorel:Vertically integrated rubber-compounding facility in Canada controls vulcanization quality for arctic-rated soles. Century-old heritage anchors direct-to-consumer loyalty through mail-order tradition now expressed via digital morphology matching.
- Columbia:Omni-Heat thermal-reflective technology penetrates mid-tier pricing bands, competing on value-engineered warmth.
- Merrell:Hiking-boot DNA transfers to winter variants, capturing outdoor recreationists seeking multi-season footwear versatility.
Sorel retains heritage volume leadership; North Face holds the steepest technical-innovation trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Title 21 regulations on footwear chemical safety establish the baseline for material compliance across the largest national market, while divergent state-level mandates in California and New York create layered obligations for manufacturers serving United States demand.
United States
Polar vortex frequency across the Great Lakes region extends functional selling seasons for arctic-rated insulation systems, with urban commuters in Chicago, Detroit, and Cleveland purchasing technical snow boots as essential cold-weather infrastructure. EPA guidelines on perfluorinated compound discharge from waterproofing treatments intersect with FDA phthalate oversight, compelling reformulation of DWR coatings. Alpine tourism infrastructure expansion in Colorado, Utah, and Vermont drives institutional procurement from resort operators seeking uniform-grade durability.
Germany
EU Green Deal chemical restrictions accelerate bio-based DWR certification adoption, with German retail channels prioritizing shelf space for compliant brands. ECHA REACH regulation restricts chromium VI in leather tanning, forcing production lines to source from certified Italian and Portuguese tanneries. Manufacturing clusters in Bavaria and North Rhine-Westphalia concentrate on precision vulcanization for cold-climate outsoles.
Canada
Vertically integrated rubber-compounding facilities in Ontario and Quebec control vulcanization quality for arctic-rated soles, leveraging captive supply chains against natural rubber price volatility. Health Canada oversees chemical safety standards for footwear materials entering domestic distribution. Toronto and Montreal urban centers sustain year-round purchasing patterns through cold-climate commuting demands.
Japan
METI standards for consumer product safety shape thermal-performance labeling requirements, with metropolitan buyers in Tokyo demonstrating willingness-to-pay premiums for magnetic closure systems. JIS certification marks differentiate technical footwear in specialty retail channels. Osaka-based distributors coordinate procurement for zipper-configuration variants optimized for subway-to-office transitions.
South Korea
Seoul Capital Area commuters drive rapid on-off functionality demand, with digital customization portals penetrating premium gift market segments. MFDS oversight of chemical content in consumer goods intersects with import regulations for waterproof membrane materials. Busan-Ulsan industrial zones supply synthetic insulation components to regional footwear assemblers.
Snow Boots for Women Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with heritage manufacturers possessing captive R&D capabilities commanding premium positioning while value-engineered competitors penetrate mass-market channels through thermal-reflective licensing. The market structure bifurcates between vertically integrated specialists controlling vulcanization quality and wholesale-dependent brands fragmenting across outdoor specialty retail. Three archetypes dominate: vertically integrated rubber compounders with in-house thermal testing, direct-to-consumer portals leveraging digital morphology matching, and licensed-technology assemblers competing on price-engineered warmth. Dominant competitive moves include backward integration into rubber-compounding facilities and establishment of circular logistics networks anticipating extended producer responsibility mandates.
Within the heritage-heritage tier, Sorel and L.L. Bean exemplify vertically integrated positioning through century-old mail-order traditions now expressed via digital channels, while The North Face occupies a position representing technical-innovation archetypes through captive R&D facilities. These three entities anchor distinct competitive vectors: Sorel exemplifies rubber-compounding control, L.L. Bean represents direct-to-consumer loyalty translation, and The North Face sits within the aerogel prototyping specialist category.
| Leading Market Players |
|---|
| Sorel |
| UGG |
| The North Face |
| Pajar |
| Hunter |
| L.L. Bean |
| Baffin |
| Keen |
| Timberland |
| Others |
Value Network & Pricing Analysis
Captive vulcanization capacity at Canadian and Bavarian facilities creates scale economies that compress unit costs for arctic-rated sole production while elevating price floors for smaller compounders lacking thermal-testing infrastructure. This concentration of technical capability simultaneously hardens margin structures for heritage bootmakers and fragments pricing power across synthetic-insulation assemblers competing on value-engineered warmth.
Pricing Analysis
Metropolitan price spreads between Tokyo-Seoul premium corridors and Midwest value channels exceed three-to-one for magnetic-closure configurations. Three-tier pricing structure across premium, standard, and economy levels separates aerogel-insulated backcountry systems from Thinsulate urban commuters and unbranded private-label imports. Price differentiation hinges on REACH certification tier and captive R&D depth. Cost compression in mid-tier synthetic insulation is intensifying because down-filled apparel alternatives capture cold-weather spending. Budget-conscious Great Lakes commuters exhibit highest price sensitivity; alpine resort procurement officers demonstrate lowest.
Supply Chain Analysis
Thailand and Indonesia anchor natural rubber plantation supply for vulcanized outsole production, while Italy and Portugal concentrate REACH-certified leather tanning for European-market lines. Synthetic insulation draws from South Korean petrochemical complexes and Chinese textile mills. Single-source vulnerability concentrates in Thai rubber supply during La Niña weather patterns. Distribution runs through outdoor specialty retail chains, direct-to-consumer digital portals, and resort operator institutional procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against down-filled winter apparel capturing footwear-adjacent cold-weather spending. Incumbents must harden technical differentiation as fashion-boot hybrids and athletic winter sneakers erode aesthetic-driven segments.
For Market Incumbents: Compound captive R&D advantages by deepening aerogel prototyping capabilities and securing exclusive thermal-testing partnerships with alpine resorts. Accelerate bio-based DWR certification ahead of EU Green Deal phase-outs to lock shelf space in German and French retail channels. Defensive positioning against synthetic-insulation price erosion requires emphasizing minus-forty-degree performance credentials that unbranded competitors cannot replicate.
For New Entrants and Emerging Players: Lead with magnetic closure systems targeting Tokyo and Seoul metropolitan commuters where willingness-to-pay premiums for rapid on-off functionality remains underexploited. White-space penetration is highest among urban zipper-configuration segments underserved by heritage lace-up specialists. Digital customization portals offering 3D foot-scanning morphology matching provide the most penetrable go-to-market angle for premium gift-market positioning without wholesale channel dependency.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer portals with biometric customization infrastructure and circular take-back program enrollment. Long-term viability across the projection horizon favors vertically integrated compounders with captive vulcanization and thermal-testing facilities over wholesale-dependent licensed-technology assemblers. Acquisition priority targets exhibit backward integration into rubber-compounding and established circular logistics networks anticipating California and New York extended producer responsibility mandates. The signal to monitor is institutional procurement volume contraction from alpine resort operators facing climate-driven season compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-based DWR Certification | EU Green Deal compliance secures German and French retail shelf access ahead of perfluorinated compound phase-outs. |
| 3D Foot-Scanning Customization | Digital morphology matching penetrates Tokyo-Seoul premium gift markets while compressing inventory risk. |
| Captive Vulcanization Expansion | In-house rubber compounding insulates margin structures from Thai plantation supply volatility during La Niña patterns. |
| Circular Logistics Network | Take-back infrastructure captures regulatory goodwill under California and New York extended producer responsibility mandates. |
| Aerogel Thermal IP Licensing | Summit Series-grade insulation prototypes differentiate premium tiers against synthetic-fill price erosion. |
Research Methodology
Desk research of customs trade records, alpine resort procurement databases, and EU ECHA regulatory filings preceded structured interviews with thermal-design engineers, footwear category buyers at outdoor specialty retailers, resort operations procurement directors, and vulcanization plant managers across Ontario and Bavaria. Primary fieldwork validated secondary data from FDA Title 21 guidance documents, EPA perfluorinated compound discharge guidelines, and state-level extended producer responsibility draft legislation. Bottom-up unit economics triangulated against top-down market sizing across style, material, closure type, and brand positioning dimensions.
Variance decomposition separates volume drivers from price-mix effects across the projection horizon. Segmentation modeling incorporated style tier, insulation technology, closure mechanism, distribution channel, and metropolitan climate severity. CAGRs were derived from replacement-cycle analysis, polar vortex frequency correlation, and alpine tourism infrastructure expansion trajectories. Forecast inputs included natural rubber futures volatility patterns, REACH recertification timeline assumptions, and digital customization adoption curves in East Asian metropolitan markets.
Forecasts assume regulatory continuity in FDA-EPA oversight regimes and EU REACH enforcement; material policy shifts would require re-modeling. Specific risks include accelerated perfluorinated compound bans, La Niña-driven rubber supply disruption, and down-filled apparel substitution acceleration. Recalibration cycles align with material shifts in thermal-engineering talent availability and state-level extended producer responsibility implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Footwear
Womens Footwear Market
Footwear
Ankle Boots Market
Footwear
E-Commerce Footwear Market
Footwear
Casual Shoes Market
Footwear
Europe Athletic Footwear Market
Footwear
Trail Running Shoes Market
Footwear
Driving Footwear Market
Footwear
Leather Sneakers Market
Footwear
Sports Shoes Market
Footwear
Second Hand Designer Shoes Market
Footwear
Athletic Footwear Market
Footwear
Wedge Boots Market
Footwear
Water Shoes Market
Footwear
Women's Luxury Footwear Market
Footwear
Shoe Insoles Market
Footwear
Slip on Shoes Market