
 US Thermal Underwear Market | 2026-2036
US Thermal Underwear Market Size, Share, and Industry Trends Forecast 2026-2036
US Thermal Underwear Market Outlook
Subscription-based replenishment programs for base layer replacements is consolidating consumer loyalty into recurring revenue streams rather than transactional purchases. Columbia Sportswear Company leverages its wholesale partnerships with specialty outdoor retailers to maintain shelf dominance across REI and Dick's Sporting Goods locations. Smartwool LLC anchors its position through vertical control over New Zealand merino sourcing and ZQ-certified wool traceability systems. Patagonia, Inc. differentiates via its Worn Wear repair and resale platform, extending product lifecycles while capturing secondary market value.
Thermal underwear comprises engineered base layer garments constructed from moisture-wicking, thermoregulating fabrics typically weighing 150-400 grams per square meter, designed to manage microclimate conditions adjacent to skin during cold exposure. Merino wool segments command premium positioning due to natural odor resistance and temperature modulation properties, while polyester blends compete on price-accessibility and synthetic durability for high-sweat activities. Women's thermal underwear represents the fastest-expanding end-user category as brands resize athletic fits beyond scaled-down men's patterns. Online distribution channels are displacing traditional retail footprints, with direct-to-consumer platforms capturing margin pools previously allocated to wholesale intermediaries.
The Federal Trade Commission enforces Green Guides standards that constrain how brands market recycled content and biodegradability claims, directly affecting product labeling and advertising compliance costs. Consumer Product Safety Commission flammability standards under 16 CFR Part 1610 govern polyester-dominant thermal garments sold to children, shaping material selection and testing protocols. California's Proposition 65 chemical disclosure requirements add state-level labeling obligations for formaldehyde and phthalate traces in textile treatments. Stakeholders must monitor evolving state-level extended producer responsibility legislation that could impose end-of-life collection mandates on apparel manufacturers.
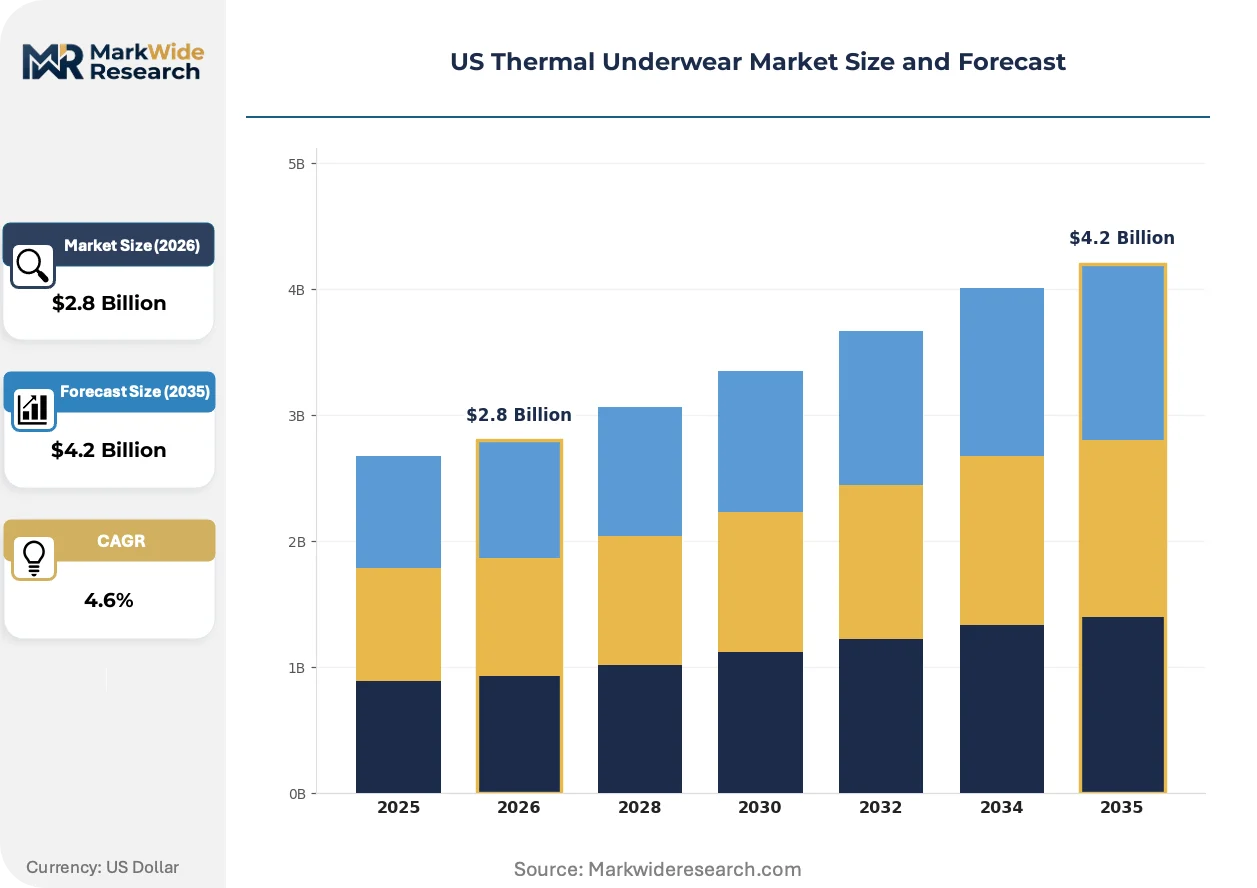
Market Dynamics
The Federal Trade Commission's Green Guides enforcement is compressing marketing claims for recycled and biodegradable thermal fabrics, forcing brands to restructure labeling investments and supply chain documentation protocols.
Growth Catalysts
- Mountain West Altitude Demand:Year-round cold exposure across Colorado, Utah, and Wyoming sustains consistent base layer consumption independent of seasonal retail cycles.
- 16 CFR Part 1610:CPSC flammability standards for children's polyester thermals create compliance barriers that favor established manufacturers with testing infrastructure.
- Moisture-Wicking Synthetics:Polyester-spandex blends with engineered capillary structures penetrate high-sweat outdoor recreation segments where merino wool faces durability constraints.
Market Restraints
- Merino Wool Supply Concentration:ZQ-certified New Zealand wool sourcing limits volume scalability for premium thermal lines during supply disruptions.
- California Proposition 65:Chemical disclosure mandates for formaldehyde traces in textile treatments add per-unit compliance costs disproportionately burdening smaller domestic manufacturers.
- Synthetic Microfiber Pollution:Polyester thermal shedding during laundering faces mounting state-level scrutiny, threatening synthetic segment positioning.
Strategic Opportunities
- Subscription Replenishment Models:Direct-to-consumer base layer replacement programs capture recurring revenue streams and disintermediate wholesale margin capture.
- Extended Producer Responsibility:Emerging state legislation on apparel end-of-life collection creates first-mover advantage for brands with circular infrastructure.
- Women's Athletic Fit Expansion:Sizing beyond scaled-down men's patterns unlocks underpenetrated female outdoor recreation participation growth.
Industry Challenges
- Traceability System Integration:ZQ wool certification and recycled content verification require ERP upgrades that strain mid-tier manufacturer IT budgets.
- Flammability Testing Bottlenecks:CPSC-accredited laboratory capacity constraints delay children's thermal product launches during peak preseason windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Thermal Underwear Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottoms, Tops, Sets, Accessories Material: Merino Wool, Fleece, Polyester, Cotton End User: Men, Women, Children, Seniors Distribution Channel: Online, Retail Stores, Distributors, Wholesalers |
| Companies Covered | Columbia Sportswear Company, Smartwool LLC, Under Armour, Inc., Fruit of the Loom, Inc., Patagonia, Inc., PVH Corp., L.L.Bean, Inc., Jockey International, Inc., Hanesbrands Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Thermal Underwear Market Strategic Shifts
Material science advances and regulatory enforcement are converging to redefine how thermal underwear is engineered, marketed, and distributed across domestic channels.
Phase-change materials embedded in polyester base layers is rewriting thermal regulation performance standards. Mountaineering and backcountry skiing adopters are migrating toward these smart fabrics at accelerating rates. The technology is compressing traditional insulation layering systems into single-garment solutions.
FTC Green Guides substantiation requirements are tightening enforcement against vague biodegradability claims. Thermal brands must now maintain third-party documentation for recycled content percentages or face advertising compliance actions. Children's and premium merino segments bear the heaviest documentation burdens.
Outdoor recreation buyers are consolidating purchases through direct-to-consumer platforms that displace specialty retail intermediaries. REI and Dick's Sporting Goods wholesale relationships face margin compression as brands capture full-stack customer data. This channel rotation is most pronounced in Colorado, Utah, and Pacific Northwest metropolitan clusters.
US Thermal Underwear Market Segmentation
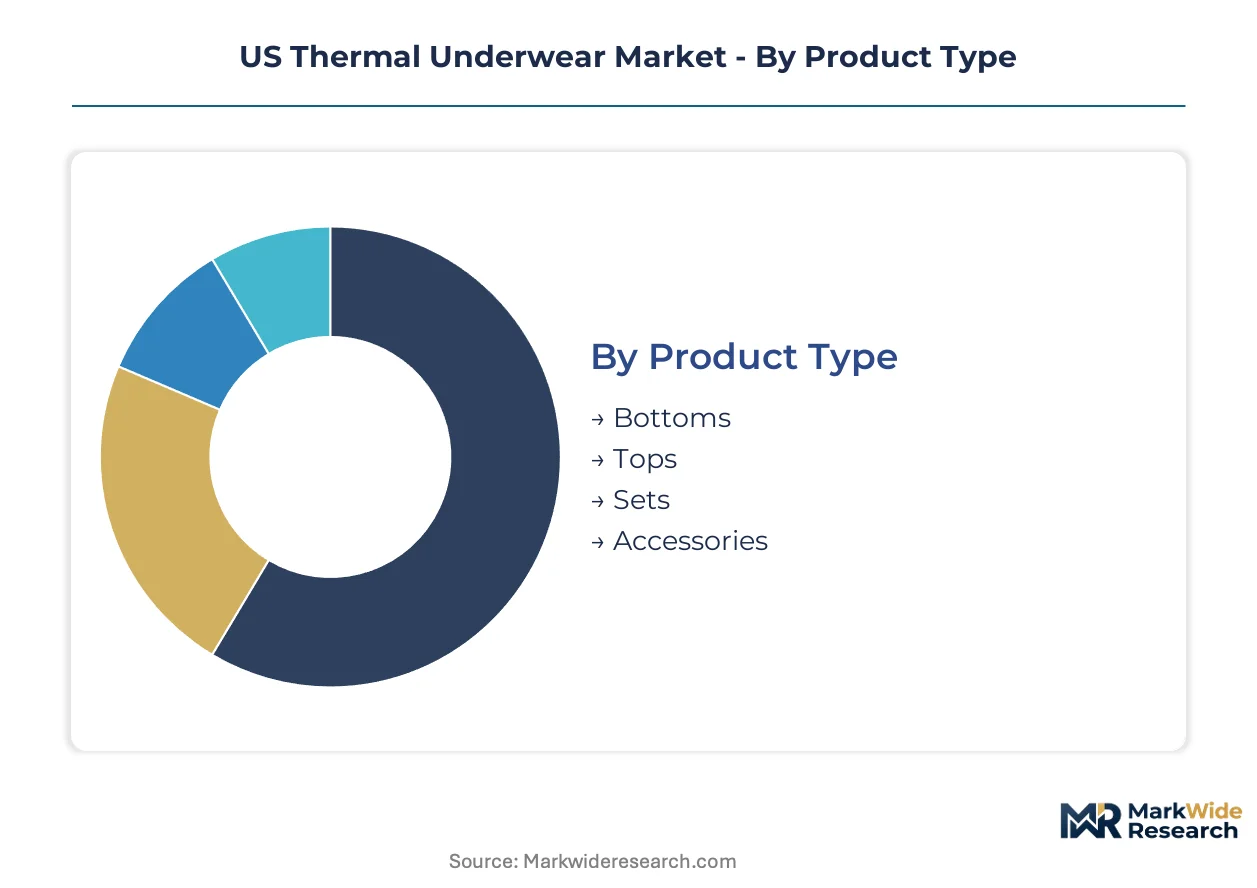
Thermal underwear segmentation reveals how capital deployment, material sourcing, and channel infrastructure shape competitive returns. Manufacturers allocate resources across product architectures, fiber technologies, demographic targets, and fulfillment systems with markedly different margin profiles.
Product Type:
Capital intensity concentrates in manufacturing infrastructure for integrated sets versus single-piece production lines.
- Bottoms:Leggings and long johns engineered with gusseted construction and articulated knees dominate outdoor labor and recreation applications. Demand clusters in Mountain West states where altitude-driven cold exposure sustains year-round consumption independent of seasonal retail cycles.
- Tops:Crew necks, quarter-zips, and mock necks incorporate flatlock seams to minimize chafing under mid-layers. Women's athletic fit expansion is reshaping pattern grading beyond scaled-down men's specifications, unlocking underpenetrated female participation in cold-weather activities.
- Sets:Coordinated top-bottom combinations reduce consumer decision friction and elevate average transaction values. Coordinated production requires matched dye lots and synchronized inventory management.
- Accessories:Balaclavas, neck gaiters, and thermal socks extend base layer systems into extremity protection. Lightweight accessories command lower absolute margins but higher inventory velocity.
Most installed capacity flows through Bottoms. Expansion is steepest in Tops.
Material:
Raw material procurement costs and vertical integration requirements vary dramatically across fiber categories.
- Merino Wool:ZQ-certified New Zealand sourcing with 18.5-19.5 micron fiber diameter delivers natural odor resistance and thermoregulation. Supply concentration limits volume scalability during disruptions, constraining premium line expansion.
- Polyester:Engineered capillary structures with 150-400 gsm weight ranges penetrate high-sweat segments where durability outweighs natural fiber benefits. FTC Green Guides enforcement is compressing recycled content marketing claims and forcing documentation protocol investments.
- Fleece:Brushed polyester or synthetic wool blends trap air in lofted pile structures for static cold exposure. Fleece manufacturing requires specialized shearing and anti-pilling treatment equipment.
- Cotton:Basic thermal knits serve price-sensitive segments despite moisture retention limitations. Cotton procurement leverages domestic textile infrastructure with minimal specialty equipment requirements.
Merino Wool captures the highest margin per unit. Polyester is gaining share fastest through moisture-wicking performance positioning.
End User:
Customer acquisition costs and lifetime value calculations diverge sharply across demographic segments with distinct fit requirements.
- Women:Athletic-specific patterning with contoured waistbands and bust darts addresses underpenetrated female outdoor recreation growth. Subscription-based replenishment programs are consolidating loyalty into recurring revenue streams for this segment.
- Men:Traditional workwear and outdoor recreation applications dominate volume. Men's thermal lines leverage established size scaling with minimal pattern development overhead.
- Children:CPSC 16 CFR Part 1610 flammability compliance creates testing infrastructure barriers favoring established manufacturers. Rapid growth phases necessitate frequent replacement cycles.
- Seniors:Circulation-focused warmth solutions with easy-don closures address aging demographic needs. Senior-targeted distribution runs through medical supply and adaptive apparel channels.
Women's segment exhibits the steepest expansion trajectory. Men's segment retains the largest installed base.
Distribution Channel:
Fulfillment infrastructure investments and margin capture economics structure competitive positioning across channel architectures.
- Online:Direct-to-consumer platforms disintermediate wholesale margin pools and capture full-stack customer data. Channel rotation is most pronounced in Colorado, Utah, and Pacific Northwest metropolitan clusters.
- Retail Stores:REI and Dick's Sporting Goods locations provide tactile evaluation and immediate fulfillment. Wholesale partnerships require slotting fee investments and seasonal inventory commitments.
- Distributors:Specialty outdoor and workwear intermediaries aggregate fragmented retail accounts. Distributor relationships reduce brand-level customer acquisition costs.
- Wholesalers:Volume-oriented procurement for institutional buyers including military and municipal contracts. Wholesaler channels prioritize price competitiveness over brand premium.
Retail Stores maintain the deepest installed infrastructure. Online is climbing the fastest through margin capture advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's thermal underwear consumption runs at roughly one-third of United States volume, though both markets share similar altitude-driven demand clusters in mountain regions. France and Italy concentrate luxury thermal apparel production while importing performance base layers from specialized manufacturers. The United Kingdom channels thermal demand through outdoor recreation retail networks that differ structurally from American direct-to-consumer platforms.
United States
Mountain West states sustain year-round thermal consumption independent of seasonal retail cycles, with Colorado, Utah, and Wyoming registering per-capita base layer purchases exceeding national averages by significant margins. The Federal Trade Commission enforces Green Guides standards that constrain recycled content marketing claims and elevate supply chain documentation costs. Denver and Salt Lake City anchor regional distribution infrastructure serving high-altitude recreation corridors.
Canada
Arctic and subarctic climates generate institutional procurement demand from municipal workforces, military units, and First Nations communities operating in extreme cold exposure conditions. Health Canada maintains textile flammability standards under the Canada Consumer Product Safety Act that align closely with CPSC 16 CFR Part 1610 protocols. Toronto and Vancouver concentrate specialty outdoor retail networks that source premium merino thermal lines from certified New Zealand suppliers.
Germany
Alpine tourism in Bavaria and Baden-Württemberg sustains consistent thermal apparel demand through skiing and mountaineering participation rates among Europe's highest. The ECHA REACH regulation governs chemical substance restrictions in textile treatments, including formaldehyde limits that exceed California Proposition 65 stringency in certain applications. Munich anchors both manufacturing R&D clusters and specialty retail distribution serving Austrian and Swiss cross-border demand.
France
Pyrenees and Alps tourism circuits generate concentrated seasonal demand peaks that differ from American altitude-driven year-round consumption patterns. The EU Green Deal's textile sustainability requirements are tightening recycled content verification standards that affect import compliance for non-EU thermal manufacturers. Lyon maintains historical textile engineering expertise that supports technical base layer development for European outdoor brands.
Italy
Dolomite mountain tourism and northern industrial workwear applications split thermal demand between recreation and occupational segments with distinct distribution channels. CE marking requirements under the EU's Personal Protective Equipment Regulation govern thermal garments marketed for professional cold-weather work applications. Biella's wool processing heritage supports premium merino thermal manufacturing for luxury and performance positioning tiers.
US Thermal Underwear Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium merino lines concentrating around vertically integrated wool processors while mass-market synthetics fragment across diversified apparel conglomerates. The vendor base organizes into three strategic archetypes: outdoor heritage brands with wholesale retail partnerships, direct-to-consumer specialists controlling fiber sourcing, and private-label manufacturers serving institutional buyers. Competitive moves center on subscription-based replenishment program launches and circular economy infrastructure investments for end-of-life garment collection.
Within the outdoor heritage tier, Columbia Sportswear Company and Patagonia, Inc. exemplify divergent strategic positioning around wholesale channel depth versus resale platform development. Smartwool LLC anchors the premium merino segment through ZQ-certified sourcing control. These three companies collectively represent how fiber specialization, channel architecture, and circular service offerings differentiate competitive positioning across price-performance segments.
| Leading Market Players |
|---|
| Columbia Sportswear Company |
| Smartwool LLC |
| Under Armour, Inc. |
| Fruit of the Loom, Inc. |
| Patagonia, Inc. |
| PVH Corp. |
| L.L.Bean, Inc. |
| Jockey International, Inc. |
| Hanesbrands Inc. |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up apparel specialists have consolidated domestic thermal manufacturing capacity, creating disciplined pricing power through volume leverage while simultaneously constraining supply flexibility through centralized production footprints.
Pricing Analysis
Capacity additions in Southeast Asian synthetic fiber production are reshaping price floors for polyester-dominant base layers. Three-tier pricing structure across premium merino, performance synthetic, and basic cotton levels stratifies around ZQ certification status and moisture-wicking engineering. Cost compression in entry-level cotton thermals is intensifying because of Bangladeshi manufacturing scale. Institutional buyers in municipal workwear segments exhibit highest price sensitivity, while backcountry recreation enthusiasts in Colorado and Utah show lowest elasticity.
Supply Chain Analysis
Merino wool supply rests on New Zealand ZQ-certified stations and Australian superfine clip auctions for 18.5-19.5 micron fiber. Synthetic yarn production draws from China, Vietnam, and domestic Carolina-based spinning operations. Brushed fleece manufacturing hinges on specialized shearing equipment concentrated in Mexico and Central America. Single-source vulnerability runs through New Zealand wool auctions during drought-disrupted shearing seasons. Distribution runs through Denver and Salt Lake City hubs serving Mountain West altitude corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Thermal Underwear Market functions as a stable compounder where altitude-driven Mountain West consumption sustains baseline demand independent of seasonal retail volatility.
For Market Incumbents: Anchor wholesale shelf dominance at REI and Dick's Sporting Goods through exclusive colorway partnerships and preseason inventory commitments. Defend against direct-to-consumer disintermediation by deploying subscription replenishment programs that capture recurring revenue streams. Certification investment in ZQ wool traceability systems creates switching costs for premium segment competitors.
For New Entrants and Emerging Players: Enter via women's athletic fit specialization where pattern development beyond scaled-down men's specifications remains underdeveloped. Target Colorado and Utah metropolitan clusters where online channel rotation has weakened traditional retail intermediaries. Deploy direct-to-consumer launches with New Zealand merino sourcing transparency as the core go-to-market angle.
For Investors and Strategic Acquirers: Outdoor conglomerates with wholesale infrastructure are the most active acquirer in this space, seeking direct-to-consumer capabilities and circular economy platforms. Long-term viability frames around extended producer responsibility legislation creating asset value in end-of-life collection infrastructure. Acquisition target archetype: vertically integrated merino specialists with ZQ certification and captive New Zealand sourcing relationships. The signal to watch is California extended producer responsibility bill progression as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Replenishment Launch | Columbia's wholesale partnerships convert transactional buyers into recurring revenue streams through automated base layer replacement. |
| ZQ Certification Investment | Smartwool's traceability systems create supply chain documentation barriers that FTC Green Guides enforcement now mandates. |
| Direct-to-Consumer Platform Buildout | Patagonia's Worn Wear resale platform captures secondary market value while extending product lifecycles against synthetic competitors. |
| Women's Athletic Fit Expansion | Resized pattern grading unlocks underpenetrated female participation in Colorado and Utah cold-weather recreation corridors. |
| Circular Infrastructure Development | End-of-life garment collection systems position first-movers for emerging state extended producer responsibility mandates. |
Study Parameters
Direct dialogue with brand managers at outdoor heritage companies, category buyers at REI and Dick's Sporting Goods, New Zealand wool procurement directors, and CPSC compliance officers grounded qualitative findings. Secondary validation drew from FTC Green Guides enforcement actions, CPSC 16 CFR Part 1610 testing protocols, ZQ Merino certification databases, and customs import records for synthetic fiber shipments. Bottom-up channel volume estimates triangulated against top-down apparel spending allocation models.
Segment-level outputs across material type, end-user demographic, product architecture, and distribution channel informed the analytical framework over the projection horizon. CAGRs were derived from historical consumption elasticities against outdoor recreation participation indices and altitude-driven climate exposure patterns. Modeled inputs included Mountain West population migration trends, subscription service adoption curves, and state-level extended producer responsibility legislative probability.
The model holds under steady FTC enforcement intensity and stable New Zealand wool auction liquidity; deviation in trade policy shifts or drought-driven fiber supply disruption would shift volume trajectories. A small set of triggers—California EPR passage, CPSC accredited laboratory capacity constraints, and synthetic microfiber state-level bans—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel & Footwear
Luxury Vegan Men's Fashion Market
Apparel & Footwear
Children's Suits and Ensembles Market
Apparel & Footwear
Global Silk Pajamas Market
Apparel & Footwear
Sports Apparel Embellishment Market
Apparel & Footwear
Australia Denim Jeans Market
Apparel & Footwear
Europe Denim Jeans Market
Apparel & Footwear
Adaptive Shapewear Market
Apparel & Footwear
Custom Cycling Clothing Market
Apparel & Footwear
Ice Hockey Apparel Market
Apparel & Footwear
Surfing Apparel and Accessory Market
Apparel & Footwear
School Shoes Market
Apparel & Footwear
Mexico Denim Jeans Market
Apparel & Footwear
Official Football Kits Market
Apparel & Footwear
Platform Shoes Market
Apparel & Footwear
Women's T-Shirts Market
Apparel & Footwear
Jeans Market